
 Europe Walk-In Refrigerators and Freezers Market | 2026-2036
Europe Walk-In Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Walk-In Refrigerators and Freezers Market Foresight
The capability gap between full-system manufacturers and component suppliers is collapsing as integrated cold-chain providers absorb more value in-house. Carrier Corporation leverages its compressor technology leadership to control distribution across Nordic markets. Foster Refrigerator anchors its position through specialized modular units for independent food retailers. Danfoss A/S competes on refrigerant control systems that extend into aftermarket service contracts.
Walk-in refrigerators and freezers are engineered insulated enclosures with polyurethane foam panels, maintaining temperatures from minus twenty degrees Celsius to ten degrees Celsius for bulk food preservation and commercial storage. These systems employ hermetic or semi-hermetic compressors with direct expansion or secondary coolant circulation to protect perishable inventory across extended supply chains. The walk-in product category dominates installed value across European food retail, while eco-friendly refrigeration technology captures expanding margin pools as fluorinated gas restrictions tighten. Modular installation types sustain growth in urban renovation projects where existing buildings constrain standard configurations.
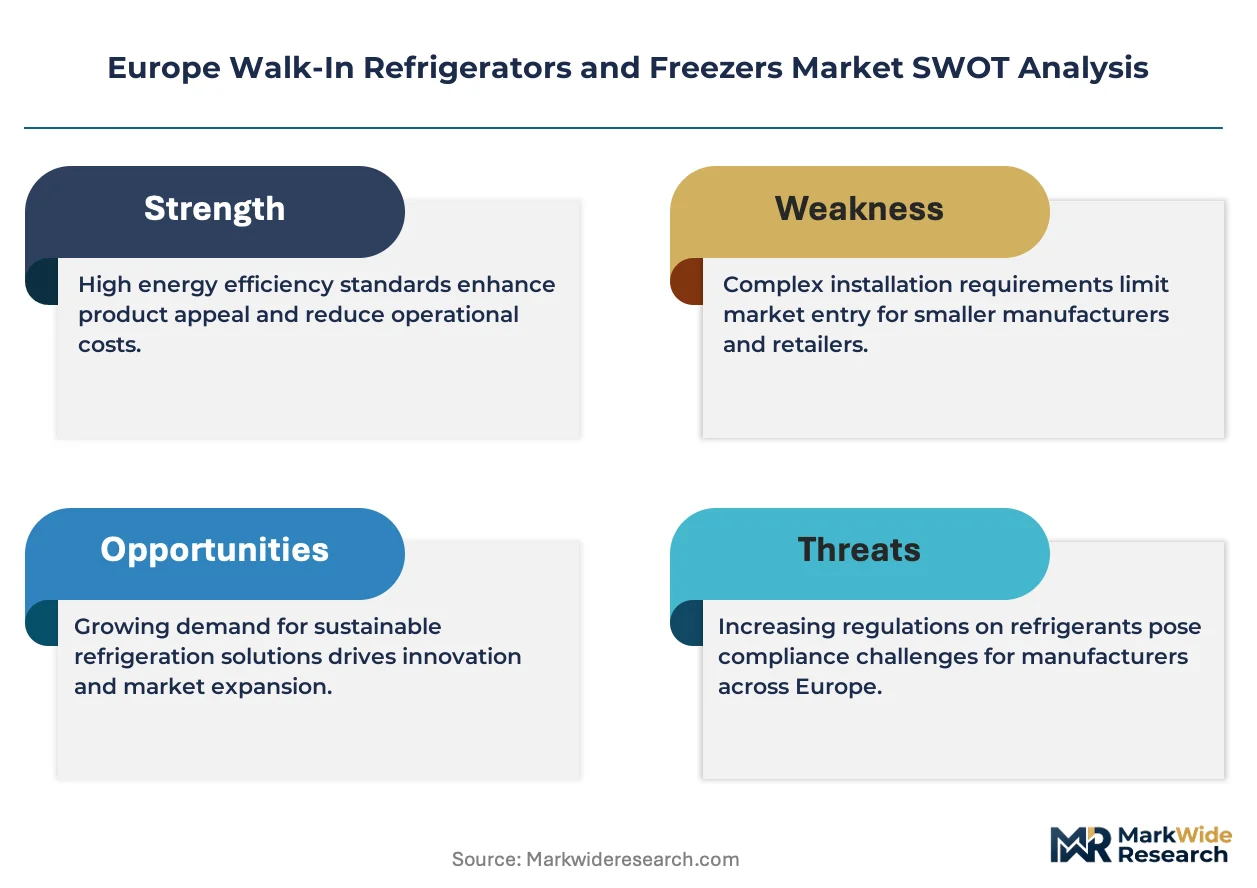
The EU F-Gas Regulation and Ecodesign Directive shape product development by mandating lower global warming potential refrigerants and minimum energy performance thresholds for commercial cold storage. CE marking requirements under the Machinery Directive govern panel assembly safety and electrical compliance for cross-border market access. Stakeholders must monitor refrigerant phase-down schedules and building energy codes to align capital deployment with compliance timelines.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale refrigerant transition across European cold storage infrastructure, collapsing the installed base of hydrofluorocarbon systems and redistributing competitive advantage toward natural refrigerant specialists.
Growth Catalysts
- Fresh food retail expansion:Supermarket chains in Germany and France are enlarging cold storage footprints to comply with stricter food safety protocols and extended supply chain requirements.
- EU F-Gas Regulation:The phasedown schedule for fluorinated gases is accelerating capital replacement cycles and opening procurement windows for compliant equipment.
- Polyurethane panel innovation:Improved insulation cores with lower thermal conductivity are reducing energy consumption thresholds for retrofit installations in urban centers.
Market Restraints
- Copper and steel input volatility:Compressor housings and panel framing depend on commodity metals whose price swings compress equipment margins.
- Certified installer scarcity:Natural refrigerant systems require specialized handling credentials that remain concentrated in Northern European labor pools.
- Legacy asset stranding:Existing HFC-based installations face accelerated obsolescence before full depreciation, freezing capital recovery for foodservice operators.
Strategic Opportunities
- Modular retrofit penetration:Eastern European food processors present untapped demand for panelized cold rooms that bypass full reconstruction permits.
- Aftermarket service bundling:Refrigerant monitoring and predictive maintenance contracts offer recurring revenue streams beyond initial equipment sales.
- CO2 transcritical adoption:The technology convergence of booster systems with heat recovery is opening commercial kitchens and bakeries previously locked out of natural refrigerant options.
Industry Challenges
- Technician certification bottlenecks:The pipeline of F-Gas-certified engineers cannot match installation demand spikes during regulatory deadline years.
- Interoperability friction:Building management system integration with legacy BACnet protocols requires custom middleware that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Walk-In Refrigerators and Freezers Market |
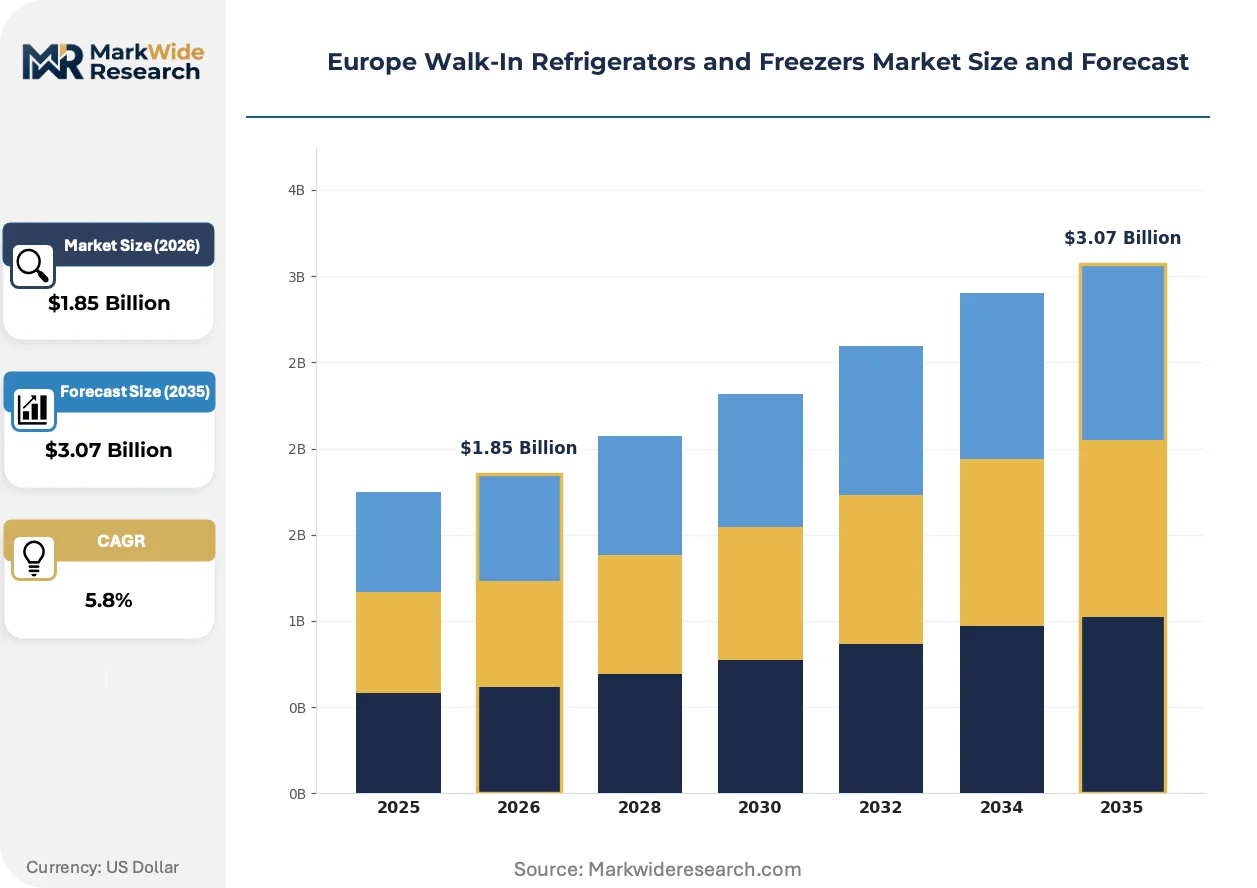
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reach-In, Walk-In, Under-Counter, Freezer Room End User: Supermarkets, Restaurants, Warehouses, Catering Services Technology: Refrigerant-Based, Thermoelectric, Mixed Refrigeration, Eco-Friendly Installation Type: Built-In, Modular, Portable, Customizable |
| Companies Covered | Danfoss A/S, Hussmann Corporation, Carrier Corporation, Emerson Electric Co., Foster Refrigerator, BSH Hausgeräte GmbH, AB Electrolux, GEA Group AG, AHT Cooling Systems GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Walk-In Refrigerators and Freezers Market Shifts & Advancements
Cold storage engineering is pivoting from standalone equipment sales toward integrated energy systems, with refrigerant choice, panel chemistry, and control architecture converging into unified procurement decisions.
CO2 transcritical refrigeration is supplanting R404A and R448A systems in supermarket applications across Scandinavia and the Netherlands. German and Danish retail chains are specifying booster architectures for new builds and comprehensive retrofits alike. This transition is compressing the addressable market for synthetic refrigerant compressors while expanding demand for high-pressure-rated heat exchangers and electronic expansion valves.
The EU F-Gas Regulation mandates an 80% reduction in hydrofluorocarbon consumption by 2030 against baseline levels. Equipment manufacturers must redesign compressor lines and recalibrate performance curves for propane, ammonia, and CO2 working fluids. Southern European markets with warmer ambient conditions face steeper engineering hurdles for CO2 gas cooler optimization.
Food retailers are consolidating vendor relationships and demanding performance guarantees spanning energy consumption, refrigerant leakage rates, and temperature stability. Full-service contracts with penalty clauses are displacing traditional equipment purchase plus separate maintenance arrangements. This concentration is most pronounced in the Benelux region where buying cooperatives negotiate pan-European framework agreements.
Europe Walk-In Refrigerators and Freezers Market Segmentation
Segmentation in the European walk-in cold storage market reveals how regulatory pressure and installation constraints reshape procurement patterns. Buyers now select equipment based on refrigerant compliance timelines and building retrofit feasibility rather than capacity alone.
Product Type:
Substitution pressure from integrated cold-chain systems threatens standalone equipment categories most acutely in mature Western European markets.
- Walk-In:Engineered insulated enclosures with polyurethane foam panels maintain temperatures from minus twenty to ten degrees Celsius for bulk commercial storage. German and French supermarket chains specify these for expanded fresh food retail footprints under stricter EU food safety protocols.
- Reach-In:Self-contained units with hermetic compressors serve smaller foodservice operations where space constraints block panelized construction. Demand concentrates in independent restaurants across Italy and Spain seeking F-Gas-compliant replacements without structural modification.
- Under-Counter:Compact refrigeration for front-of-house beverage and ingredient storage in urban food retail.
- Freezer Room:Ultra-low temperature enclosures for frozen goods distribution centers and industrial food processing.
Walk-In retains volume leadership; Reach-In holds the steepest expansion curve as retrofit demand accelerates.
End User:
Cost tier stratification separates capital-intensive new construction from maintenance-budget replacement cycles across customer types.
- Supermarkets:Large-format retail chains deploy centralized cold storage networks with CO2 transcritical booster architectures. Scandinavian and Dutch buying cooperatives negotiate pan-European framework agreements bundling equipment, installation, and predictive maintenance under performance guarantees.
- Restaurants:Independent and chain foodservice operators prioritize modular panel systems that bypass full reconstruction permits in dense urban centers. Eastern European markets present untapped penetration opportunities for standardized cold room configurations.
- Warehouses:Third-party logistics providers serving temperature-controlled supply chains.
- Catering Services:Event and institutional food preparation requiring portable or temporary cold storage solutions.
Supermarkets command the premium tier; Restaurants are gaining share fastest as regulatory deadlines force equipment turnover.
Technology:
Application requirements dictate refrigerant selection, with ambient climate conditions and heat recovery needs determining viable technology pathways.
- Eco-Friendly:Natural refrigerant systems using CO2, propane, or ammonia working fluids comply with EU F-Gas Regulation phase-down mandates. German and Danish retail chains specify these for new builds and comprehensive retrofits, though Southern European markets face steeper engineering hurdles for gas cooler optimization in warmer conditions.
- Refrigerant-Based:Synthetic hydrofluorocarbon systems face accelerated obsolescence as the EU mandates an eighty percent consumption reduction. Existing installed base stranding risks freeze capital recovery for foodservice operators delaying replacement decisions.
- Thermoelectric:Solid-state cooling for small-scale or precision temperature applications.
- Mixed Refrigeration:Hybrid architectures combining multiple cooling technologies for load flexibility.
Refrigerant-Based retains installed base dominance; Eco-Friendly climbs the fastest as procurement windows align with compliance timelines.
Installation Type:
Customer type and building vintage determine installation feasibility, with urban renovation projects driving divergence from standard configurations.
- Modular:Panelized cold rooms assemble from prefabricated polyurethane core sections enabling rapid deployment without structural permits. Eastern European food processors adopt these for facility expansions where regulatory approval timelines constrain conventional construction.
- Built-In:Custom-engineered enclosures integrate with permanent building infrastructure for large-scale distribution centers.
- Portable:Mobile units for temporary capacity needs in catering and event logistics.
- Customizable:Bespoke dimensions and specifications for non-standard facility constraints.
Built-In captures the project-scale premium; Modular expands most quickly as urban retrofit demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Walk-in cold storage deployment patterns diverge sharply across Europe, with Northern markets prioritizing CO2 transcritical retrofits while Southern operators balance compliance costs against warmer ambient engineering challenges.
Germany
Discounter chains Aldi and Lidl drive centralized cold room expansion for fresh produce distribution. The Federal Environment Agency enforces strict F-Gas phase-down timelines that compress replacement cycles. Industrial clusters around Cologne and Hamburg concentrate compressor manufacturing and panel fabrication capacity serving pan-European supply chains.
France
Hypermarket operators Carrefour and Auchan enlarge back-of-house cold storage footprints to meet extended supply chain requirements. ANSM and environmental regulators coordinate refrigerant handling certification standards. The Île-de-France corridor anchors specification engineering for modular panel systems deployed across francophone African export markets.
Netherlands
Buying cooperatives representing Albert Heijn and Jumbo negotiate framework agreements bundling equipment, installation, and predictive maintenance. The Dutch Emissions Authority monitors F-Gas compliance through mandatory leakage reporting. Rotterdam's port logistics zone concentrates third-party cold storage providers serving re-export trade flows.
Italy
Independent restaurant operators and small-format food retailers generate retrofit demand for reach-in replacements without structural modification. Local environmental agencies implement EU F-Gas Regulation with regionally varying enforcement intensity. Milan's commercial kitchen equipment district channels distribution southward into underpenetrated Mediterranean markets.
Poland
Food processors and emerging retail chains adopt modular panelized cold rooms to bypass lengthy construction permits. The Chief Inspectorate of Environmental Protection aligns national refrigerant phase-down schedules with EU mandates. Warsaw and Łódź industrial zones attract manufacturing investment serving Eastern European expansion markets.
Europe Walk-In Refrigerators and Freezers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-system manufacturers absorbing value previously captured by component suppliers. The market structure concentrates procurement power among Scandinavian and Benelux buying cooperatives while fragmenting across Southern European independent operators. Three archetypes dominate: compressor technology leaders controlling distribution networks, modular panel specialists serving urban retrofit demand, and refrigerant control system providers extending into aftermarket service. Competitive moves center on pan-European framework agreement capture and natural refrigerant certification pipeline development.
Within the integrated systems tier, Carrier Corporation and Danfoss A/S exemplify divergent strategic positioning—Carrier leveraging compressor technology leadership across Nordic markets, Danfoss competing on refrigerant control systems that extend into predictive maintenance contracts. Foster Refrigerator occupies a specialist position through modular unit configurations tailored to independent food retailers. These three anchors demonstrate how geographic focus and technical specialization partition competitive advantage under tightening EU F-Gas Regulation compliance requirements.
| Leading Market Players |
|---|
| Danfoss A/S |
| Hussmann Corporation |
| Carrier Corporation |
| Emerson Electric Co. |
| Foster Refrigerator |
| BSH Hausgeräte GmbH |
| AB Electrolux |
| GEA Group AG |
| AHT Cooling Systems GmbH |
| Others |
Supply & Pricing Matrix
Ninety-day compressor lead times for CO2 transcritical systems concentrate pricing power among German and Danish panel fabricators serving pan-European supermarket cooperatives. This inventory compression amplifies margin capture for vertically integrated manufacturers while squeezing independent installers competing on equipment-only tenders.
Pricing Analysis
Long-term framework agreements dominate procurement for Scandinavian and Benelux buying cooperatives bundling equipment, installation, and predictive maintenance under multi-year performance guarantees. Price differentiation rests on F-Gas certification tier and after-sales service bundling depth, with premium tiers commanding extended warranty and refrigerant monitoring clauses. Cost compression in standard equipment tiers intensifies as Chinese compressor imports penetrate Southern European spot markets. Independent restaurant operators across Italy and Spain exhibit highest price sensitivity, prioritizing reach-in replacements without structural modification over full cold room retrofits.
Supply Chain Analysis
Inventory buffers for polyurethane foam panels and hermetic compressors cluster in industrial zones around Cologne, Hamburg, and Warsaw, feeding just-in-time assembly for modular cold room deployments. European walk-in refrigeration draws from copper and steel feedstock anchored in German and Polish metalworking corridors, with electronic expansion valves and high-pressure heat exchangers sourced from Danish and Swedish component specialists. Single-source vulnerability concentrates in CO2 transcritical compressor lines where two manufacturers control Nordic distribution. Distribution runs through buying cooperatives in Northern Europe and fragmented dealer networks across Mediterranean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe walk-in refrigeration market functions as a defensive moat sustained by regulatory entrenchment: the EU F-Gas Regulation's certification requirements create switching costs that lock in incumbent relationships through compliance deadline cycles.
For Market Incumbents: Compound certification pipeline advantages by acquiring F-Gas-certified installation networks in Poland and Italy where technician scarcity constrains competitor expansion. Deepen backward integration into polyurethane panel fabrication to capture margin pools from commodity metal volatility threatening equipment-only vendors. Prioritize predictive maintenance contract attachment rates among German discounter chains facing accelerated replacement timelines.
For New Entrants and Emerging Players: Fast-track F-Gas certification partnerships with Polish technical institutes unlock Eastern European food processor demand for modular panel systems bypassing lengthy construction permits. White-space concentrates in independent restaurant retrofit across Spain and Portugal where reach-in replacement cycles outpace incumbent service coverage. Go-to-market leverage rests on remote refrigerant monitoring subscriptions bundled with equipment finance.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded cold storage divisions lacking natural refrigerant engineering capabilities. Five-to-ten-year viability favors specialists with captive compressor technology and pan-European service footprint. Monitor CO2 transcritical adoption rates in Southern European supermarket trials as inflection signal for technology convergence timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Certification Pipeline Investment | Secures technician capacity ahead of EU F-Gas Regulation deadline years in Germany and France. |
| Backward Integration into Polyurethane Panel Fabrication | Captures margin pools from copper and steel input volatility compressing equipment-only vendor margins. |
| Predictive Maintenance Contract Bundling | Converts supermarket cooperative framework agreements into recurring revenue with penalty-backed performance guarantees. |
| Modular Panel System Standardization | Penetrates Eastern European food processor demand where construction permit timelines constrain conventional cold room deployment. |
| CO2 Transcritical Heat Recovery Integration | Opens commercial kitchen and bakery segments previously locked out of natural refrigerant options by ambient climate constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with supermarket procurement directors, commercial kitchen equipment distributors, F-Gas-certified installation contractors, and cold storage facility maintenance managers. Secondary validation drew from EU F-Gas Regulation compliance filings, Ecodesign Directive technical documentation, national environmental agency refrigerant phase-down schedules, and trade customs data for compressor and panel imports. Bottom-up equipment shipment analysis triangulated against top-down cold storage construction permit records across Germany, France, Netherlands, Italy, and Poland.
Across the projection horizon, volume and value outputs reflect segmentation modeling by product type, end-user category, refrigerant technology pathway, and installation configuration. CAGRs were derived from replacement cycle analysis aligned with regulatory compliance timelines and capital expenditure patterns across supermarket chain disclosures. Industry-specific forecast inputs incorporated F-Gas-certified technician pipeline estimates and polyurethane foam insulation thermal conductivity improvement curves.
Decision-makers should treat outputs as directional under base assumptions of sustained EU F-Gas Regulation enforcement and no material commodity metal price dislocation; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Retail Cooler Market