
 US Wine Market | 2026-2036
US Wine Market Size, Share, and Industry Trends Forecast 2026-2036
US Wine Market Intelligence
A shift in purchasing power towards Millennial consumers, who prioritize authenticity and digital engagement, is reorganizing the competitive landscape. E&J Gallo Winery leverages its extensive distribution network to reach this demographic through both off-premise retail and emerging channels. Constellation Brands differentiates its portfolio with brands that resonate with younger drinkers' preferences for sustainable products. Jackson Family Wines sustains its position in the premium segment through its focus on terroir-specific and estate-grown wines.
US wine is an alcoholic beverage produced via the fermentation of grapes, with its identity and quality standards legally defined by American Viticultural Areas (AVAs). These designations, such as Napa Valley or Sonoma Coast, guarantee the geographic origin of at least 85% of the grapes used. The market structure shows significant volume in the Value and Premium price tiers, though growth is pronounced in the Super Premium category. E-commerce and Direct-to-Consumer distribution channels are expanding market share from traditional off-premise retail.
The Alcohol and Tobacco Tax and Trade Bureau (TTB) governs wine production, labeling, and advertising at the federal level. State-specific Alcohol Beverage Control (ABC) boards create a complex patchwork of rules, particularly for interstate shipping and retail sales. Navigating the divergent state regulations for direct-to-consumer sales remains the central challenge for wineries seeking to expand their national footprint.
Market Dynamics
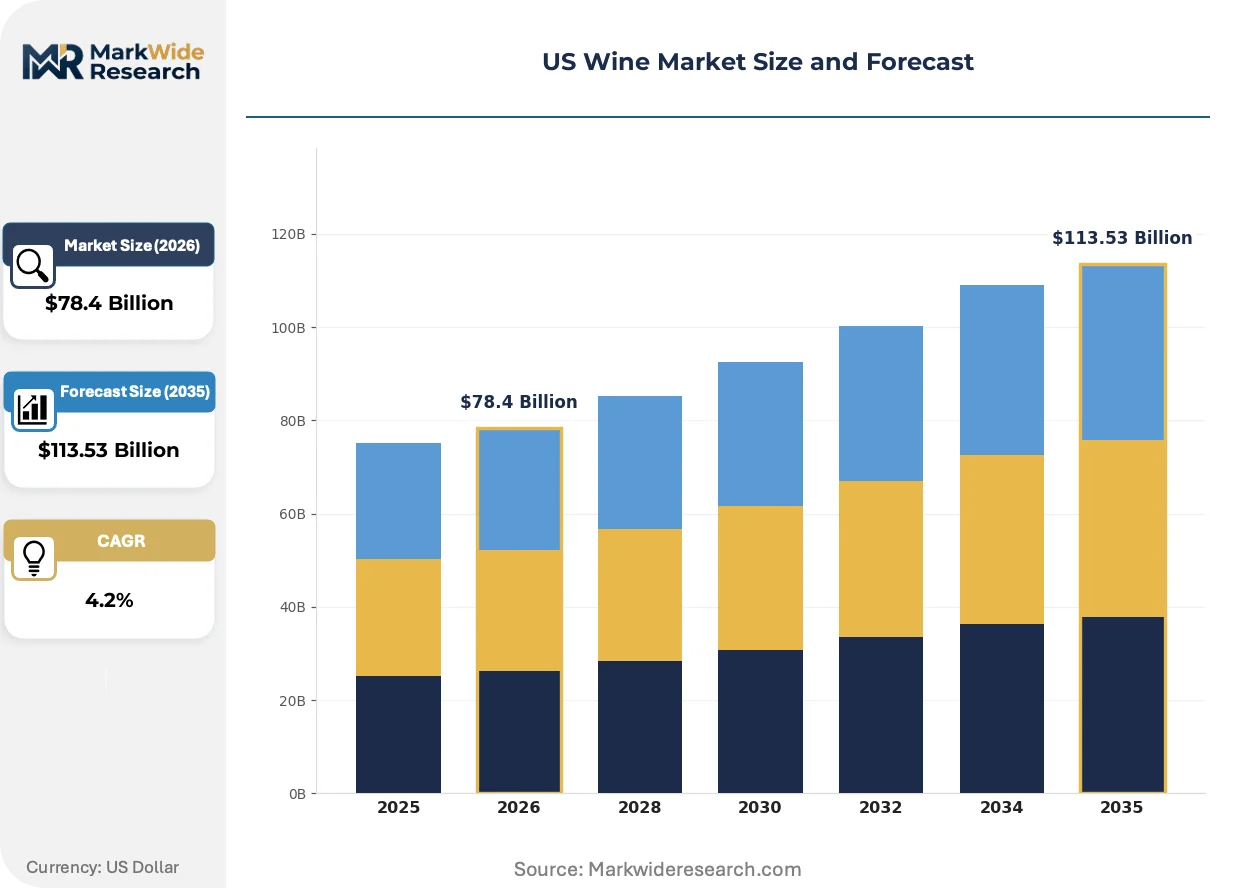
The central tension shaping the US wine market is the collision between fragmented state-level direct-to-consumer shipping laws and the purchasing habits of a digitally native Millennial consumer base demanding seamless e-commerce access to authentic brands.
Growth Catalysts
- Evolving DTC Regulations:The gradual modernization of state laws governing interstate wine shipping continues to open new geographic markets for wineries, particularly smaller producers who rely on direct sales to reach consumers outside traditional distribution.
- Digital Engagement Platforms:The adoption of sophisticated e-commerce and customer relationship management software enables wineries to effectively target Millennial and Gen Z drinkers with personalized marketing and build brand loyalty through digital storytelling.
- Premiumization and Terroir Focus:A strong consumer appetite for premium and super-premium wines, defined by specific American Viticultural Areas (AVAs), supports value growth and encourages investment in quality-driven viticulture and winemaking.
Market Restraints
- Regulatory Patchwork:The inconsistent and complex nature of Alcohol Beverage Control (ABC) board regulations across different states creates significant compliance burdens and logistical hurdles, limiting national market access for many wineries.
- Input Cost Pressures:Climate-related events such as wildfires and droughts, especially in key growing regions like California and Oregon, introduce volatility in grape yields and quality, increasing production costs and supply uncertainty.
- Competitive Beverage Categories:Intense competition from craft spirits, hard seltzers, and ready-to-drink cocktails for consumer attention and share of alcohol consumption, particularly among younger demographics, restrains volume growth.
Strategic Opportunities
- Expansion in Growth States:Targeting the expanding premium wine consumer base in major metropolitan areas within states like Texas and Florida presents a significant opportunity for wineries to capture new demand outside of traditional strongholds.
- Subscription and Club Models:Developing curated wine club and subscription services offers a recurring revenue stream and a direct channel to engage loyal customers, bypassing the complexities of the three-tier system.
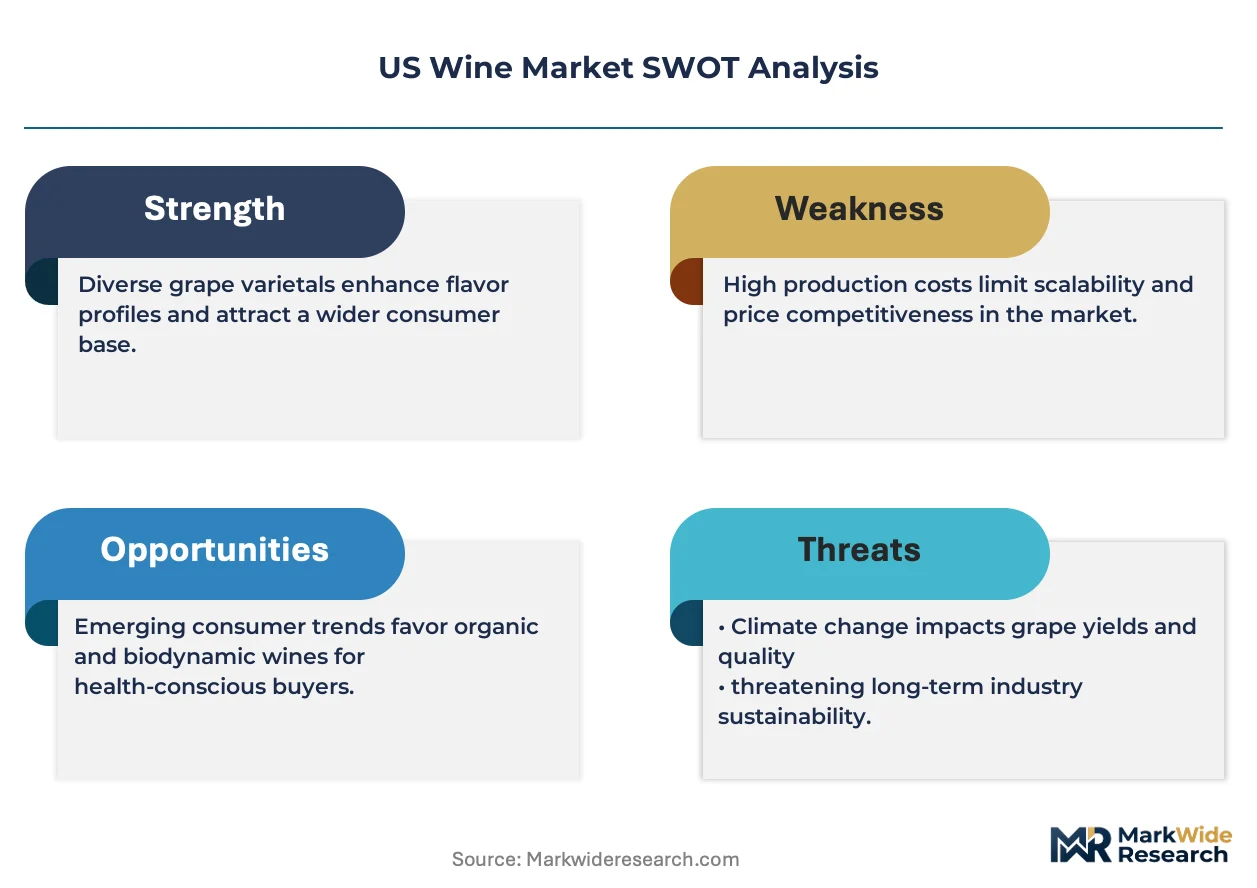
- Sustainable and Niche Wines:There is a growing market for wines produced with certified sustainable, organic, or biodynamic practices, as well as for low-alcohol and no-alcohol alternatives that cater to health-conscious consumers.
Industry Challenges
- Multi-State Compliance:The operational challenge of managing licensing, tax remittance, and reporting requirements for direct-to-consumer shipping across numerous state jurisdictions demands specialized legal and logistical expertise, increasing overhead.
- Logistical Infrastructure Development:Building and scaling a temperature-controlled logistics and fulfillment network for national DTC sales requires significant capital investment, posing a barrier for small and mid-sized wineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wine Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $113.53 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Sparkling Wine, Dessert Wine Distribution Channel: Off-Premise Retail, On-Premise Retail, E-commerce, Direct-to-Consumer Price Tier: Premium, Super Premium, Value, Ultra-Premium Customer Type: Millennials, Gen X, Baby Boomers, Wine Enthusiasts |
| Companies Covered | E&J Gallo Winery, The Wine Group, Constellation Brands, Treasury Wine Estates, Trinchero Family Estates, Delicato Family Vineyards, Jackson Family Wines, Deutsch Family Wine & Spirits, Ste. Michelle Wine Estates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wine Market Strategic Shifts & Innovations
The market is being redefined by the convergence of data-driven production methods and a consumer-led demand for greater transparency in sourcing and brand narrative. This shift prioritizes digital channels and elevates the importance of verifiable product origin, such as AVA designations.
Precision viticulture, utilizing tools like aerial drones and in-field sensors, provides real-time data on soil moisture, vine health, and grape maturity. Wineries in premium AVAs like Napa Valley are increasingly adopting this technology to optimize irrigation and harvest timing. This data-centric management **is decomposing** traditional, intuition-based farming into a series of measurable, controllable inputs, enhancing both yield consistency and the expression of terroir.
Ongoing rule-making by the Alcohol and Tobacco Tax and Trade Bureau (TTB) to establish new American Viticultural Areas (AVAs) directly impacts competitive strategy. The formal recognition of a new AVA provides wineries within its boundaries a powerful tool for geographic branding and product differentiation. This regulatory process most affects producers in emerging wine regions, who can leverage a new AVA designation on their labels to justify premium price points and connect with connoisseurs.
A fundamental change in consumption patterns is seeing a move away from simple retail transactions toward experience-based purchasing. This behavioral shift disrupts the established three-tier system by elevating the role of direct-to-consumer channels like winery e-commerce sites, tasting rooms, and subscription clubs. The trend is most pronounced among younger consumers in urban markets, where brand story and authentic engagement are key drivers of purchasing decisions over simple retail availability.
US Wine Market Segmentation
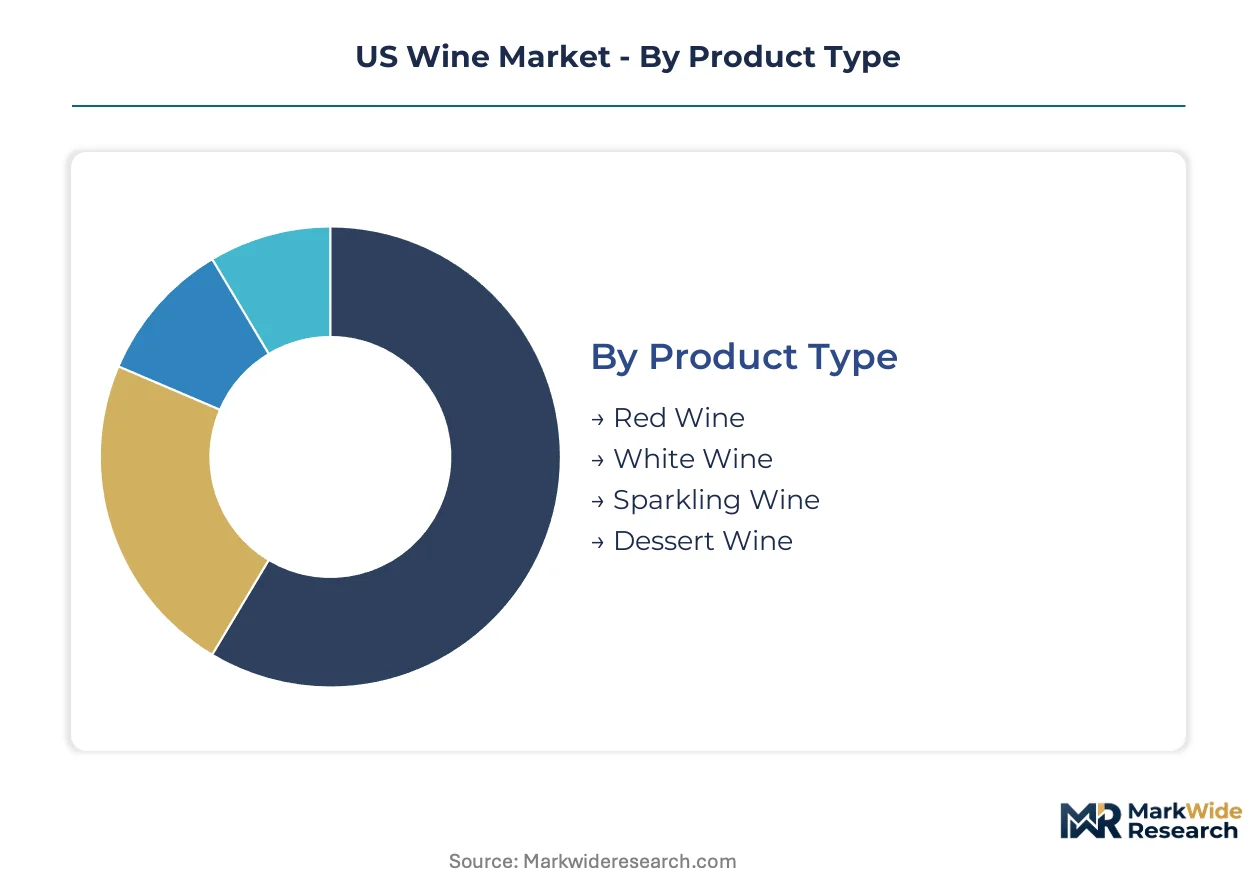
The US wine market segments into distinct categories based on product type, distribution channel, price tier, and customer demographics. Understanding these divisions helps wineries tailor their product offerings and market strategies to specific consumer needs and purchasing behaviors. This segmentation provides clarity on market dynamics and growth opportunities for various stakeholders.
Product Type:
The US wine landscape features diverse product types, each with distinct production concentrations and consumer bases across states.
- Red Wine:This category encompasses wines made from dark-skinned grapes, fermented with their skins to impart color and tannins. Demand for Cabernet Sauvignon and Pinot Noir concentrates in major metropolitan areas like New York and Los Angeles, driven by consumer preference for established varietals.
- White Wine:These wines are produced from green or dark-skinned grapes, fermented without the skins, resulting in lighter colors and often fruitier profiles. Chardonnay and Sauvignon Blanc maintain strong demand across California and Florida, supported by their versatility and broad appeal.
- Sparkling Wine:Characterized by effervescence, these wines undergo a secondary fermentation process. Consumption patterns show growth in celebratory occasions and younger demographics.
- Dessert Wine:Sweet wines, often served with or after meals, are produced using late-harvested grapes or specialized fermentation techniques. This niche segment appeals to consumers seeking unique flavor profiles and specific food pairings.
Red Wine commands the established base. The steepest expansion runs through Sparkling Wine.
Distribution Channel:
Distribution channels for US wine vary significantly in their maturity and digital integration.
- Off-Premise Retail:This channel includes sales through grocery stores, liquor stores, and convenience stores, where wine is purchased for consumption elsewhere. It represents the largest volume channel for wine sales in the US, driven by consumer convenience and broad product availability.
- Direct-to-Consumer:Wineries sell directly to consumers via tasting rooms, wine clubs, and e-commerce platforms. This channel offers higher margins for producers and is expanding rapidly due to evolving state regulations and consumer demand for authentic brand engagement.
- On-Premise Retail:This segment comprises sales in restaurants, bars, and hotels, where wine is consumed on-site. The channel faces fluctuating demand influenced by dining trends and local hospitality regulations.
- E-commerce:Online platforms facilitate wine sales directly to consumers, often through third-party retailers or winery websites. Digital sales are gaining traction, offering convenience and access to a wider selection for consumers.
Traditional retail channels maintain substantial volume. Emerging direct-to-consumer models are rapidly gaining market share.
Price Tier:
Profitability across US wine price tiers reflects varying production costs and consumer willingness to pay for quality cues.
- Super Premium:Wines in this tier typically retail between $15-$25 per bottle, characterized by specific varietals, regional designations, and quality winemaking. Growth in this segment is pronounced in urban centers, driven by consumer appreciation for craftsmanship and perceived value.
- Premium:This tier includes wines priced from $8-$15, offering a balance of quality and affordability. The segment holds significant market volume across diverse consumer groups, supported by widespread availability and consistent quality.
- Value:Wines priced under $8 per bottle constitute this tier, focusing on accessibility and everyday consumption. This segment maintains a large consumer base, particularly in budget-conscious households.
- Ultra-Premium:Wines exceeding $25 per bottle, often from highly regarded AVAs or limited production, define this tier. These wines cater to connoisseurs and collectors, emphasizing rarity and prestige.
The Value segment anchors a broad consumer base. Super Premium wines command the highest per-bottle revenue growth.
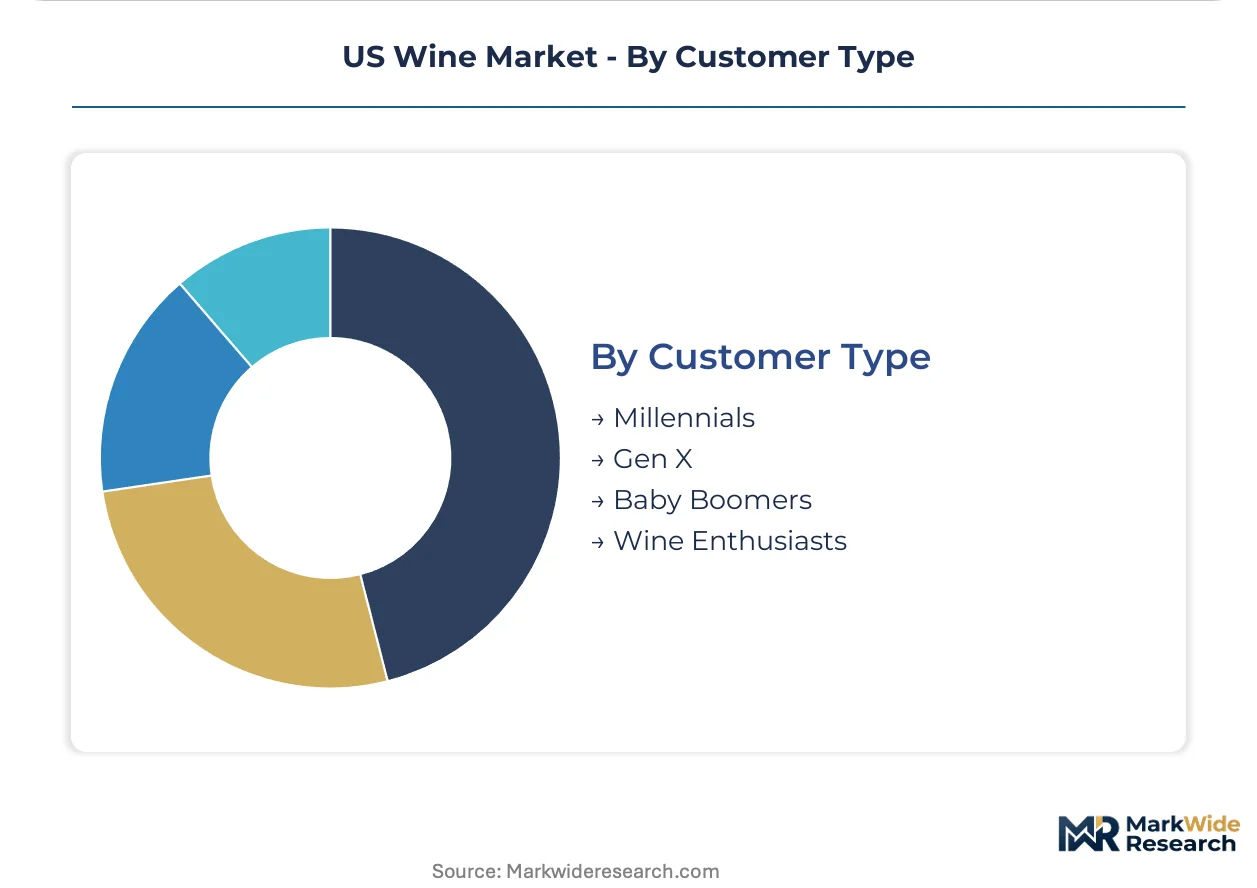
Customer Type:
Each customer type engages with the US wine market through distinct purchasing behaviors and digital preferences.
- Millennials:This demographic, born between 1981 and 1996, prioritizes authenticity, sustainable practices, and digital engagement when purchasing wine. Their demand concentrates in urban markets, where they seek out unique brands and direct-to-consumer experiences.
- Baby Boomers:Born between 1946 and 1964, this group represents a mature and established wine-drinking demographic, often preferring traditional varietals and brand loyalty. Their purchasing power remains significant, particularly in off-premise retail channels.
- Gen X:Consumers born between 1965 and 1980 often balance quality with value, showing interest in both established brands and emerging wine regions. This group exhibits consistent purchasing habits across various channels.
- Wine Enthusiasts:This segment includes consumers with a deep interest in wine, often seeking education, unique varietals, and high-quality offerings. They frequently engage with subscription models and winery events.
Baby Boomers represent a loyal, established consumer group. Millennials are redefining market engagement through digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US wine market sees significant intra-national trade, with established wine-producing states like California exporting extensively to consumer-dense regions such as the New York Metro area. This dynamic shapes distribution networks and regional market access. The evolution of state-specific Alcohol Beverage Control (ABC) rules directly influences these trade flows.
California
California's wine market thrives on consumer demand for premium and super-premium wines, often tied to specific terroir. The state's AVAs, recognized by the TTB, provide crucial branding and differentiation. Wineries in the Napa Valley and Sonoma Coast regions leverage these designations to command higher price points.
Texas
Texas represents a growth state with an expanding premium wine consumer base, particularly in its major metropolitan areas. The TABC oversees all alcohol sales, including the evolving direct-to-consumer shipping regulations within the state. Urban centers such as Houston and Austin demonstrate strong purchasing power for higher-tier wines.
Florida
Florida exhibits consistent demand for white wines and sparkling varieties, supported by its large tourist industry and growing population. The state's Division of Alcoholic Beverages and Tobacco manages licensing and compliance for all wine distribution channels. Metropolitan hubs like Miami and Tampa are key centers for premium wine consumption.
New York Metro
The New York Metro area demonstrates significant Millennial purchasing power and a strong preference for authentic, digitally accessible brands. The NYSLA governs wine sales, including the complex direct shipping rules impacting out-of-state wineries. New York City's urban market leads in adopting e-commerce and wine club models for premium selections.
US Wine Market Key Industry Players
Player mix skews toward established, multi-brand conglomerates alongside specialized, terroir-focused estates. The US wine market exhibits a tiered structure, from large-scale volume producers to boutique, premium segment players. Strategic archetypes include diversified beverage giants, regional specialists, and direct-to-consumer innovators. Dominant competitive moves involve extensive distribution network leverage and portfolio differentiation through sustainable products.
Among established producers, E&J Gallo Winery represents the archetype of a large-scale diversified producer, leveraging its extensive distribution network across various channels. Constellation Brands exemplifies a portfolio differentiator, focusing on brands that resonate with younger drinkers' preferences for sustainable products and modern consumption habits. Jackson Family Wines occupies a position as a premium segment specialist, anchoring its offerings in terroir-specific and estate-grown wines that appeal to connoisseurs. These entities collectively shape the market's competitive dynamics through their distinct approaches to production, branding, and consumer engagement, influencing pricing and market access across various tiers.
| Leading Market Players |
|---|
| E&J Gallo Winery |
| The Wine Group |
| Constellation Brands |
| Treasury Wine Estates |
| Trinchero Family Estates |
| Delicato Family Vineyards |
| Jackson Family Wines |
| Deutsch Family Wine & Spirits |
| Ste. Michelle Wine Estates |
| Others |
Cost & Logistics Intelligence
The rise of alternative packaging formats, such as canned wine, is reshaping material sourcing from traditional glass bottle manufacturers and simultaneously influencing pricing economics for convenient, entry-level wine products. This dynamic encourages wineries to explore diverse supply channels beyond conventional glass suppliers, impacting overall production costs. The shift also allows for greater flexibility in distribution, particularly for outdoor consumption scenarios.
Pricing Analysis
Terroir-specific production methods for premium wines create a pricing gap between mass-produced and AVA-designated offerings. The market operates on a tiered pricing structure across Value, Premium, Super Premium, and Ultra-Premium levels. Price differentiation stems from quality grade, specifically AVA designation, and established brand premium. Pricing softness reflects intense competition from craft spirits and hard seltzers, particularly in the Value segment. Ultra-Premium consumers exhibit the least price sensitivity, valuing rarity and prestige.
Supply Chain Analysis
Port congestion on the West Coast, particularly for imports of wine-making equipment and specialized bottles, increases inbound logistics costs for US wineries. Grape supply concentrates heavily in California, Oregon, and Washington, forming the core raw material dependency. Climate-related events like wildfires and droughts in these key growing regions present a significant structural risk to grape yields and quality. Distribution runs through a complex three-tier system, although direct-to-consumer channels are expanding rapidly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wine market is in an early-cycle expansion, driven by increasing digital engagement and direct-to-consumer channel penetration among Millennial consumers.
For Market Incumbents: Fortify existing distribution networks against emerging direct-to-consumer models while selectively investing in digital platforms. Leverage established brand equity in traditional retail to counter competitive beverage categories. Expand capacity in high-demand American Viticultural Areas like Napa Valley to maintain premium positioning and meet consumer demand. Streamline compliance processes for multi-state shipping to reduce overhead.
For New Entrants and Emerging Players: Lead with niche product differentiation in underserved segments like sustainable, organic, or low-alcohol wines. Target metropolitan areas in growth states like Texas and Florida, where Millennial consumers seek authentic brands. Utilize e-commerce and subscription models for direct market access and compelling brand storytelling. Focus on transparent sourcing and digital engagement to build loyalty.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors agile, digitally-native brands with strong authentic narratives and clear AVA designations. Long-term viability rests on adapting to evolving consumer preferences and navigating complex state-level regulatory landscapes. Identify boutique wineries with established AVA designations and robust direct-to-consumer infrastructure. The signal to watch is the continued modernization of state direct-to-consumer shipping laws.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Enhances brand engagement and offers higher margins by bypassing traditional distribution layers. |
| Sustainable Product Line Introduction | Attracts health-conscious and environmentally aware Millennial consumers seeking ethical brands. |
| Precision Viticulture Investment | Optimizes grape quality and yield, improving consistency and terroir expression in premium wines. |
| Regional Market Entry (e.g., Texas/Florida) | Captures new demand from expanding premium wine consumer bases outside traditional strongholds. |
| Wine Club & Subscription Model Development | Secures recurring revenue streams and fosters deep loyalty with engaged customer segments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of TTB regulations, state ABC board reports, and industry association publications. Primary interviews included winery owners, distribution managers, e-commerce platform providers, and retail buyers across key US wine regions. This process ensured bottom-up market sizing and top-down validation of segment trends and market dynamics.
Product type, distribution channel, price tier, and customer demographics were the segmentation dimensions modeled. The analytical framework projected compound annual growth rates (CAGRs) over the projection horizon, integrating historical data with forward-looking market indicators. Forecast inputs included evolving DTC shipping regulations and consumer premiumization trends across major metropolitan areas.
Forecasts assume regulatory continuity in federal TTB and state ABC frameworks; material policy shifts would require re-modeling. Unforeseen climate events or significant changes in consumer alcohol consumption patterns represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Low-Alcohol Beer Market