
 France Alcohol E-Commerce Market | 2026-2036
France Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
France Alcohol E-Commerce Market Insights
The gap between premium terroir wines and mass-market labels is shifting how French e-commerce platforms curate inventory and price discovery tools. Vinatis leverages direct relationships with Bordeaux and Burgundy châteaux to secure allocation-limited vintages. Millésima anchors its catalog around en primeur futures and cellar-worthy bottles. Nicolas competes through its hybrid click-and-collect network bridging digital convenience with physical store fulfillment.
France alcohol e-commerce encompasses the digital sale and home delivery of wine, beer, spirits, and ready-to-drink beverages, typically requiring age-verification protocols, temperature-controlled logistics, and compliance with France's strict public health advertising codes. Wine dominates transaction volume given France's domestic production base and cultural consumption patterns, though spirits represents the fastest-growing product type as younger buyers explore craft distilleries through subscription services. Third-party marketplaces capture significant traffic but direct sales channels command stronger margin pools by eliminating platform commission structures.
ANSM oversight of health messaging, DGCCRF enforcement of consumer protection standards, and the Evin Law's advertising constraints collectively shape how platforms acquire customers and display product information. France's national pharmaceutical regulator maintains vigilance over alcohol-related health claims in digital marketing. Stakeholders must monitor evolving enforcement patterns around influencer partnerships and app-based delivery promotions.
Market Dynamics
France's Evin Law advertising prohibitions are compressing customer acquisition channels and forcing platforms toward content-driven discovery models that rely on terroir storytelling rather than traditional promotional campaigns.
Growth Catalysts
- Île-de-France same-day infrastructure:Dense urban logistics networks in Paris and inner suburbs enable sub-two-hour delivery windows that convert browsing into immediate purchase behavior among time-constrained professionals.
- ANSM health claim frameworks:Clarified guidance on permissible alcohol-related messaging allows platforms to deploy educational content about responsible consumption without triggering enforcement actions.
- En primeur futures trading:Digital pre-release allocation systems for Bordeaux and Burgundy vintages attract collector capital that locks in revenue months before physical bottling.
Market Restraints
- CNIL age-verification mandates:Strict biometric and document-based identity checks at checkout create friction that elevates cart abandonment rates compared to standard e-commerce categories.
- Temperature-controlled last-mile costs:Refrigerated vehicle requirements for wine transport in summer months inflate per-delivery expenses beyond mass-market parcel economics.
- Château allocation concentration:Limited-release prestige bottlings from classified growth producers remain concentrated among a handful of negociants, constraining platform inventory breadth.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur penetration:Coastal retirement corridors and seasonal tourism flows remain underserved by dedicated alcohol e-commerce infrastructure relative to Paris basin density.
- Spirits subscription convergence:Craft distillery discovery boxes pair with existing wine club logistics to capture younger cohorts exploring beyond traditional grape-based categories.
- Click-and-collect regulatory clarity:DGCCRF guidance on in-store pickup verification protocols enables hybrid fulfillment models that bypass residential delivery constraints.
Industry Challenges
- Sommelier-curator talent scarcity:Platforms struggle to recruit certified wine professionals capable of authoring credible terroir content that satisfies both consumer education needs and Evin Law compliance standards.
- Legacy POS integration friction:Independent wine merchants operating under the Nicolas franchise network face technical barriers synchronizing inventory visibility between physical tills and digital storefronts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Alcohol E-Commerce Market |
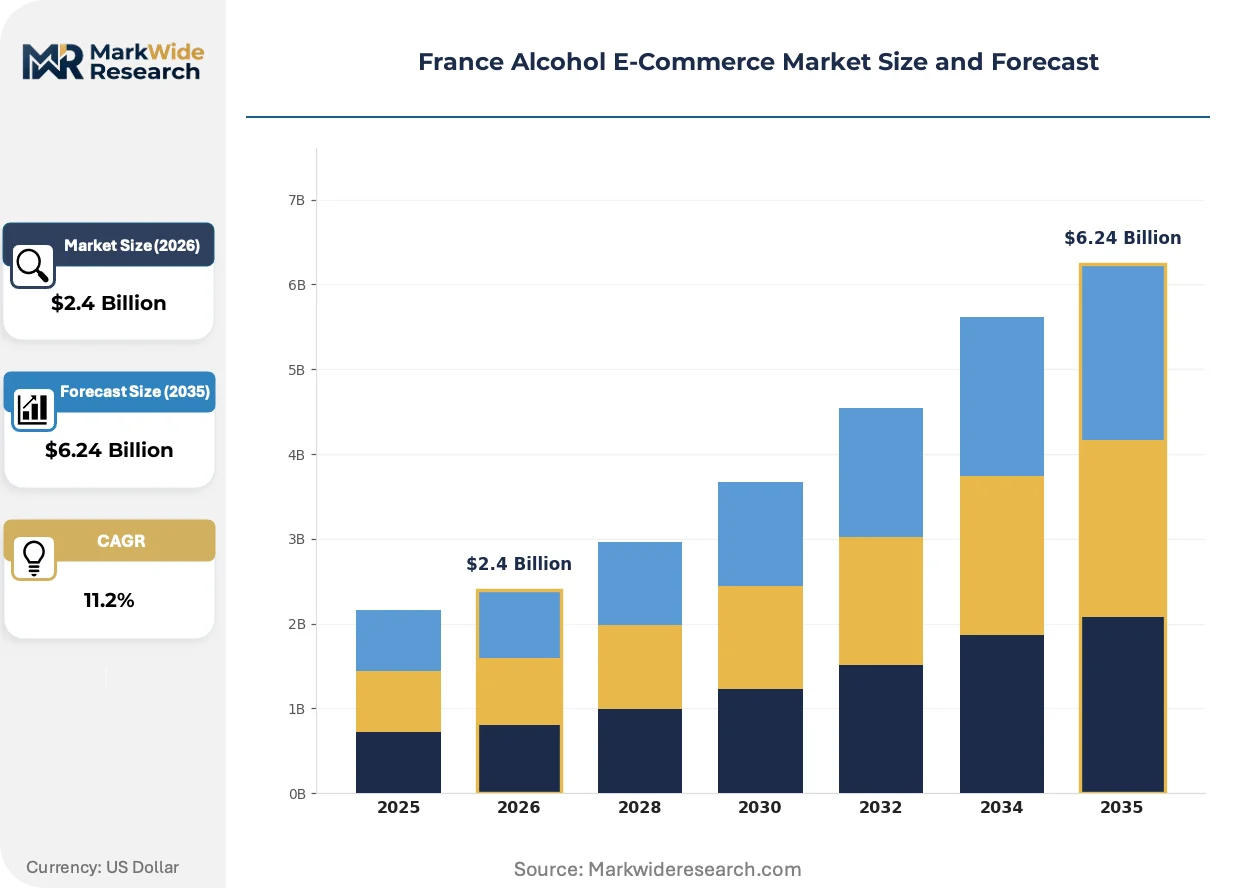
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine, Beer, Spirits, Ready-to-Drink Distribution Channel: Online Retailers, Direct Sales, Third-Party Marketplaces, Subscription Services Price Tier: Premium, Mid-Range, Economical, Luxury Customer Type: Individuals, Corporations, Events, Retailers |
| Companies Covered | Vinatis, Vivino, Millésima, Nicolas, La Maison du Whisky, Drinks&Co, Carrefour Ma Cave, E.Leclerc Ma Cave, Cdiscount Vins & Champagnes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Alcohol E-Commerce Market Trends and Innovations
Artificial intelligence recommendation engines are displacing traditional curation hierarchies and enabling personalized discovery pathways that surface obscure appellations matched to individual palate profiles.
Blockchain provenance tracking is overtaking paper-based certification for high-value allocations. Collector buyers in Lyon and Bordeaux now demand immutable harvest-to-delivery records. This compression of trust verification is reducing return rates on premium purchases and locking buyer loyalty to platforms with deployed ledger infrastructure.
DGCCRF enforcement patterns around influencer partnerships are tightening disclosure requirements for alcohol-related social media content. Platforms must now audit third-party creator contracts for explicit age-gating and health warning integration. The spirits segment faces the steepest compliance burden as cocktail culture content dominates youth-oriented channels.
Subscription-based purchasing is displacing transactional bottle buying among urban millennials. Monthly curated selections from Loire and Rhône producers replace supermarket restocking cycles. This shift concentrates demand forecasting complexity in Île-de-France and Grand Est warehouse operations where inventory must align with predicted preference clusters rather than individual SKUs.
France Alcohol E-Commerce Market Segmentation
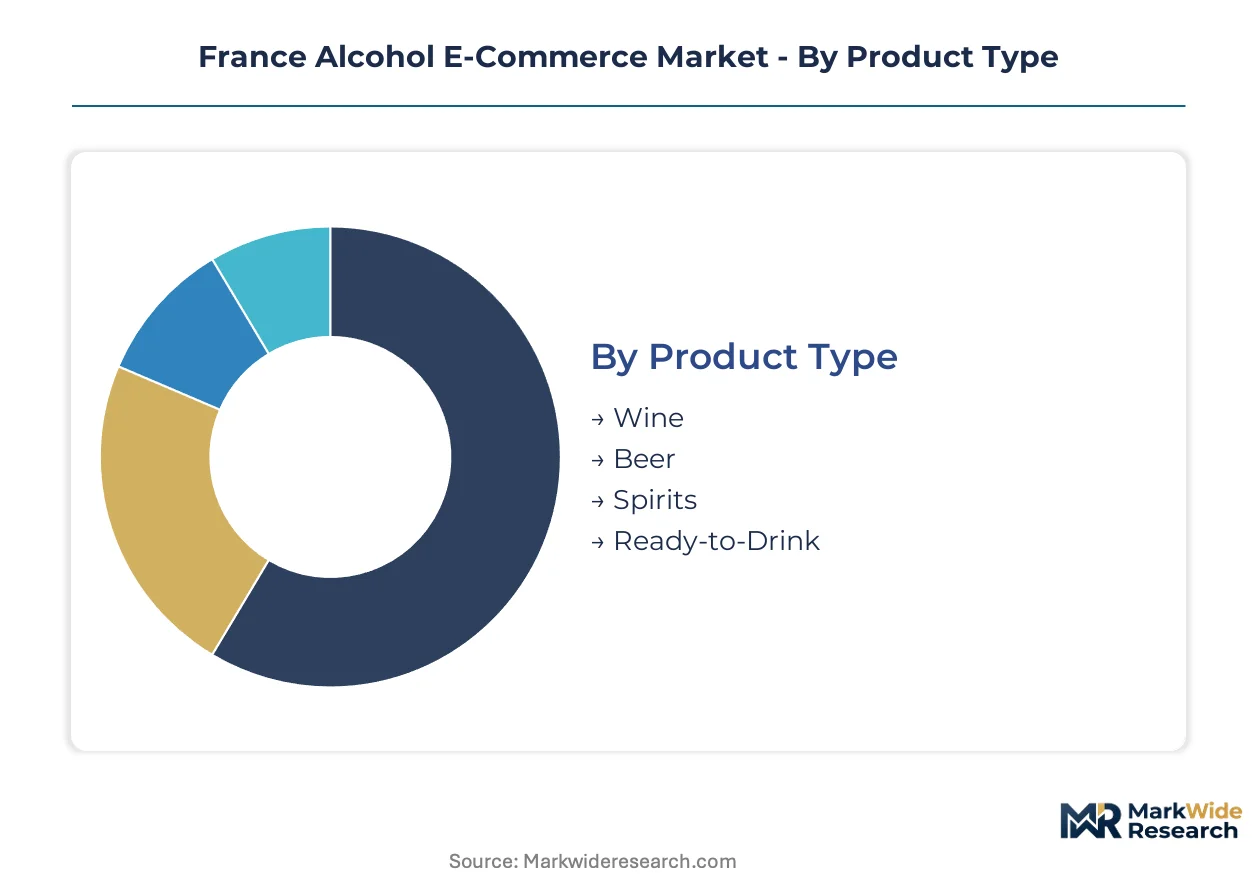
France's alcohol e-commerce platforms curate inventory across multiple dimensions to match Evin Law constraints with divergent buyer preferences. Segmentation strategies determine fulfillment infrastructure investments and margin capture potential.
Product Type:
Supply concentration among Bordeaux and Burgundy châteaux shapes platform procurement strategies and allocation access.
- Wine:Domestic production from Loire, Rhône, and Champagne appellations dominates transaction volume. Île-de-France professionals drive demand for same-day delivery of AOC-classified bottles, constrained by château allocation limits.
- Spirits:Craft distillery discovery through subscription models attracts urban millennials exploring beyond traditional categories. Cognac and Armagnac reserves from southwestern producers anchor collector demand in Lyon and Bordeaux.
- Beer:Regional microbreweries in Grand Est and Hauts-de-France supply specialty retailers with limited-run releases.
- Ready-to-Drink:Pre-mixed cocktail formats gain traction among younger buyers seeking convenience without home bartending equipment.
Wine absorbs the bulk of installed capacity; spirits is expanding most quickly.
Distribution Channel:
Margin structures vary sharply across fulfillment models, with direct channels capturing superior economics versus marketplace commissions.
- Online Retailers:Specialist platforms maintain temperature-controlled warehouses in Île-de-France to enable sub-two-hour delivery windows. These operators invest in sommelier-curated content to satisfy Evin Law compliance while driving discovery.
- Direct Sales:Château-owned e-commerce portals eliminate intermediary margins and capture full allocation value. Burgundy producers leverage this channel for limited-release vintages unavailable through wholesale networks.
- Third-Party Marketplaces:Generalist platforms aggregate traffic but compress margins through commission structures and promotional pricing pressure.
- Subscription Services:Monthly curated selections concentrate demand forecasting complexity in warehouse operations, requiring predictive alignment with preference clusters rather than individual SKUs.
Online retailers command the deepest fulfillment infrastructure; subscription services are climbing the fastest.
Price Tier:
Buyer segmentation by expenditure level determines platform authentication protocols and provenance verification investments.
- Premium:AOC-classified wines and single-estate spirits require blockchain provenance tracking to satisfy collector verification demands in Lyon and Bordeaux.
- Mid-Range:Regional appellations and established distillery brands balance margin capture with volume throughput in Grand Est logistics hubs.
- Economical:Mass-market labels face pricing pressure from supermarket private labels, limiting platform differentiation opportunities.
- Luxury:En primeur futures and allocated prestige bottlings attract investment-oriented buyers seeking cellar-worthy appreciation potential.
Premium tier absorbs the bulk of platform authentication investment; luxury is gaining share fastest among collector demographics.
Customer Type:
Procurement patterns diverge sharply between individual consumption and institutional volume requirements.
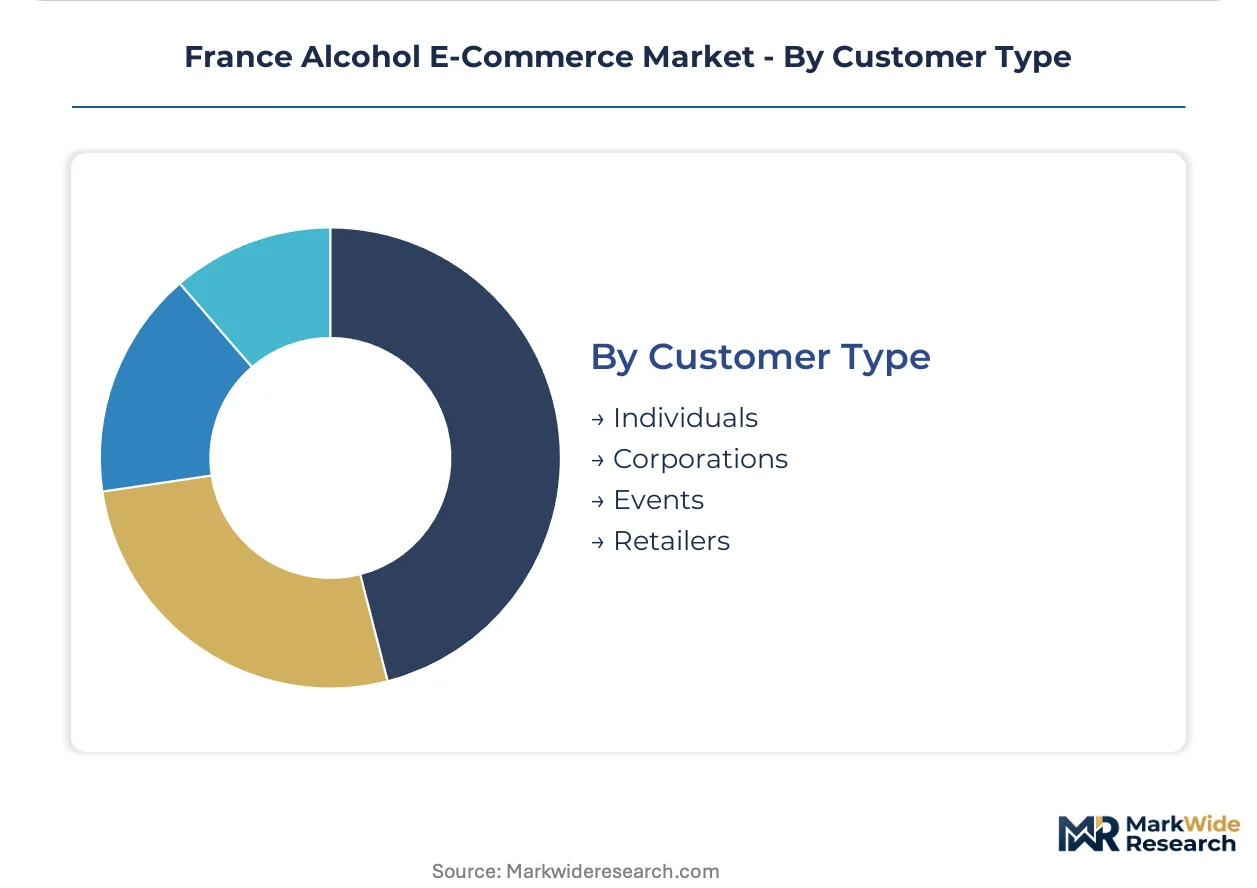
- Individuals:Urban millennials in Paris and Lyon drive recurring purchases through mobile-optimized discovery interfaces. Age-verification friction at checkout elevates cart abandonment relative to standard e-commerce categories.
- Corporations:Hospitality groups and investment funds purchase en primeur allocations and cellar collections through dedicated account management.
- Events:Wedding and corporate catering planners require flexible delivery scheduling and bulk-format packaging.
- Retailers:Independent wine merchants leverage hybrid click-and-collect models to synchronize physical inventory with digital storefront visibility.
Individuals generate the highest transaction frequency; corporations deliver the steepest average order values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors France's alcohol e-commerce density, with Île-de-France's same-day delivery infrastructure commanding the densest fulfillment network and highest transaction velocity in the national market.
Île-de-France
Urban professionals in Paris and inner suburbs drive sub-two-hour delivery demand for AOC-classified wines. ANSM oversight of health messaging shapes platform content strategies. The capital's logistics corridors concentrate temperature-controlled warehouse capacity serving collector buyers and corporate hospitality accounts.
Auvergne-Rhône-Alpes
Lyon's affluent demographic sustains premium wine discovery through mobile-optimized interfaces. CNIL age-verification mandates create checkout friction that elevates cart abandonment. The city's established négociant relationships anchor allocation access for Burgundy and northern Rhône bottlings.
Provence-Alpes-Côte d'Azur
Coastal retirement corridors and seasonal tourism flows generate underserved demand for dedicated alcohol e-commerce infrastructure. DGCCRF enforcement of consumer protection standards tightens disclosure requirements for influencer partnerships. Nice and Cannes lack the fulfillment density of Paris basin operations.
Nouvelle-Aquitaine
Bordeaux's château allocation systems attract en primeur futures trading through direct sales portals. The Evin Law's advertising prohibitions compress customer acquisition channels for regional platforms. The city's wine merchant heritage supports hybrid click-and-collect models bridging physical and digital fulfillment.
Hauts-de-France
Regional microbreweries in Lille and surrounding areas supply specialty retailers with limited-run beer releases. Temperature-controlled last-mile costs inflate per-delivery expenses during summer months. The logistics hub's proximity to Belgian and UK markets positions it for cross-border spirits distribution expansion.
France Alcohol E-Commerce Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fulfillment sophistication and allocation access. Specialist wine platforms command superior economics through direct château relationships and en primeur futures trading. The vendor base clusters into three strategic archetypes: pure-play digital specialists with sommelier-curated catalogs, hybrid omnichannel operators bridging physical and digital fulfillment, and generalist marketplaces aggregating traffic through promotional pricing. Competitive moves concentrate on securing allocation-limited vintages and deploying blockchain provenance infrastructure.
Within the pure-play specialist tier, Vinatis and Millésima exemplify archetypes built around direct producer relationships and collector-oriented curation. Nicolas occupies a position bridging franchise retail heritage with digital storefront expansion. These three anchors represent divergent strategic postures: allocation-focused futures trading, terroir storytelling compliance, and hybrid click-and-collect density.
| Leading Market Players |
|---|
| Vinatis |
| Vivino |
| Millésima |
| Nicolas |
| La Maison du Whisky |
| Drinks&Co |
| Carrefour Ma Cave |
| E.Leclerc Ma Cave |
| Cdiscount Vins & Champagnes |
| Others |
Pricing and Supply Chain Analysis
Captive supply relationships with Bordeaux and Burgundy châteaux anchor both inventory access and margin capture for French alcohol e-commerce platforms, creating pricing power that commodity retailers cannot replicate. Direct allocation agreements eliminate intermediary markups while Evin Law compliance investments erect barriers that protect incumbent economics.
Pricing Analysis
Value-based pricing tied to harvest quality and allocation scarcity anchors premium tier positioning. Three-tier pricing structure across en primeur futures, AOC-classified bottles, and mass-market labels reflects château reputation and provenance verification depth. Pricing pressure stems from supermarket private-label competition in the economical tier, compressing platform differentiation. Corporate hospitality buyers show lowest price sensitivity; individual millennials in Île-de-France exhibit highest sensitivity to delivery fees.
Supply Chain Analysis
Single-source vulnerability sits with château allocation systems concentrated among Bordeaux and Burgundy negociants. Geographic supply concentration centers on France's domestic wine regions, with Cognac and Armagnac reserves drawing from southwestern producers. Raw material dependencies include temperature-controlled vehicle fleets, age-verification technology stacks, and sommelier-curator talent pools. Supply chain risk manifests through château allocation concentration limiting inventory breadth. Distribution runs through hybrid click-and-collect nodes bridging physical and digital fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's alcohol e-commerce market functions as a cost-of-compliance story where Evin Law advertising prohibitions create barrier-to-entry moats favoring platforms with established terroir content capabilities and regulatory expertise.
For Market Incumbents: Cement allocation relationships with classified growth producers through multi-year en primeur commitments that lock in inventory access. Deepen direct-to-château e-commerce infrastructure to bypass negociant margins, while investing in blockchain provenance tracking to satisfy collector verification demands in Lyon and Bordeaux against emerging marketplace competitors. For New Entrants and Emerging Players: Begin with spirits subscription convergence targeting urban millennials exploring craft distilleries, as this segment faces lower château allocation barriers than wine. Provence-Alpes-Côte d'Azur's coastal retirement corridors offer penetrable white-space with underserved fulfillment infrastructure. Deploy mobile-optimized discovery interfaces with embedded age-verification to reduce CNIL-mandated checkout friction. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hybrid omnichannel operators seeking digital capability augmentation. Long-term viability over the next decade hinges on platforms with deployed temperature-controlled logistics and direct château relationships. Monitor DGCCRF enforcement patterns around influencer partnerships as an inflection indicator for customer acquisition cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Château Allocation Agreement | Secures limited-release inventory unavailable through wholesale networks, locking in premium margin pools. |
| Blockchain Provenance Deployment | Reduces return rates on high-value purchases by compressing trust verification for collector buyers in Bordeaux. |
| Spirits Subscription Launch | Captures younger cohorts exploring craft distilleries through curated discovery boxes paired with wine logistics. |
| Click-and-Collect Network Expansion | Enables hybrid fulfillment that bypasses residential delivery constraints under clarified DGCCRF protocols. |
| Sommelier-Curator Talent Acquisition | Satisfies Evin Law compliance standards while authoring credible terroir content that drives organic discovery. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving platform operations directors, château export managers, DGCCRF compliance officers, and logistics providers specializing in temperature-controlled transport. Secondary sources included ANSM guidance documents, CNIL age-verification frameworks, Evin Law enforcement patterns, and Île-de-France delivery infrastructure databases. Bottom-up transaction volume estimates triangulated against top-down market sizing from customs export records and platform revenue disclosures.
Data-stream reconciliation across shipment volumes, average order values, and regional delivery density informed the analytical framework. Segmentation dimensions modeled encompassed product type, distribution channel, price tier, and customer archetype across the projection horizon. CAGRs derived from logistic curve fitting against historical penetration rates, with inputs including château allocation release schedules, same-day delivery capacity expansion timelines, and spirits subscription growth trajectories.
Underlying measurement precision varies by segment; en primeur futures and luxury tier transactions carry tighter precision than mass-market volume estimates. Forecasts reflect assumptions around regulatory enforcement consistency, logistics cost trajectories, and generational consumption pattern shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Asia-Pacific Tequila Market