
 Premix Bottled Cocktails Market | 2026-2036
Premix Bottled Cocktails Market Size, Share, and Industry Trends Forecast 2026-2036
Premix Bottled Cocktails Market Analytics
Multi-source flavor procurement is expanding as bottlers diversify botanical and spirit bases across hemispheres. Diageo plc leverages its integrated supply network to secure consistent ingredient quality across continents. Bacardi Limited anchors Caribbean rum heritage into premix formulations that sustain tropical flavor authenticity. Suntory Holdings Limited competes through Japanese whisky-infused variants that occupy premium shelf positions in Asian and North American channels.
Premix bottled cocktails comprise pre-blended alcoholic beverages sealed in retail-ready containers, typically formulated to precise alcohol-by-volume specifications between 4% and 15% with stabilized flavor emulsions for shelf consistency. These products serve commercial and home consumption by eliminating on-site mixing labor while delivering batch-standardized taste profiles. Ready-to-Drink formats dominate volume throughput in supermarket and convenience channels where grab-and-go purchasing prevails. Craft Cocktails command concentrated margin pools in specialty stores and online retail, where premium shoppers accept price premiums for small-batch provenance and artisanal ingredient claims. Cans lead packaging type growth due to lightweight logistics, rapid chilling properties, and aluminum recycling infrastructure maturation across developed markets.
FDA labeling requirements govern alcohol content disclosure and allergen warnings in the United States, while EU REACH frameworks regulate flavor additive safety thresholds and migration limits from coated metal packaging. TTB certificate-of-label approval processes in the United States create compliance lead times that shape product launch cadences and reformulation cycles. Stakeholders must monitor evolving extended producer responsibility mandates for single-use beverage containers across multiple jurisdictions, as deposit-return schemes and recycled-content minimums will determine which packaging formats achieve cost-competitive scale.
Market Dynamics
The EU's F-Gas Regulation and evolving packaging waste directives are compressing reformulation timelines and forcing material substitutions across European production lines. Bottlers must reconcile aluminum sourcing constraints with extended producer responsibility mandates while maintaining shelf-stable emulsion chemistry.
Growth Catalysts
- Urban Hospitality Corridor Expansion:Premium shoppers in dense metropolitan zones are shifting procurement toward canned formats that enable grab-and-go consumption without on-site labor. This concentration creates volume anchors for specialty retail channels.
- Aluminum Recycling Infrastructure Maturation:Deposit-return schemes and closed-loop collection systems in developed markets are lowering packaging compliance costs. Bottlers leveraging this infrastructure gain margin flexibility against glass-dependent competitors.
- Flavor Emulsion Stabilization:Advances in lipid-compatible preservation chemistry are extending shelf consistency for botanical-forward formulations. This technical progress enables multi-source ingredient procurement across hemispheres without taste degradation.
Market Restraints
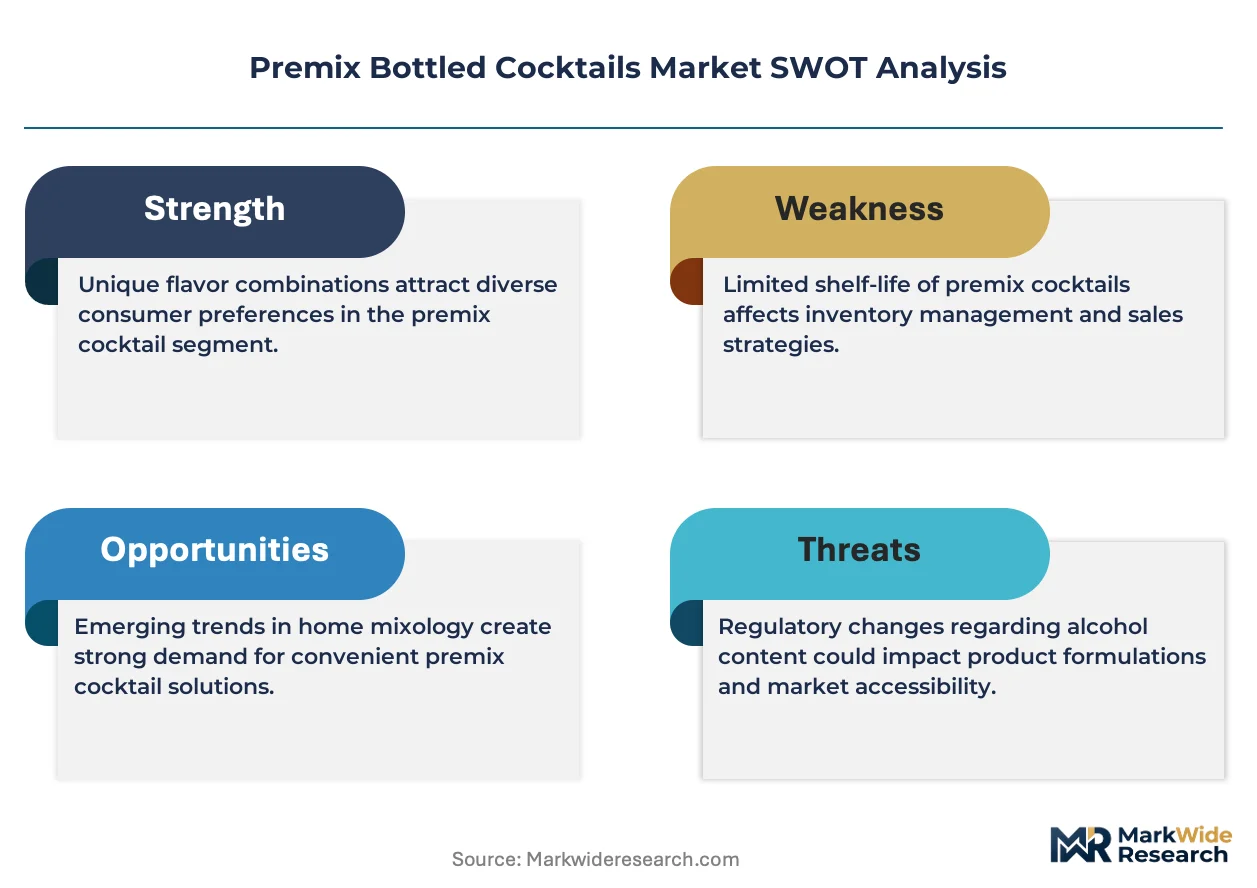
- TTB Certificate-of-Label Approval Friction:The United States Alcohol and Tobacco Tax and Trade Bureau's review timelines create 90-120 day launch delays that compress product development windows and elevate working capital requirements.
- Spirit Base Concentration Risk:Caribbean rum supply chains face climate vulnerability and shipping bottlenecks that threaten tropical flavor authenticity for heritage-dependent formulations.
- Glass-to-Metal Migration Costs:Existing bottling lines require retooling investments to handle aluminum can seaming and internal coating specifications, creating stranded asset risk for capital-intensive facilities.
Strategic Opportunities
- Japanese Whisky-Infused Variant Expansion:Premium shelf positions in Asian and North American channels remain underpenetrated for Japanese spirit-forward premixes, creating whitespace for provenance-focused positioning.
- E-Commerce Direct-to-Consumer Channel Development:Specialty retail consolidation is pushing craft cocktail producers toward owned digital channels where small-batch storytelling commands price premiums unavailable in supermarket allocations.
- EU REACH Framework Compliance Services:Flavor additive safety documentation and migration testing requirements create advisory revenue potential for laboratories and regulatory consultancies serving mid-tier bottlers.
Industry Challenges
- Emulsion Chemistry Talent Scarcity:Formulation scientists capable of stabilizing alcohol-fat-water interfaces across temperature ranges command premium compensation that strains R&D budgets for emerging producers.
- Multi-Jurisdiction Label Harmonization:Divergent allergen disclosure thresholds between FDA and EFSA frameworks force SKU proliferation or lowest-common-denominator labeling that sacrifices market-specific claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premix Bottled Cocktails Market |
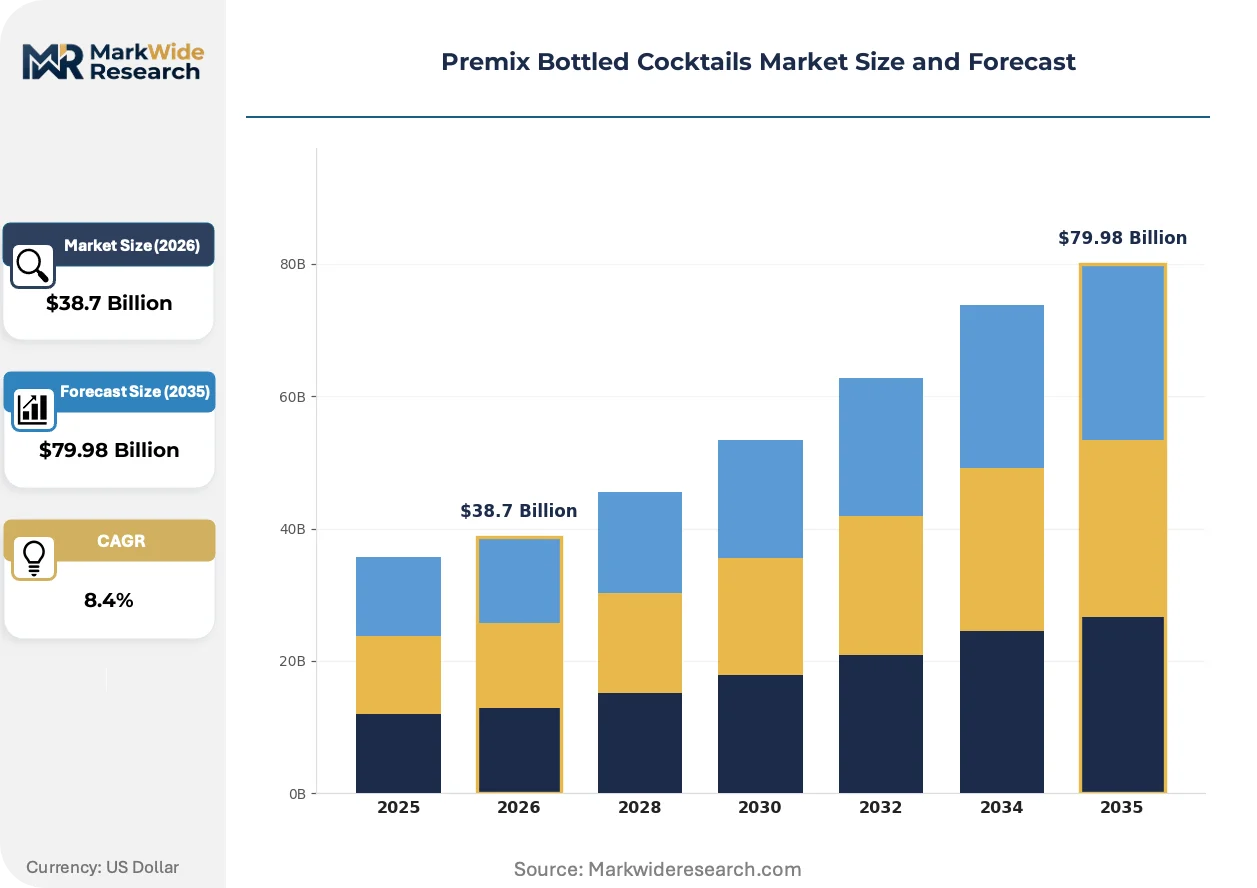
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Low-Alcohol Cocktails, Craft Cocktails, Flavored Mixes Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Bars Customer Type: Millennials, Health-Conscious Consumers, Premium Shoppers, Casual Drinkers Packaging Type: Glass Bottles, Cans, Pouches, Tetra Packs |
| Companies Covered | Diageo plc, Anheuser-Busch InBev SA/NV, Pernod Ricard SA, Bacardi Limited, Constellation Brands, Inc., Suntory Holdings Limited, Brown-Forman Corporation, Campari Group, Asahi Group Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premix Bottled Cocktails Market Evolving Landscape
Formulation science and packaging engineering are converging to reshape competitive positioning, with regulatory compliance emerging as a technical differentiator rather than pure cost burden. Material specifications and channel configuration are becoming inseparable design decisions.
High-pressure processing technology is unifying pasteurization and flavor preservation functions previously handled through thermal or chemical methods. Mid-sized craft bottlers in the United States are adopting this equipment at accelerating rates to claim "never heated" positioning on specialty retail shelves. This shift is unifying quality signaling with operational efficiency, compressing the traditional trade-off between shelf stability and taste fidelity.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration equipment that chills premix inventory through distribution channels. Industrial consequence includes accelerated capital replacement cycles for cold-chain logistics providers serving European markets. Specialty retailers in Germany and France are responding by consolidating supplier relationships with bottlers offering ambient-stable formulations that reduce refrigeration dependency.
Home consumption occasions are displacing on-premise mixing rituals as younger demographics prioritize convenience without sacrificing perceived craft authenticity. Supermarket and convenience channels are capturing volume previously routed through bars and restaurants, with canned formats dominating these transfers. This behavioral rotation is most visible in United States coastal metropolitan corridors where apartment dwellers lack space for home bar setups.
Premix Bottled Cocktails Market Segmentation
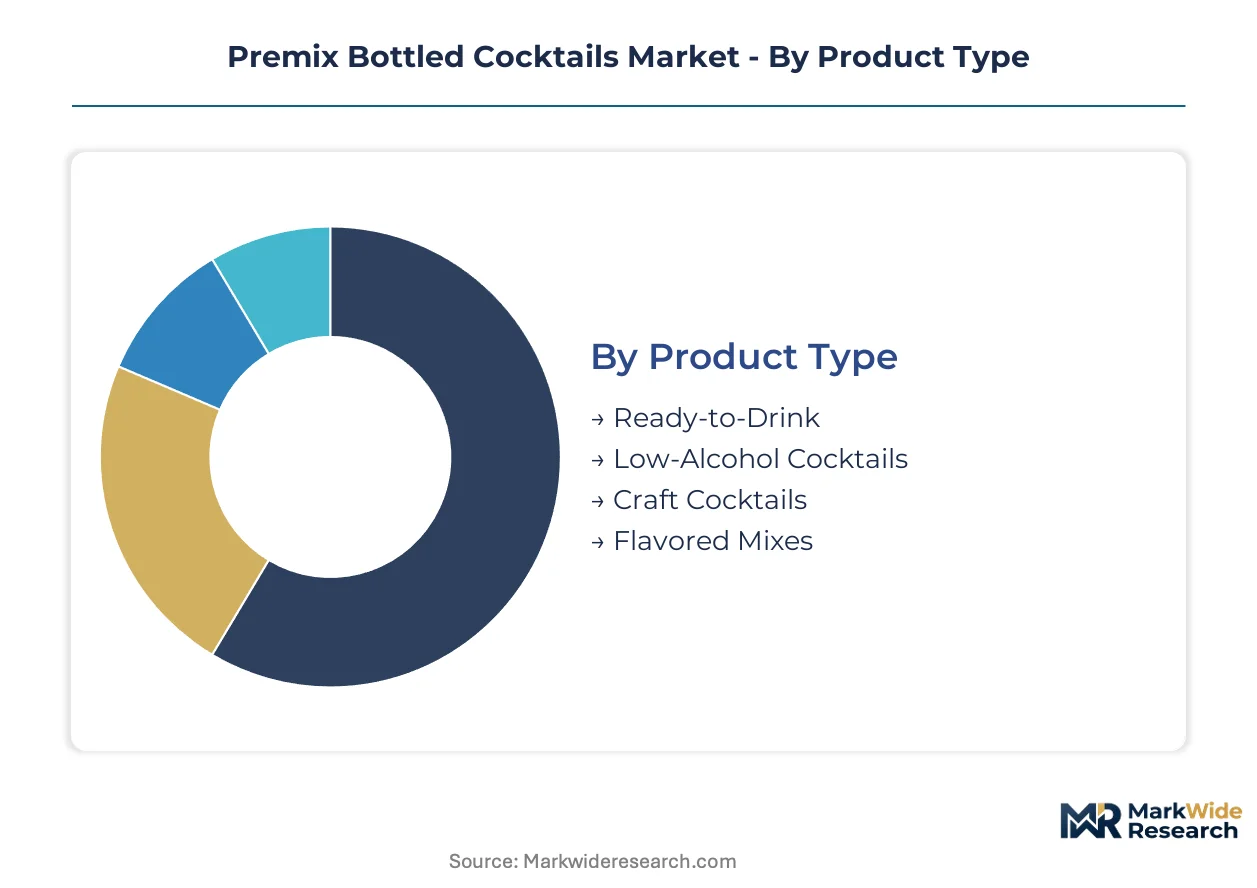
Premix bottled cocktails fragment across four distinct taxonomies that determine regulatory exposure, margin capture, and channel access. Each segmentation layer imposes specific compliance burdens and production constraints that reshape competitive positioning.
Product Type:
TTB certificate-of-label approval requirements vary sharply across alcohol-by-volume thresholds, with craft formulations facing extended review timelines due to non-standard ingredient declarations.
- Ready-to-Drink:Pre-blended formulations standardized between 4% and 15% ABV with stabilized emulsion chemistry for ambient shelf stability. Volume concentrates in United States supermarket and convenience channels where grab-and-go purchasing dominates. Aluminum can formats capture share fastest due to deposit-return scheme compatibility.
- Craft Cocktails:Small-batch productions emphasizing artisanal ingredient provenance and heritage spirit bases. Demand clusters in specialty retail and direct-to-consumer channels where premium shoppers accept price premiums for batch-specific storytelling. TTB label friction compresses launch cadences for rotational flavor programs.
- Low-Alcohol Cocktails:Sub-4% ABV variants targeting health-conscious consumption occasions.
- Flavored Mixes:Non-alcoholic bases requiring consumer-supplied spirit addition.
Leading the category by volume: Ready-to-Drink. Growing fastest: Craft Cocktails.
Distribution Channel:
Channel selection dictates cold-chain requirements, age-verification protocols, and margin retention structures.
- Supermarkets:High-velocity retail environments demanding ambient-stable formulations and standardized case configurations. United States coastal metropolitan corridors generate concentrated throughput for canned formats. Slotting fee structures favor established bottlers with TTB compliance track records.
- Specialty Stores:Curated retail environments prioritizing provenance narratives and limited-batch exclusivity. Japanese whisky-infused variants command premium shelf positions in Asian and North American urban corridors. Staff education requirements elevate brand storytelling investment.
- Online Retail:Direct-to-consumer platforms requiring age-gating infrastructure and state-by-state shipping compliance.
- Bars:On-premise channels seeking labor-cost reduction through pre-batch consistency.
Dominating volume throughput: Supermarkets. Expanding most quickly: Online Retail.
Customer Type:
Demographic targeting determines flavor portfolio composition, packaging format preference, and price-point architecture.
- Millennials:Convenience-oriented cohort prioritizing grab-and-go formats and social-media-compatible packaging aesthetics. Urban apartment dwellers in United States coastal corridors drive canned format adoption due to space-constrained home bar setups. Rotational flavor novelty sustains repeat purchase frequency.
- Premium Shoppers:Provenance-focused buyers accepting price premiums for heritage spirit authenticity and small-batch production claims. Caribbean rum heritage formulations anchor tropical flavor preferences. Specialty retail consolidation pushes this segment toward owned digital channels.
- Health-Conscious Consumers:Sub-4% ABV and botanical-forward formulation seekers.
- Casual Drinkers:Occasional consumption households prioritizing value-tier pricing.
Generating highest per-unit margins: Premium Shoppers. Expanding addressable base fastest: Millennials.
Packaging Type:
Material specifications determine EU REACH migration testing requirements, extended producer responsibility compliance costs, and cold-chain dependency.
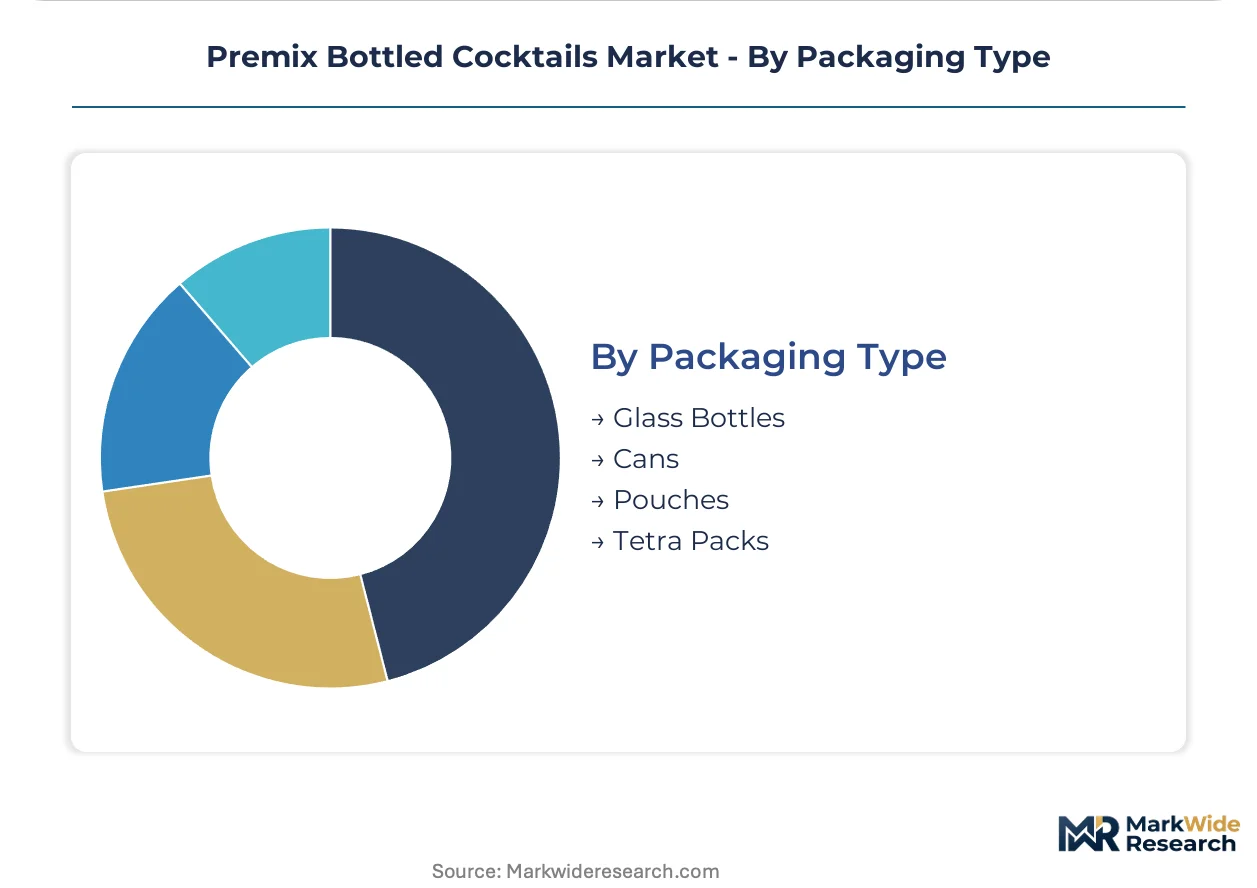
- Cans:Aluminum formats enabling lightweight logistics, rapid chilling, and closed-loop recycling infrastructure. EU F-Gas Regulation pressures are accelerating ambient-stable formulation development to reduce refrigeration dependency. Deposit-return scheme maturation across developed markets lowers compliance cost burden relative to glass.
- Glass Bottles:Premium positioning formats requiring heavier logistics investment and higher breakage risk. Existing bottling lines face stranded asset risk from retooling requirements for aluminum seaming equipment. Internal coating specifications for metal migration compliance add capital intensity.
- Pouches:Flexible formats targeting outdoor consumption occasions.
- Tetra Packs:Aseptic carton systems for ambient-stable juice-forward formulations.
Commanding volume leadership: Cans. Steepest expansion trajectory: Glass Bottles in premium craft sub-segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caribbean rum heritage anchors supply chains for tropical formulations, while metropolitan consumption corridors in developed markets drive format innovation. Regulatory divergence between FDA and EU REACH frameworks shapes regional go-to-market strategies. Urban density and aluminum recycling infrastructure maturity determine packaging transitions.
United States
Coastal metropolitan corridors generate concentrated throughput for canned formats as apartment-dwelling millennials displace home bar setups. TTB certificate-of-label approval creates 90-120 day friction that compresses product launch windows. Specialty retail channels in New York and Los Angeles command premium positioning for craft cocktail sub-segments.
Germany
The EU F-Gas Regulation phases down hydrofluorocarbon refrigeration equipment, forcing ambient-stable formulation development. Deposit-return schemes lower aluminum packaging compliance costs relative to glass-dependent competitors. Industrial clusters in Bavaria and North Rhine-Westphalia host bottling lines retooling for internal coating specifications.
Japan
Japanese whisky-infused variants occupy premium shelf positions across Asian and North American export channels. METI standards govern flavor additive safety thresholds for domestic distribution. Tokyo and Osaka metropolitan zones concentrate demand for high-ABV craft formulations with provenance storytelling.
United Kingdom
Specialty retail consolidation pushes craft producers toward owned digital channels where batch-specific claims command price premiums. EFSA allergen disclosure thresholds diverge from FDA frameworks, forcing SKU proliferation. London hospitality corridors drive canned format adoption for grab-and-go consumption.
Australia
TGA-equivalent state-level alcohol regulators govern labeling requirements that vary across New South Wales, Victoria, and Queensland. High-pressure processing technology adoption accelerates among mid-sized craft bottlers seeking "never heated" positioning. Sydney and Melbourne urban density supports aluminum recycling infrastructure maturation.
Premix Bottled Cocktails Market Competitive Landscape
Global majors compete with regional champions across spirit base authenticity and channel access. The vendor base stratifies between integrated beverage conglomerates with captive distribution and craft specialists dependent on specialty retail relationships. Three archetypes dominate: heritage spirit owners leveraging provenance claims, diversified alcohol portfolios optimizing cross-category logistics, and Japanese whisky-forward specialists occupying premium niches. Capacity expansion in aluminum canning lines and strategic partnerships with cold-chain logistics providers represent the dominant competitive moves.
Within the heritage-provenance tier, Diageo plc and Bacardi Limited exemplify integrated supply network advantages. Suntory Holdings Limited occupies a position as the Japanese whisky-infused variant specialist. These three entities represent contrasting geographic anchoring strategies—British-Caribbean rum heritage versus Japanese spirit authenticity—each commanding distinct shelf position premiums in their respective target corridors.
| Leading Market Players |
|---|
| Diageo plc |
| Anheuser-Busch InBev SA/NV |
| Pernod Ricard SA |
| Bacardi Limited |
| Constellation Brands, Inc. |
| Suntory Holdings Limited |
| Brown-Forman Corporation |
| Campari Group |
| Asahi Group Holdings, Ltd. |
| Others |
Value Network & Pricing Analysis
Premium-versus-commodity ABV tier divergence separates craft cocktail formulations commanding artisanal premiums from mass-market ready-to-drink variants competing on logistics efficiency, with this bifurcation manifesting in divergent aluminum sourcing strategies and cold-chain investment profiles across United States and European production corridors.
Pricing Analysis
Service-bundling separates premium craft cocktails with batch-provenance storytelling and direct-to-consumer education from unbundled ready-to-drink formats competing purely on shelf-turn velocity. Three-tier pricing structure across premium, standard, and economy levels reflects ABV concentration, heritage spirit authenticity, and extended producer responsibility compliance costs. Pricing pressure stems from TTB label approval delays compressing product launch windows and elevating working capital requirements. Ready-to-drink supermarket buyers exhibit highest price sensitivity, while specialty retail premium shoppers accept significant markups for Japanese whisky-infused and Caribbean rum heritage formulations.
Supply Chain Analysis
Spirit base procurement rests on Caribbean rum heritage producers, Japanese whisky distillers, and North American craft botanical suppliers as the tripartite input foundation. Aluminum can sheet, flavor emulsion stabilizers, and internal coating chemicals constitute critical component dependencies. Single-source vulnerability concentrates in Caribbean climate-exposed rum supply chains threatened by shipping bottlenecks and weather volatility. Distribution runs through supermarket and convenience channel consolidation in United States coastal corridors, specialty retail curation in German and Japanese urban zones, and accelerating direct-to-consumer platform development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over emulsion chemistry talent and aluminum canning capacity determines margin defense against TTB-regulated launch friction and EU packaging compliance escalation.
For Market Incumbents: Acquire emulsion chemistry formulation laboratories and captive aluminum canning lines to secure batch consistency and reduce coating specification compliance costs. Defend against craft cocktail entrants by locking specialty retail shelf contracts in New York and Los Angeles corridors before rotational flavor programs achieve TTB approval. Prioritize ambient-stable formulation R&D to reduce EU F-Gas Regulation refrigeration dependency.
For New Entrants and Emerging Players: High-pressure processing technology adoption offers unclaimed "never heated" positioning in mid-sized United States craft bottler segments underserved by conglomerate equipment allocation. Target online retail direct-to-consumer channels where age-gating infrastructure investments create barriers against supermarket-dependent incumbents. Leverage Japanese whisky-infused variant whitespace in North American specialty retail through provenance-forward storytelling.
For Investors and Strategic Acquirers: Exit pathways concentrate in conglomerate portfolio rationalization and craft brand rollup consolidation across the medium-term horizon. Acquisition target archetypes include mid-tier bottlers with TTB compliance track records and ambient-stable formulation capabilities. Watch aluminum recycling infrastructure maturation rates and deposit-return scheme legislative momentum as inflection indicators for packaging format cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Canning Capacity Expansion | Captive canning lines reduce EU REACH migration testing costs and internal coating specification compliance burden. |
| Direct-to-Consumer Channel Development | Owned digital platforms bypass supermarket slotting fee structures and enable batch-specific price premiums. |
| Ambient-Stable Formulation Investment | Shelf-stable emulsion chemistry reduces EU F-Gas Regulation refrigeration dependency and cold-chain logistics costs. |
| Heritage Spirit Base Vertical Integration | Captive Caribbean rum and Japanese whisky sourcing secures tropical flavor authenticity against climate supply risk. |
| High-Pressure Processing Technology Adoption | "Never heated" positioning claims differentiate craft bottlers in specialty retail channels against thermal-pasteurized competitors. |
Research Methodology
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with bottling plant managers, specialty retail category buyers, flavor emulsion chemists, and cold-chain logistics providers. Bottom-up volume modeling across ready-to-drink and craft cocktail segments combined with top-down value reconciliation from supermarket scanner data and direct-to-consumer platform metrics.
Historical ABV tier pricing trendlines and aluminum packaging cost trajectories informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, packaging format, and regional regulatory cluster. CAGRs derived from curve-fitting approaches applied to volume throughput data, incorporating TTB approval timeline friction and EU extended producer responsibility mandate implementation schedules as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Caribbean rum supply disruption and EU F-Gas Regulation acceleration scenarios. Forecasts reflect documented assumptions regarding aluminum recycling infrastructure maturation and deposit-return scheme legislative adoption. A small set of named triggers—TTB label approval backlog expansion, REACH flavor additive threshold revisions, and climate-induced Caribbean shipping bottlenecks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market