
 Rum Market | 2026-2036
Rum Market Size, Share, and Industry Trends Forecast 2026-2036
Rum Market Intelligence
Buyer concentration across on-premise channels is rebalancing as independent craft bars fragment share from legacy nightclub chains. Bacardi Limited leverages its integrated Caribbean distillation network to sustain bulk supply advantages. Diageo plc anchors its portfolio through Captain Morgan's spiced rum dominance in North American retail. Pernod Ricard competes via premium aged expressions that command higher pour rates in European cocktail bars.
Rum is a sugarcane-derived spirit distilled from molasses or fresh cane juice, typically aged in charred oak barrels at 40–75% ABV, serving as a base for cocktails and premium sipping categories. Dark rum and spiced rum occupy the deepest margin pools, where barrel-aging duration and proprietary spice blends create pricing power that light rum cannot match. Duty-free shops represent a high-velocity channel for ultra-premium aged expressions, while online retail captures trial-sized and limited-release allocations.
EU REACH frameworks govern flavor additive compliance, while EFSA labeling mandates reshape ingredient transparency across export batches. The US TTB enforces strict age-statement verification that limits geographic sourcing claims. Stakeholders must monitor evolving additive restrictions and on-premise licensing shifts that could redirect volume between retail and hospitality channels.
Market Dynamics
Premium cocktail culture in craft bars is fragmenting on-premise channels, while EU EFSA labeling mandates force additive transparency reforms that reshape export compliance costs for Caribbean distillers.
Growth Catalysts
- EFSA Additive Disclosure Mandates:European spirits labeling regulations under EFSA are tightening additive disclosure requirements, forcing reformulation investments that differentiate clean-label producers in EU duty-free and retail channels.
- Barrel-Aging Infrastructure:Caribbean basin heritage distillers leverage tropical aging warehouses to accelerate maturation velocity, compressing time-to-market for premium sipping expressions versus temperate-climate competitors.
- Craft Cocktail Bars:Independent craft bars fragment share from legacy nightclub chains, creating pull-through for ultra-premium aged rums at higher pour rates than mass-market venues.
Market Restraints
- Molasses Input Volatility:Sugarcane harvest fluctuations in Brazil and India transmit price volatility through molasses supply contracts, squeezing margin predictability for bulk rum producers.
- Caribbean Basin Concentration:Aged rum heritage and bulk distillation capacity concentrate in the Caribbean basin, creating geographic supply risk from hurricane disruption and climate stress on cane yields.
- US TTB Age Verification:The US TTB enforces strict age-statement verification that limits geographic sourcing claims, constraining marketing narratives for blended expressions with multi-origin components.
Strategic Opportunities
- Online Retail Allocation:E-commerce channels capture trial-sized and limited-release allocations, enabling direct-to-consumer relationships that bypass traditional three-tier distribution markups.
- EU Green Deal Alignment:Carbon-neutral distillation investments align with EU Green Deal procurement preferences, opening preferential shelf placement in European retail and hospitality accounts.
- Spiced Rum Innovation:Proprietary spice blend development creates pricing power in the spiced rum segment, where flavor differentiation commands retail premiums that light rum cannot match.
Industry Challenges
- Master Blender Talent Scarcity:Expertise in solera aging and multi-vat blending concentrates among retiring Caribbean specialists, constraining capacity expansion for premium aged expressions.
- Oak Barrel Capex Intensity:Charred American oak and ex-bourbon barrel procurement requires substantial working capital, with extended aging cycles locking up inventory for 5-25 years before revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rum Market |
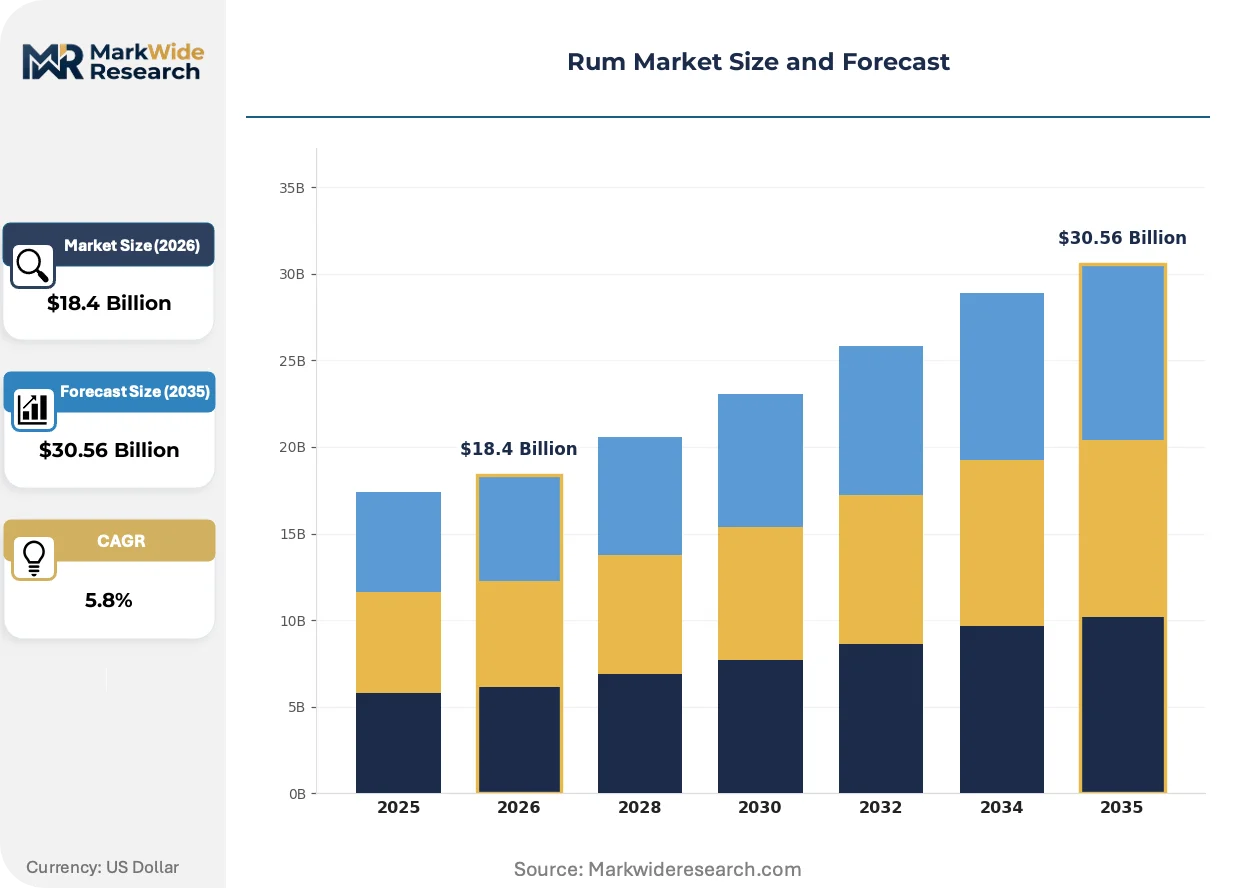
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Rum, Dark Rum, Spiced Rum, Overproof Rum End User: Households, Bars, Restaurants, Nightclubs Packaging Type: Glass Bottles, PET Bottles, Tetra Packs, Kegs Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Duty-Free Shops |
| Companies Covered | Captain Morgan, Tanduay Distillers Inc., Bacardi Limited, Flor de Caña, Demerara Distillers Limited, Diageo plc, Mount Gay Distilleries, Ron Diplomático, Pernod Ricard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rum Market Strategic Shifts & Innovations
Active cask-finishing experimentation and additive transparency requirements are compressing traditional aging orthodoxies while opening new flavor territories for premium positioning.
Precision cask-finishing programs using ex-sherry, ex-port, and ex-wine barrels is rewriting the maturation economics for mid-tier distillers. Caribbean and Central American producers are adopting 12-18 month secondary finishes to simulate extended aging depth. This technique compresses the capital intensity required for premium market entry.
EU REACH frameworks govern flavor additive compliance across export batches, forcing reformulation of caramel color and sugar dosing practices. EFSA labeling mandates reshape ingredient transparency requirements. European cocktail bars and retail buyers are responding by sourcing additive-free expressions that command pour premiums.
Buyer concentration across on-premise channels is fragmenting as independent craft bars displace legacy nightclub chains. Volume is redirecting toward venues that prioritize ultra-premium aged expressions over high-volume well-pour contracts. This shift is most visible in London, New York, and Singapore cocktail bar clusters.
Rum Market Segmentation
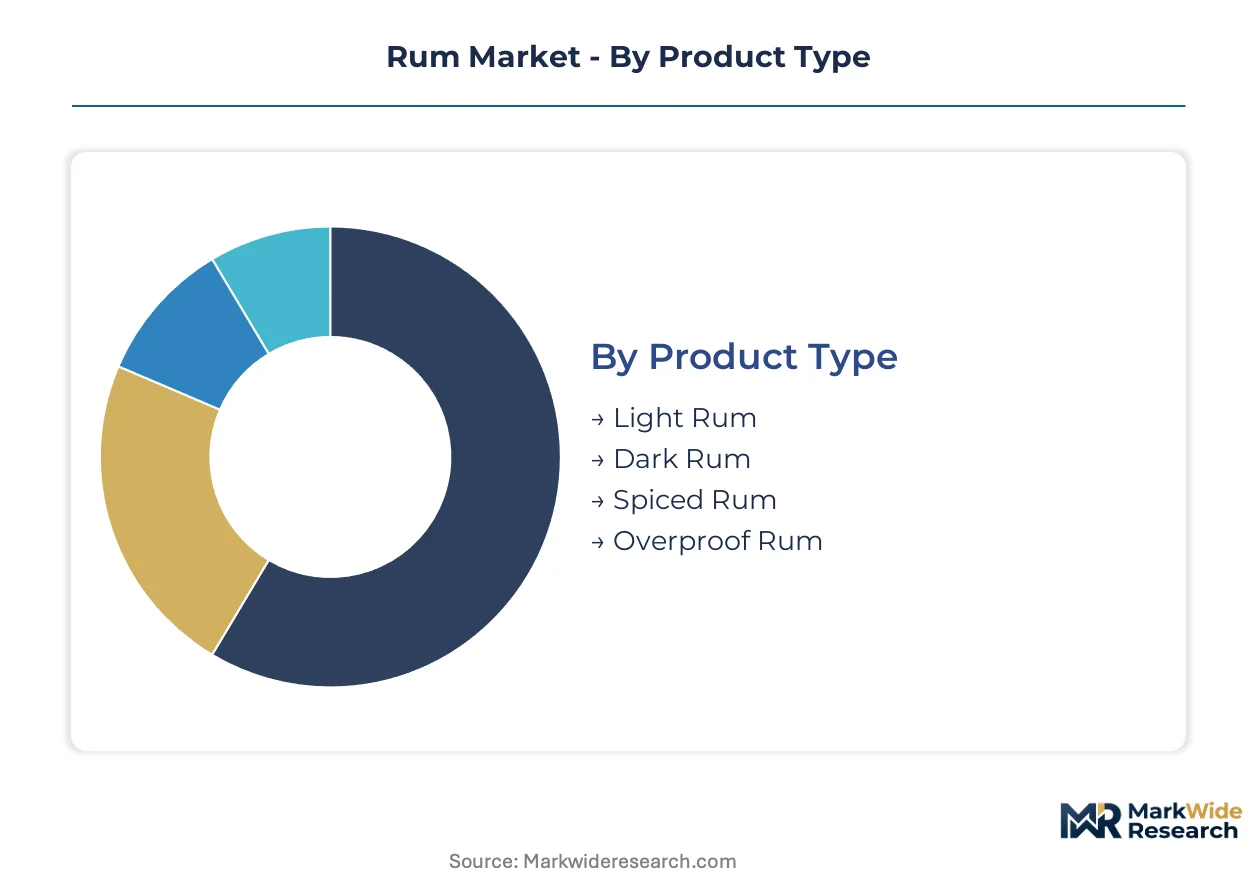
Rum segmentation reveals how barrel-aging protocols, ABV thresholds, and packaging formats partition margin capture across consumption occasions. Distillers align product architecture with channel-specific velocity requirements and on-premise pour economics.
Product Type:
Distillation method and maturation duration define the technical axis, separating unaged expressions from barrel-developed complexity tiers.
- Light Rum:Column-distilled spirits aged minimally or not at all, typically bottled at 40% ABV with neutral flavor profiles suited for high-volume cocktail bases. Demand concentrates in US and Brazilian retail channels where price-sensitive mixing applications dominate volume.
- Dark Rum:Pot or column-distilled spirits aged 3-12 years in charred oak, developing caramel and vanilla compounds through tropical warehouse maturation. Caribbean heritage producers command export premiums in European cocktail bars where aged sipping expressions drive higher pour rates.
- Spiced Rum:Base rum infused with proprietary spice blends and often dosed with caramel color, creating flavor differentiation that commands retail shelf price premiums.
- Overproof Rum:High-ABV expressions bottled at 57-75% alcohol content, serving niche tiki cocktail applications and flambé cooking segments.
Mature deployment sits with Dark Rum. Newer deployment is concentrated in Spiced Rum.
End User:
Consumption venue determines packaging format, pricing architecture, and brand positioning investments required for channel access.
- Households:At-home consumption via retail purchase, where 750ml glass bottle formats and spiced rum flavor accessibility drive repeat purchase velocity.
- Bars:Independent craft cocktail venues where premium aged expressions and overproof blending stocks support higher-margin pour rates than mass-market accounts.
- Restaurants:Food-service licensing with dessert flambé and rum-based sauce applications, favoring mid-tier dark rum in 1-liter formats.
- Nightclubs:High-volume well-pour contracts where light rum dominates mixed drink throughput, though share is fragmenting toward craft bar alternatives.
Volume leadership sits with Nightclubs. Margin expansion concentrates in Bars.
Packaging Type:
Material science and logistics economics shape how producers align liquid investment with channel velocity and breakage risk profiles.
- Glass Bottles:Premium positioning standard for aged expressions, where bottle weight and closure quality signal quality tier in retail and on-premise environments.
- PET Bottles:Lightweight polymer formats reducing freight costs and breakage risk in emerging market distribution where infrastructure fragility elevates supply chain risk.
- Tetra Packs:Aseptic carton technology capturing trial-sized and travel retail allocations with reduced environmental footprint versus glass alternatives.
- Kegs:Stainless steel returnable formats serving high-volume on-premise accounts with draft rum cocktail programs, compressing per-ounce serving costs.
Investment concentration sits with Glass Bottles. Format innovation is accelerating in Tetra Packs.
Distribution Channel:
Route-to-market selection governs margin retention, consumer data access, and regulatory compliance burden across geographies.
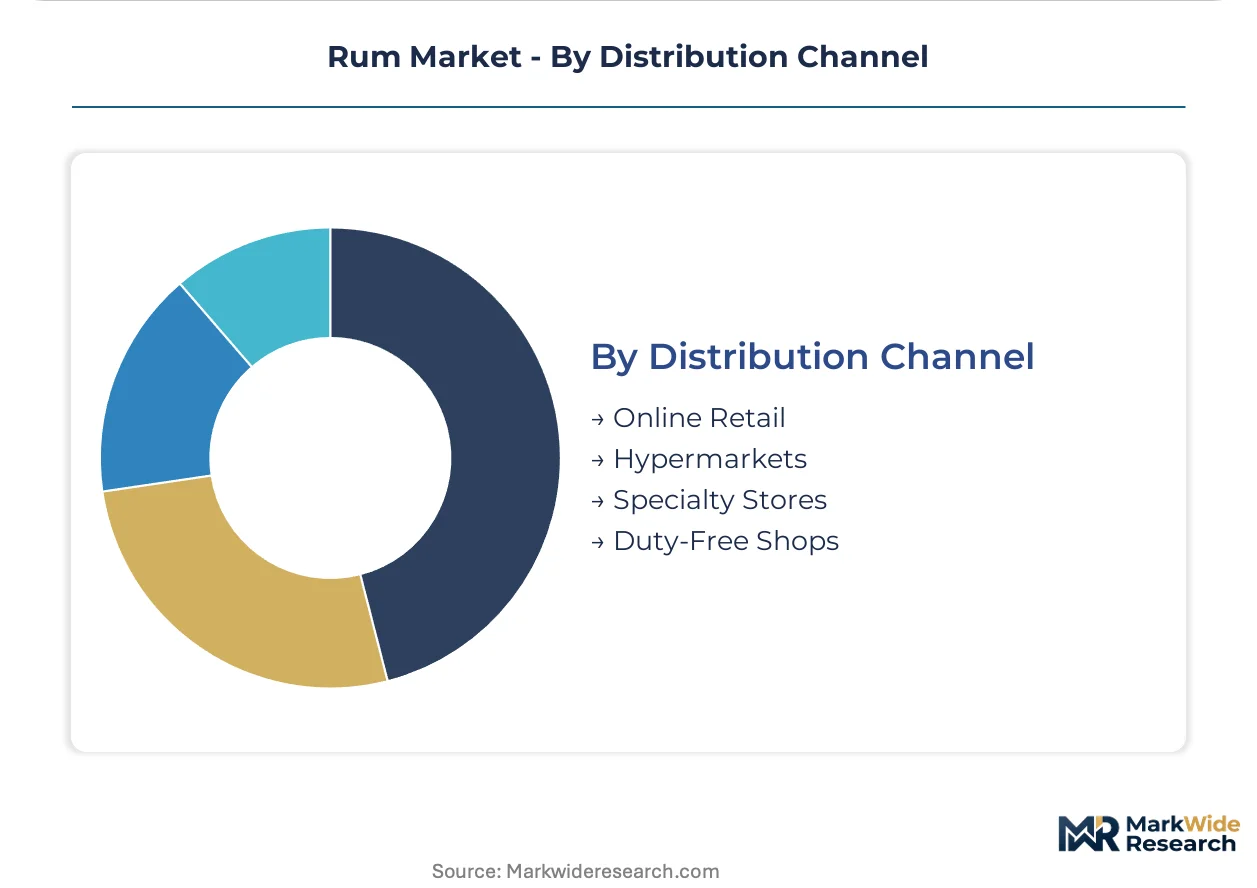
- Online Retail:Direct-to-consumer platforms capturing limited-release allocations and subscription-based aged rum clubs, bypassing three-tier distribution markups in permissive jurisdictions.
- Hypermarkets:Mass retail chains in Brazil and Mexico where promotional pricing and spiced rum brand blocking drive household penetration at scale.
- Specialty Stores:Independent spirits merchants in London, Paris, and New York where curated aged rum selections and staff education support premium price realization.
- Duty-Free Shops:Travel retail channels in Caribbean and Middle Eastern hubs where ultra-premium aged expressions achieve velocity through tourism-driven purchase occasions.
Margin retention sits with Online Retail. Volume scale concentrates in Hypermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugarcane plantations in Brazil's São Paulo state anchor the Western Hemisphere's molasses supply chain, feeding distilleries across the Caribbean basin and North American blending facilities.
United States
Captain Morgan and Bacardi command retail shelf space through spiced rum dominance and Puerto Rican distillation integration. TTB age-statement verification constrains multi-origin blending claims. Miami and New York cocktail bar clusters pull ultra-premium aged expressions at elevated pour rates.
United Kingdom
London's independent craft bars fragment on-premise share from legacy nightclub chains, creating demand for additive-free sipping rums. EFSA labeling mandates under REACH frameworks reshape import compliance costs. Edinburgh and Glasgow specialty merchants curate Caribbean aged selections for educated consumers.
Germany
Berlin's bar scene drives premium rum cocktail culture with emphasis on transparent ingredient sourcing. EU Green Deal procurement preferences favor carbon-neutral distillation investments. Hamburg's port logistics handle bulk Caribbean imports for Central European redistribution.
France
Martiniquan and Guadeloupean agricole rums leverage AOC protected designation status in Parisian retail. ANSM and DGCCRF enforcement of additive disclosure creates competitive differentiation for clean-label producers. Lyon and Bordeaux cocktail venues emphasize terroir-specific cane juice expressions.
Philippines
Tanduay Distillers anchors domestic volume leadership through molasses-based production scaled across Luzon. BIS-equivalent national standards govern alcohol content labeling for export batches. Manila's nightlife districts concentrate mass-market consumption while Cebu duty-free channels capture tourist-driven premium purchases.
Rum Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cask-finishing specialization and direct-to-consumer allocation models. The vendor base stratifies between integrated Caribbean distillers with captive sugarcane supply and contract-dependent blenders sourcing bulk spirits. Three archetypes dominate: heritage distillers with solera aging expertise, multinational spirits conglomerates with portfolio breadth, and craft specialists exploiting secondary cask finishes. Competitive moves center on barrel inventory accumulation and e-commerce channel bypass of traditional three-tier distribution.
Among Caribbean-heritage distillers, Bacardi Limited and Mount Gay Distilleries exemplify integrated production models with tropical aging infrastructure. Diageo plc occupies a position as a multinational portfolio operator leveraging Captain Morgan's spiced rum recognition. These three represent distinct competitive vectors: vertical integration, brand equity scale, and flavor innovation specialization respectively.
| Leading Market Players |
|---|
| Captain Morgan |
| Tanduay Distillers Inc. |
| Bacardi Limited |
| Flor de Caña |
| Demerara Distillers Limited |
| Diageo plc |
| Mount Gay Distilleries |
| Ron Diplomático |
| Pernod Ricard |
| Others |
Cost & Logistics Intelligence
Family-owned Caribbean distillers with multi-generational solera aging programs anchor supply discipline through captive barrel inventories, translating extended maturation cycles into premium pricing power that contract-dependent blenders cannot replicate. Their ownership structure insulates pricing from quarterly earnings pressure, allowing sustained investment in 12-25 year aging programs that define category tier boundaries.
Pricing Analysis
Volume leadership concentrates in mass-market light rum sold through Brazilian and US hypermarkets at commodity-adjacent price points, while margin capture concentrates in ultra-premium aged expressions commanding elevated pour rates at London, New York, and Singapore cocktail bars. Three-tier pricing structure across premium, standard, and economy levels reflects barrel-aging duration, with 8-15 year expressions capturing the steepest price escalation. Pricing pressure stems from molasses input volatility transmitted through Brazilian and Indian sugarcane harvest fluctuations, squeezing predictability for bulk producers. Household retail buyers exhibit highest price sensitivity, while independent craft bar procurement teams prioritize additive-free provenance over per-bottle cost.
Supply Chain Analysis
EU REACH certification and EFSA additive disclosure compliance act as qualification gates that filter export access for Caribbean distillers unable to reformulate caramel color and sugar dosing practices. Geographic supply concentrates in Puerto Rico, Cuba, and Barbados, with Brazilian São Paulo state molasses feeding distillation across the Caribbean basin. Raw material dependencies center on charred American oak and ex-bourbon barrels, sugarcane molasses, and proprietary yeast cultures. Supply chain risk manifests in hurricane disruption exposure to tropical aging warehouses concentrated in low-lying coastal zones. Distribution runs through three-tier wholesale networks in North America, with duty-free channels and direct-to-consumer e-commerce capturing growing share in permissive jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rum market dynamics are supply-constrained by finite master blender expertise and extended barrel-aging cycles, with oak inventory accumulation acting as the primary capacity bottleneck supporting premium pricing discipline.
For Market Incumbents: Lock in solera aging capacity through long-term barrel supply contracts with American cooperages before oak price escalation accelerates. Deepen backward integration into cane cultivation or molasses offtake agreements to insulate margin from Brazilian harvest volatility. Counter emerging cask-finishing specialists by accelerating secondary maturation programs using ex-sherry and ex-port barrels. For New Entrants and Emerging Players: Begin with online retail allocation of limited-release expressions to bypass three-tier distribution markups and establish direct consumer relationships. Target EU specialty merchants in Berlin, Paris, and Edinburgh where clean-label additive-free positioning commands shelf price premiums unavailable in mass retail. Pursue carbon-neutral distillation certification to align with EU Green Deal procurement preferences. For Investors and Strategic Acquirers: Distressed-cycle entries favor Caribbean heritage distillers with captive aging warehouses and AOC-protected cane juice expressions in Martinique and Guadeloupe. Long-term viability rests on barrel inventory depth and master blender succession planning rather than brand marketing spend. Watch for TTB age-statement enforcement tightening as signal of regulatory premiumization that favors compliant producers with verified provenance documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Barrel Inventory Accumulation | Charred American oak procurement locks in maturation capacity before cooperage supply tightens. |
| Direct-to-Consumer E-Commerce Launch | Online retail bypasses three-tier markups while capturing consumer data for allocation optimization. |
| Carbon-Neutral Distillation Certification | EU Green Deal alignment secures preferential placement in Berlin and Hamburg hospitality accounts. |
| Secondary Cask-Finishing Program | Ex-sherry and ex-port barrel programs compress time-to-premium for mid-tier distillers. |
| Additive-Free Reformulation | EFSA compliance investment differentiates clean-label producers in London cocktail bar procurement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among master blenders, Caribbean distillery operations directors, EU specialty spirits merchants, and US three-tier distribution executives. Bottom-up volume modeling triangulated against top-down value estimates derived from EFSA enforcement patterns and TTB age-statement verification records. Secondary sources included EU REACH compliance databases, Caribbean export authority documentation, and US TTB COLA registry analysis.
Data-stream reconciliation across production volume, export shipment, and retail scan data informed the analytical framework applied across the projection horizon. Segmentation dimensions modeled encompassed distillation method, maturation duration, ABV tier, packaging format, and channel route-to-market. CAGRs were derived from weighted average growth assumptions calibrated to barrel-aging cycle economics and on-premise channel fragmentation patterns. Forecast inputs incorporated molasses price volatility indices and craft bar venue expansion trajectories in identified metropolitan clusters.
Hurricane frequency intensification, EFSA additive restriction tightening, and US TTB geographic sourcing claim enforcement are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding sustained Caribbean basin production capacity and continued EU duty-free channel velocity. A model refresh is warranted upon material change in tropical aging warehouse damage incidence or master blender talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Home Brew Boiler Market