
 Cannabis-Based Alcoholic Beverages Market | 2026-2036
Cannabis-Based Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis-Based Alcoholic Beverages Market Intelligence
Beverage formulation chemists with dual expertise in alcohol fermentation and cannabinoid emulsification is reorganizing production capacity across North America. Canopy Growth Corporation leverages its licensed facility network to sustain THC beverage output at scale. Tilray Brands anchors its position through vertical integration from cultivation to bottling. Truss Beverage Co. competes via exclusive distribution partnerships with established alcohol retailers.
Cannabis-based alcoholic beverages combine ethanol with hemp-derived cannabinoids—typically THC, CBD, or terpene blends—using nanoemulsion technology to achieve water-soluble stability and predictable onset timing. These products serve recreational consumers seeking controlled-dose alternatives to smoking or conventional drinking. Ready-to-drink formats dominate current revenue pools due to convenience and portion standardization, while terpene-infused spirits command premium positioning through flavor complexity. THC-forward wine and beer segments occupy niche positions where regulatory allowances permit cross-category experimentation.
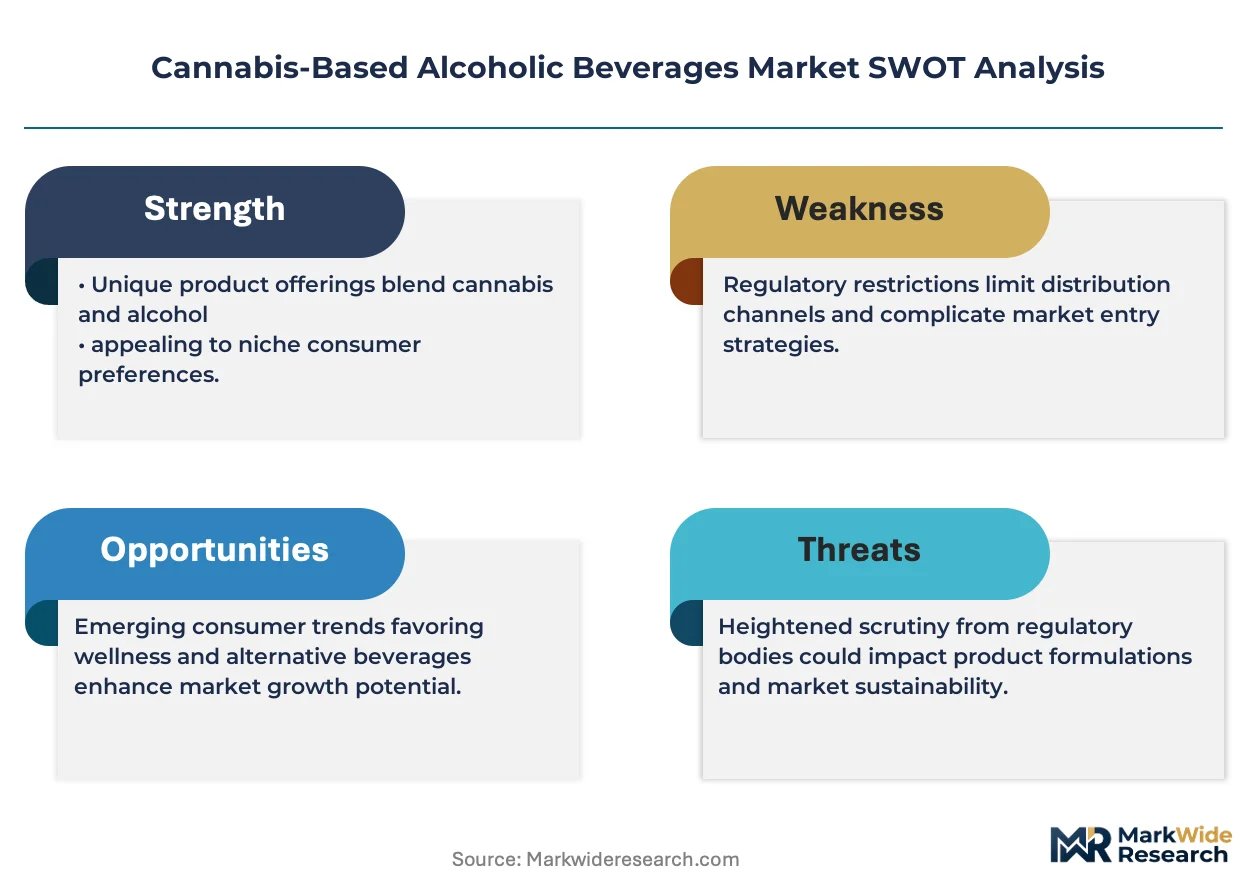
Health Canada and the US Alcohol and Tobacco Tax and Trade Bureau impose divergent labeling, potency caps, and channel restrictions that fragment market access. State-level cannabis regulators in California and Colorado layer additional testing requirements atop federal alcohol standards. The FDA maintains ambiguous positioning on CBD-alcohol combinations, creating compliance uncertainty for interstate commerce. Stakeholders must monitor pending federal rescheduling decisions and state-by-state retail integration policies to anticipate distribution expansion timelines.
Market Dynamics
Nanoemulsion technology is compressing formulation timelines and enabling shelf-stable THC-alcohol combinations that previously separated within weeks. This single technical breakthrough is restructuring manufacturing economics and opening retail channels previously closed to unstable emulsions.
Growth Catalysts
- Health Canada Cannabis Beverage Framework:Federal licensing for co-manufacturing facilities allows alcohol producers to add THC lines without separate cannabis cultivation permits. This policy removes capital barriers that previously forced brands to build standalone facilities.
- Millennial nightlife consumption:Social venues in Los Angeles, Toronto, and Denver report elevated trial rates for low-dose THC cocktails among consumers aged 25-40 seeking alternatives to high-ABV drinking.
- Terpenoid extraction precision:Steam-distilled cannabis-derived flavor compounds now replicate strain-specific profiles without botanical inconsistency, giving formulators predictable sensory outcomes batch-to-batch.
Market Restraints
- Input cost volatility:Hemp-derived THC isolate prices fluctuate with seasonal biomass yields and extraction capacity constraints in Colorado and Oregon cultivation zones.
- FDA interstate commerce ambiguity:The agency's refusal to affirm GRAS status for CBD-alcohol combinations blocks national distribution networks and forces state-by-state compliance builds.
- Substitution threat from non-alcoholic cannabis beverages:Zero-proof THC seltzers avoid dual regulatory burdens and appeal to health-positioned consumers, compressing addressable demand for ethanol-cannabinoid combinations.
Strategic Opportunities
- Germany's cannabis legalization pathway:The country's phased commercial framework creates first-mover advantage for beverage brands establishing compliant supply chains before full retail liberalization.
- Direct-to-consumer subscription channels:California and Colorado permit licensed delivery platforms to bypass traditional three-tier alcohol distribution, capturing margin otherwise lost to wholesale intermediaries.
- Blockchain-integrated provenance tracking:Immutable batch records from cultivation to point-of-sale address regulatory audit requirements while building consumer trust through transparent potency verification.
Industry Challenges
- Dual-competency formulation talent:Chemists trained in both ethanol fermentation science and lipophilic cannabinoid emulsification remain scarce, extending R&D timelines and inflating compensation premiums.
- Co-packing facility certification delays:Alcohol bottlers seeking cannabis amendments face 12-18 month queue times for Health Canada or state-equivalent inspections, freezing capacity expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis-Based Alcoholic Beverages Market |
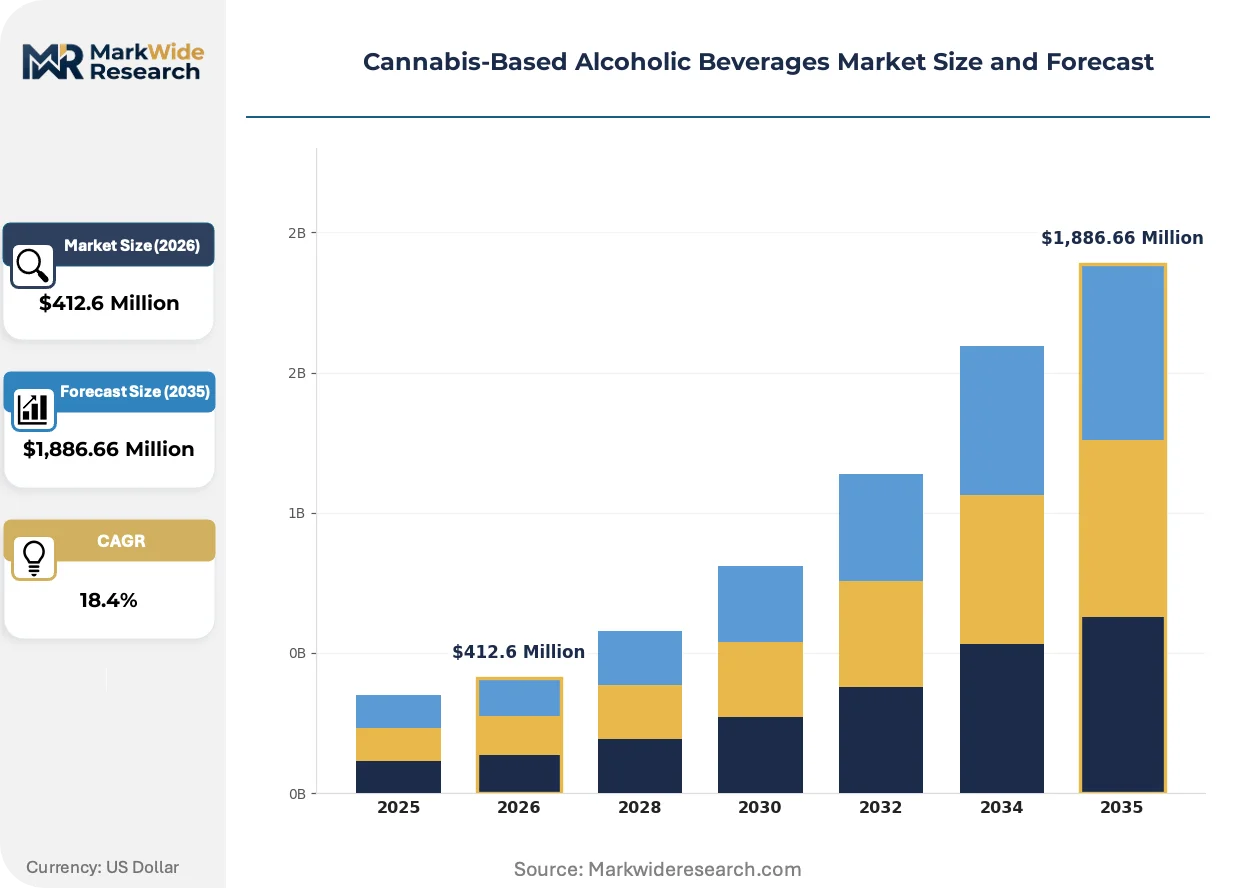
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,886.66 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Ready-to-Drink Ingredients: Hemp Extract, THC, CBD, Terpenes Packaging Type: Bottles, Cans, Kegs, Pouches Distribution Channel: Online, Liquor Stores, Dispensaries, Supermarkets |
| Companies Covered | Canopy Growth Corporation, Tilray Brands, Inc., Truss Beverage Co., Keef Brands, Lagunitas Brewing Co., Rebel Coast, BevCanna Enterprises, Cann Social Tonics, Cronos Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis-Based Alcoholic Beverages Market Strategic Shifts & Innovations
Formulation science and regulatory navigation are converging to reshape competitive positioning. Three developments are compressing product development cycles and redefining what constitutes a viable market entry.
Water-compatible nanoemulsion systems is supplanting traditional oil-based THC infusions in premium ready-to-drink production. California craft distilleries and Ontario licensed producers are adopting lipid-particle sizing below 100 nanometers to achieve optical clarity and rapid onset timing. This technical shift is collapsing the sensory gap between cannabis beverages and conventional cocktails, forcing legacy alcohol brands to accelerate internal formulation programs or risk channel displacement.
REACH-compliant flavor ingredient disclosure is extending to cannabis-derived terpenes sold into European markets. ECHA substance registration requirements now cover novel botanical extracts at thresholds that capture imported terpenoid formulations. German and Dutch regulators are enforcing documentation standards that exceed North American norms, compelling exporters to rebuild supply chain transparency or abandon continental expansion.
On-premise consumption venues are fragmenting beverage procurement across multiple specialized distributors. Los Angeles cocktail bars and Toronto cannabis lounges now source THC spirits through licensed cannabis wholesalers while maintaining separate alcohol vendor relationships. This channel complexity is elevating logistics coordination costs and favoring suppliers with dual-license capabilities or integrated delivery platforms.
Cannabis-Based Alcoholic Beverages Market Segmentation
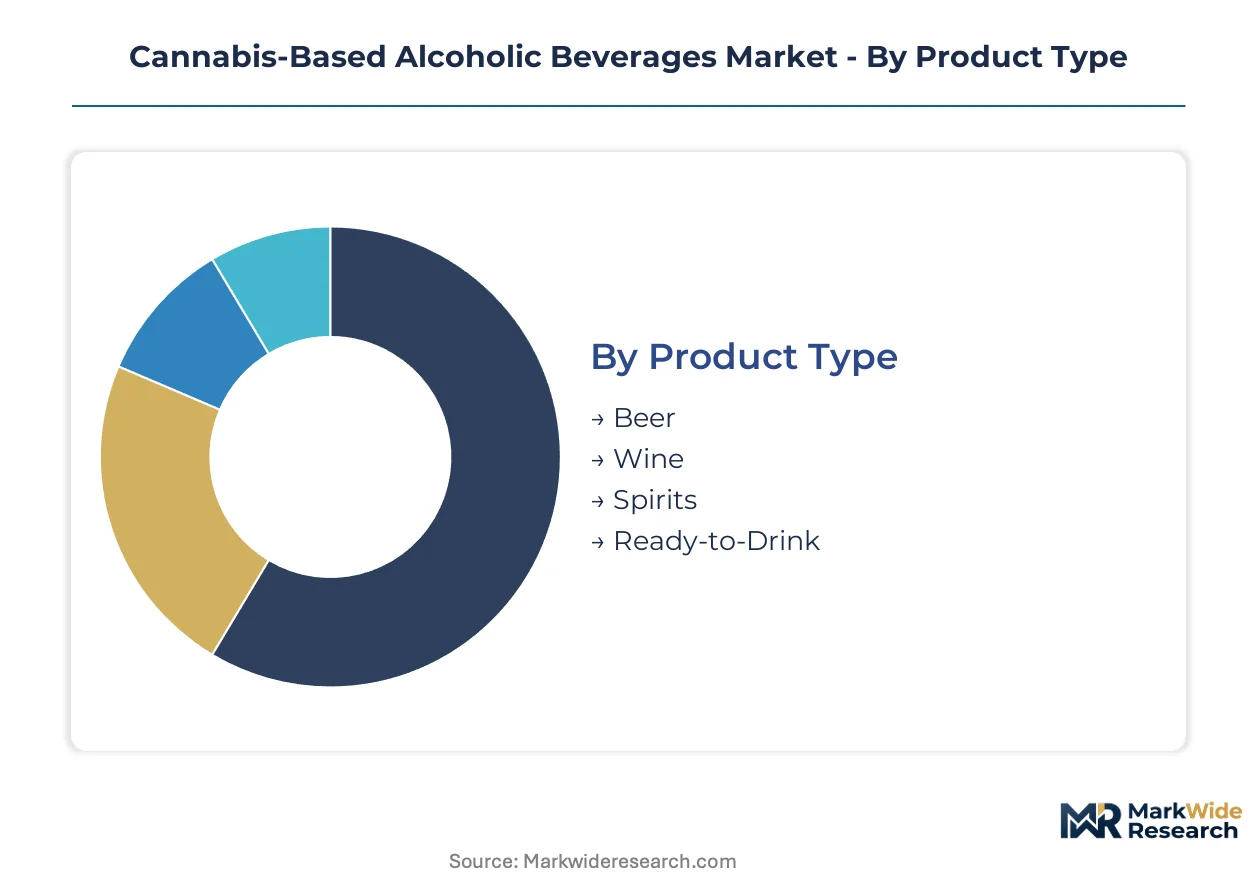
Segmentation in cannabis-based alcoholic beverages determines regulatory pathway, manufacturing investment, and channel access. Each dimension carries distinct compliance burdens and margin profiles that shape competitive entry strategies.
Product Type:
FDA and TTB classification rules diverge sharply across beverage categories, dictating labeling requirements and permissible potency thresholds.
- Ready-to-Drink:Pre-mixed cocktails and seltzers leverage nanoemulsion stability for standardized dosing. California and Colorado dispensaries report concentrated demand among 25-40 year-old consumers seeking portion-controlled alternatives to traditional cocktails.
- Spirits:THC-infused vodkas, gins, and whiskeys command premium positioning through terpene complexity and craft distillation credentials. Health Canada permits higher potency ceilings for spirits versus beer, attracting formulation investment to Ontario and British Columbia facilities.
- Beer:Cannabis-infused lagers and ales face compressed margins due to volume-based taxation and per-unit potency caps in most jurisdictions.
- Wine:THC-forward wines occupy niche positioning where state regulations explicitly permit cross-category experimentation; limited distribution outside experimental markets.
Ready-to-Drink handles the majority of throughput; Spirits is gaining share fastest as premium positioning commands superior unit economics.
Ingredients:
Input selection determines federal oversight intensity and interstate commerce feasibility.
- THC:Psychoactive tetrahydrocannabinol requires state cannabis licensing and triggers strict potency testing. Demand concentrates in California's adult-use market where social consumption venues drive trial.
- CBD:Non-intoxicating cannabidiol faces FDA GRAS status ambiguity that blocks national alcohol distribution networks.
- Terpenes:Steam-distilled cannabis-derived flavor compounds enable strain-specific replication without botanical inconsistency.
- Hemp Extract:Broad-spectrum hemp inputs navigate the 2018 Farm Bill framework with fewer restrictions than marijuana-derived alternatives.
THC dominates current formulation volumes; Terpenes is climbing the fastest as precision extraction technology matures.
Packaging Type:
Container selection reflects channel strategy and consumption occasion targeting.
- Cans:Aluminum formats suit on-premise consumption and outdoor venues where glass restrictions apply. Colorado and California breweries prioritize canning lines for THC beverage production.
- Bottles:Glass packaging commands premium positioning in spirits and wine categories where traditional aesthetics influence purchase decisions.
- Kegs:Draft systems serve licensed cannabis lounges in Toronto and Los Angeles with controlled-pour dosing infrastructure.
- Pouches:Flexible packaging targets festival and event consumption with lightweight logistics and rapid chill properties.
Cans absorb the largest production share; Kegs is expanding most quickly as on-premise cannabis venues proliferate.
Distribution Channel:
Channel access fragments across alcohol and cannabis regulatory frameworks with limited overlap.
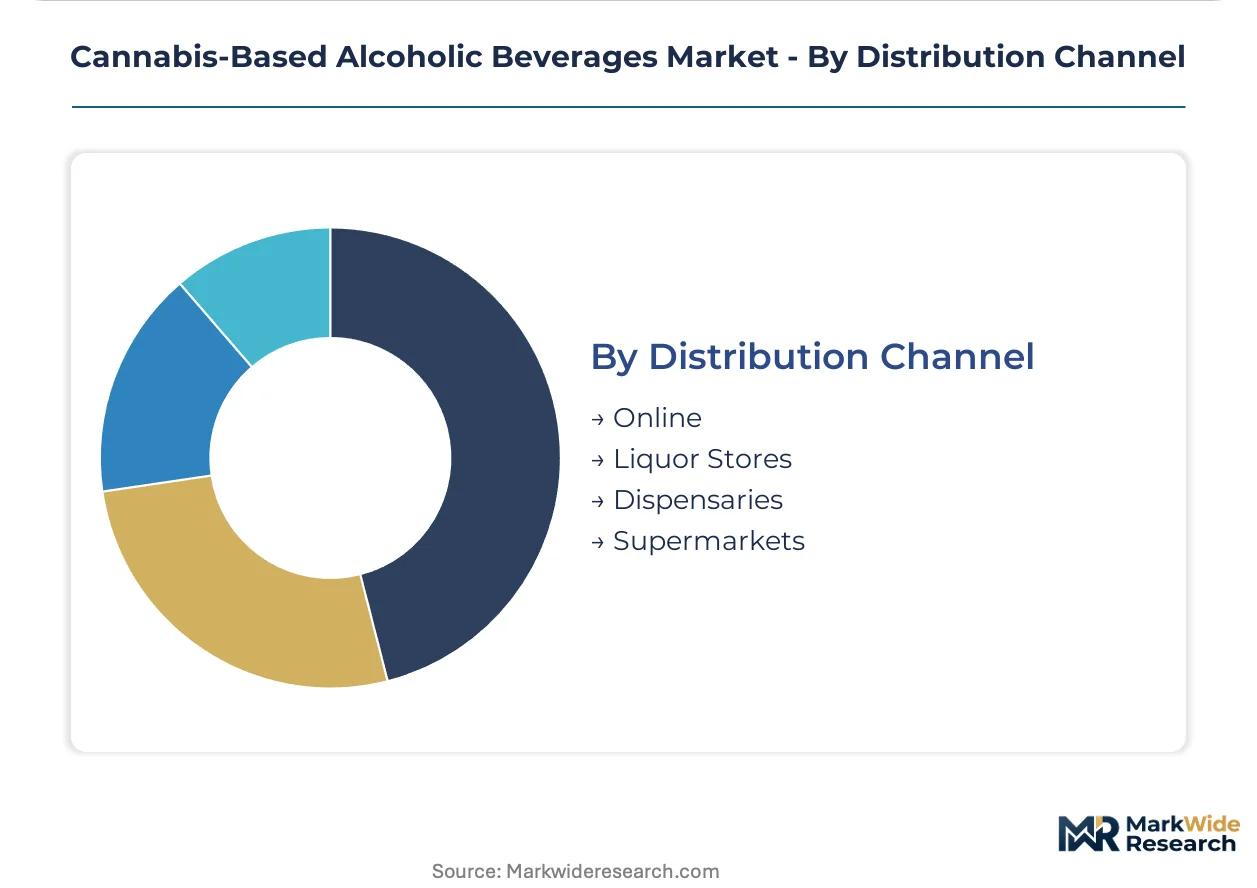
- Dispensaries:Licensed cannabis retailers in California, Colorado, and Ontario maintain exclusive rights to THC-forward products above regulatory thresholds.
- Liquor Stores:Traditional alcohol retailers in select jurisdictions now carry hemp-derived CBD beverages where dual licensing permits.
- Online:Direct-to-consumer platforms in California and Colorado bypass three-tier distribution, capturing margin otherwise lost to wholesale intermediaries.
- Supermarkets:Grocery channel access remains restricted to non-THC hemp beverages in jurisdictions with progressive CBD frameworks.
Dispensaries control the dominant volume pathway; Online is showing the steepest expansion trajectory as delivery platforms secure operational licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada anchors the dominant geography through its federal licensing framework for co-manufacturing facilities. This policy architecture enables alcohol producers to add THC lines without separate cannabis cultivation permits. Jurisdictional fragmentation across federal and state-level regulators defines market access patterns.
United States
California's social consumption venues in Los Angeles and San Francisco drive elevated trial rates for low-dose THC cocktails among millennial demographics. The Alcohol and Tobacco Tax and Trade Bureau imposes potency caps and labeling requirements that diverge from FDA positioning on CBD-alcohol combinations. Colorado's Denver-Boulder corridor concentrates formulation R&D as state regulators layer additional testing requirements atop federal alcohol standards.
Canada
Ontario's licensed producers leverage Health Canada's co-manufacturing provisions to sustain beverage output at scale without standalone facility investments. Federal cannabis regulations permit higher potency ceilings for spirits versus beer, attracting formulation investment to Toronto and British Columbia production zones. Vancouver-area facilities specialize in nanoemulsion technology for shelf-stable THC-alcohol combinations.
Germany
Berlin and Hamburg nightlife operators anticipate phased commercial liberalization under the country's cannabis legalization pathway. ECHA substance registration requirements under REACH now cover imported terpenoid formulations at thresholds exceeding North American documentation standards. Bavarian craft distilleries explore compliant supply chain establishment before full retail liberalization.
Australia
New South Wales and Victoria licensed venues report emerging demand for controlled-dose cannabis beverages in premium hospitality settings. The Therapeutic Goods Administration maintains distinct scheduling frameworks for THC versus CBD that influence beverage formulation decisions. Melbourne's specialty bars pioneer controlled-pour dosing infrastructure for on-premise consumption.
Netherlands
Amsterdam's established cannabis coffee shop culture creates receptive infrastructure for beverage category expansion. Dutch regulators enforce documentation standards for novel botanical extracts that align with emerging ECHA requirements. Rotterdam logistics hubs position for European distribution as German market liberalization proceeds.
Cannabis-Based Alcoholic Beverages Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Cannabis-Based Alcoholic Beverages Market. Licensed facility networks with nanoemulsion capabilities command premium positioning, while co-packing specialists compete on throughput economics. The vendor base organizes around three strategic archetypes: vertically integrated cultivator-producers, formulation-technology licensors, and distribution-anchored brand houses. Competitive moves concentrate on co-manufacturing partnerships and regulatory compliance infrastructure rather than price-based rivalry.
Within the vertically integrated tier, Canopy Growth Corporation and Tilray Brands occupy positions that exemplify cultivation-to-bottling control. Truss Beverage Co. anchors the distribution-partnership archetype through exclusive retailer relationships. These three entities represent contrasting strategic bets on whether captive supply chains, formulation IP, or channel access will dominate value capture as regulatory frameworks mature.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Tilray Brands, Inc. |
| Truss Beverage Co. |
| Keef Brands |
| Lagunitas Brewing Co. |
| Rebel Coast |
| BevCanna Enterprises |
| Cann Social Tonics |
| Cronos Group Inc. |
| Others |
Cost & Logistics Intelligence
Facility-scale economies in Ontario and British Columbia co-manufacturing plants compress unit costs for nanoemulsion-stable THC beverages, concentrating pricing power among licensed producers with Health Canada amendments while forcing smaller craft entrants toward premium positioning or contract manufacturing relationships.
Pricing Analysis
California dispensaries command 15-25% premiums over Colorado retail channels for identical THC-spirit formulations, reflecting state-level taxation layering and social consumption venue density. Three-tier pricing structure across premium nanoemulsion cocktails, standard emulsion-based seltzers, and economy-tier hemp-extract beers separates quality-grade tiers with certification investment in Health Canada compliance as the primary differentiation driver. Pricing pressure stems from zero-proof THC seltzer substitution in health-positioned segments, compressing addressable ethanol-cannabinoid demand. Dispensary buyers exhibit highest price sensitivity for ready-to-drink formats, while on-premise cannabis lounges absorb premium spirits with limited elasticity.
Supply Chain Analysis
THC isolate inventory cycles run 8-14 weeks from Colorado and Oregon biomass harvest through extraction to bottling, creating working capital intensity that favors scaled players with offtake agreements. Geographic supply concentration centers on Canada for co-manufacturing infrastructure, Colorado for extraction capacity, and California for formulation R&D and brand development. Raw material dependencies include hemp-derived THC isolate, steam-distilled terpenoid formulations, and nanoemulsion surfactant packages. Single-source vulnerability in Colorado extraction capacity exposes brands to seasonal biomass yield volatility. Distribution runs through dual-license wholesalers in California and direct-to-consumer platforms where state delivery frameworks permit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against zero-proof THC beverages that bypass dual regulatory burdens and capture health-positioned consumers, requiring strategic repositioning to sustain ethanol-cannabinoid relevance.
For Market Incumbents: Secure nanoemulsion formulation IP through exclusive licensing or captive R&D investment to differentiate shelf-stable products from separating emulsions that trigger retail delisting. Defend channel position by acquiring or building direct-to-consumer delivery infrastructure in California and Colorado before platform consolidation locks out late entrants. Vertical integration into terpenoid extraction reduces input cost volatility from Oregon and Colorado biomass spot markets. For New Entrants and Emerging Players: Lead with Germany's phased commercial liberalization as a white-space geography where ECHA REACH compliance requirements have filtered out opportunistic competitors lacking documentation infrastructure. Target on-premise cannabis lounge supply in Toronto and Los Angeles where dual-license complexity creates margin capture for specialized logistics providers. Go-to-market through keg-format draft systems with controlled-pour dosing hardware addresses venue infrastructure gaps. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulation-technology licensors with nanoemulsion patent estates and recurring royalty streams from co-manufacturing partnerships, offering superior cash-flow quality versus brand-dependent volume plays. Long-term viability across the analysis window rests on regulatory integration rather than cultivation scale, favoring acquisition targets with Health Canada co-manufacturing amendments and TTB label approvals already secured. Monitor FDA GRAS status determinations for CBD-alcohol combinations as the inflection signal for interstate commerce expansion or continued state-by-state fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoemulsion Patent Licensing | Captures recurring royalties from co-manufacturers adopting lipid-particle sizing below 100 nanometers for shelf stability. |
| Health Canada Co-Manufacturing Amendment | Removes 12-18 month facility certification delays that freeze capacity expansion for unlicensed alcohol bottlers. |
| Direct-to-Consumer Platform Buildout | Bypasses three-tier alcohol distribution margin loss in California and Colorado delivery-permissive jurisdictions. |
| REACH-Compliant Terpenoid Supply Chain | Enables European market entry before German retail liberalization completes, securing first-mover positioning. |
| Dual-License Logistics Integration | Resolves channel complexity for Los Angeles and Toronto venues sourcing through separate alcohol and cannabis wholesalers. |
Research Approach
Operator-level perspectives from beverage formulation chemists, Health Canada licensing officers, California dispensary procurement managers, and Toronto cannabis lounge operators anchored the qualitative base for supply chain and regulatory pathway assessment. Primary interview insights combined with secondary validation from TTB label approval databases, Health Canada amended facility registries, ECHA REACH substance registrations, and state-level cannabis regulator testing requirement disclosures. Bottom-up volume builds across product type, ingredient, packaging, and channel segments triangulated against top-down category spending estimates from retail audit partners.
Sensitivity analysis around FDA GRAS status timing, German commercial liberalization phasing, and Colorado biomass yield volatility tested forecast robustness across the projection horizon. Segmentation dimensions modeled include product category, cannabinoid input type, packaging format, and distribution channel regulatory framework. CAGRs derived from category adoption curve analysis incorporating millennial trial rate data from Los Angeles and Denver social venues. Industry-specific inputs encompass nanoemulsion technology penetration rates and co-manufacturing facility amendment queue times.
The analysis sits within stated boundaries; outcomes outside Health Canada co-manufacturing policy continuity, state-level social consumption venue licensing expansion, or stable nanoemulsion IP enforcement would require recalibration. Forecasts reflect documented assumptions regarding regulatory integration timelines and consumer substitution elasticity between ethanol-cannabinoid and zero-proof alternatives. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Bayberry Wine Market