
 Sous Vide Cooking Appliances Market | 2026-2036
Sous Vide Cooking Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Sous Vide Cooking Appliances Market Analytics
Stainless steel heating elements are shifting toward ceramic-coated alternatives in mid-tier immersion circulators, trimming unit costs while preserving thermal conductivity. Anova Culinary leverages direct-to-consumer channel control to sustain price positioning against mass-market entrants. PolyScience Culinary anchors its presence in commercial kitchens through NSF-certified construction and institutional warranty terms. ChefSteps differentiates via proprietary algorithmic temperature control that reduces protein overcooking incidents.
Sous vide cooking appliances are precision temperature-controlled devices that maintain water baths within 0.1°C variance to achieve consistent protein doneness through low-temperature, extended-duration cooking. Units integrate PID controllers, circulation pumps, and insulated vessels to eliminate thermal stratification and ensure uniform heat distribution across food surfaces. Immersion circulators and combo units command the strongest margin pools as consumers favor modular upgrades over full-system replacements. Smart and app-controlled mechanisms represent the fastest-expanding control dimension, though manual units retain volume leadership in emerging markets where smartphone penetration lags culinary professionalization.
FDA food safety guidelines and NSF International commercial kitchen standards shape product certification requirements and channel access across the United States, while CE marking and EU food-contact material regulations govern European market entry. These frameworks elevate compliance costs for smaller manufacturers but simultaneously protect incumbents with established testing protocols. Stakeholders must weigh whether to prioritize smart-feature development for premium households or durability certifications for restaurant and catering procurement channels.
Market Dynamics
Restaurant labor compression across the United States and Germany is accelerating precision-cooking capital deployment as operators seek protein consistency without skilled line-cook overhead.
Growth Catalysts
- NSF Commercial Certification:United States institutional procurement channels now require NSF International validation for kitchen equipment, creating compliant product pull-through in foodservice.
- PID Controller Miniaturization:Semiconductor process improvements are reducing thermostat component costs in mid-tier immersion circulators without sacrificing thermal precision.
- Japan Culinary Professionalization:Tokyo and Osaka cooking schools are expanding sous vide technique modules, embedding equipment familiarity among next-generation chefs.
Market Restraints
- Heating Element Supply Concentration:Ceramic-coated resistor manufacturing clusters in Guangdong province, exposing brands to single-region disruption risk.
- Copper Price Volatility:Circulator motor windings and vessel construction remain exposed to London Metal Exchange copper contract swings.
- Water Bath Footprint Constraints:European commercial kitchens face space limitations that restrict adoption of combo units exceeding 20-liter capacity.
Strategic Opportunities
- India Premium Home Kitchens:Mumbai and Bangalore high-rise developments are incorporating built-in appliance niches sized for compact immersion circulators.
- Cloud-Connected Recipe Ecosystems:App-based temperature libraries are converging with voice-assistant platforms to reduce novice user error rates.
- EU Energy Labeling Revisions:Pending Ecodesign regulations may advantage thermally insulated vessel designs in continental retail placement.
Industry Challenges
- Calibration Technician Scarcity:Commercial warranty service networks lack sufficient field engineers certified for PID controller verification.
- CE Marking Timeline Compression:Evolving EU food-contact material testing protocols are extending product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sous Vide Cooking Appliances Market |
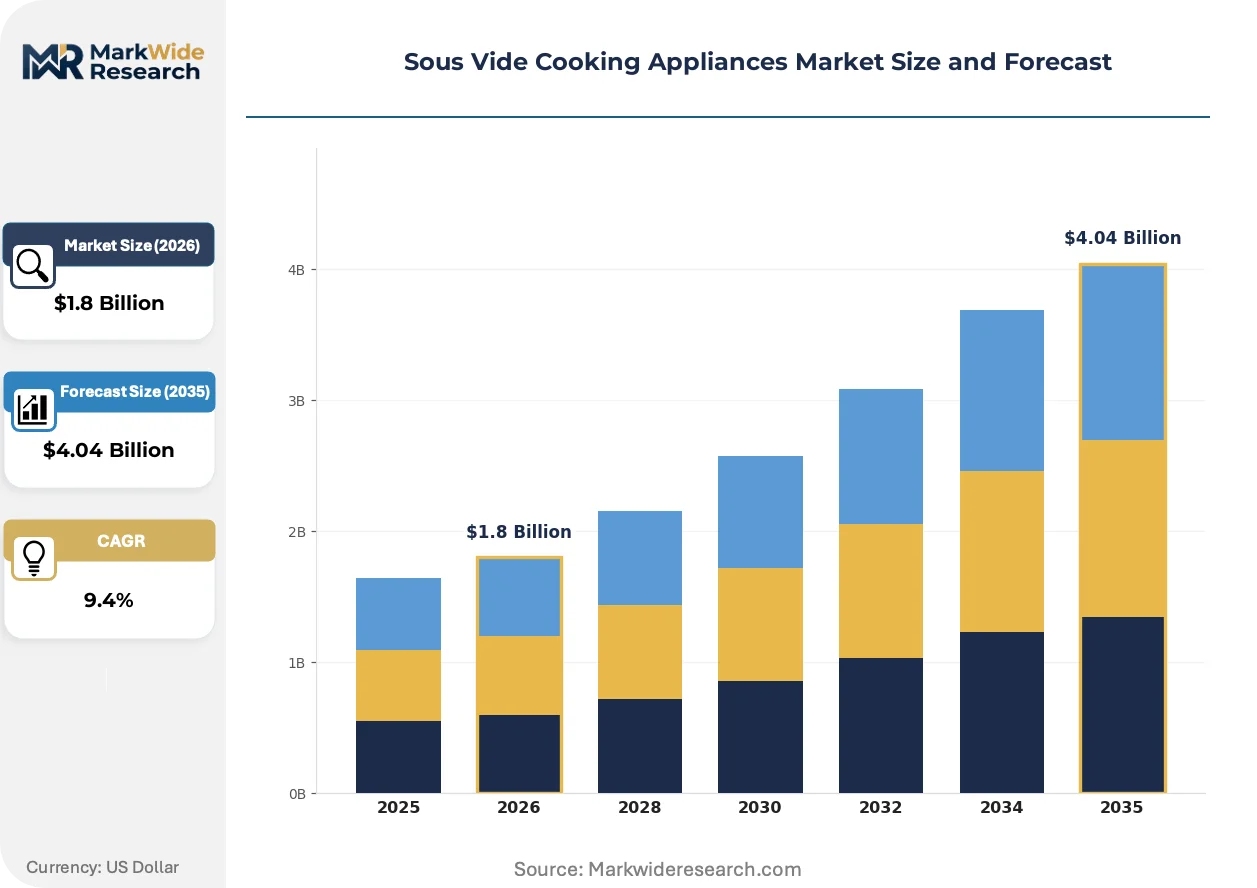
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookers, Immersion Circulators, Vacuum Sealers, Combo Units End User: Households, Restaurants, Catering Services, Culinary Schools Heating Technology: Electric, Induction, Gas, Water Bath Control Mechanism: Manual, Digital, Smart, App-Controlled |
| Companies Covered | Anova Culinary, PolyScience Culinary, SousVide Supreme, Oliso, Sansaire, Nomiku, VacMaster, ChefSteps, Gourmia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sous Vide Cooking Appliances Market Evolving Landscape
Smart connectivity architectures are redefining how temperature control algorithms deploy across price tiers, compressing feature differentiation cycles.
Bluetooth-enabled probe systems are modularizing hardware-software separation in mid-market immersion circulators. Home cooks in Germany and Japan are adopting these configurations faster than full-vessel replacements. The technology is modularizing upgrade pathways and compressing replacement cycle timing.
REACH substance restrictions on perfluorinated compounds are forcing ceramic-coating formulation changes in heating element manufacturing. European suppliers are accelerating fluoropolymer-free thermal barrier development. Commercial-grade circulators targeting EU foodservice channels are absorbing compliance testing costs ahead of 2026 enforcement windows.
Direct-to-consumer subscription bundling is displacing traditional retail attachment models for recipe content and temperature probes. Premium home segments in the United States are shifting toward annual membership structures over perpetual license purchases. This pattern is most visible in coastal metropolitan markets where culinary content consumption overlaps with appliance purchasing.
Sous Vide Cooking Appliances Market Segmentation
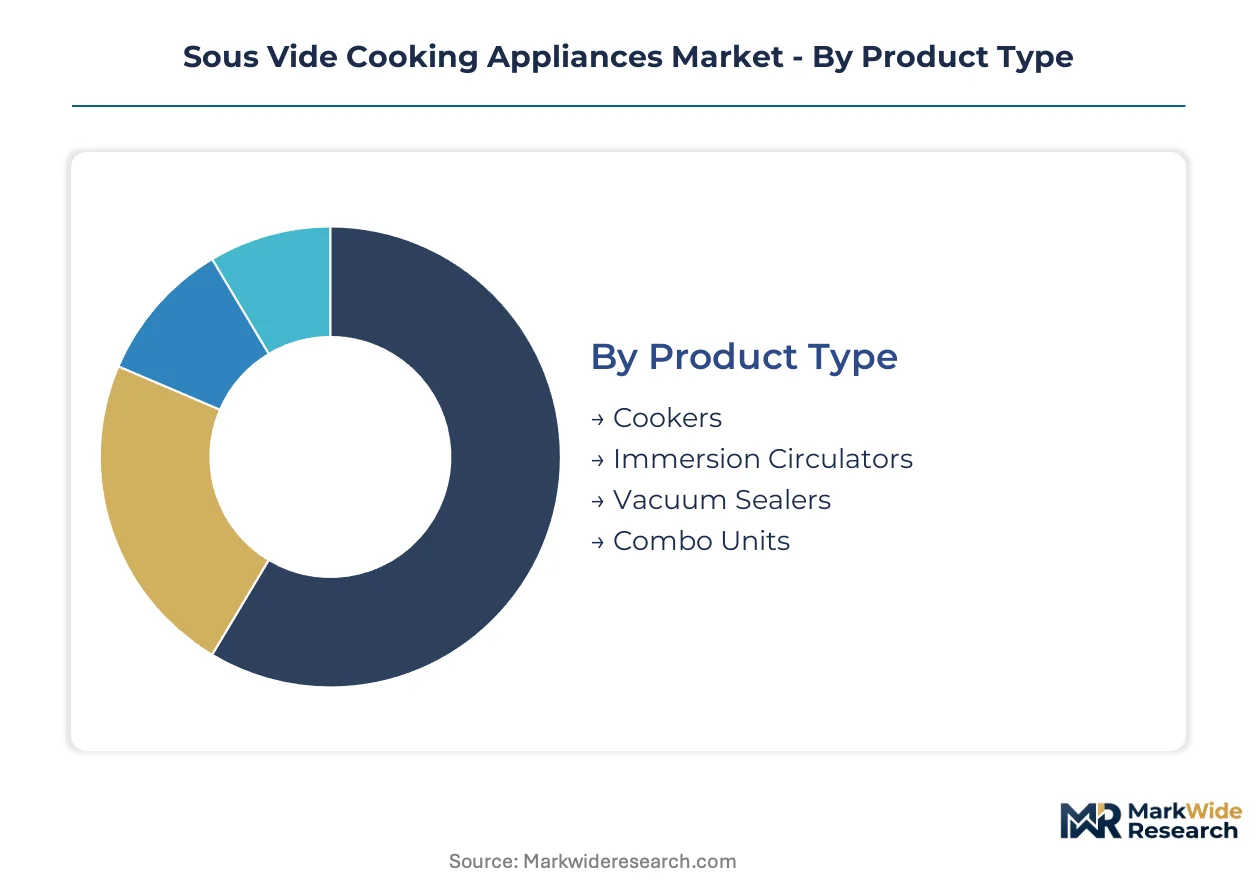
Segmentation in sous vide equipment separates buyers by kitchen infrastructure constraints, skill levels, and procurement channel requirements. Manufacturers optimize thermal engineering and connectivity stacks differently for home countertop units versus NSF-certified commercial installations.
Product Type:
Commercial buyers prioritize thermal precision and throughput capacity; home buyers favor footprint flexibility and storage efficiency.
- Cookers:Self-contained vessels with integrated heating elements and circulation pumps eliminate external container procurement. Demand concentrates in United States suburban households seeking countertop simplicity without accessory purchasing. Thermal insulation quality determines energy efficiency ratings under pending EU Ecodesign regulations.
- Immersion Circulators:Modular wand-style units clip onto existing pots or polycarbonate containers, enabling incremental kitchen upgrades. Restaurants across Germany and Japan favor this format for line-cook station flexibility and rapid vessel swapping during service rushes. PID controller miniaturization has compressed unit costs without sacrificing 0.1°C variance specifications.
- Vacuum Sealers:External suction and chamber-style units complete the sous vide workflow by eliminating air pockets that insulate food from water bath heat transfer.
- Combo Units:Integrated circulator-sealer systems target culinary schools in Tokyo and Osaka where technique standardization requires uniform equipment pairing.
Volume sits with immersion circulators; growth tilts toward combo units as institutional procurement standardizes around integrated workflows.
End User:
Skill level and labor cost exposure separate these buyer groups more than price sensitivity alone.
- Households:Premium kitchen investors in United States coastal metros and German urban centers drive smart-connected unit adoption. App-based recipe libraries reduce technique learning curves for protein doneness targets.
- Restaurants:Labor compression across United States and German foodservice accelerates precision-cooking capital deployment. NSF certification gates institutional channel access.
- Catering Services:Mobile operations prioritize compact immersion circulators and insulated transport vessels for off-site protein finishing.
- Culinary Schools:Tokyo and Osaka cooking programs embed sous vide modules, creating equipment familiarity among next-generation chefs entering restaurant kitchens.
Restaurants generate the steepest expansion trajectory; households retain absolute volume leadership through replacement cycle compression.
Heating Technology:
Energy source selection tracks kitchen infrastructure availability and operating cost structures across geographies.
- Electric:Resistive heating elements with ceramic coatings dominate immersion circulator manufacturing. Guangdong province concentration exposes supply chains to single-region disruption risk.
- Induction:Electromagnetic coil systems enable rapid water bath heating with superior energy efficiency. Premium home kitchens in Japan favor this technology where electricity costs exceed natural gas.
- Gas:Direct flame heating persists in legacy commercial installations lacking electrical capacity upgrades.
- Water Bath:Traditional bain-marie configurations retain niche presence in European culinary education for technique demonstration purposes.
Electric commands current volume; induction gains share fastest as energy efficiency regulations tighten across EU member states.
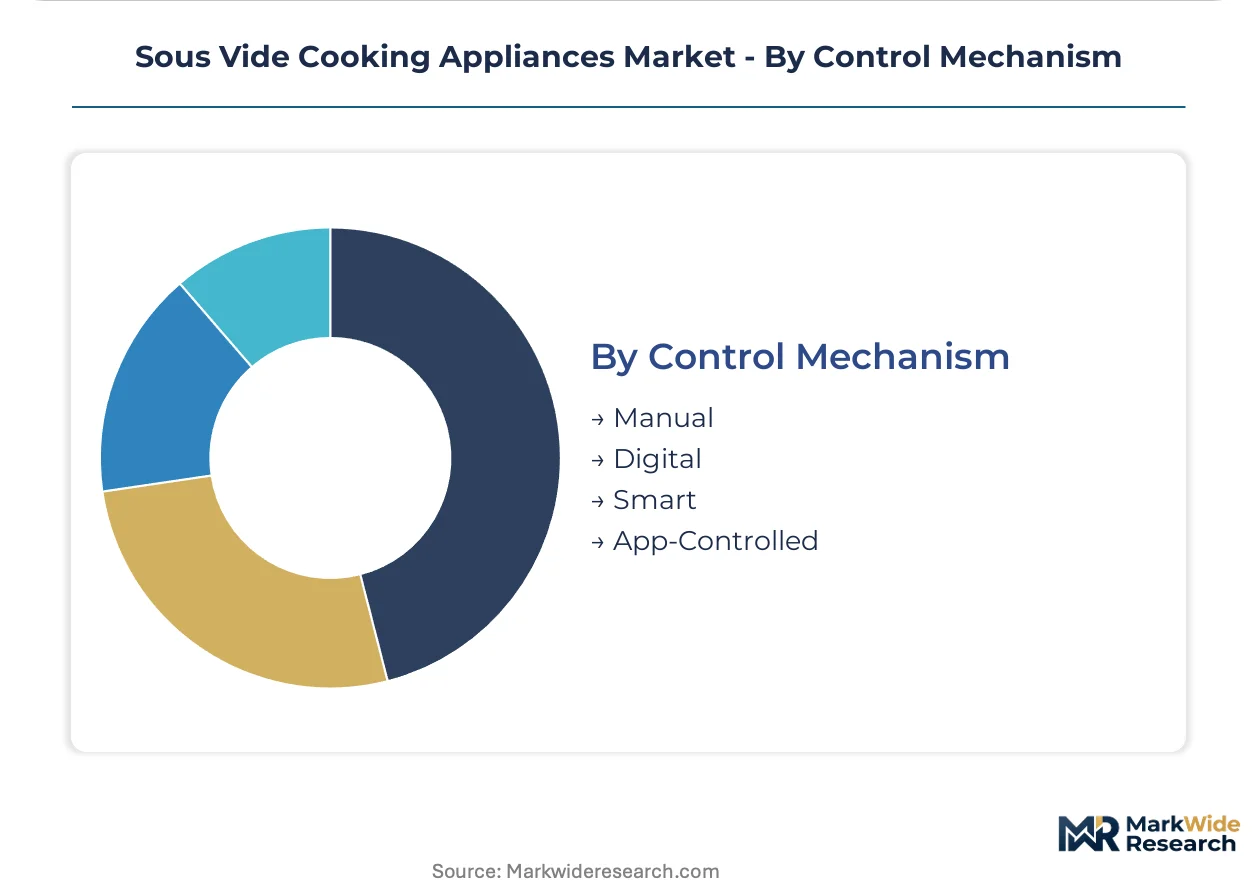
Control Mechanism:
Interface complexity separates novice users from professionals seeking repeatable precision without cognitive load.
- Manual:Dial-based temperature setting retains dominance in emerging markets where smartphone penetration lags culinary professionalization. Simple mechanical thermostats reduce failure modes in high-humidity commercial environments.
- Digital:Push-button interfaces with LED displays bridge price-performance gaps in mid-tier German and Japanese retail channels.
- Smart:WiFi-enabled units with cloud recipe synchronization target United States premium households. Bluetooth probe modularization accelerates upgrade pathways without full system replacement.
- App-Controlled:Voice-assistant integration and temperature library access reduce novice user error rates. Direct-to-consumer subscription bundling displaces traditional retail attachment models in coastal metropolitan markets.
Manual controls retain volume in price-sensitive segments; app-controlled mechanisms climb the fastest as connectivity infrastructure penetrates home kitchens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households and foodservice operators account for the densest concentration of sous vide equipment demand, with premium coastal metros and institutional procurement channels driving divergent product specifications across price tiers.
United States
Restaurant labor compression in New York and California accelerates precision-cooking capital deployment as operators seek protein consistency without skilled line-cook overhead. FDA food safety guidelines and NSF International commercial kitchen standards shape product certification requirements and channel access. Los Angeles and Chicago culinary programs embed sous vide modules, creating equipment familiarity among next-generation chefs.
Germany
Energy efficiency regulations and commercial kitchen space constraints drive adoption of compact immersion circulators over combo units in Berlin and Munich foodservice operations. CE marking and EU food-contact material regulations govern market entry, elevating compliance costs for smaller manufacturers. Stuttgart industrial clusters host precision thermostat component suppliers serving mid-tier equipment manufacturers.
Japan
Tokyo and Osaka cooking schools expanding sous vide technique modules embed equipment familiarity among next-generation chefs entering restaurant kitchens. METI efficiency standards and JIS certification requirements shape product development roadmaps. Nagoya manufacturing corridors concentrate ceramic-coated heating element production for domestic and export markets.
India
Mumbai and Bangalore high-rise developments incorporating built-in appliance niches sized for compact immersion circulators signal emerging premium home kitchen demand. BIS appliance safety standards and FSSAI food-contact material regulations establish compliance frameworks for market entry. Delhi-NCR catering services prioritize portable precision-cooking equipment for off-site protein finishing.
United Kingdom
London metropolitan culinary professionals drive smart-connected unit adoption through app-based recipe library integration. REACH substance restrictions on perfluorinated compounds force ceramic-coating formulation changes in heating element supply chains. Manchester and Birmingham foodservice distributors consolidate procurement around NSF-equivalent certified equipment for hospitality sector contracts.
Sous Vide Cooking Appliances Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer channels concentrating around culinary-content brands while commercial procurement favors institutional-certification holders. The vendor base organizes into three tiers: premium smart-connected specialists, mid-tier mass-market entrants, and commercial-grade NSF-certified suppliers. Two dominant competitive moves define current positioning: direct-to-consumer subscription bundling displacing traditional retail attachment models, and backward integration into ceramic-coated heating element production reducing Guangdong supply chain exposure.
Within the premium smart-connected tier, Anova Culinary and ChefSteps exemplify direct-to-consumer channel control strategies, while PolyScience Culinary anchors the commercial-grade certification segment. These three entities represent divergent archetypes—content-driven household penetration, algorithmic precision differentiation, and institutional warranty terms—each occupying distinct competitive space without direct feature-for-feature overlap. The market structure rewards specialization over convergence, with limited incentive for tier-crossing given divergent customer acquisition economics and service network requirements.
| Leading Market Players |
|---|
| Anova Culinary |
| PolyScience Culinary |
| SousVide Supreme |
| Oliso |
| Sansaire |
| Nomiku |
| VacMaster |
| ChefSteps |
| Gourmia |
| Others |
Value Network & Pricing Analysis
Backward integration into ceramic-coated heating element production anchors both supply security and margin defense for mid-tier immersion circulator manufacturers facing Guangdong concentration risk. This upstream control over thermal resistor sourcing simultaneously insulates brands from single-region disruption and sustains price positioning against mass-market entrants competing on component cost alone.
Pricing Analysis
Volume leadership sits with manual-control immersion circulators in emerging markets, while margin pools concentrate in smart-connected and NSF-certified commercial tiers. Price differentiation hinges on certification grade and connectivity stack depth, with FDA and NSF compliance gates commanding institutional premiums. Pricing pressure stems from semiconductor-driven PID controller cost compression filtering into mid-market tiers. Household buyers in United States coastal metros show lowest price sensitivity; emerging-market manual-unit purchasers exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and evolving EU Ecodesign regulations are reshaping sourcing patterns for thermal insulation materials and precision thermostat components. Manufacturing gravity centers on Guangdong province for ceramic-coated resistors, Nagoya corridors for heating element finishing, and Stuttgart clusters for PID controller semiconductors. Copper windings for circulator motors and polycarbonate vessel resins constitute critical raw material dependencies. Single-region exposure to Guangdong ceramic-coating capacity presents the dominant structural vulnerability. Distribution runs through direct-to-consumer channels for premium smart brands and foodservice equipment distributors for commercial NSF-certified lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where REACH substance restrictions and CE marking timeline compression will force smaller manufacturers without testing infrastructure to exit. Compliance cost elevation favors incumbents with established certification protocols and captive laboratory relationships.
For Market Incumbents: Hedge against ceramic-coating supply disruption by diversifying heating element sourcing beyond Guangdong through Nagoya supplier partnerships or in-house coating capacity. Lock in institutional channel access by accelerating NSF and CE marking investments ahead of evolving EU food-contact material enforcement windows. Defensive consolidation around certification infrastructure separates sustainable operators from compliance-lagged competitors. For New Entrants and Emerging Players: App-based temperature libraries with voice-assistant integration offer the most penetrable wedge for household segments where novice user error reduction commands premium positioning. Target Mumbai and Bangalore premium high-rise kitchens with compact immersion circulators sized for built-in appliance niches. Pursue direct-to-consumer subscription bundling over traditional retail attachment to capture coastal metropolitan culinary content consumers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to kitchen equipment conglomerates seeking smart connectivity capabilities and direct-to-consumer channel infrastructure. Five-to-ten year viability favors brands with backward-integrated heating element production and established NSF service networks over pure-play software-layer entrants. Watch FDA guidance evolution on connected appliance data security as an inflection signal for regulatory-compressed M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive ceramic-coating capacity insulates margins from Guangdong supply shocks and REACH compliance delays. |
| NSF Certification Acceleration | Institutional warranty terms unlock foodservice procurement channels in United States and United Kingdom hospitality. |
| Direct-to-Consumer Subscription Launch | Annual membership structures displace retail attachment in coastal metros where recipe content overlaps appliance purchase. |
| Bluetooth Probe Modularization | Hardware-software separation compresses replacement cycles for German and Japanese mid-market upgrade pathways. |
| EU Ecodesign Compliance Pre-positioning | Thermally insulated vessel designs secure retail placement advantage under pending continental energy labeling revisions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with restaurant equipment procurement managers, commercial kitchen consultants, PID controller semiconductor engineers, and culinary school program directors. FDA guidance documents, NSF International certification databases, CE marking technical files, and EU Ecodesign preparatory studies supplied regulatory boundary conditions. Bottom-up unit shipment estimates triangulated against top-down consumer expenditure patterns and foodservice capital expenditure surveys.
Granularity-level modeling deployed product-type splits across cookers, immersion circulators, and combo units; end-user segmentation separating households, restaurants, catering services, and culinary schools; and control mechanism tiers spanning manual, digital, smart, and app-controlled interfaces. CAGRs derived from fitted adoption curves against historical replacement cycle data and projected culinary professionalization rates. Copper price volatility assumptions and semiconductor cost compression trajectories fed sensitivity bands around base-case thermal engineering adoption.
Several conditions sit outside the modeled scope, including abrupt REACH enforcement acceleration, pandemic-scale restaurant labor market disruptions, and smartphone penetration trajectory deviations in emerging markets. Forecasts embed assumptions about regulatory timeline stability and commodity price mean-reversion that external shocks could invalidate. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Dispensing Systems and Equipment Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Global Food Deaerators Market