
 Pineapple Beer Market | 2026-2036
Pineapple Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Pineapple Beer Market Insights
Multi-pack bundling of canned variants is consolidating as the dominant configuration pattern in pineapple beer merchandising. Heineken N.V. leverages its global canning infrastructure to distribute tropical-flavored lines through mainstream retail. Maui Brewing Co anchors its positioning in Hawaiian-sourced ingredient narratives for draft and specialty releases. BrewDog competes through direct-to-consumer subscription boxes that rotate limited-edition pineapple expressions quarterly.
Pineapple beer denotes a fruit-adjunct fermented beverage brewed with pineapple juice, puree, or natural flavoring, typically achieving 4-7% ABV with titratable acidity between 0.5-1.2% to balance residual sweetness against hop bitterness. The product serves commercial purposes across on-premise draft programs, off-premise packaged goods, and seasonal limited releases targeting experimental consumers. Canned beer commands the fastest-growing packaging format as aluminum sourcing stabilizes and single-serve portability aligns with outdoor consumption occasions. Craft beer retains the deepest margin pool where small-batch pricing offsets higher per-unit production costs. Sweet flavor profiles attract entry-level drinkers while tart expressions capture repeat purchases among established craft enthusiasts.
The FDA governs labeling and ingredient safety for pineapple beer distributed in the United States, while the EU's Food Information to Consumers Regulation mandates allergen and nutritional declarations across European markets. China's SAMR enforces GB standards for fermented alcoholic beverages that restrict artificial flavoring claims and require country-of-origin labeling for imported fruit adjuncts. These frameworks elevate compliance costs for cross-border brands but simultaneously create market access barriers that protect established domestic producers. Stakeholders must monitor evolving packaging waste directives and deposit-return scheme expansions that will reshape channel economics for canned and bottled formats alike.
Market Dynamics
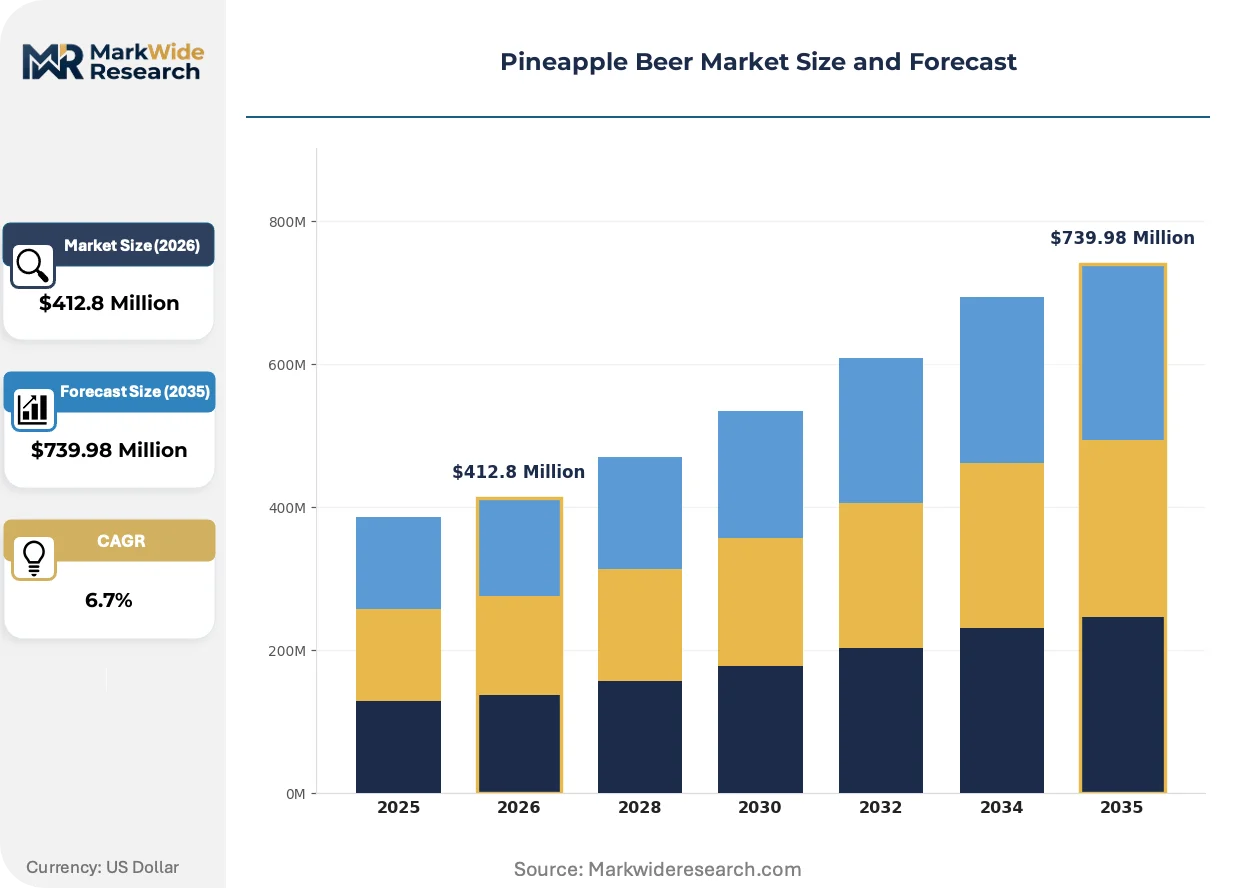
Aluminum can supply stabilization and tightening additive disclosure mandates across multiple jurisdictions are compressing formulation timelines while expanding distribution reach for portable formats.
Growth Catalysts
- GB Standards Evolution:China's SAMR enforcement of stricter country-of-origin labeling for imported fruit adjuncts is accelerating domestic sourcing partnerships among craft producers.
- Gastropub Draft Expansion:Specialty bars in Portland, Oregon and comparable clusters are rotating fruit-infused lines quarterly, creating predictable offtake for small-batch pineapple expressions.
- Canning Infrastructure:Stabilized aluminum sourcing is enabling single-serve portability that aligns with outdoor consumption occasions across camping and festival verticals.
Market Restraints
- Input Cost Volatility:Pineapple puree and natural flavoring costs fluctuate with tropical harvest cycles in Thailand and Costa Rica, squeezing margin predictability for year-round SKUs.
- Regulatory Friction:The EU's Food Information to Consumers Regulation mandates granular allergen declarations that complicate cross-border labeling for multi-fruit blends.
- Technical Limitation:Titratable acidity control between 0.5-1.2% requires precise fermentation monitoring that smaller craft operations lack capital to automate.
Strategic Opportunities
- Direct-to-Consumer Channels:Subscription box models rotating limited-edition quarterly releases are capturing repeat purchase behavior among experimental drinkers in urban clusters.
- Deposit-Return Schemes:Expanding packaging waste directives in Germany and Nordic markets create channel economics that favor aluminum over glass for import brands.
- Hawaiian Ingredient Narratives:Geographic indication storytelling around Pacific-sourced pineapple is differentiating premium positioning in Japanese and South Korean import markets.
Industry Challenges
- Compliance Timeline Compression:NMPA disclosure rule evolution in China requires reformulation documentation that extends product registration cycles by 8-14 months.
- Talent Scarcity:Brewers with dual competency in fruit adjunct chemistry and TTB/FDA label compliance command premium compensation that strains small craft payrolls.
- Integration Complexity:Legacy fermentation vessels require retrofitting for fruit puree handling, creating capex friction for established breweries pivoting into adjunct categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pineapple Beer Market |
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $739.98 Million |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Beer, Canned Beer, Draft Beer, Bottled Beer Flavor Profile: Sweet, Tart, Fruity, Balanced Sales Channel: Retail Stores, Online, Bars, Restaurants Packaging Type: Glass Bottle, Can, Keg, Plastic Bottle |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., Asahi Group Holdings, Maui Brewing Co, Molson Coors Beverage Company, Stone Brewing, BrewDog, Tsingtao Brewery Group, SanTan Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pineapple Beer Market Trends and Innovations
Formulation transparency and packaging sustainability are converging to reshape competitive positioning, with technology and regulatory pressure operating as dual accelerants.
Cross-flow filtration systems are unifying clarity standards and shelf stability for fruit-adjunct beers. Craft breweries in Oregon and Washington are adopting these systems at 15-20% annual replacement rates for legacy centrifuge setups. This unifying technology is compressing the quality gap between small-batch and scaled production, enabling regional brands to enter mainstream retail without private-label co-packing.
The EU's F-Gas Regulation and associated packaging waste directives are mandating aluminum recycling content thresholds that reshape supplier qualification. Brewers sourcing cans through European distribution must now document post-consumer recycled content percentages in procurement contracts. German and Dutch retailers are responding by prioritizing SKUs with verified circularity credentials in planogram negotiations.
Experimental consumers are consolidating purchases around discovery-oriented retail formats that unbundle variety from volume commitment. Independent bottle shops in Portland and comparable clusters are displacing supermarket beer aisles as the primary trial channel for limited releases. This behavioral shift concentrates launch success in geographic markets with dense specialty retail infrastructure.
Pineapple Beer Market Segmentation
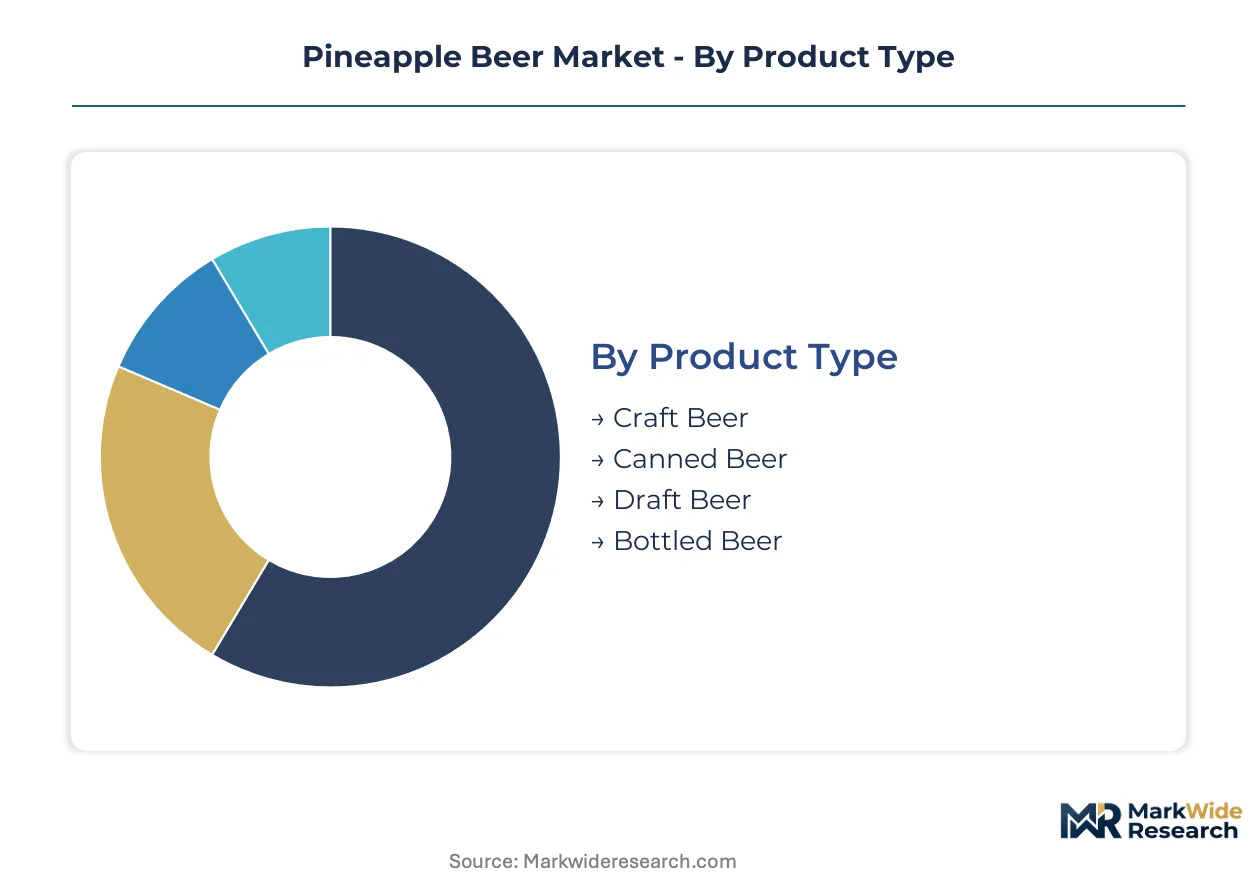
Segmentation in pineapple beer reveals how capital deployment, flavor chemistry, and channel economics stratify producer viability. Brewers must align fermentation infrastructure with packaging format and distribution pathway to capture margin in a market where aluminum sourcing and draft rotation cycles determine competitive survival.
Product Type:
Capital intensity varies sharply across brewing scales, with automated canning lines and taproom infrastructure demanding fundamentally different investment profiles.
- Craft Beer:Small-batch production in 10-30 barrel systems achieves 4-7% ABV with titratable acidity precision. Portland, Oregon taprooms concentrate demand where experimental consumers pay premium pricing for limited releases.
- Canned Beer:Aluminum sourcing stabilization has enabled scaled canning infrastructure deployment. Camping and festival verticals in the United States and Germany drive single-serve portability demand.
- Draft Beer:Keg logistics require cold-chain investment that gastropubs absorb through quarterly rotation commitments.
- Bottled Beer:Glass packaging demands higher per-unit freight costs that limit geographic radius for regional brands.
Canned beer absorbs the bulk of installed capacity; craft beer is expanding most quickly.
Flavor Profile:
Consumer repeat purchase behavior splits along acidity tolerance, with formulation chemistry determining production batch consistency requirements.
- Tart:Higher titratable acidity (0.9-1.2%) demands precise fermentation monitoring that commands premium pricing from established craft enthusiasts. Japanese specialty bars rotate these expressions quarterly.
- Sweet:Residual sugar retention attracts entry-level drinkers but shortens shelf stability. China's evolving GB standards scrutinize additive disclosure for these formulations.
- Fruity:Multi-fruit blends complicate EU allergen labeling under Food Information to Consumers Regulation.
- Balanced:Mid-range acidity targets broadest distribution but sacrifices differentiation in crowded retail sets.
Tart profiles command the deepest margin pool; sweet formulations are climbing the fastest among new category entrants.
Sales Channel:
Channel selection determines regulatory exposure, with on-premise draft programs facing distinct compliance burdens from off-premise packaged goods.
- Retail Stores:Mainstream grocery and independent bottle shops in Portland concentrate trial behavior. Heineken's global distribution infrastructure dominates shelf placement.
- Bars:Specialty draft rotations in Germany and Japan create predictable offtake for small-batch producers. Quarterly menu changes force supply chain responsiveness.
- Online:Direct-to-consumer subscription models bypass three-tier distribution but face state-by-state shipping restrictions in the United States.
- Restaurants:Gastropub partnerships require volume commitments that strain small craft payrolls.
Retail stores absorb the bulk of installed capacity; online channels are gaining share fastest.
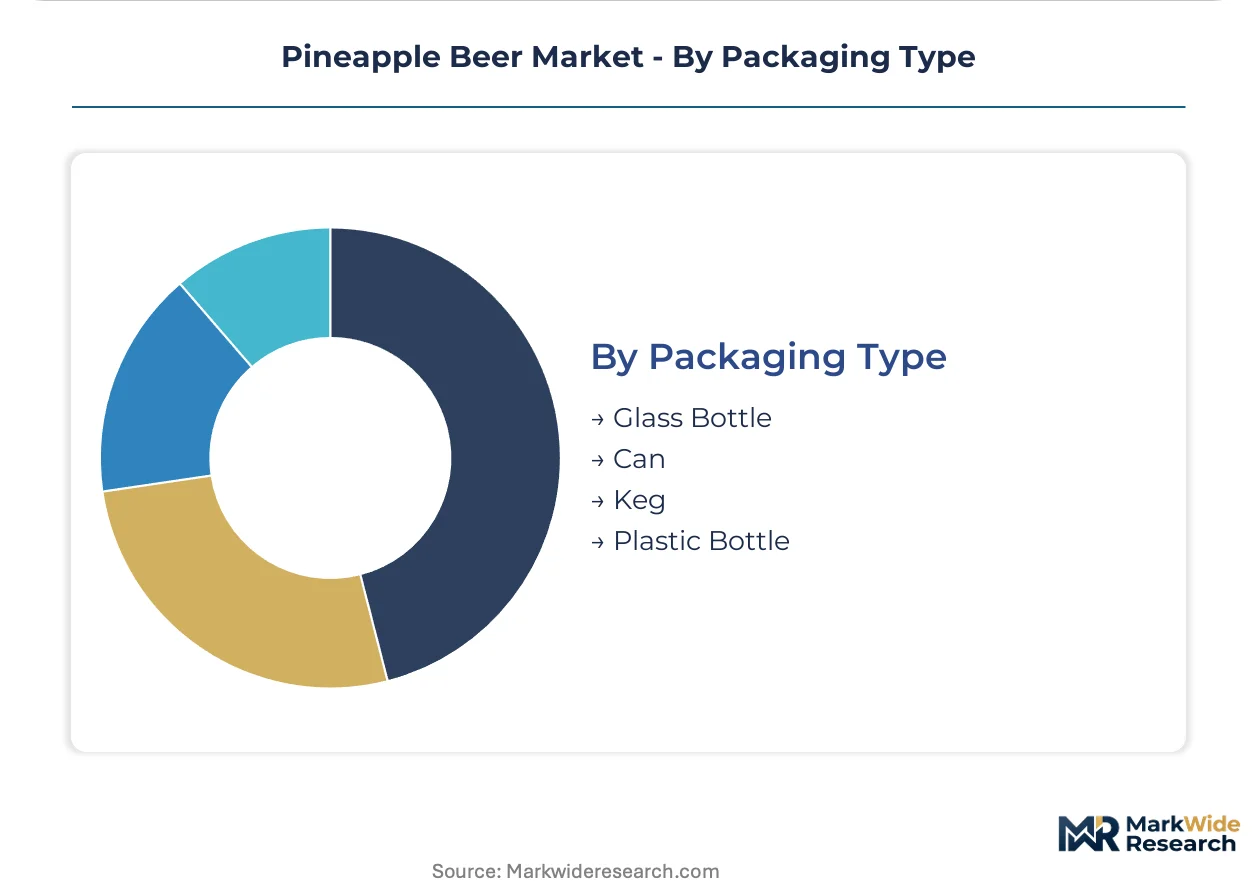
Packaging Type:
Material selection intersects with deposit-return scheme economics, particularly in German and Nordic markets where circularity credentials influence retailer planogram negotiations.
- Can:Aluminum recycling content thresholds under EU F-Gas Regulation reshape supplier qualification. Post-consumer recycled percentages now appear in procurement contracts.
- Glass Bottle:Higher weight increases freight costs but supports premium positioning in Japanese import markets.
- Keg:Reusable stainless systems minimize per-serve packaging waste for on-premise accounts.
- Plastic Bottle:Limited adoption due to flavor permeability concerns and tightening packaging waste directives.
Cans absorb the bulk of installed capacity; keg formats are expanding most quickly in gastropub verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of pineapple beer concentrates in established brewing clusters while consumption spreads through import-dependent markets. Tropical ingredient sourcing from Thailand and Costa Rica supplies fermentation facilities in North America, Europe, and East Asia. Regulatory divergence across FDA, EU F-Gas Regulation, and China's SAMR shapes formulation and packaging decisions for cross-border brands.
United States
Specialty bars in Portland, Oregon rotate fruit-infused draft lines quarterly, creating predictable offtake for small-batch pineapple expressions. The FDA governs labeling and ingredient safety, mandating nutritional declarations that elevate compliance costs for multi-fruit blends. Independent bottle shops across the Pacific Northwest concentrate trial behavior among experimental consumers.
Germany
Gastropubs in Berlin and Munich expand fruit-adjunct draft rotations to capture younger demographics seeking flavor experimentation. The EU's F-Gas Regulation and packaging waste directives mandate aluminum recycling content thresholds that reshape supplier qualification for canning operations. Deposit-return scheme economics favor aluminum over glass in planogram negotiations with mainstream retailers.
China
Urban consumers in Shanghai and Beijing demonstrate rising interest in craft fruit beers despite traditional lager dominance. SAMR enforces evolving GB standards for fermented alcoholic beverages that restrict artificial flavoring claims and require country-of-origin labeling for imported pineapple adjuncts. Domestic craft producers accelerate partnerships with Hainan Province growers to satisfy provenance requirements.
Japan
Specialty bars in Tokyo and Osaka rotate tart pineapple expressions with higher titratable acidity for established craft enthusiasts. METI oversight aligns with Food Sanitation Act requirements for imported fruit adjunct documentation. Premium positioning around Hawaiian-sourced ingredient narratives differentiates import brands in Tokyo's dense specialty retail corridor.
Australia
Outdoor consumption occasions across Queensland and New South Wales drive single-serve portability demand for canned variants. The country's national food regulator enforces labeling standards for alcoholic beverages that align with broader Commonwealth consumer protection frameworks. Independent breweries in Melbourne and Sydney leverage stabilized aluminum sourcing to expand distribution into camping and festival verticals.
Pineapple Beer Market Competitive Landscape
The competitive structure tilts toward multinational beverage conglomerates with global canning infrastructure and craft specialists with geographic ingredient narratives. Market concentration splits between scale-driven mainstream distribution and fragmented artisanal production. Three archetypes dominate: tropical-origin storytellers, direct-to-consumer subscription operators, and legacy brewers diversifying into fruit-adjunct lines. Capacity expansion in aluminum canning and strategic partnerships with tropical ingredient suppliers constitute the primary competitive moves.
Among multinational conglomerates, Heineken N.V. and Anheuser-Busch InBev occupy positions defined by global distribution infrastructure and mainstream retail shelf placement. Within the craft specialist tier, Maui Brewing Co exemplifies geographic indication storytelling through Hawaiian-sourced ingredient narratives. BrewDog represents the direct-to-consumer archetype through subscription-based limited-edition rotations. Tsingtao Brewery Group anchors the Asia-Pacific production base for fruit-adjunct expansion.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| Asahi Group Holdings |
| Maui Brewing Co |
| Molson Coors Beverage Company |
| Stone Brewing |
| BrewDog |
| Tsingtao Brewery Group |
| SanTan Brewing Company |
| Others |
Pricing and Supply Chain Analysis
Quarterly gastropub draft rotations in Portland, Oregon and comparable clusters demand predictable small-batch supply, forcing producers to absorb premium aluminum sourcing costs and tropical fruit puree volatility into margin structures.
Pricing Analysis
Margin tightening in craft-tier pineapple beer reflects aluminum recycling content mandates under EU F-Gas Regulation and Thai-Costa Rican harvest cycle volatility. Three-tier pricing structure across premium Hawaiian-origin, standard domestic craft, and economy multinational lines separates brands by ingredient provenance and titratable acidity precision. Cost-down pressure on entry-level sweet formulations accelerates because China's SAMR scrutinizes additive disclosure. Independent bottle shops show least price sensitivity; mainstream grocery buyers in Germany and Australia demand circularity credentials at parity pricing.
Supply Chain Analysis
China's evolving GB standards for country-of-origin labeling reshape sourcing toward Hainan Province domestic partnerships. Pineapple puree supply concentrates in Thailand and Costa Rica; aluminum can manufacturing draws from Chinese and German smelters. Single-source vulnerability in tropical fruit adjuncts creates margin unpredictability for year-round SKUs. Distribution runs through three-tier wholesale in the United States, direct-to-consumer subscription in urban clusters, and deposit-return scheme channels in German retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum can capacity constraints and titratable acidity automation requirements prop pricing power for producers with existing fermentation infrastructure.
For Market Incumbents: Anchor positioning through Hawaiian-sourced ingredient narratives that differentiate premium tiers in Japanese import markets. Defend against direct-to-consumer subscription entrants by locking quarterly rotation commitments with gastropub chains in Portland, Oregon and Berlin. Deepen backward integration into Pacific pineapple puree supply through Hainan Province partnerships that satisfy China's SAMR provenance rules. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for experimental quarterly releases targeting urban craft enthusiasts. White-space exists in tart-profile formulations for Japanese specialty bars and deposit-return scheme-optimized canning for German retail. Launch through independent bottle shop consignment in Pacific Northwest clusters before mainstream grocery expansion. For Investors and Strategic Acquirers: Re-rating potential sits with craft specialists possessing automated titratable acidity control and established Pacific ingredient sourcing relationships given tightening additive disclosure mandates. Long-term viability favors producers with dual competency in fruit adjunct chemistry and multi-jurisdiction label compliance. Watch NMPA registration timeline compression in China as inflection indicator for cross-border brand access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Hawaiian Ingredient Sourcing Partnership | Pacific provenance narratives differentiate premium positioning in Japanese and South Korean import markets. |
| Direct-to-Consumer Subscription Launch | Quarterly limited-edition rotations capture repeat purchase behavior among experimental urban drinkers. |
| Automated Titratable Acidity Installation | Fermentation precision equipment enables tart-profile consistency that commands craft enthusiast premiums. |
| Deposit-Return Scheme Can Optimization | Aluminum circularity credentials unlock German retailer planogram negotiations under EU packaging directives. |
| Cross-Flow Filtration System Adoption | Clarity standardization compresses quality gaps between small-batch and scaled production for retail entry. |
Research Methodology
Trade databases, regulatory filings, and customs records formed the secondary backbone, supplemented by primary interviews with craft brewery owners, gastropub beverage directors, aluminum procurement managers, and tropical fruit puree distributors. Bottom-up volume triangulation across packaging formats and flavor profiles converged with top-down value estimates derived from taproom pricing and retail scan data.
Historical trendline analysis tracked segment evolution across the projection horizon, with CAGRs derived from elasticity modeling against aluminum price indices and craft beer penetration curves. Segmentation dimensions included product type, flavor chemistry, sales channel, and packaging material, with forecast inputs incorporating NMPA registration timelines and EU F-Gas Regulation implementation phases.
The model holds under stable aluminum sourcing and gradual regulatory harmonization; deviation in tropical harvest disruption or abrupt GB standards enforcement would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Mezcal Market