
 Wine Filtering Machine Market | 2026-2036
Wine Filtering Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Filtering Machine Market Analytics
Craft distillery adoption is shifting the end-user mix as spirits producers adopt wine-grade filtration protocols for cask-finished products. Krones AG leverages its bottling-line integration expertise to bundle filter units with turnkey winery installations. Alfa Laval anchors its position through heat-exchanger and separation synergies that reduce cross-contamination risk. Bucher Vaslin specializes in gentle must-handling systems that preserve aromatic compounds during pre-fermentation clarification.
Wine filtering machines are pressure-driven separation systems that remove suspended solids, yeast, bacteria, and colloidal haze from fermented grape must and finished wine, typically operating at 0.1 to 10 micron ratings and temperatures between -4°C and 25°C to protect heat-sensitive phenolics and volatile esters. Cross-flow filtration dominates new capacity additions because its tangential flow pattern minimizes membrane fouling and extends run times between chemical cleans. Membrane filters capture the fastest growth in technology terms as wineries replace diatomaceous earth with polymeric hollow-fiber modules that eliminate powder handling hazards and waste disposal burdens. Ultrafiltration occupies the premium tier for protein and polysaccharide stabilization without excessive tannin stripping.
FDA beverage safety regulations and TTB labeling requirements shape equipment validation protocols, while EU REACH compliance governs seal and membrane material selection for European exports. France's national food safety agency enforces strict oenological additive limits that drive sterile filtration adoption over chemical stabilization. Stakeholders must monitor evolving PFAS restrictions in membrane polymers and energy-efficiency mandates that could redesign pump and motor specifications.
Market Dynamics
Cross-flow membrane technology is compressing filtration economics by eliminating diatomaceous earth handling and extending run cycles between chemical cleans, forcing wineries to retire legacy plate-and-frame systems ahead of depreciation schedules.
Growth Catalysts
- TTB Label Integrity Mandates:US beverage alcohol labeling requirements now require validated sterile filtration records for export certification, pushing automated validation protocols into mid-size winery capital budgets.
- Champagne Houses:France's ANSM enforces strict oenological additive limits that eliminate chemical stabilization options, making membrane filtration the only compliant path to microbial stability in premium sparkling production.
- Hollow-Fiber Polymers:Polymeric membrane modules eliminate powder handling hazards and hazardous waste streams associated with diatomaceous earth disposal, reducing occupational safety liabilities.
Market Restraints
- Membrane Polymer Supply:Perfluorinated polymer feedstocks face tightening EU REACH restrictions and emerging PFAS liability exposure, concentrating qualified suppliers in Germany and Japan.
- Technical Limitation:Ultrafiltration's 0.1-micron rating strips excessive tannin from full-bodied reds, limiting adoption in Cabernet Sauvignon and Malbec production despite protein stability benefits.
- Energy Cost Structure:Cross-flow systems require continuous pumping at 2-4 bar differential pressure, exposing operators to electricity tariff volatility in markets with renewable transition surcharges.
Strategic Opportunities
- India's Nascent Wine Sector:Maharashtra and Karnataka state governments offer capital subsidies for food-processing equipment under PLI-aligned schemes, creating first-mover positioning for membrane filtration vendors.
- Spirits Convergence:Cask-finished whiskey and rum producers are adopting wine-grade sterile filtration for pre-bottling clarification, opening adjacent equipment demand with shared technical specifications.
- EU Green Deal Alignment:Energy-efficiency mandates for industrial pumps and motors are accelerating variable-frequency drive adoption, enabling filtration OEMs to bundle compliance-ready packages.
Industry Challenges
- Membrane Certification Timelines:FDA food-contact notifications and EU migration testing for new polymer formulations extend product development cycles by 18-24 months, freezing formulation innovation.
- Legacy System Integration:Wineries operating 1990s-era plate filters lack PLC infrastructure and sanitary welding standards, requiring complete utility rebuilds to accommodate modern skids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Filtering Machine Market |
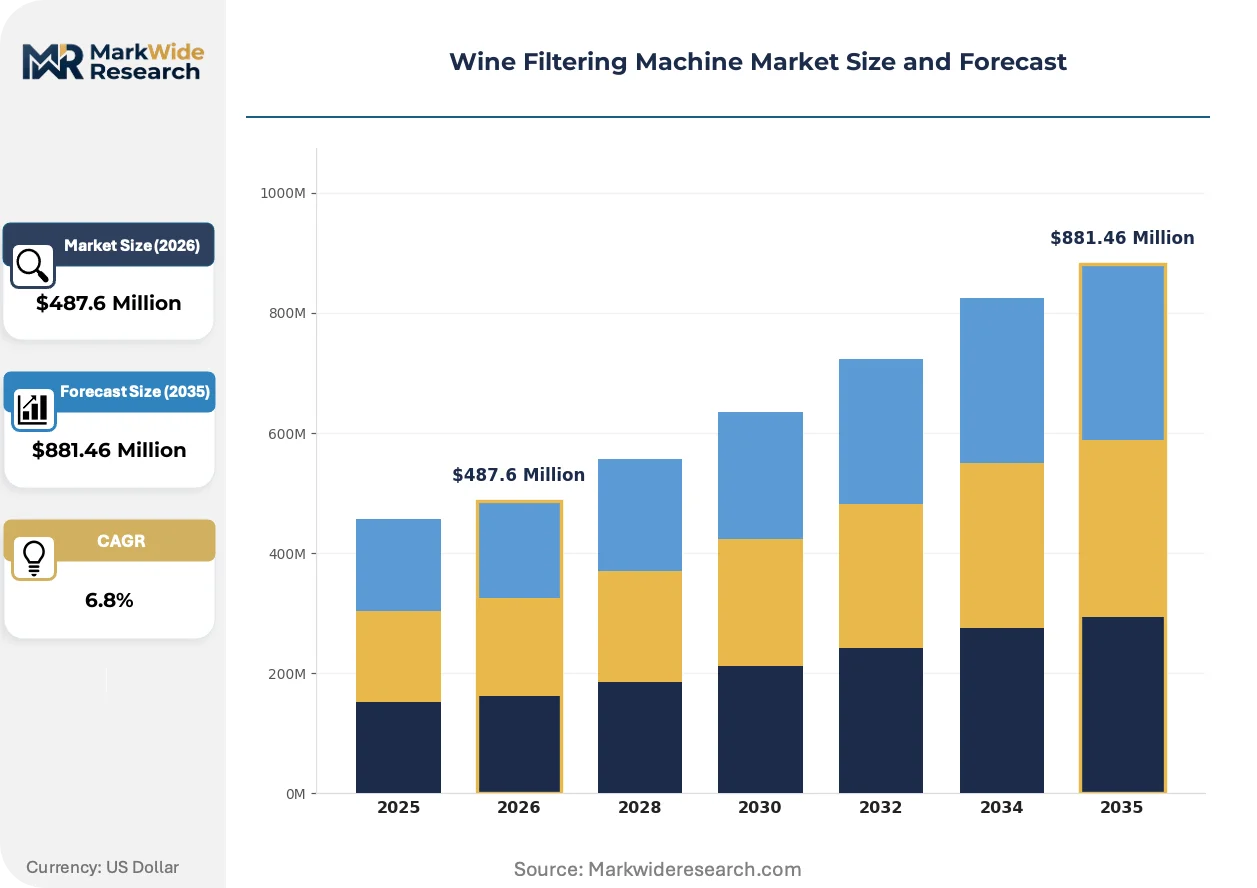
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-flow Filters, Plate Filters, Cartridge Filters, Membrane Filters End User: Wineries, Breweries, Distilleries, Beverage Producers Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Clarification, Stabilization, Sterilization, Purification |
| Companies Covered | Parker Hannifin, Krones AG, Alfa Laval, Bucher Vaslin, Criveller Group, Sartorius, Pall Corporation, Della Toffola Group, Gai Macchine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Filtering Machine Market Evolving Landscape
Equipment architecture is pivoting from standalone filtration skids toward integrated process trains that combine must clarification, heat exchange, and sterile filtration under unified control systems.
Mobile filtration services are decentralizing capital deployment in the wine industry. Regional service providers now trailer cross-flow units between harvest contracts, allowing small wineries to access sterile filtration without seven-figure capital commitments. This asset-light model compresses payback periods from seven years to single-season operating leases.
EU F-Gas Regulation is accelerating refrigerant transitions in filtration-cooling circuits. Wineries must replace R-404A and R-507A with lower-GWP alternatives by 2030, forcing heat-exchanger redesigns and retooling of glycol-chilled filtration lines. Champagne producers face the tightest compliance deadlines due to their reliance on precise temperature control during disgorgement.
Boutique wineries are unbundling after-sales service from equipment purchase contracts. Rather than multi-year maintenance agreements, buyers now procure membrane replacement and CIP chemistry through third-party supply houses. This disintermediation pressures OEM margin pools while expanding independent service networks in Napa Valley and Sonoma County.
Wine Filtering Machine Market Segmentation
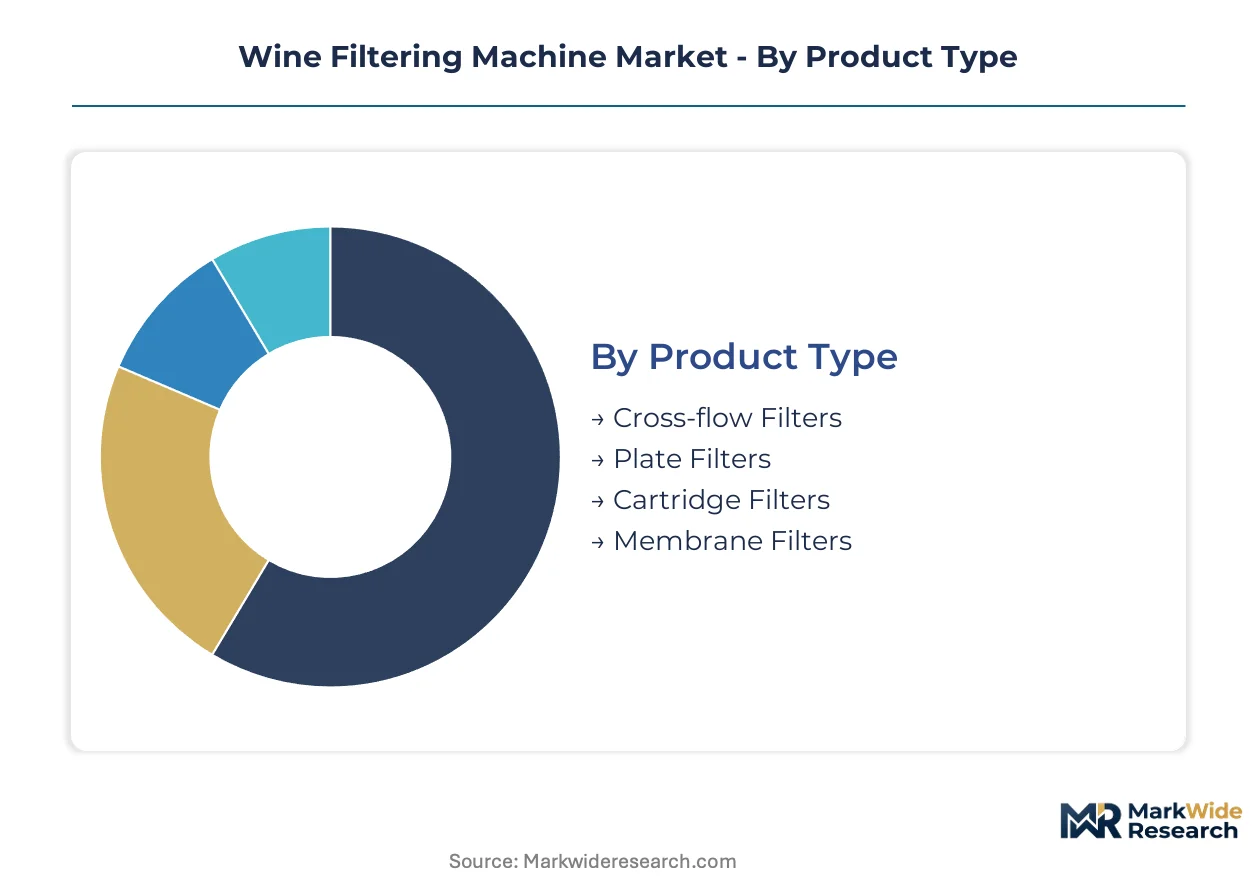
Wine filtering machine procurement splits sharply between high-volume bulk producers and precision-focused premium houses. Equipment specification diverges across this divide, with membrane technologies commanding premium winery budgets while plate systems retain cost-sensitive volume operations.
Product Type:
Volume producers favor established mechanical formats. Premium wineries invest in membrane sophistication.
- Cross-flow Filters:Tangential flow patterns minimize membrane fouling and extend run cycles between chemical cleans. Demand concentrates in Champagne houses modernizing legacy equipment to meet ANSM additive limits while preserving traditional method protocols.
- Membrane Filters:Polymeric hollow-fiber modules eliminate diatomaceous earth powder hazards and waste disposal burdens. Napa Valley and Sonoma County boutique wineries deploy these for unfiltered-style wines requiring guaranteed microbial stability without chemical intervention.
- Plate Filters:Legacy plate-and-frame systems dominate established bulk operations with depreciated capital bases. TTB validation mandates are forcing premature retirement ahead of schedule.
- Cartridge Filters:Disposable cartridge formats serve small-batch producers and mobile filtration service providers. Maharashtra and Karnataka state subsidies under PLI-aligned schemes are accelerating first-time adoption in India's nascent wine sector.
Mature deployment sits with Plate Filters. Newer deployment is concentrated in Membrane Filters.
End User:
Customer mix is shifting as spirits producers adopt wine-grade protocols.
- Wineries:Traditional grape-based operations span bulk cooperatives to estate bottlers. FDA and TTB beverage safety requirements now mandate validated sterile filtration records for export certification, pushing automated systems into mid-size capital budgets.
- Distilleries:Cask-finished whiskey and rum producers are adopting wine-grade sterile filtration for pre-bottling clarification. This adjacent demand shares technical specifications with premium wine applications.
- Breweries:Beer producers utilize cross-flow systems for haze stability without pasteurization heat damage. Equipment specifications diverge at membrane pore ratings optimized for protein-polyphenol complexes rather than wine tannins.
- Beverage Producers:Non-alcoholic and functional drink manufacturers deploy filtration for microbial security and shelf-life extension. EU F-Gas Regulation compliance deadlines are forcing heat-exchanger redesigns in glycol-chilled lines.
Established procurement sits with Wineries. Fastest-expanding demand is emerging from Distilleries.
Technology:
Pore-size precision determines application suitability and capital allocation priority.
- Microfiltration:0.1 to 10 micron ratings remove yeast, bacteria, and suspended solids while protecting heat-sensitive phenolics. Champagne producers rely on precise temperature control during disgorgement operations.
- Ultrafiltration:0.01 to 0.1 micron separation stabilizes proteins and polysaccharides without excessive tannin stripping. Technical limitation in full-bodied reds constrains Cabernet Sauvignon and Malbec adoption despite protein stability benefits.
- Nanofiltration:Selective ion and small-molecule separation supports dealcoholization and tartrate stability applications. EU REACH compliance governs membrane polymer selection for export-bound equipment.
- Reverse Osmosis:High-pressure separation enables alcohol adjustment and water removal for concentrate production. Energy cost exposure from continuous 2-4 bar differential pumping creates tariff vulnerability in markets with renewable transition surcharges.
Commercial maturity rests with Microfiltration. Steepest expansion trajectory belongs to Ultrafiltration.
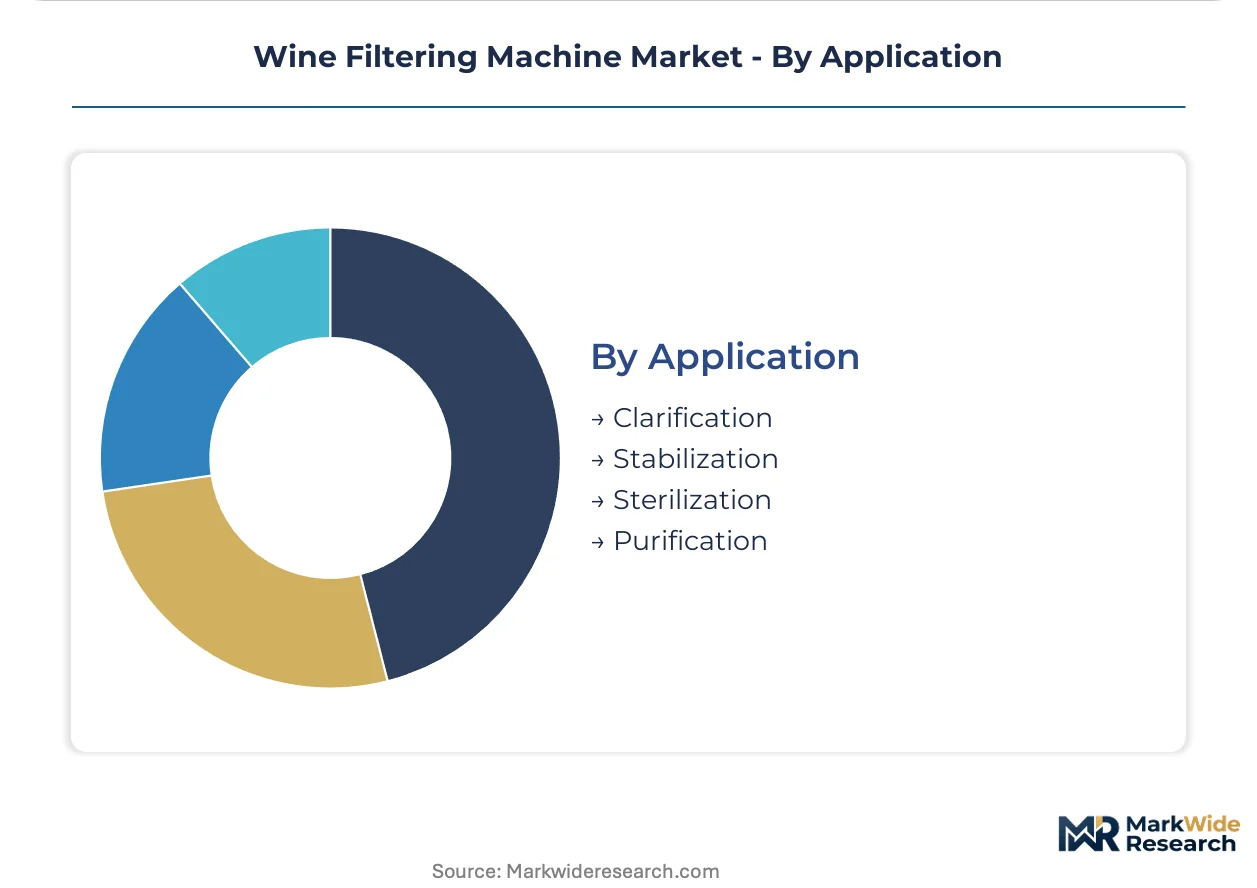
Application:
Process stage determines equipment configuration and validation requirements.
- Sterilization:Absolute microbial elimination for export-certified finished wine. TTB label integrity mandates require automated validation protocols with documented filtration records.
- Stabilization:Protein and colloidal haze prevention without chemical additives. ANSM oenological limits in France eliminate alternative stabilization paths for premium sparkling production.
- Clarification:Pre-fermentation must handling and post-fermentation solids removal. Bucher Vaslin's gentle systems preserve aromatic compounds during this critical stage.
- Purification:Removal of off-odors, taints, and process contaminants from compromised lots. Mobile filtration services deploy trailer-mounted cross-flow units for seasonal spot demand.
Regulatory pressure concentrates on Sterilization. Operational flexibility is expanding fastest in Purification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Napa Valley's agricultural enterprise zones and Sonoma County's wine industry tax incentives are concentrating new filtration capacity investments in Northern California, while France's Champagne region and India's emerging wine belts offer parallel expansion corridors shaped by distinct regulatory frameworks.
United States
Boutique wineries in Napa Valley and Sonoma County are expanding cross-flow membrane capacity to meet consumer preference for premium unfiltered-style wines with guaranteed microbial stability. FDA beverage safety regulations and TTB labeling requirements now mandate validated sterile filtration records for export certification, pushing automated systems into mid-size capital budgets. Northern California clusters anchor domestic demand as mobile filtration services decentralize capital deployment through seasonal operating leases.
France
Champagne houses are modernizing legacy equipment to balance traditional method protocols with ANSM oenological additive limits that eliminate chemical stabilization options. EU F-Gas Regulation deadlines force heat-exchanger redesigns in glycol-chilled disgorgement lines by 2030. The Champagne-Ardenne cluster drives premium-tier membrane adoption as producers seek compliant paths to microbial stability without powder-based filtration.
India
Maharashtra and Karnataka state governments offer capital subsidies for food-processing equipment under PLI-aligned schemes, creating first-mover positioning for membrane filtration vendors. The country's national food safety regulator enforces beverage safety standards that favor validated sterile systems over conventional clarification. Nascent wine production in Nashik and Bengaluru corridors is attracting cartridge filter deployments for small-batch producers without seven-figure capital commitments.
Germany
EU REACH restrictions on perfluorinated polymer feedstocks are concentrating qualified membrane suppliers in German and Japanese industrial corridors. The country's chemical regulator enforces strict migration testing protocols that extend product development cycles for new polymer formulations. Bavarian and Baden-Württemberg equipment fabricators are bundling variable-frequency drive packages to meet EU Green Deal energy-efficiency mandates for industrial pumps and motors.
Italy
Premium estate bottlers in Piedmont and Tuscany are replacing diatomaceous earth with polymeric hollow-fiber modules to eliminate powder handling hazards and waste disposal burdens. CE marking requirements govern equipment validation for intra-European trade and export certification. Northern Italian wine machinery clusters are integrating filtration skids with turnkey bottling lines to capture turnkey winery installation contracts.
Wine Filtering Machine Market Competitive Landscape
Top-tier vendors anchor premium membrane technology, while mid-tier fabricators compete on bundled bottling-line integration and regional service networks. The vendor base stratifies across three functional tiers: filtration specialists with separation expertise, turnkey systems integrators with bottling-line synergies, and regional machinery builders with harvest-season service proximity. Dominant competitive moves include strategic partnerships between membrane polymer suppliers and skid fabricators, plus geographic expansion through mobile filtration service franchising.
Among European-headquartered filtration specialists, Alfa Laval AB and Sartorius AG exemplify the premium-tier archetype through their positioning in heat-exchanger and separation technologies. Krones AG represents the systems-integrator archetype, leveraging bottling-line bundling expertise to capture turnkey winery installations. Parker Hannifin Corporation occupies a position within the industrial automation tier, supplying pressure-control components that underpin cross-flow system reliability. These three entities collectively span the technology-to-integration value chain without overlapping core competencies.
| Leading Market Players |
|---|
| Parker Hannifin |
| Krones AG |
| Alfa Laval |
| Bucher Vaslin |
| Criveller Group |
| Sartorius |
| Pall Corporation |
| Della Toffola Group |
| Gai Macchine |
| Others |
Value Network & Pricing Analysis
Perfluorinated polymer feedstock indices cascade through membrane module manufacturing into three distinct pricing tiers, compressing margins for hollow-fiber suppliers while amplifying bargaining power for German and Japanese polymer compounders facing EU REACH restrictions.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard delivery schedules as Champagne houses and Napa Valley boutique wineries accelerate harvest-season procurement. Three-tier pricing structure across premium, standard, and economy levels separates validated FDA-tier membrane systems from CE-marked mid-range skids and depreciated plate-filter overhauls. Pricing pressure stems from mobile filtration service operators undercutting capital-equipment vendors with single-season operating leases. Bulk cooperatives exhibit highest price sensitivity; premium estate bottlers prioritize microbial validation over unit economics.
Supply Chain Analysis
Transoceanic freight cost volatility from German and Japanese polymer compounders to Italian and French skid fabricators amplifies landed cost uncertainty for membrane module procurement. Supply concentrates in Germany, Japan, and Italy for perfluorinated polymers, precision hollow-fiber extrusion, and turnkey bottling-line integration respectively. Raw material dependencies span polyethersulfone resin, stainless-steel sanitary tubing, and variable-frequency drive controllers. Single-source vulnerability concentrates in REACH-compliant polymer formulations. Distribution runs through OEM direct sales for premium tier, regional machinery distributors for mid-market, and mobile service franchises for asset-light segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where membrane polymer supply security and aftermarket service network density determine sustainable margin capture.
For Market Incumbents: To counter mobile filtration service disintermediation, membrane OEMs should acquire regional bottling-line integrators to bundle filtration skids with turnkey winery installations. Captive hollow-fiber extrusion capacity insulates against REACH-driven polymer supply rationing. For New Entrants and Emerging Players: Capture India's nascent wine sector through PLI-aligned capital subsidy partnerships with Maharashtra and Karnataka state agencies. Cartridge filter deployments for small-batch producers offer lowest competitive friction against entrenched cross-flow vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mobile filtration service operators with trailer-mounted asset bases in Northern California and Champagne-Ardenne corridors. Monitor EU F-Gas Regulation compliance deadlines as inflection indicator for heat-exchanger retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-compliant membrane feedstock security anchors premium-tier supply continuity for FDA-validated systems. |
| Mobile Service Network Franchising | Seasonal asset-light deployment compresses winery payback periods from seven-year capital cycles to single-harvest operating leases. |
| Bottling-Line Bundling Partnerships | Turnkey winery installation contracts capture filtration attach rates through Krones AG integration expertise. |
| Variable-Frequency Drive Retrofit Programs | EU Green Deal pump efficiency mandates create compliance-ready package differentiation for German fabricators. |
| Distillery Adjacent Market Entry | Cask-finished spirits filtration shares technical specifications with premium wine sterile clarification protocols. |
Research Methodology
Independent corroboration across equipment procurement directors at Champagne houses, technical directors at membrane polymer compounders, and aftermarket service heads at Italian machinery clusters underwrites the qualitative findings. Primary interviews with winery operations managers, distillery production leads, and mobile filtration service operators combined with secondary validation from FDA food-contact notification databases, EU REACH substance restriction filings, and TTB export certification records. Bottom-up unit deployment tallies and top-down capital expenditure surveys triangulate market sizing.
Comparable-period anchoring to historical filtration capacity installations across bulk cooperative, estate bottler, and spirits producer segments structures the projection framework. Modeled dimensions span membrane technology tier, end-use vertical, application stage, and regional regulatory cluster. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate EU F-Gas Regulation compliance timelines and PLI scheme subsidy trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS polymer substitution timelines and renewable energy tariff volatility affecting cross-flow pumping economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Craft Rum Market