
 Alcohol Enzymes Market | 2026-2036
Alcohol Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Enzymes Market Intelligence
Enzyme formulation services is reconfiguring margin pools away from commoditized bulk sales toward customized blends for craft distillers and cellulosic ethanol operators. Novozymes A/S leverages its Novo Nordisk heritage in fermentation scale-up to dominate microbial strain supply for starch-to-ethanol pathways. DuPont de Nemours, Inc. competes through its Pioneering enzyme platforms optimized for high-temperature liquefaction in corn wet mills. BASF SE anchors its position with backward integration into genetically modified Trichoderma reesei production for cellulase manufacturing.
Alcohol enzymes are protein biocatalysts, typically derived from fungal or bacterial fermentation, that hydrolyze polysaccharides into fermentable sugars at temperatures between 55°C and 95°C and pH ranges of 4.0 to 6.5, serving as process enablers in beverage fermentation, bioethanol production, and industrial alcohol synthesis. Glucoamylase commands the largest revenue share among product types due to its indispensable role in saccharification, the rate-limiting step in both brewing and fuel ethanol operations. Beverage production applications retain structural dominance in value terms, though biofuel production exhibits the fastest trajectory as cellulosic ethanol technologies mature and lignocellulosic feedstock pretreatment improves.
The EPA's Renewable Fuel Standard and the EU's revised Renewable Energy Directive create compliance-driven demand for certified enzyme inputs that meet lifecycle greenhouse gas reduction thresholds. India's BIS standards for industrial enzymes and China's GB standards for food-grade biocatalysts impose purity and activity specifications that filter subscale suppliers from import markets. Stakeholders must monitor how evolving carbon-border adjustment mechanisms reshape the cost competitiveness of regionally produced versus imported enzyme formulations.
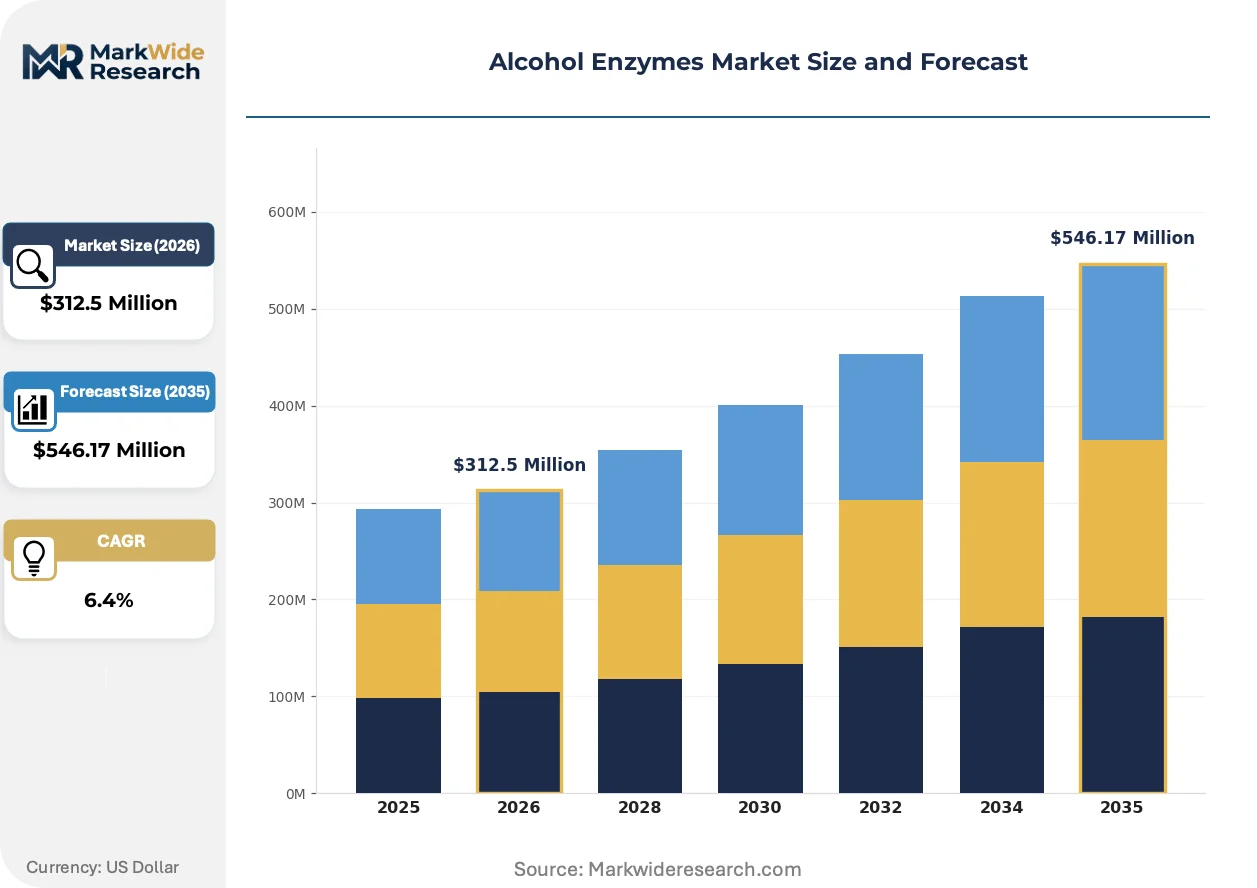
Market Dynamics
CRISPR-based enzyme engineering is compressing strain development timelines from years to months, fundamentally altering how biofuel producers and beverage manufacturers secure biocatalyst supply. This acceleration is redrawing competitive boundaries between specialized enzyme houses and integrated biotechnology platforms.
Growth Catalysts
- Renewable Fuel Standard compliance:The EPA's lifecycle greenhouse gas thresholds mandate certified enzyme inputs for bioethanol producers, forcing procurement upgrades across US fuel ethanol operations.
- Cellulosic ethanol maturation:Improved lignocellulosic pretreatment methods are unlocking commercial-scale deployment of cellulase cocktails for agricultural residue conversion.
- China's ethanol blending mandates:State-backed E10 programs are scaling domestic enzyme manufacturing capacity and redirecting global supply chain gravity toward Chinese producers.
Market Restraints
- Raw material volatility:Corn starch and agricultural substrate prices swing with climate-induced harvest variability, squeezing margin predictability for enzyme formulators.
- Supply concentration risk:Denmark and Netherlands-based fermentation specialists control critical microbial strain IP, creating single-source dependencies for high-performance glucoamylase.
- Technical limitation:Cellulase enzyme stability under industrial pretreatment conditions remains inconsistent, delaying full commercialization of second-generation bioethanol pathways.
Strategic Opportunities
- India's biofuel expansion:The country's 20% ethanol blending target by 2025 under its Ethanol Blended Petrol program creates import substitution potential for localized enzyme production.
- Craft distiller customization:Small-batch spirits producers are commissioning bespoke enzyme blends for heritage grain varieties, opening premium formulation services.
- EU Green Deal integration:The revised Renewable Energy Directive's RED III sustainability criteria reward enzymes with verified carbon-intensity scores, favoring suppliers with transparent supply chains.
Industry Challenges
- Fermentation scale-up expertise gap:Industrial biologists with simultaneous mastery of CRISPR editing and thousand-liter bioreactor operation command scarcity premiums, constraining R&D velocity.
- Multi-jurisdiction certification burden:Enzyme producers must simultaneously satisfy FDA GRAS determinations, EU food enzyme approvals, and China's GB standards, extending product launch timelines.
- Legacy equipment incompatibility:Next-generation thermostable enzymes require retemperatured liquefaction trains, forcing capital-intensive retrofits at established corn wet mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Enzymes Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Glucoamylase, Protease, Cellulase Application: Beverage Production, Biofuel Production, Food Processing, Waste Treatment End User: Beverage Industry, Biofuel Companies, Food Manufacturers, Environmental Firms Form: Liquid, Powder, Granular, Concentrated |
| Companies Covered | Novozymes A/S, DuPont de Nemours, Inc., BASF SE, Amano Enzyme Inc., Advanced Enzyme Technologies Ltd., Associated British Foods Plc, Kerry Group Plc, Koninklijke DSM N.V., Ajinomoto Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Enzymes Market Strategic Shifts & Innovations
Biocatalyst development is diverging along two vectors: precision-engineered strains for commodity biofuel scale and artisanal formulations for beverage differentiation. This bifurcation is fragmenting R&D investment patterns and reshaping how enzyme houses organize their technical service capabilities.
CRISPR-Cas9 genome editing is hybridizing traditional fungal hosts like Aspergillus niger with synthetic biology toolkits to produce multi-enzyme cocktails in single fermentation runs. Cellulosic ethanol operators in the US Midwest are piloting these consolidated bioprocessing strains to reduce unit costs. The technology is hybridizing what were previously separate upstream and downstream process steps, compressing capital requirements for greenfield biofuel plants.
The EU's revised Renewable Energy Directive imposes stricter sustainability certification on imported biofuels, cascading into enzyme procurement specifications. Fuel ethanol producers must now document that their biocatalyst suppliers meet delegated act criteria for land-use change and greenhouse gas savings. Brazilian sugarcane ethanol exporters are responding by sourcing enzymes with EU-recognized sustainability credentials, reshaping procurement priorities for international enzyme traders.
Buyer consolidation among multinational biofuel producers is compressing enzyme supply agreements into multi-year performance contracts with embedded technical service clauses. These arrangements displace spot purchasing and force smaller enzyme houses to build captive application engineering teams. The pattern is most visible in the US Corn Belt, where three ethanol majors now control over half of industrial glucoamylase procurement volume.
Alcohol Enzymes Market Segmentation
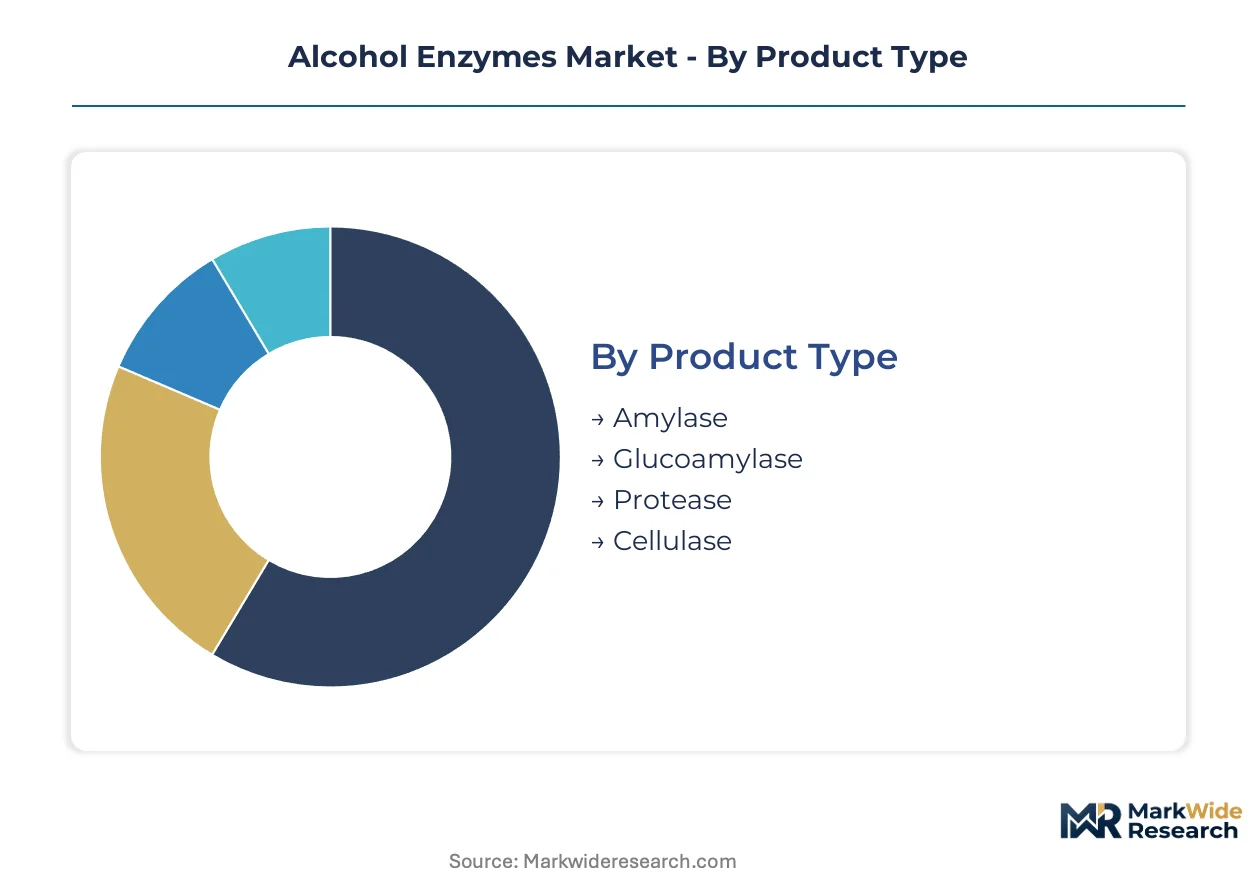
Enzyme procurement patterns diverge sharply across product chemistries and end-use specifications. Distillers prioritize saccharification efficiency while biofuel operators optimize for thermostability under industrial pretreatment conditions.
Product Type:
Replacement cycles vary from quarterly cellulase cocktail refreshes to multi-year glucoamylase supply agreements tied to fermentation train configurations.
- Glucoamylase:Fungal-derived exo-acting hydrolase that cleaves α-1,4 and α-1,6 glycosidic bonds to release glucose monomers from starch dextrins. Fuel ethanol operators in Iowa and Nebraska specify high-temperature variants for simultaneous saccharification and fermentation, though cellulase instability in lignocellulosic streams constrains second-generation adoption.
- Cellulase:Multi-component enzyme system comprising endoglucanases, exoglucanases, and β-glucosidases that depolymerize cellulose into cellobiose and glucose. Brazilian sugarcane bagasse processors and US corn stover pilots drive demand, yet enzyme denaturation under acidic pretreatment conditions limits commercial deployment at scale.
- Amylase:Endo-acting α-amylase randomly hydrolyzes internal starch bonds to reduce viscosity during liquefaction.
- Protease:Peptide bond-cleaving enzymes used for protein haze prevention in brewing and yeast nutrition optimization.
Glucoamylase dominates installed base. Cellulase is where expansion concentrates.
Application:
Margin structures invert between mature beverage contracts and speculative cellulosic biofuel pilots.
- Beverage Production:Brewing and distilling operations deploy enzyme cascades for starch liquefaction, protein stabilization, and flavor precursor liberation. Scottish malt whisky distillers and Kentucky bourbon producers maintain long-term supply relationships with formulation houses, though craft segment fragmentation is opening bespoke blend opportunities.
- Biofuel Production:First-generation corn ethanol relies on glucoamylase-amylase combinations, while second-generation pathways require engineered cellulase cocktails. Chinese state ethanol blending mandates are scaling domestic manufacturing capacity for E10 compliance, redirecting procurement gravity toward indigenous suppliers.
- Food Processing:Sweetener manufacturers and bakery enzyme applications constitute stable demand basins.
- Waste Treatment:Anaerobic digestion facilities utilize hydrolytic enzymes for organic matter solubilization.
Beverage production anchors revenue stability. Biofuel production is gaining share fastest.
End User:
Technical service intensity scales inversely with customer scale—multinational biofuel majors demand embedded application engineering while craft operators purchase spot formulations.
- Biofuel Companies:Vertically integrated ethanol producers negotiate multi-year performance contracts with technical service clauses. US Corn Belt consolidation has concentrated glucoamylase procurement among three majors controlling majority volume, squeezing smaller enzyme houses into specialty niches.
- Beverage Industry:Multinational brewers and heritage distillers split procurement between standardized bulk enzymes and customized heritage grain formulations. India's emerging craft spirits sector is commissioning bespoke blends for indigenous millet varieties.
- Food Manufacturers:Industrial bakeries and sweetener plants constitute price-sensitive volume buyers.
- Environmental Firms:Waste-to-energy operators represent emerging demand with limited specification sophistication.
Biofuel companies command procurement leverage. Beverage industry is where margin expansion concentrates.
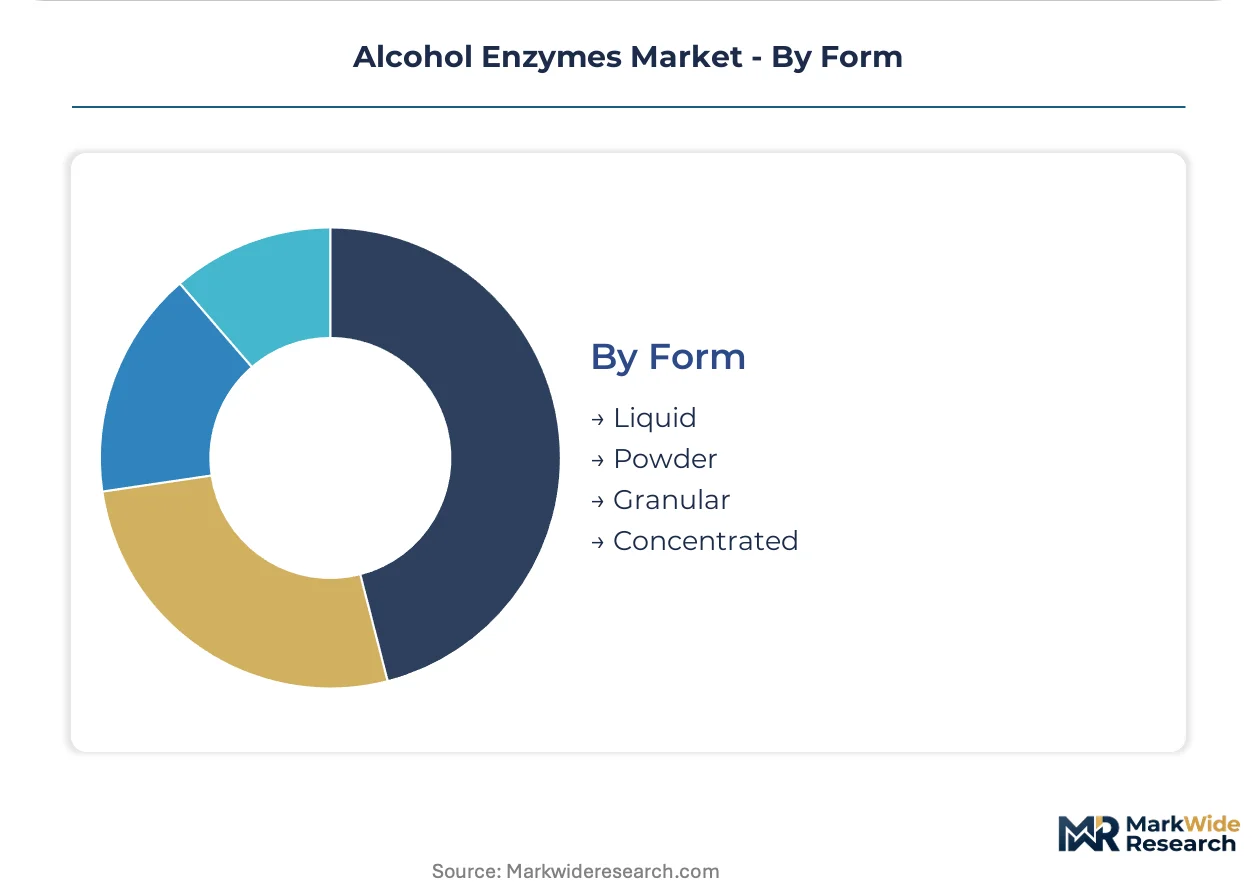
Form:
Logistics economics and dosing precision requirements segment supply formats.
- Liquid:Ready-to-dose aqueous suspensions dominate continuous fermentation operations. Brazilian sugarcane mills and US corn wet mills specify bulk tanker deliveries with automated dosing integration, though cold chain requirements constrain distribution radius.
- Powder:Spray-dried formulations offer shelf stability and reduced shipping costs for remote distilleries. Scottish island whisky producers and Indian pot still operators favor powder for irregular consumption patterns.
- Granular:Free-flowing solid formats suit specific dosing equipment configurations.
- Concentrated:High-activity preparations reduce storage footprint at large-scale facilities.
Liquid formats dominate throughput-intensive installations. Powder is where geographic expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers exhibit the least price sensitivity due to state-backed procurement mandates, while Indian and Brazilian operators negotiate aggressively on enzyme formulations. European purchasers prioritize sustainability certification premiums over unit cost.
United States
The EPA's Renewable Fuel Standard compliance deadlines drive enzyme procurement upgrades across Iowa and Nebraska ethanol corridors. Corn wet mills in the US Midwest negotiate multi-year glucoamylase contracts with embedded technical service clauses. The concentration of fuel ethanol capacity around Council Bluffs and Decatur creates localized demand clusters for thermostable enzyme variants.
China
State-mandated E10 ethanol blending programs scale domestic manufacturing capacity for starch-to-ethanol biocatalysts. GB standards for food-grade enzymes and industrial biocatalysts filter subscale suppliers from import markets. Yangtze River Delta fermentation clusters near Shanghai are expanding cellulosic enzyme pilot production for agricultural residue conversion.
Brazil
Sugarcane bagasse processors drive cellulase demand for second-generation ethanol pathways, though enzyme denaturation under acidic pretreatment constrains deployment. ANVISA and environmental agency regulations govern industrial biocatalyst imports. São Paulo state ethanol majors consolidate procurement leverage through multi-year performance contracts with sustainability verification requirements.
India
The 20% ethanol blending target by 2025 under the Ethanol Blended Petrol program creates import substitution opportunities for localized enzyme production. BIS standards for industrial enzymes impose purity specifications that challenge subscale domestic formulators. Maharashtra and Karnataka distilleries are commissioning bespoke enzyme blends for indigenous millet and sorghum varieties in emerging craft spirits segments.
Germany
The EU's revised Renewable Energy Directive RED III imposes stricter sustainability certification on enzyme inputs for biofuel compliance. ECHA and EFSA frameworks govern food enzyme approvals and industrial biocatalyst registrations. Bavarian brewing clusters and Rhineland biofuel pilot plants anchor demand for certified low-carbon-intensity enzyme formulations.
Alcohol Enzymes Market Key Industry Players
Capability concentration sits with specialized fermentation houses; scale advantage sits with diversified biotechnology platforms. The vendor base organizes into three tiers: integrated multinational suppliers with captive strain libraries, mid-cap regional formulators with application engineering depth, and niche specialists serving craft beverage segments. Dominant competitive moves include backward integration into genetically modified microbial production and multi-year performance contracting with embedded technical service obligations.
Among Danish and Dutch fermentation specialists, Novozymes A/S and Koninklijke DSM N.V. exemplify the integrated platform archetype with heritage scale-up expertise. BASF SE anchors the chemical conglomerate tier with upstream control over Trichoderma reesei production. DuPont de Nemours, Inc. represents the diversified materials science approach to enzyme platform development. These three occupy positions that smaller regional formulators struggle to replicate without equivalent fermentation infrastructure investment.
| Leading Market Players |
|---|
| Novozymes A/S |
| DuPont de Nemours, Inc. |
| BASF SE |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies Ltd. |
| Associated British Foods Plc |
| Kerry Group Plc |
| Koninklijke DSM N.V. |
| Ajinomoto Co., Inc. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Danish and Dutch microbial strain libraries compresses pricing tier spreads while forcing buyers into long-term offtake commitments that lock in supply chain topology. Corn starch price volatility transmits directly into enzyme formulation costs, squeezing margin predictability for regional formulators and accelerating consolidation around integrated fermentation platforms with captive upstream control.
Pricing Analysis
Technical service bundling drives lifetime value in enzyme supply relationships, with multi-year performance contracts embedding application engineering support commanding premium positioning over spot bulk sales. Pricing stratifies across performance tiers—thermostable variants for continuous corn wet mills, standard grades for batch distilleries, and economy formulations for price-sensitive food processors—with differentiation anchored in certification grade (FDA GRAS, EU food enzyme approvals, China GB standards) and volume scale. Cost compression in standard-grade glucoamylase intensifies as Chinese domestic manufacturers scale E10-mandated capacity, while pricing stability persists in cellulase cocktails where thermostability under acidic pretreatment remains technically constrained. Biofuel majors exhibit least price sensitivity due to Renewable Fuel Standard compliance premiums; craft distillers negotiate most aggressively on per-kilogram basis.
Supply Chain Analysis
Contract-manufacturing concentration sits with Novozymes A/S and Koninklijke DSM N.V. in Denmark and the Netherlands, where heritage fermentation infrastructure and CRISPR-edited strain libraries create capacity bottlenecks for high-performance biocatalysts. Supply draws from China, Denmark, and the Netherlands for finished enzyme formulations, with genetically modified Trichoderma reesei and Aspergillus niger production tethered to temperate-climate fermentation clusters. Raw material dependencies center on corn starch substrates, agricultural residue feedstocks for cellulase induction, and specialized nitrogen sources for microbial cultivation. Single-source vulnerability concentrates in glucoamylase strains controlled by two integrated platforms, creating procurement chokepoints for US Corn Belt ethanol operators. Distribution runs through bulk tanker networks for liquid formats serving continuous operations, with powder formulations reaching remote distilleries via regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
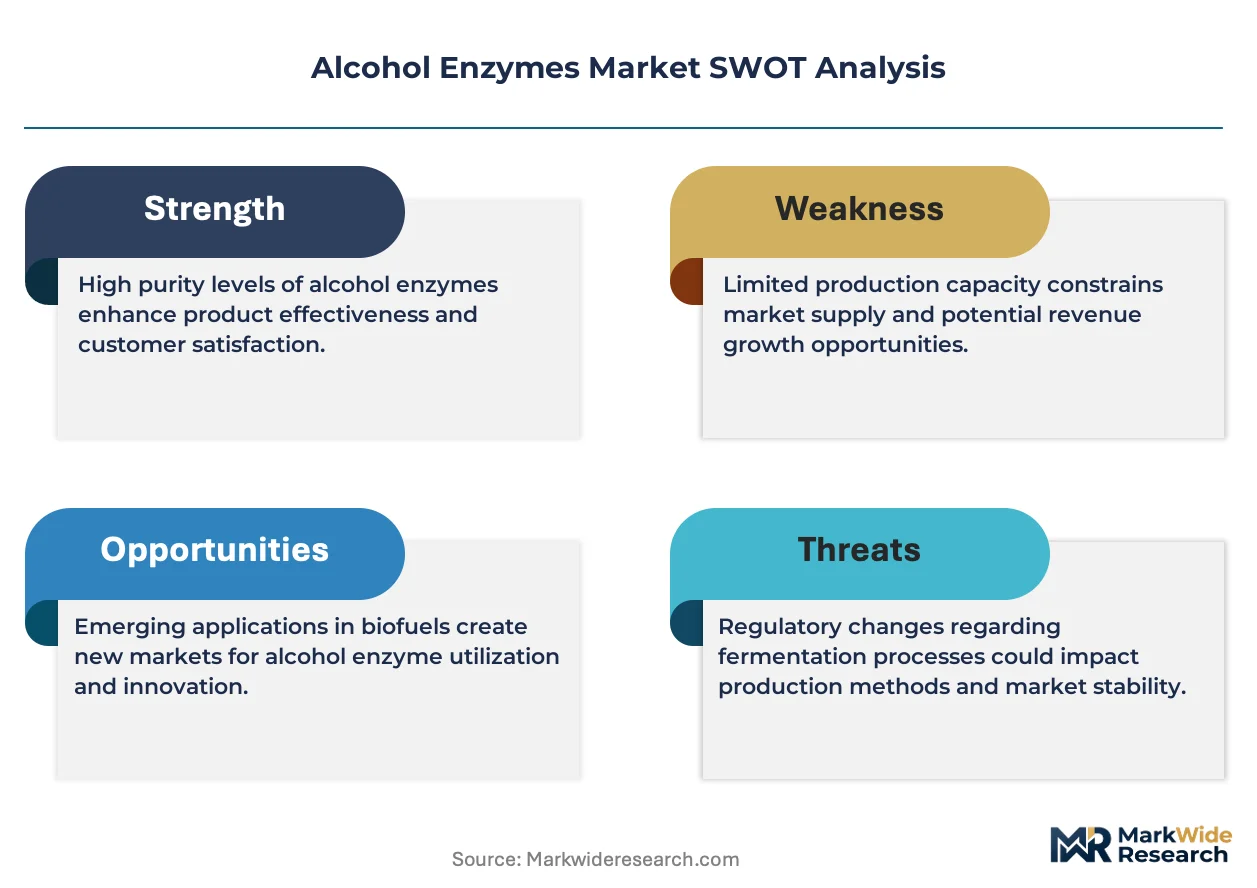
The alcohol enzymes market rewards simultaneous mastery of CRISPR genome editing and thousand-liter bioreactor scale-up, a capability intersection that remains scarce and concentrates competitive advantage among integrated fermentation platforms with decades of strain optimization heritage.
For Market Incumbents: Pre-empt displacement by CRISPR-native biotechnology platforms through captive investment in consolidated bioprocessing strains that merge upstream and downstream steps. Lock in Corn Belt ethanol majors with embedded technical service teams and multi-year performance guarantees that raise switching costs. Accelerate backward integration into agricultural residue supply chains to secure cellulase feedstock independence ahead of second-generation bioethanol commercialization. For New Entrants and Emerging Players: Pursue white-space opportunities in India's craft spirits sector, where bespoke enzyme blends for indigenous millet and sorghum varieties command formulation premiums and established players lack localized application engineering presence. Target Maharashtra and Karnataka distillery clusters with heritage-grain customization services that multinational houses cannot economically replicate. Lead with rapid-turnaround blend development and technical support responsiveness rather than competing on bulk glucoamylase scale. For Investors and Strategic Acquirers: EPA Renewable Fuel Standard compliance deadlines reshape the acquisition landscape by concentrating procurement leverage among ethanol majors and forcing smaller formulators into distress. Long-term viability favors platforms with demonstrated CRISPR strain development velocity and established multi-jurisdiction regulatory dossiers. Acquisition target archetype: mid-cap regional formulators with application engineering depth in underserved geographies but lacking fermentation scale-up infrastructure. Signal to watch: Chinese state ethanol blending mandate acceleration triggering domestic capacity overbuild and export price pressure on global spot markets.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Development Investment | Compresses development timelines from years to months, enabling rapid response to cellulosic ethanol process requirements. |
| Multi-Jurisdiction Regulatory Dossier Expansion | Simultaneous FDA GRAS, EFSA food enzyme, and China GB approvals extend addressable market and raise competitive barriers. |
| Backward Integration into Feedstock Supply | Captive agricultural residue sourcing secures cellulase production economics and insulates against corn starch price volatility. |
| Embedded Technical Service Team Deployment | Application engineering presence at major ethanol facilities locks in multi-year contracts and displaces spot purchasing. |
| Consolidated Bioprocessing Strain Commercialization | Single-fermentation multi-enzyme cocktails reduce capital intensity for greenfield cellulosic ethanol plants. |
Research Approach
A standing panel of fermentation process engineers, biofuel procurement directors, craft distillery operations managers, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA Renewable Fuel Standard filings, EU ECHA biocatalyst registration databases, China GB standards documentation, and SEC 10-K disclosures from listed enzyme manufacturers. Bottom-up volume modeling triangulated against top-down market sizing derived from corn wet mill capacity utilization and ethanol blending mandate trajectories.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning enzyme product chemistry (glucoamylase, cellulase, amylase, protease), application end-use (beverage production, biofuel production, food processing), and geographic regulatory cluster (US EPA compliance, EU RED III certification, China E10 mandate, India EBP program). CAGRs emerged from iterative reconciliation of installed base replacement cycles, greenfield capacity buildout schedules, and technology adoption S-curves for cellulosic ethanol pathways. Industry-specific inputs included lignocellulosic pretreatment method maturation timelines and CRISPR strain development velocity benchmarks.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, biofuel policy stringency, or carbon-border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding cellulosic ethanol commercialization pace and Chinese domestic manufacturing scale-up. Quarterly review of EPA compliance deadline adjustments, EU delegated act sustainability criteria revisions, and Chinese state procurement tender volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Craft Beer Market