
 UK Tequila Market | 2026-2036
UK Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
UK Tequila Market Insights
A capital-intensity divergence between craft distillers and mass-market bottlers is unwinding competitive stability across the UK Tequila Market. José Cuervo leverages its established distribution network to secure shelf dominance in major supermarket chains. Fortaleza differentiates through small-batch heritage production that commands premium positioning in specialist retailers.
Tequila is a distilled spirit produced exclusively from the fermented sugars of the blue weber agave plant, with Blanco bottled immediately after distillation while Reposado and Añejo undergo oak barrel aging from two months to three years. The spirit serves as both a sipping category and a cocktail base for commercial bars and home mixologists. Blanco and Reposado lead volume flows through On-Trade and Off-Trade channels, while Cristalino anchors margin pools as the fastest-growing premium sub-category. E-Commerce and Duty-Free sales channels are expanding fastest as direct-to-consumer platforms reshape how Premium Buyers and Millennials access limited releases.
HMRC administers alcohol duty and labeling compliance, while Trading Standards enforces product authenticity and origin claims under UK-EU trade provisions. These frameworks determine import cost structures, bottle labeling requirements, and market access conditions for Mexican-origin producers. Stakeholders must monitor potential tariff adjustments and evolving duty stamp obligations as the UK refines its post-Brexit alcohol taxation regime.
Market Dynamics
HMRC alcohol duty reforms are compressing import margins while premium cocktail bars in London, Manchester and Edinburgh accelerate agave-based menu expansion. This dual pressure is restructuring competitive positioning between mass-market distributors and heritage craft bottlers.
Growth Catalysts
- On-Trade sophistication:Premium cocktail bars in Edinburgh and Manchester are expanding dedicated agave programs. Bartender education investments elevate consumer appreciation for terroir-driven expressions.
- E-Commerce platform maturation:Direct-to-consumer channels bypass traditional wholesale markups. Millennial buyers access limited releases previously restricted to specialist retailers.
- UK-EU Trade and Cooperation Agreement:Rules-of-origin provisions stabilize Mexican import access. Producers secure predictable cost structures for Blanco and Reposado shipments.
Market Restraints
- Agave input concentration:Jalisco highlands supply 85% of premium blue weber cultivation. Weather volatility and harvest cycles create raw material price swings.
- HMRC duty stamp obligations:Post-Brexit labeling requirements add compliance layers. Smaller importers face disproportionate administrative burden relative to volume.
- Substitute spirit competition:English gin and premium rum capture overlapping occasion spend. Category switching costs remain low for casual consumers.
Strategic Opportunities
- Cristalino sub-category expansion:Filtered aged expressions command premium positioning without traditional Añejo price points. Specialist retailers in Greater London report strongest velocity.
- Duty-Free channel development:Heathrow and Manchester Airport concessions target international travelers. Limited editions drive margin capture absent domestic duty exposure.
- Home mixology kit bundling:Off-Trade retailers pair Blanco with bar tools and recipe cards. This convergence of spirits retail and experiential consumption builds basket value.
Industry Challenges
- Certification timeline compression:Trading Standards authenticity enforcement demands accelerated documentation. Import batches face extended clearance periods during peak seasonal windows.
- Talent scarcity in agave sourcing:UK-based buyers lack deep relationships with Jalisco distillers. Relationship-building travel costs burden emerging brand portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Tequila Market |
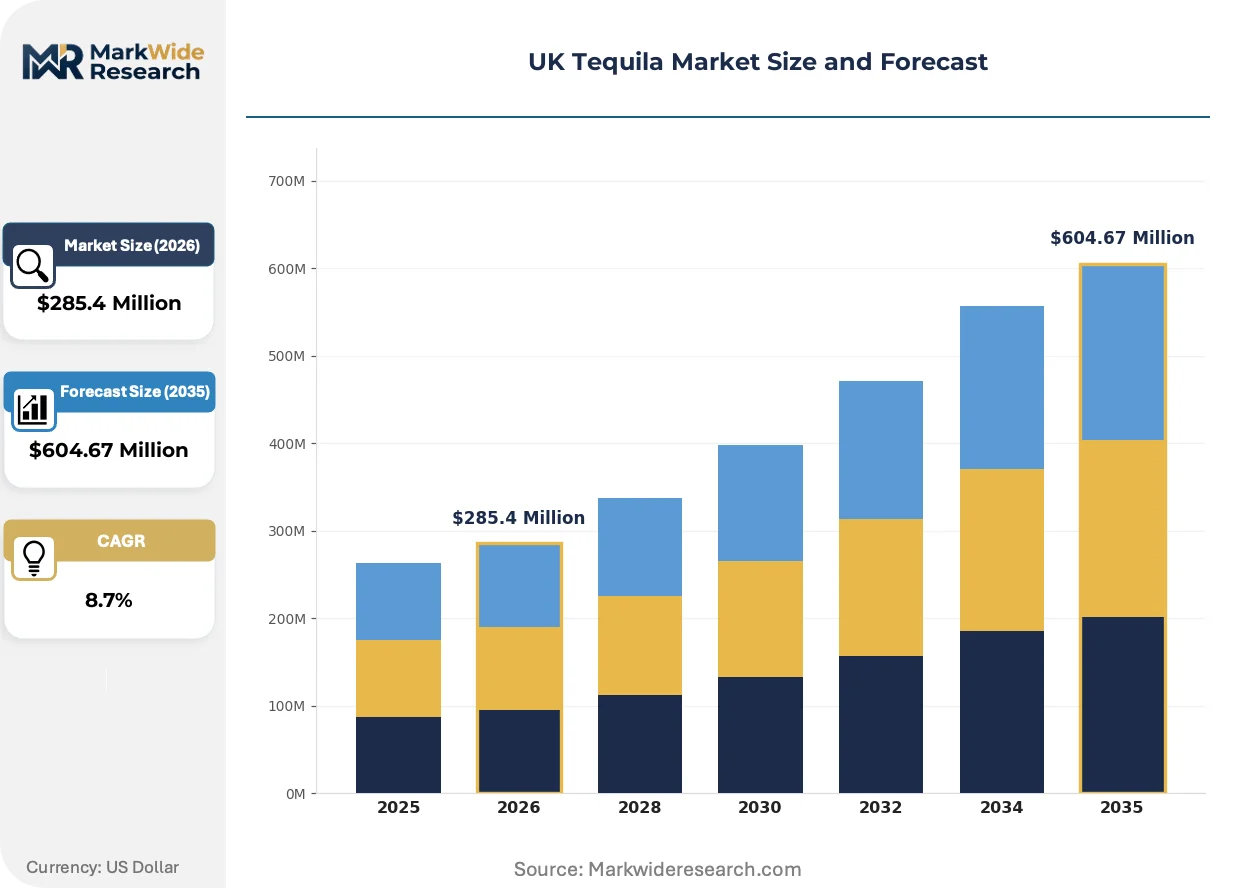
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo, Cristalino Packaging Type: Bottle, Can, Boxed Set, Miniature, Gift Pack Sales Channel: On-Trade, Off-Trade, E-Commerce, Duty-Free Consumer Segment: Millennials, Generation X, Baby Boomers, Premium Buyers, Occasional Drinkers |
| Companies Covered | Don Julio, Ocho Tequila, El Jimador, Don Londres, Fortaleza, José Cuervo, Sauza, LALO, Patrón, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Tequila Market Trends and Innovations
Three forces are restructuring how tequila reaches UK consumers: production technology evolution, post-Brexit regulatory recalibration, and channel behavior transformation among younger demographics.
Additive-free production methods are displacing conventional flavoring and coloring practices in premium positioning. Specialist retailers in Shoreditch and Notting Hill now stock expressions certified by independent laboratory analysis. This transparency standard is compressing margins for legacy brands dependent on glycerin and caramel additives.
HMRC's revised alcohol duty structure imposes tiered taxation based on ABV thresholds. High-strength expressions above 40% ABV face steeper duty increments. Premium producers are responding with cask-strength releases positioned for connoisseur segments willing to absorb tax passthrough.
Subscription-based spirits discovery services are fragmenting traditional Off-Trade loyalty. Millennials in Bristol and Brighton receive curated monthly selections bypassing supermarket shelves. This channel shift is most visible among collectors seeking limited-batch Reposado and extra-Añejo expressions unavailable through conventional retail.
UK Tequila Market Segmentation
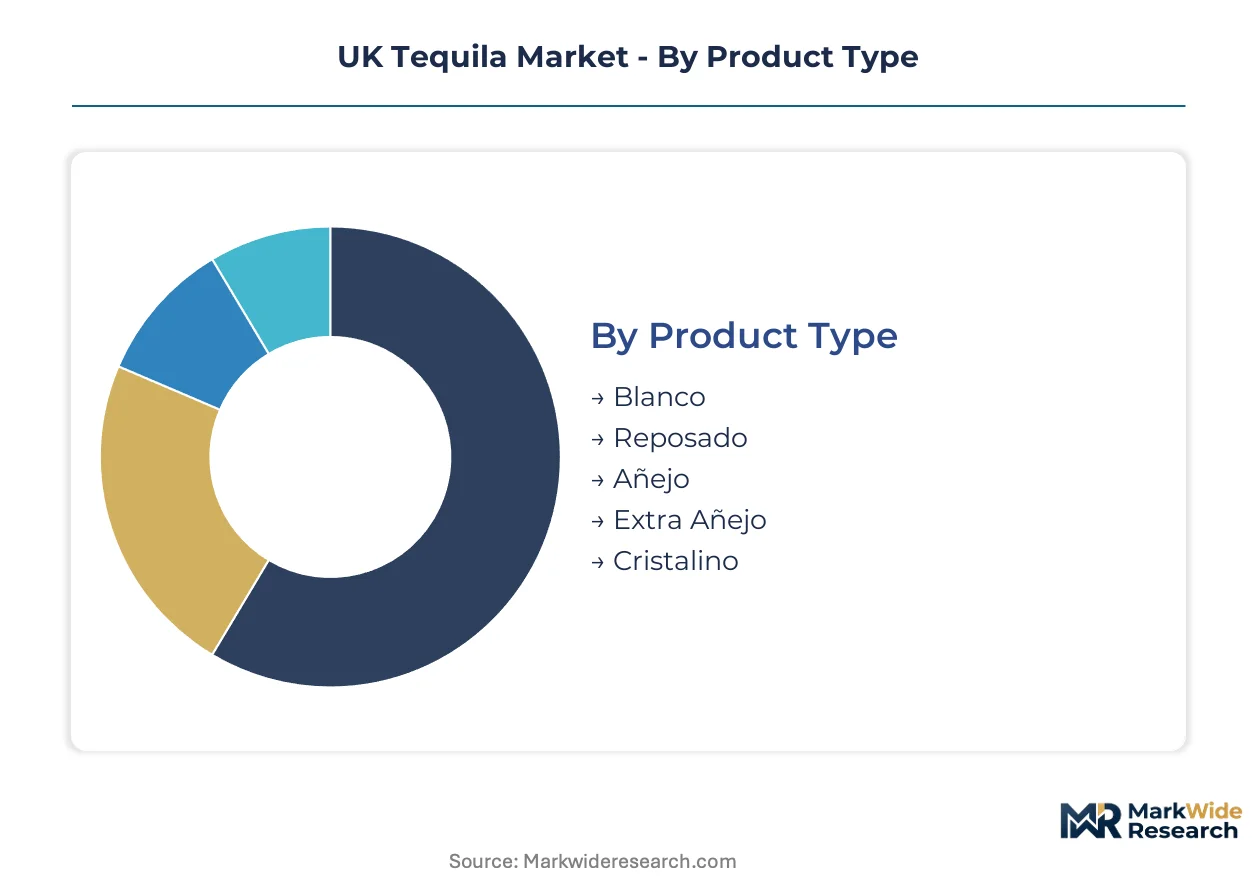
Segmentation in the UK Tequila Market reveals how premiumization pressures and channel fragmentation create divergent margin architectures. Distinct consumer cohorts and sales pathways demand tailored positioning strategies from importers and distributors.
Product Type:
Margin pools concentrate in aged expressions where oak maturation justifies price premiums, though unaged variants drive volume velocity through cocktail applications.
- Blanco:Bottled immediately post-distillation without oak contact, preserving raw agave character and peppery brightness. Greater London bars deploy Blanco as the foundation for Paloma and Margarita programs, with bartender education investments elevating terroir awareness among Millennial patrons.
- Reposado:Aged two to twelve months in oak barrels, developing vanilla and caramel notes while retaining agave backbone. Manchester and Edinburgh premium cocktail bars feature Reposado in sipping flights, with heritage craft bottlers commanding shelf space through small-batch provenance storytelling.
- Añejo:One to three years of oak maturation produces complex, whiskey-like profiles for connoisseur segments.
- Extra Añejo:Extended aging beyond three years creates ultra-premium positioning for collector markets.
- Cristalino:Filtered aged expressions that remove color while preserving barrel-derived complexity, bridging Añejo depth with Blanco versatility.
Blanco holds installed capacity. Cristalino is rotating up the share rankings.
Packaging Type:
Packaging cost tiers separate mass-market accessibility from gift-oriented premium capture, with format innovation reshaping Off-Trade basket economics.
- Bottle:Standard 700ml glass remains the volume backbone across supermarket and specialist retail. Bristol and Brighton Millennials gravitate toward embossed, hand-numbered bottles that signal craft authenticity and justify price premiums over private-label alternatives.
- Gift Pack:Bundled presentations with glassware or cocktail tools command seasonal velocity peaks. Heathrow Airport concessions target international travelers with limited-edition gift sets, capturing margin pools absent domestic HMRC duty exposure.
- Can:Single-serve ready-to-drink formats expand occasion accessibility for casual consumption.
- Boxed Set:Multi-bottle collections enable vertical tasting experiences for enthusiast segments.
- Miniature:50ml formats support trial and travel retail sampling programs.
Bottle formats dominate procurement volumes. Gift Pack configurations are climbing the fastest.
Sales Channel:
Channel behavior transformation among younger demographics is fragmenting traditional wholesale loyalty, with direct access platforms capturing margin previously absorbed by intermediaries.
- On-Trade:Licensed premises including bars, restaurants, and hotels where consumption occurs on-site. Premium cocktail bars in Shoreditch and Notting Hill expand dedicated agave programs, with bartender investments in Jalisco terroir education converting casual drinkers to sipping occasions.
- E-Commerce:Direct-to-consumer platforms bypass traditional wholesale markups and expand geographic reach. Subscription services in Greater London deliver curated Reposado selections to Millennial collectors seeking limited releases unavailable through conventional retail.
- Off-Trade:Supermarkets and specialist retailers where consumption occurs off-premises.
- Duty-Free:Airport and port concessions targeting international travelers with tax-advantaged pricing.
On-Trade maintains established throughput. E-Commerce is expanding most quickly.
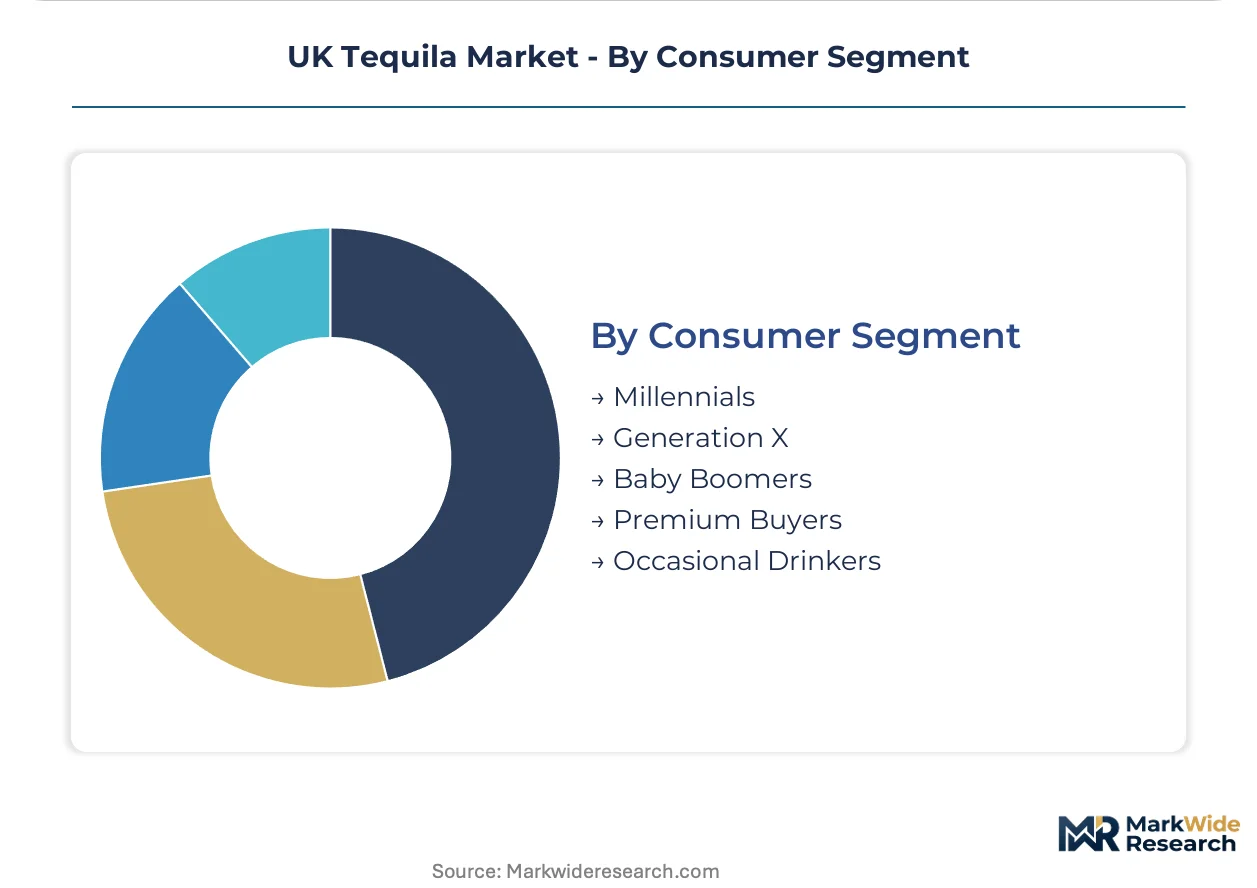
Consumer Segment:
Generational cohorts exhibit divergent occasion patterns and price elasticity, with premium buyers demonstrating insensitivity to HMRC duty passthrough.
- Millennials:Urban drinkers aged 27-42 driving craft discovery and cocktail experimentation. Edinburgh and Manchester Millennials access additive-free expressions through specialist retailers, with transparency certification displacing legacy brands dependent on glycerin and caramel coloring.
- Premium Buyers:Connoisseur segments prioritizing provenance, limited production, and sensory complexity over price. Greater London collectors absorb cask-strength price premiums despite steeper HMRC duty increments on high-ABV expressions above 40%.
- Generation X:Established drinkers with stable brand loyalties and occasion-based purchasing.
- Baby Boomers:Traditionalist segments favoring recognized heritage brands and standard expressions.
- Occasional Drinkers:Infrequent purchasers with low category engagement and high substitution elasticity.
Millennials anchor volume growth. Premium Buyers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows into the UK concentrate through London and Manchester distribution hubs, with HMRC duty structures determining landed cost advantages across regional markets. Consumer sophistication varies sharply between metropolitan cocktail corridors and provincial retail catchments.
Greater London
Shoreditch and Notting Hill cocktail bars drive additive-free tequila discovery among Millennial patrons. Trading Standards enforces origin claims under UK-EU trade provisions. Specialist retailers in Camden and Hackney stock laboratory-certified expressions displacing glycerin-dependent legacy brands.
Scotland
Edinburgh's premium bar scene expands dedicated agave programs with terroir-focused bartender education. HMRC alcohol duty reforms compress margins for high-ABV cask-strength releases. Glasgow off-trade channels report rising Cristalino velocity among collector segments.
North England
Manchester anchors northern distribution with expanding premium cocktail infrastructure. Post-Brexit labeling requirements add compliance layers for smaller importers. Leeds and Liverpool specialist retailers feature heritage craft bottlers with small-batch provenance storytelling.
Southwest England
Bristol and Brighton Millennials access subscription-based discovery services bypassing supermarket shelves. HMRC duty stamp obligations create administrative burden for emerging brand portfolios. Bath specialist retailers target weekend visitors with gift-pack configurations.
Wales
Cardiff cocktail bars lag London sophistication but show accelerating agave menu expansion. UK-EU rules-of-origin provisions stabilize Mexican import access for regional distributors. Newport off-trade channels rely on supermarket chains for standard Blanco and Reposado availability.
UK Tequila Market Competitive Landscape
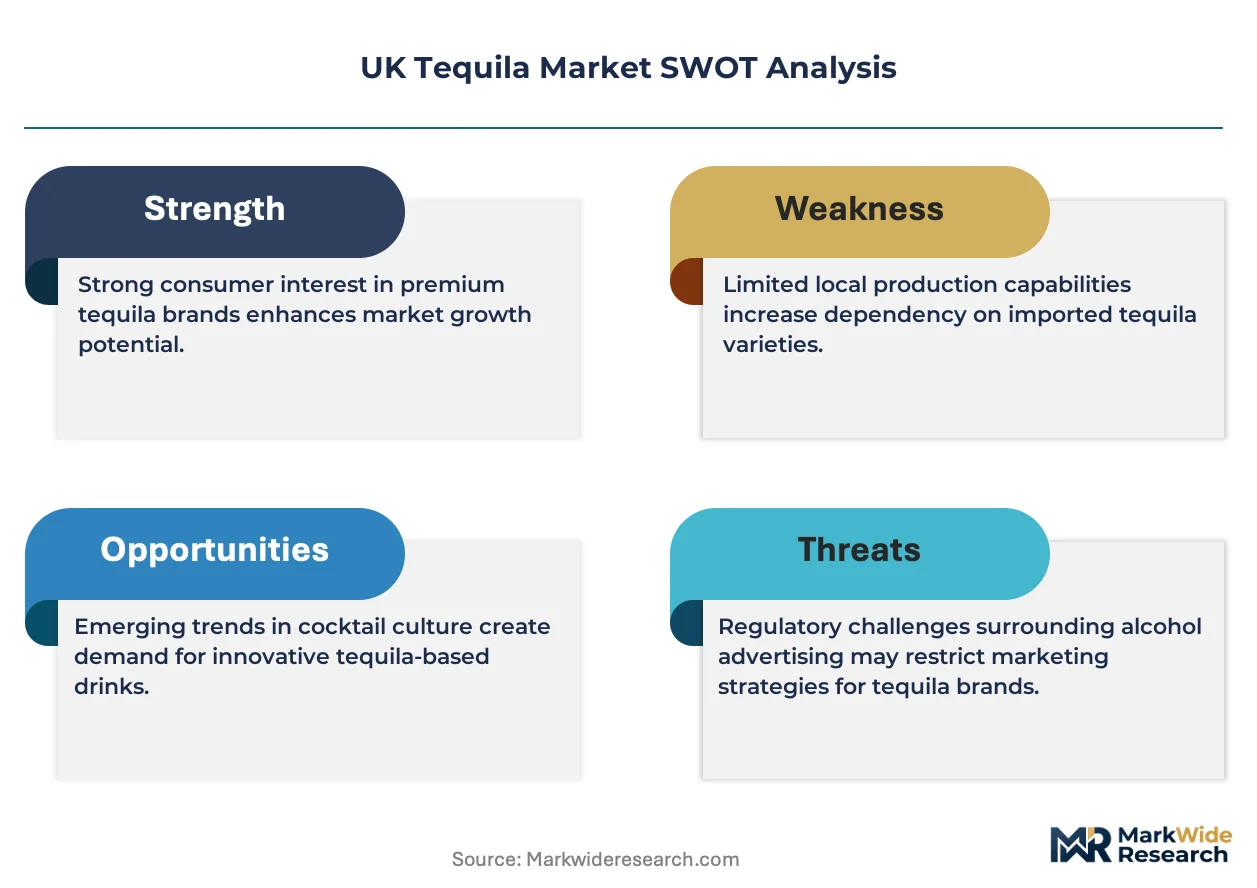
Concentration sits with heritage craft bottlers and mass-market distributors operating in parallel tiers. The UK market exhibits bifurcated structure: supermarket chains favor established volume players with shelf dominance, while specialist retailers cultivate limited-release relationships with Jalisco-based producers. Two strategic archetypes define competitive positioning — scale-driven distributors leveraging logistics networks, and provenance-focused specialists commanding premium through additive-free certification. Dominant competitive moves include portfolio diversification across aged expressions and direct-to-consumer channel development bypassing wholesale markups.
Within the heritage craft tier, Fortaleza and Ocho Tequila exemplify small-batch production archetypes with Jalisco highlands sourcing. Among mass-market distributors, José Cuervo occupies a position representing established shelf presence in major supermarket chains. Don Julio sits within the premium standard tier, bridging accessibility and connoisseur positioning through consistent aged expression availability.
| Leading Market Players |
|---|
| Don Julio |
| Ocho Tequila |
| El Jimador |
| Don Londres |
| Fortaleza |
| José Cuervo |
| Sauza |
| LALO |
| Patrón |
| Others |
Pricing and Supply Chain Analysis
Ninety-day agave harvest-to-distillation cycles in Jalisco highlands tether UK landed costs to seasonal raw material availability, compressing margin buffers for importers while amplifying pricing power for vertically integrated heritage producers with captive cultivation.
Pricing Analysis
The customization-premium spread between standard supermarket Blanco and hand-numbered, additive-certified expressions spans three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with additive-free laboratory verification commanding specialist retailer premiums. Pricing pressure stems from HMRC duty stamp obligations disproportionately burdening smaller import portfolios. Casual consumers in provincial Off-Trade channels exhibit highest price sensitivity, while Premium Buyers in Greater London absorb cask-strength tax passthrough without volume elasticity.
Supply Chain Analysis
Jalisco highlands agave concentration creates single-source vulnerability for UK import flows, with 85% of premium blue weber cultivation resting on Mexican terroir. Blue weber agave hearts, oak barrels for aging, and glass bottle packaging constitute critical input dependencies. Tariff exposure under UK-EU Trade and Cooperation Agreement rules-of-origin provisions threatens cost structure predictability. Distribution runs through London and Manchester bonded warehousing hubs before fragmenting to specialist retailers and supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
English gin and premium rum substitution threats intensify as HMRC duty reforms compress tequila import margins, forcing incumbents to defend occasion-based consumption through experiential differentiation rather than price competition.
For Market Incumbents: Compound bartender education investments in Edinburgh and Manchester to deepen On-Trade loyalty against substitute spirit encroachment. Secure additive-free certification for core expressions to displace glycerin-dependent legacy competitors. Build backward integration into Jalisco highlands agave sourcing to insulate against harvest volatility and raw material price swings. For New Entrants and Emerging Players: Differentiate on transparency certification and small-batch provenance storytelling to capture Bristol and Brighton Millennial subscribers bypassing supermarket shelves. Target Cristalino sub-category white space where filtered aged expressions bridge Añejo complexity with Blanco versatility. Deploy direct-to-consumer platform launches with curated discovery services to circumvent established wholesale markups. For Investors and Strategic Acquirers: Long-term, this sits as a premiumization play because additive-free craft bottlers command durable margin expansion as transparency standards displace conventional flavoring practices. Acquisition targets should exhibit Jalisco highlands sourcing relationships and laboratory-certified production methods. Watch HMRC duty structure recalibration as the inflection signal determining import cost trajectory and portfolio viability.| Strategic Initiative | Industry Significance |
|---|---|
| Additive-Free Certification Investment | Trading Standards enforcement and consumer transparency demands displace glycerin-dependent legacy brands from specialist retail. |
| Direct-to-Consumer Platform Launch | Subscription services in Greater London and Bristol bypass wholesale markups while capturing Millennial collector loyalty. |
| Jalisco Highlands Sourcing Partnership | Cultivation relationships in Mexico's premium agave terroir secure raw material priority during harvest cycle constraints. |
| Bartender Education Program Expansion | Edinburgh and Manchester agave-focused training converts cocktail consumers to sipping occasions with higher per-occasion spend. |
| Cristalino Sub-Category Development | Filtered aged expressions capture margin pools between Reposado accessibility and Añejo connoisseur positioning. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with spirits importers, specialist retail buyers, HMRC compliance officers, and premium cocktail bar operators; and secondary validation through customs import records, HMRC duty guidance publications, and UK-EU Trade and Cooperation Agreement documentation. Bottom-up volume triangulation across product type and channel segments converged with top-down market sizing from trade flow analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, packaging configuration, sales channel, and consumer generational cohort. CAGRs were derived from trend extrapolation calibrated to observed velocity patterns in Greater London and Manchester distribution hubs. Agave harvest cycle dynamics and HMRC duty structure evolution served as industry-specific forecast sensitivity inputs.
Material uncertainties — agave price volatility, tariff renegotiation outcomes, and Trading Standards enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding consumer premiumization trajectory and channel shift momentum. Practitioners should keep alternative scenarios live as post-Brexit alcohol taxation regime refinements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market