
 Brewery Heat Exchanger Market | 2026-2036
Brewery Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Brewery Heat Exchanger Market Outlook
Germany's brewery equipment manufacturing base is fragmenting as regional fabricators compete with multinational suppliers for craft brewing contracts. Alfa Laval leverages its plate heat exchanger portfolio to dominate European wort cooling retrofits. Paul Mueller Company anchors North American demand through stainless steel fabrication scale. GEA Group differentiates with integrated pasteurization lines that bundle thermal processing equipment.
A brewery heat exchanger is a thermal transfer device engineered from corrugated stainless steel plates or tubular alloys, designed to regulate fluid temperatures within brewing processes while maintaining sanitary surface finishes rated for CIP protocols. Its primary commercial purpose centers on rapid wort cooling, yeast propagation temperature control, and energy recovery from hot water streams. Plate configurations command the largest installed base across craft and large-scale breweries due to compact footprint and modularity, while titanium-clad variants capture premium margin pools in high-chloride water regions. Shell-and-tube designs sustain demand among legacy lager producers running continuous pasteurization cycles.
The EU F-Gas Regulation and REACH chemical compliance frameworks mandate refrigerant phase-downs and material traceability in thermal equipment sold across member states, forcing OEM redesign cycles. The US FDA and EPA jointly govern sanitary surface standards and effluent thermal discharge limits for brewery process water. Stakeholders must monitor evolving refrigerant classifications and material certification requirements as regulatory thresholds tighten without grandfathering existing installed units.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant-dependent cooling systems toward thermal recovery architectures, compressing OEM redesign cycles and reshaping procurement specifications across European craft brewing clusters.
Growth Catalysts
- Refrigerant Phase-Down Mandates:The EU F-Gas Regulation mandates hydrofluorocarbon reduction timelines, accelerating brewery investment in ammonia-based and glycol-free cooling loops that rely on advanced plate heat exchanger configurations.
- Craft Brewery Expansion:São Paulo state's craft beer corridor is scaling production capacity, driving wort cooling equipment demand from regional fabricators serving mid-scale lager operations.
- Energy Recovery Systems:Hot water stream recapture technology is hybridizing with traditional cooling circuits, enabling breweries to offset thermal loads through integrated heat exchanger networks.
Market Restraints
- Stainless Steel Price Volatility:Grade 316L sheet metal input costs fluctuate with nickel commodity markets, squeezing fabrication margins for European and North American equipment suppliers.
- Specialized Welding Labor Scarcity:Orbital welding certification for sanitary tubing joints is concentrating in German and Danish technical institutes, creating regional supply bottlenecks for high-purity heat exchanger assembly.
- Legacy Pasteurization Infrastructure:Continuous-flow shell-and-tube systems in mature lager facilities create substitution friction against compact plate-based retrofits due to integrated line dependencies.
Strategic Opportunities
- Brazilian Craft Corridor Penetration:Minas Gerais and Rio Grande do Sul states outside São Paulo's core cluster present underdeveloped demand for modular wort cooling capacity among emerging microbreweries.
- REACH Material Traceability:Compliance documentation requirements for stainless steel alloy sourcing are creating certification-based differentiation opportunities for suppliers with integrated metallurgical auditing systems.
- Water-Stressed Regions:Titanium-clad plate configurations are capturing premium positioning in high-chloride groundwater zones across coastal India and the Middle East where standard 316L suffers pitting corrosion.
Industry Challenges
- Sanitary Welding Certification Timelines:ASME BPE and 3-A SSI qualification periods for automated orbital welding procedures extend equipment delivery schedules by 8-14 weeks, compressing project windows for seasonal brewery expansions.
- Legacy Control System Integration:Proprietary SCADA architectures in existing brewhouses require custom protocol bridges to interface with modern heat exchanger monitoring sensors, inflating commissioning costs and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewery Heat Exchanger Market |
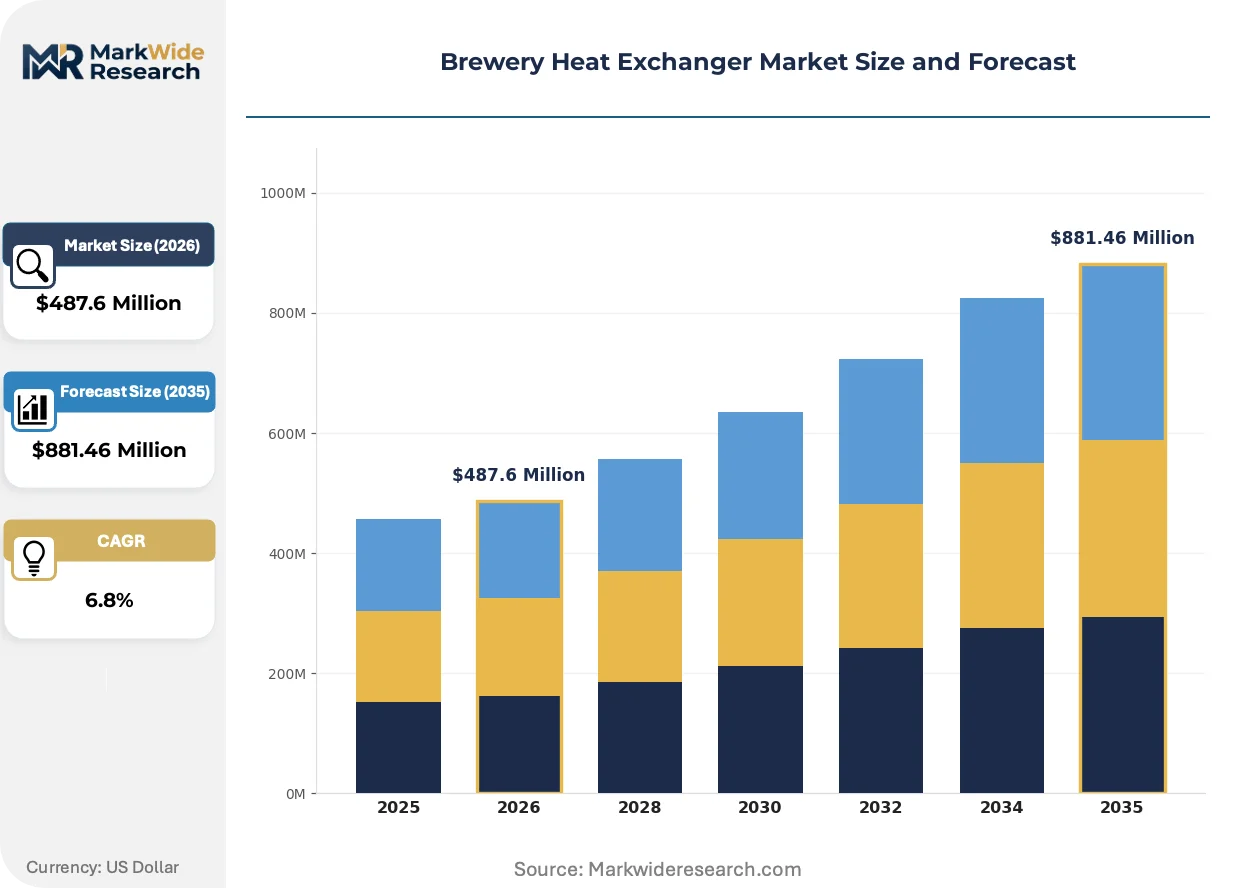
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Plate, Shell-and-Tube, Air-Cooled, Double-Pipe Material: Stainless Steel, Copper, Aluminum, Titanium Application: Wort Cooling, Yeast Management, Hot Water Recirculation, Pasteurization End User: Craft Breweries, Large Scale Breweries, Microbreweries, Cidery |
| Companies Covered | WCR Incorporated, Paul Mueller Company, Alfa Laval, Praj Industries Ltd., HGMC, GEA Group, Koch Engineered Solutions, HRS Process Systems, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewery Heat Exchanger Market Strategic Shifts
Equipment architectures are converging around thermal efficiency metrics and refrigerant-independent designs, compressing the traditional separation between wort cooling and energy recovery functions.
Compact plate-and-frame configurations with laser-welded cassette designs are hybridizing with shell-and-tube durability standards, enabling craft breweries to access industrial-grade thermal performance without footprint penalties. Mid-scale lager producers across Bavaria and Bohemia are adopting these hybrid systems at accelerated replacement cycles. The technology is compressing the historical tiering between premium European fabricators and regional equipment suppliers.
The EU F-Gas Regulation's refrigerant quota allocation mechanism is redirecting capital toward ammonia and CO2 secondary loop architectures that eliminate synthetic refrigerant dependencies entirely. Equipment manufacturers must now engineer for flammable and high-pressure working fluids, altering safety enclosure and materials specifications. German craft breweries operating under strict local environmental ordinances are leading this transition, specifying fully sealed plate heat exchanger circuits with integrated leak detection.
After-sales service unbundling is disrupting traditional bundled maintenance contracts, with craft brewery operators increasingly procuring heat exchanger cleaning and gasket replacement through specialized third-party sanitary service providers rather than OEM channels. This channel fragmentation is compressing spare parts margin pools for original equipment manufacturers while expanding independent service network viability. The shift is most visible in the United States, where regional CIP service companies are capturing recurring revenue streams previously retained by Alfa Laval and Paul Mueller Company field organizations.
Brewery Heat Exchanger Market Segmentation
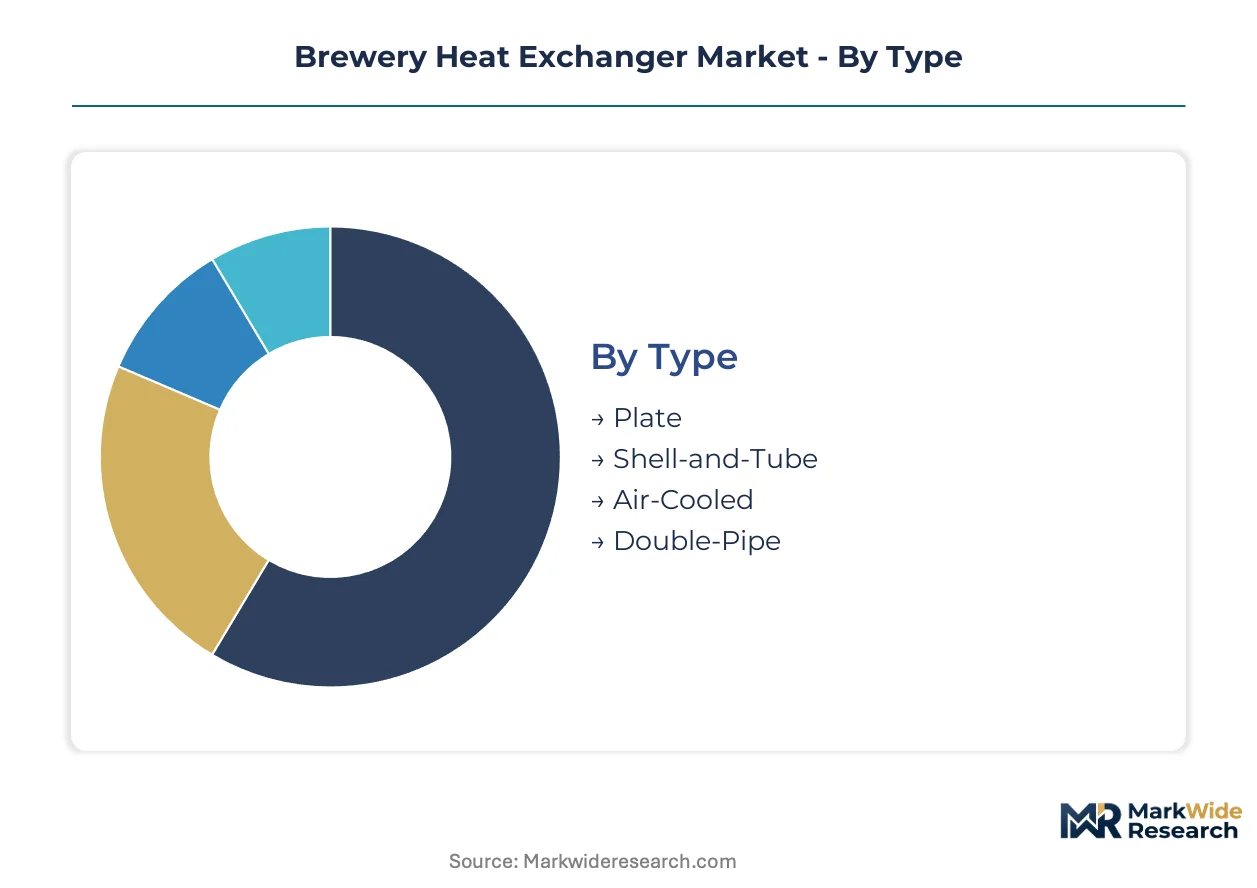
Equipment specification in brewery heat exchangers tracks directly to production scale and thermal load profiles. Material selection and configuration type determine capital allocation patterns across craft and industrial brewing operations.
Type:
Mature plate configurations dominate installed capacity while emerging hybrid architectures reshape procurement specifications.
- Plate:Corrugated stainless steel plates arranged in gasketed or welded cassettes deliver turbulent flow patterns and compact thermal transfer surfaces. Craft breweries across Bavaria and Bohemia specify these for wort cooling retrofits where floor space constraints limit shell-and-tube footprints. Demand concentrates among mid-scale lager producers replacing legacy cooling circuits.
- Shell-and-Tube:Tubular bundles housed within cylindrical pressure vessels withstand continuous pasteurization cycles and high-pressure steam sterilization. Large-scale Brazilian facilities in São Paulo state retain these for integrated production lines where line stoppage costs exceed retrofit savings. The configuration sustains demand through durability specifications in 24-hour brewing operations.
- Air-Cooled:Finned-tube arrays eliminate cooling water dependencies in water-stressed production zones.
- Double-Pipe:Concentric tube designs serve pilot brewing systems and small-batch experimental operations.
Plate configurations handle the majority of throughput; Air-Cooled is climbing the fastest on share as water scarcity reshapes site selection.
Material:
Cost tier stratification separates commodity alloys from corrosion-resistant premium grades.
- Stainless Steel:Grade 316L austenitic alloys with molybdenum additions resist chloride pitting in standard brewing water chemistries. German fabricators source this grade exclusively for EU F-Gas Regulation compliant systems where material traceability documentation is mandatory. Price volatility in nickel markets compresses fabrication margins.
- Titanium:Commercially pure and alloyed grades deliver exceptional corrosion resistance in high-chloride coastal groundwater zones. Craft breweries across coastal India and Middle Eastern production facilities specify titanium-clad plate configurations despite 3-4x capital cost premiums. The material captures positioning where 316L failure rates justify lifecycle cost analysis.
- Copper:Traditional wort chiller material retained in heritage equipment specifications.
- Aluminum:Lightweight alloys serve air-cooled exchanger fin stock and cost-sensitive auxiliary applications.
Stainless Steel commands the largest installed base; Titanium is expanding most quickly in premium coastal markets.
Application:
Volume concentration centers on thermal control points where process continuity determines output quality.
- Wort Cooling:Rapid temperature reduction from boiling to yeast-pitching ranges (20°C) demands high heat transfer coefficients and sanitary surface finishes. Brazilian craft corridors around São Paulo and Minas Gerais states are scaling capacity in this segment as lager production targets expand. The application drives plate exchanger procurement cycles.
- Pasteurization:Continuous thermal treatment for packaged beer stability requires precise temperature holding zones and regeneration sections for energy recovery. Legacy Czech and German lager facilities maintain shell-and-tube infrastructure for this application due to integrated line dependencies and validation documentation requirements.
- Yeast Management:Propagation tank temperature control for viability optimization.
- Hot Water Recirculation:Energy recovery from process streams for CIP and utility heating.
Wort Cooling manages the largest equipment spend; Yeast Management is gaining share fastest as propagation automation expands.
End User:
Customer type determines specification complexity and service channel preferences.
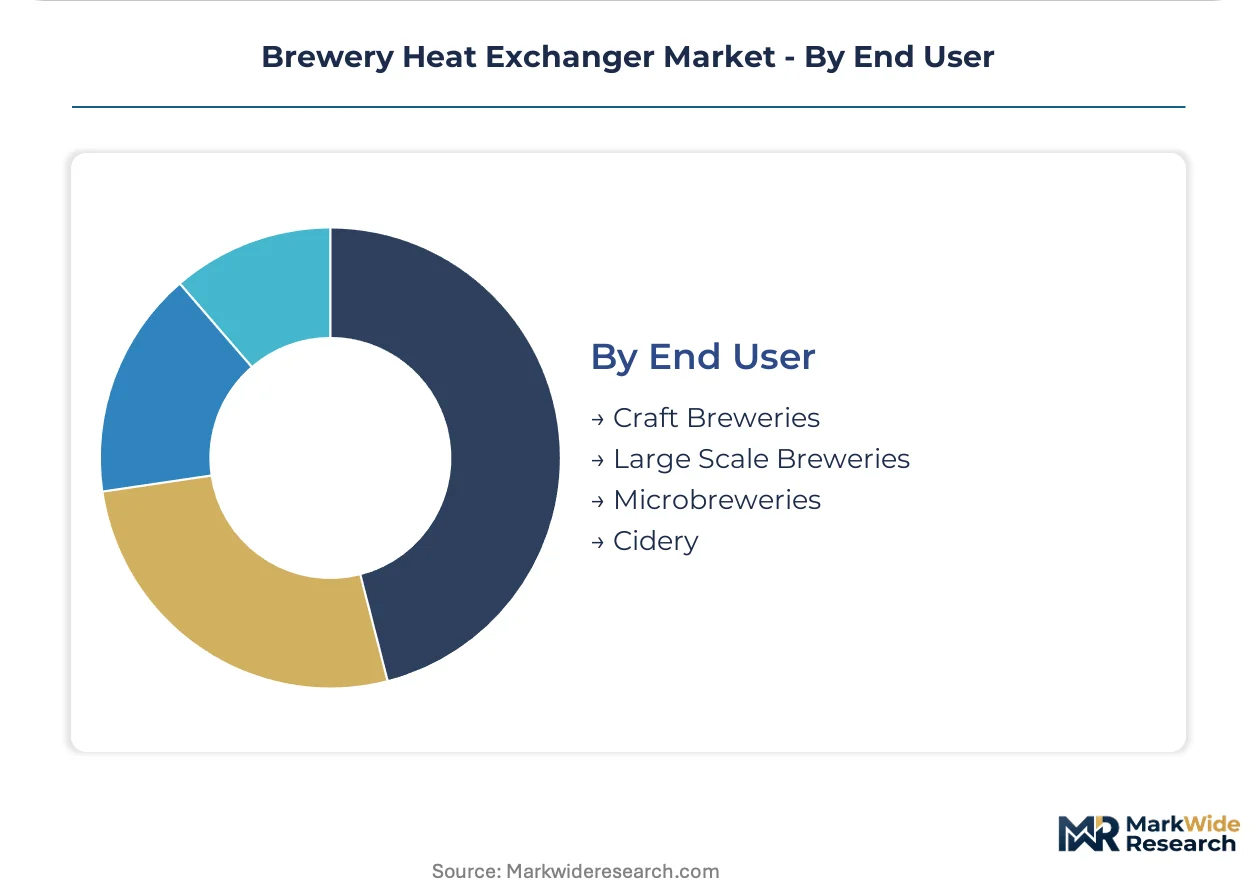
- Craft Breweries:Independent operations producing under defined annual barrel thresholds prioritize modular plate systems with rapid installation and third-party CIP service compatibility. German craft clusters specify ammonia-compatible plate exchangers to satisfy local environmental ordinances beyond EU F-Gas Regulation baselines.
- Large Scale Breweries:Industrial facilities with integrated packaging and distribution infrastructure require validated pasteurization lines and centralized SCADA integration. These operators retain OEM service contracts and demand ASME BPE certification documentation for orbital welding procedures.
- Microbreweries:Sub-craft scale operations with tasting room distribution.
- Cidery:Fermented apple and fruit beverage producers with similar thermal processing requirements.
Large Scale Breweries account for the greatest equipment volume; Craft Breweries are expanding most quickly as regional production clusters mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's craft breweries favor ammonia-based plate configurations for wort cooling, while Brazil's lager producers retain shell-and-tube pasteurization lines; coastal India specifies titanium-clad variants against chloride corrosion.
Germany
Bavarian craft clusters scale modular plate heat exchanger capacity to meet lager production targets. The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs, accelerating investment in refrigerant-independent thermal systems. North Rhine-Westphalia fabricators compete for retrofit contracts across Bohemian-border brewing corridors.
Brazil
São Paulo state's craft beer corridor drives wort cooling equipment procurement from regional suppliers. ANVISA governs sanitary surface standards for thermal processing equipment in beverage production. Minas Gerais and Rio Grande do Sul microbreweries present underdeveloped demand for modular capacity expansion.
United States
Large-scale breweries in the Midwest retain OEM service contracts for validated pasteurization lines. The FDA and EPA jointly govern sanitary surface finishes and effluent thermal discharge limits. Pacific Northwest craft operators increasingly procure third-party CIP services rather than bundled OEM maintenance.
India
Coastal craft breweries in Maharashtra and Karnataka specify titanium-clad plate configurations against high-chloride groundwater corrosion. BIS material certification requirements create documentation barriers for imported alloy sourcing. Tamil Nadu's emerging microbrewery clusters drive demand for compact air-cooled alternatives in water-stressed zones.
China
Yangtze River Delta brewing equipment manufacturers scale stainless steel fabrication for domestic craft brewery expansion. MIIT industrial standards govern pressure vessel certification for thermal processing equipment. Shandong Peninsula fabricators supply corrugated plate cassettes to regional lager producers upgrading legacy cooling circuits.
Brewery Heat Exchanger Market Competitive Environment
Capability concentration sits with European fabricators holding orbital welding certification and REACH traceability systems; scale advantage sits with North American and Asian suppliers leveraging stainless steel procurement volume. The vendor base separates into three tiers: multinational thermal engineering groups, regional equipment fabricators, and specialized sanitary service providers. Consolidation pressure operates through M&A activity among mid-scale European specialists and capacity expansion among Asian plate manufacturers.
Within the multinational tier, Alfa Laval and GEA Group occupy positions defined by integrated thermal processing portfolios and European regulatory compliance depth. Paul Mueller Company anchors North American demand through stainless steel fabrication scale. Among India-based specialists, Praj Industries Ltd. and HRS Process Systems exemplify regional fabricators competing on modular system customization for emerging craft brewery markets.
| Leading Market Players |
|---|
| WCR Incorporated |
| Paul Mueller Company |
| Alfa Laval |
| Praj Industries Ltd. |
| HGMC |
| GEA Group |
| Koch Engineered Solutions |
| HRS Process Systems |
| Krones AG |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp corridor freight costs transmit stainless steel sheet volatility directly into European fabrication pricing, compressing margins for regional suppliers while amplifying price spreads between REACH-certified and uncertified equipment tiers across downstream craft brewery procurement.
Pricing Analysis
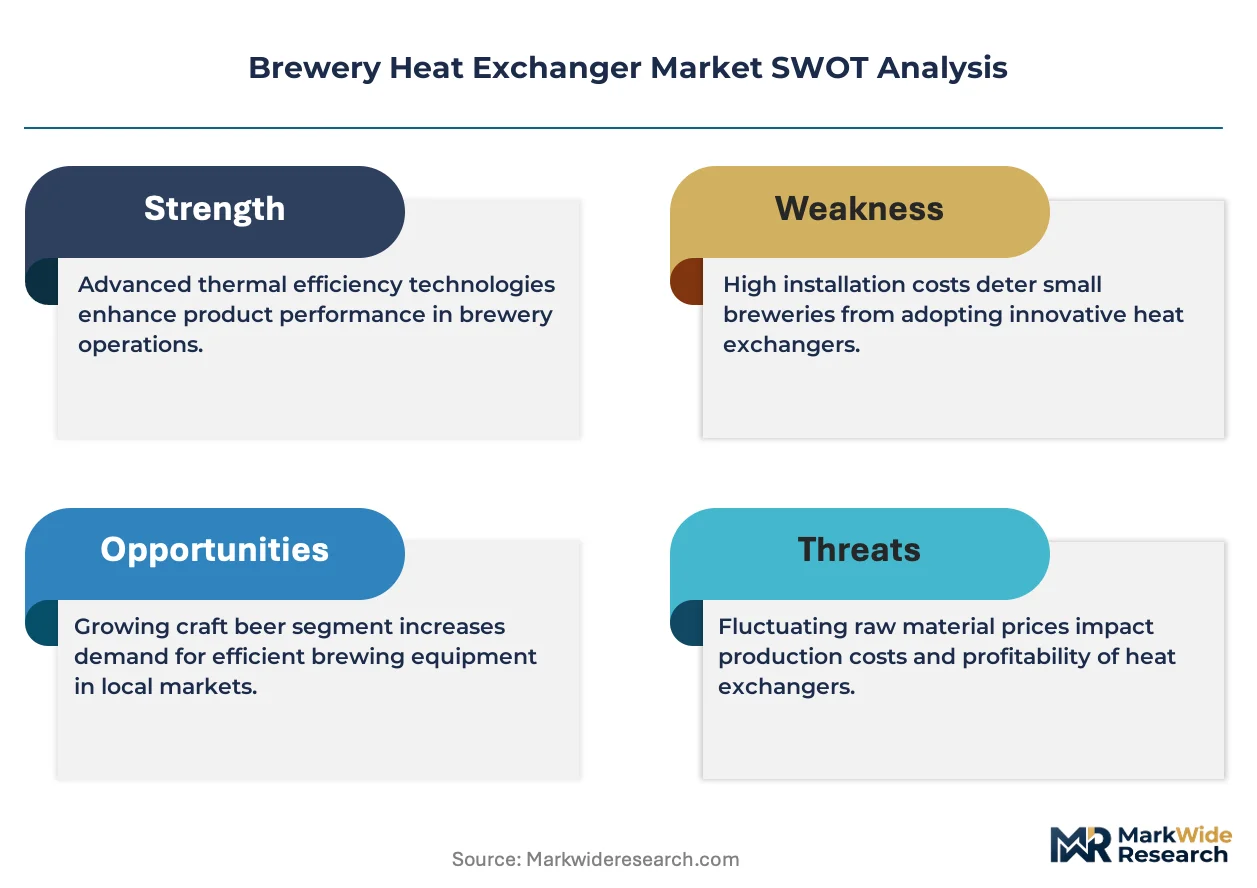
Geographic price spreads between German-certified and Asian-imported units exceed 40% at equivalent thermal ratings. Three-tier pricing structure separates titanium-clad premium configurations from standard 316L plate systems and economy air-cooled alternatives. Cost compression in mid-grade segments is intensifying because nickel commodity swings transmit rapidly through spot-contract hybrid purchasing. Craft breweries in Brazil and India exhibit highest price sensitivity, while large-scale European lager facilities prioritize certification documentation over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for corrugated plate cassette sourcing. Grade 316L stainless steel draws from Indonesian nickel smelters, German cold-rolling mills, and Chinese fabrication centers. Titanium sponge feeds from Japanese and Kazakh primary producers. Single-source vulnerability concentrates in orbital welding equipment certified for ASME BPE compliance. Distribution runs through OEM direct sales for large-scale breweries and regional equipment distributors serving craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brewery heat exchanger penetration sits at early-cycle expansion as EU F-Gas Regulation retrofit mandates accelerate replacement timelines across European craft clusters.
For Market Incumbents: Pre-empt service unbundling by capturing third-party CIP provider networks before channel fragmentation erodes spare parts revenue. Lock in ammonia-compatible plate configurations through German environmental ordinance compliance to defend against Asian cost competitors. Prioritize REACH traceability system investments as procurement specifications harden material documentation requirements. For New Entrants and Emerging Players: Build out modular air-cooled capacity for water-stressed Indian and Middle Eastern coastal zones where titanium-clad premiums justify local assembly partnerships. Target Minas Gerais and Rio Grande do Sul microbreweries outside São Paulo's saturated core. Lead with rapid-installation value propositions and third-party service compatibility to bypass entrenched OEM maintenance relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents with under-monetized sanitary welding capabilities and dormant brewery equipment portfolios. Long-term viability centers on refrigerant-independent thermal architecture ownership as synthetic coolant phase-downs accelerate globally. Watch ammonia infrastructure investment rates in German craft corridors as inflection signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Traceability System Deployment | Material certification documentation satisfies EU F-Gas Regulation procurement specifications for German craft brewery retrofits. |
| Ammonia-Compatible Plate Configuration | Sealed circuit designs with integrated leak detection address flammable refrigerant safety requirements under local environmental ordinances. |
| Third-Party CIP Service Network Acquisition | Channel control prevents margin erosion from independent sanitary service providers capturing recurring brewery maintenance revenue. |
| Titanium-Clad Local Assembly Partnership | Regional fabrication reduces premium equipment delivery costs for high-chloride groundwater zones in coastal India and the Middle East. |
| Orbital Welding Certification Expansion | ASME BPE qualification capacity alleviates 8-14 week delivery bottlenecks compressing seasonal brewery expansion project windows. |
Study Parameters
A standing panel of brewery engineering directors, thermal equipment procurement managers, aftermarket service heads, and regulatory compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU F-Gas Regulation implementation filings, REACH chemical database updates, ASME BPE certification registries, and stainless steel trade flow customs records. Bottom-up equipment shipment tallies triangulated against top-down production capacity estimates across the analysis window.
Scenario-bracketing framed low, baseline, and high penetration assumptions across type, material, application, and end-user segmentation dimensions. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline modeling, and craft brewery formation rates. Forecast inputs incorporated refrigerant phase-down quota allocations, nickel commodity price trajectories, and regional water stress indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fabricators or accelerated ammonia infrastructure subsidies would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market