
 Garlic Supplements Market | 2026-2036
Garlic Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Garlic Supplements Market Analytics
Allicin-standardized extracts is rebalancing raw garlic powder economics as manufacturers absorb higher input costs for validated bioactive content. NOW Foods leverages vertical integration into aged garlic cultivation to sustain margin stability across volatile crop cycles. Wakunaga of America Co. Ltd. anchors its position through Kyolic-branded aging protocols that differentiate on cardiovascular clinical data. Solaray Inc. competes via organic certification and non-GMO positioning in natural retail channels.
Garlic supplements comprise processed Allium sativum preparations standardized to allicin, S-allyl cysteine, or alliin content, manufactured through freeze-drying, cold-aging, or oil-extraction methods to preserve organosulfur bioactivity for cardiovascular, immune, and antimicrobial applications. Capsules dominate volume due to dosing precision and enteric-coating compatibility, while extracts command premium pricing from concentrated allicin yields and clinical trial backing. Online Retailers represent the fastest-expanding distribution channel as direct-to-consumer brands bypass pharmacy markups through subscription models and telehealth integrations.
FDA dietary supplement GMPs and NDI notifications govern new garlic extract introductions in the United States, while EFSA health claim regulations constrain cardiovascular marketing in Europe and force reformulation toward general wellness positioning. FSSAI fortification guidelines and BIS quality standards shape product registration and label claims in India, where ayurvedic co-positioning opens distinct regulatory pathways. Stakeholders must monitor evolving pharmacovigilance requirements for anticoagulant interaction warnings as garlic supplement use expands among polypharmacy populations.
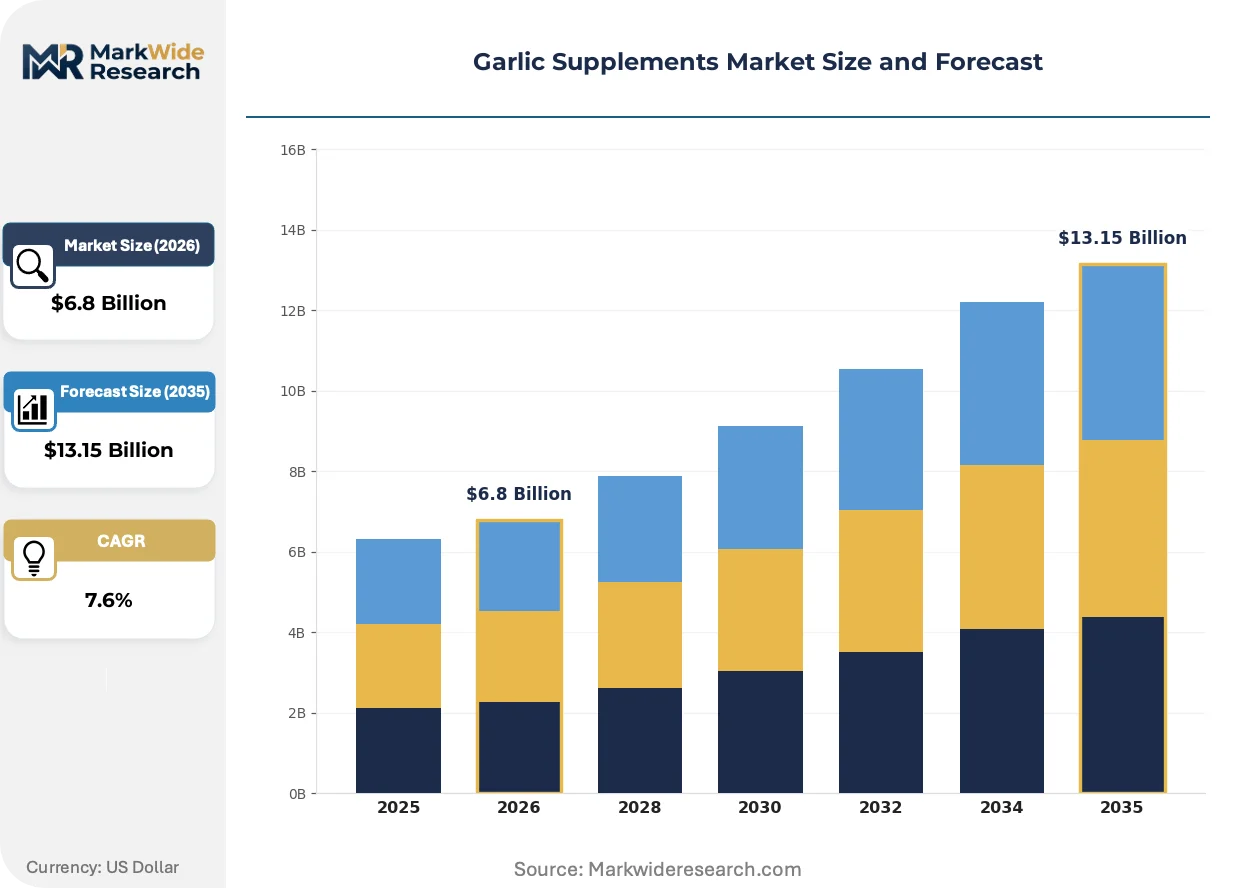
Market Dynamics
Allicin standardization protocols are compressing raw garlic powder margins as manufacturers absorb higher validation costs for bioactive content certification, forcing a bifurcation between commodity-grade and clinically-backed product tiers.
Growth Catalysts
- Employer cardiovascular wellness mandates:Corporate health clinics in Germany and the United States are expanding odor-controlled formulation procurement as preventive care benefits.
- FSSAI fortification guidelines:India's regulatory pathway for ayurvedic co-positioning is opening distinct registration channels for garlic supplements with traditional medicine claims.
- Enteric-coating technology:Pharmaceutical-grade capsule manufacturing is enabling allicin preservation through gastric transit, improving bioavailability metrics for clinical applications.
Market Restraints
- Allium sativum crop volatility:Weather-dependent harvests in Chinese and Spanish growing regions create input cost instability for non-integrated processors.
- FDA NDI notification pathway:Novel extract introductions face extended compliance timelines and safety documentation requirements that delay market entry.
- Synthetic antihypertensive substitution:Prescription ACE inhibitors and statins compete for the same cardiovascular wellness patient population with reimbursable coverage.
Strategic Opportunities
- Telehealth-integrated subscription models:Direct-to-consumer platforms are bypassing pharmacy markups through automated replenishment and remote consultation bundling.
- EFSA general wellness repositioning:European manufacturers are reformulating away from cardiovascular claims toward immune support to circumvent health claim restrictions.
- Aged garlic extract convergence:S-allyl cysteine stabilization protocols combined with organic certification are creating premium positioning in natural retail channels.
Industry Challenges
- Organosulfur analytical expertise scarcity:Validated allicin quantification requires specialized HPLC-MS capabilities that contract laboratories struggle to scale.
- Anticoagulant interaction surveillance:Pharmacovigilance systems must expand warning label protocols as polypharmacy populations adopt garlic supplements alongside warfarin and aspirin regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garlic Supplements Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powder, Extracts End User: Individuals, Health Enthusiasts, Athletes, Seniors Packaging Type: Bottles, Blister Packs, Sachets, Bulk Bins Distribution Channel: Online Retailers, Pharmacies, Health Stores, Supermarkets |
| Companies Covered | Solaray Inc., Swisse, NOW Foods, GNC, Doppelherz, Nature’s Bounty Co., Holland & Barrett, Blackmores, Wakunaga of America Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garlic Supplements Market Evolving Landscape
Freeze-drying and cold-aging processing methods are displacing conventional heat-extraction techniques as bioactivity preservation becomes the primary competitive differentiator in premium supplement tiers.
Enteric-coated capsule technology is absorbing higher manufacturing costs to deliver intact allicin to intestinal absorption sites, enabling hospital procurement committees to specify these formulations for post-cardiac event patient protocols. German pharmacy chains are prioritizing shelf space for clinically validated products, compressing margins for uncoated commodity alternatives.
EFSA health claim regulations are constraining cardiovascular marketing across European Union member states, forcing reformulation investments toward immune and antimicrobial positioning that circumvents strict substantiation requirements. Manufacturers in Italy and France are redirecting clinical trial budgets toward general wellness endpoints.
Subscription-based direct purchasing is displacing traditional pharmacy distribution as telehealth platforms integrate supplement recommendations into remote consultation workflows. United States employer wellness programs are channeling garlic supplement procurement through centralized benefits administrators, bypassing retail markup structures entirely.
Garlic Supplements Market Segmentation
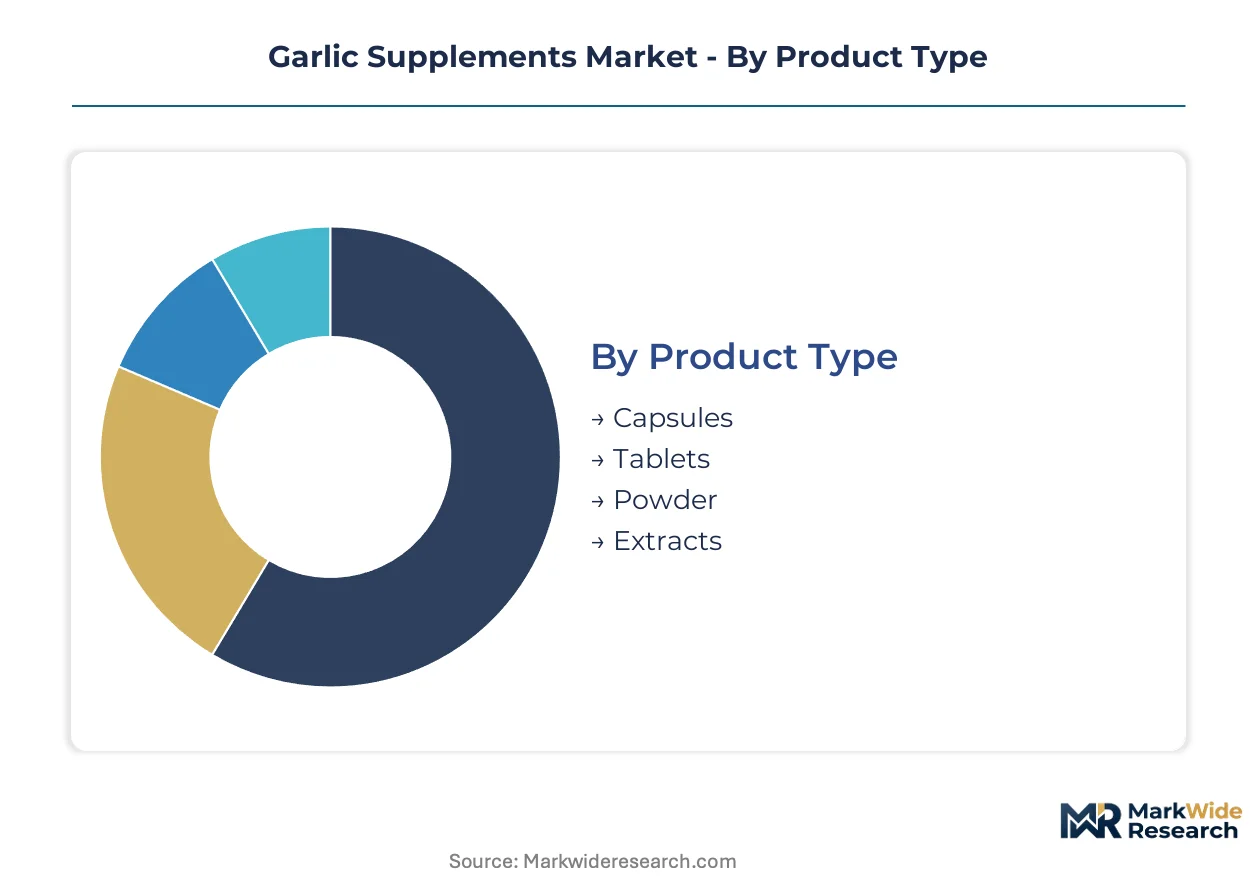
Garlic supplement manufacturers configure production lines around organosulfur stability requirements, creating divergent capital needs across delivery formats. Segmentation reveals where clinical validation investments concentrate versus commodity-scale operations.
Product Type:
Extracts demand the heaviest upfront investment in HPLC-MS validation infrastructure and cold-aging fermentation capacity, while powder operations run on simpler drying and milling equipment.
- Capsules:Enteric-coated gelatin or vegetable cellulose shells protect allicin from gastric degradation, enabling precise dosing for cardiovascular protocols. German pharmacy chains prioritize these formulations for patient compliance programs, absorbing premium manufacturing costs.
- Extracts:Concentrated allicin or S-allyl cysteine preparations require multi-stage solvent extraction and standardized potency verification. NOW Foods and Wakunaga compete here through proprietary aging protocols that justify clinical trial investments.
- Tablets:Compressed formulations with binders and disintegrants suit cost-sensitive retail segments in Indian and Southeast Asian markets where BIS quality standards govern dissolution specifications.
- Powder:Freeze-dried or air-dried raw material for bulk blending into functional foods and ayurvedic preparations, favored by FSSAI-registered manufacturers targeting fortification guidelines.
Most installed capacity flows through Capsules. Expansion is steepest in Extracts.
End User:
Volume concentrates among preventive health adopters, while margin accrues to condition-specific segments requiring clinical substantiation.
- Seniors:Polypharmacy populations seeking anticoagulant-sparing cardiovascular support drive pharmacist-guided purchasing in US Medicare Advantage plans and German long-term care facilities, triggering expanded interaction warning requirements.
- Health Enthusiasts:Biohacking communities and wellness program participants subscribe to high-potency aged garlic protocols through telehealth-integrated platforms, bypassing traditional pharmacy markups entirely.
- Individuals:General preventive users responding to immune support positioning in EFSA-constrained European markets where cardiovascular claims face strict substantiation hurdles.
- Athletes:Endurance competitors pursuing antimicrobial and circulation benefits, particularly in cycling and marathon training communities with established supplement regimens.
Health Enthusiasts generate the highest per-unit margins. Seniors represent the largest addressable population base.
Packaging Type:
Moisture barrier specifications and shelf-life extension technologies determine cost structures across single-serve and bulk formats.
- Bottles:HDPE or amber glass containers with desiccant inserts dominate pharmacy and health store channels, supporting 24-month stability claims for allicin-standardized products.
- Blister Packs:Aluminum-laminated cold-form foils enable unit-dose compliance packaging for hospital discharge protocols and employer wellness program distribution.
- Sachets:Flexible film single-serve packets suit powder samples and travel formats in Asian convenience retail, requiring lower minimum order quantities for brand trials.
- Bulk Bins:Food-service and compounding pharmacy supply for institutional buyers, constrained by FSSAI and FDA facility registration requirements for repackaging operations.
Bottles command the largest production volume. Blister Packs are gaining share fastest in clinical procurement channels.
Distribution Channel:
Channel selection determines regulatory exposure and margin retention, with direct models capturing value previously absorbed by pharmacy intermediaries.
- Online Retailers:Subscription platforms and telehealth integrations enable automated replenishment with remote consultation bundling, bypassing brick-and-mortar markups in US and German markets. FDA dietary supplement GMPs and state pharmacy board regulations govern fulfillment center operations.
- Pharmacies:German pharmacy-led counseling drives premium positioning for clinically validated products, while US independents face margin pressure from centralized benefits administrator procurement.
- Health Stores:Natural retail channels prioritize organic certification and non-GMO verification, with Solaray and comparable brands competing through shelf-space negotiations.
- Supermarkets:Mass-market placement for odor-controlled commodity formulations, constrained by slotting fees and private label competition in price-sensitive segments.
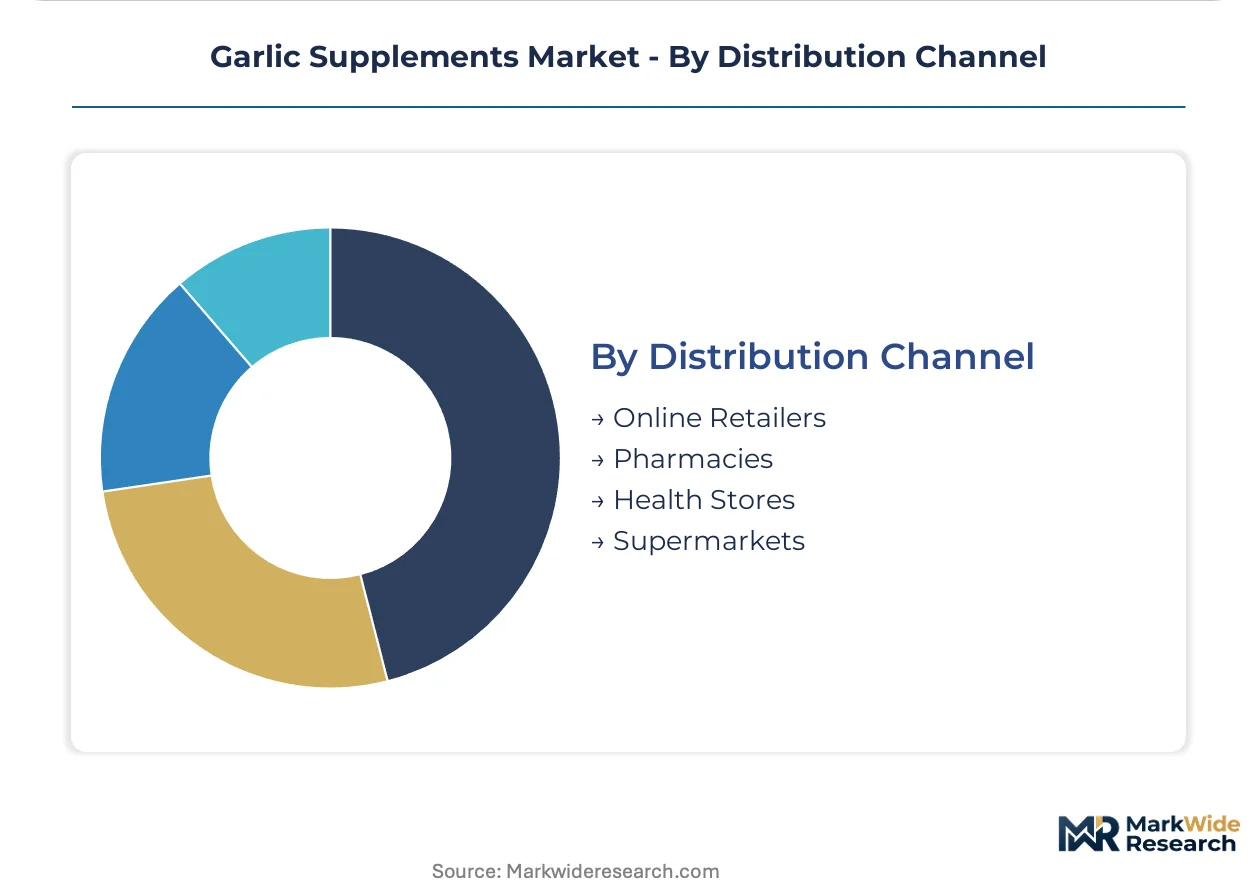
Pharmacies retain the deepest clinical credibility. Online Retailers are climbing the fastest as telehealth bundling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmacy-led counseling clusters in Bavaria and North Rhine-Westphalia anchor premium-tier demand for clinically validated garlic formulations. Employer wellness mandates in the United States and ayurvedic fortification guidelines in India reshape procurement patterns across three continents.
United States
Employer cardiovascular wellness programs channel garlic supplement procurement through centralized benefits administrators, bypassing retail markups. FDA dietary supplement GMPs and NDI notification pathways govern novel extract introductions with extended compliance timelines. NOW Foods leverages in-house production of aged garlic cultivation in Illinois and Wisconsin facilities to sustain margin stability.
Germany
Pharmacy-led supplement counseling in Bavaria and North Rhine-Westphalia drives premium positioning for odor-controlled formulations. EFSA health claim regulations constrain cardiovascular marketing, forcing reformulation toward general wellness endpoints. Wakunaga of America Co. Ltd. distributes Kyolic-branded products through Apotheke chains that prioritize clinically validated shelf placements.
India
FSSAI fortification guidelines and BIS quality standards shape product registration for ayurvedic co-positioned garlic supplements. Traditional medicine claims open distinct regulatory pathways distinct from pharmaceutical regulations. Manufacturing clusters in Maharashtra and Gujarat concentrate freeze-dried powder operations for domestic and export markets.
China
Allium sativum crop cultivation in Shandong and Henan provinces supplies raw material for global processors facing weather-dependent harvest volatility. SAMR and GB standards govern dietary supplement quality specifications with increasing stringency. Zhengzhou and Jinan processing hubs export bulk extracts to European and North American finished goods manufacturers.
Australia
TGA regulations enforce stringent manufacturing practice standards for garlic supplement imports and domestic production. Health Store channels in Sydney and Melbourne prioritize organic certification and non-GMO verification for natural retail positioning. Blackmores anchors premium-tier distribution through pharmacy and practitioner networks with clinical trial-backed formulations.
Garlic Supplements Market Competitive Landscape
Global majors compete with regional champions across clinical validation and distribution channel access. The vendor base stratifies between vertically integrated cultivators, contract manufacturers, and brand marketers with pharmacy relationships. Three archetypes dominate: allicin-standardized extract specialists, aged garlic protocol developers, and organic-certified commodity processors. Capacity expansion in cold-aging fermentation and strategic partnerships with telehealth platforms represent the dominant competitive moves.
Within the aged garlic extract tier, Wakunaga of America Co. Ltd. and NOW Foods exemplify backward integration strategies that stabilize input costs across volatile crop cycles. Solaray Inc. occupies a position in the organic-certified segment where non-GMO verification commands shelf space premiums in natural retail channels. Doppelherz represents the pharmacy-channel archetype in European markets where clinician counseling drives adherence and repeat purchase rates.
| Leading Market Players |
|---|
| Solaray Inc. |
| Swisse |
| NOW Foods |
| GNC |
| Doppelherz |
| Nature's Bounty Co. |
| Holland & Barrett |
| Blackmores |
| Wakunaga of America Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Organic certification mandates gate qualified supply access and premium-tier pricing power, as FSSAI fortification guidelines and EFSA health claim regulations force manufacturers to absorb validation costs for bioactive content verification that commodity processors cannot meet.
Pricing Analysis
Input-cost pass-through from weather-dependent Allium sativum harvests in Shandong and Henan provinces compresses margins for non-integrated processors while vertically integrated cultivators sustain stability. Pricing stratifies across allicin-standardized extracts, enteric-coated capsules, and raw powder tiers, with certification grade and clinical trial backing as primary differentiation drivers. Cost compression in commodity powder segments intensifies as German pharmacy chains prioritize clinically validated formulations. Health enthusiasts demonstrate lowest price sensitivity for aged garlic protocols, while Indian bulk buyers exhibit highest sensitivity to per-kilogram fluctuations.
Supply Chain Analysis
Workforce availability constraints in Zhengzhou and Jinan processing hubs limit scaling of HPLC-MS analytical capabilities required for allicin standardization. Raw material supply concentrates in China, Spain, and India, drawing from freeze-dried bulb, solvent extraction chemicals, and enteric-coating polymers. Single-source vulnerability runs through Chinese crop concentration exposed to climate volatility. Distribution runs through pharmacy-led counseling networks in Germany, telehealth-integrated subscription platforms in the United States, and ayurvedic wholesale channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aged garlic extract tiers where S-allyl cysteine stabilization commands premium positioning, while backward integration into cultivation absorbs input volatility that erodes commodity-grade competitors.
For Market Incumbents: Cement pharmacy channel control through Kyolic-branded aging protocol exclusivity and Apotheke shelf-space prioritization. Expand captive supply of odor-controlled formulations in Illinois and Wisconsin facilities to defend against telehealth-integrated subscription entrants. Deepen HPLC-MS analytical infrastructure to maintain allicin validation leadership as contract laboratory scarcity intensifies.
For New Entrants and Emerging Players: Enter via FSSAI-registered ayurvedic co-positioning in Maharashtra and Gujarat manufacturing clusters where traditional medicine claims circumvent pharmaceutical regulations. Target immune support repositioning in EFSA-constrained European markets with general wellness endpoints. Deploy direct-to-consumer subscription bundling with remote consultation platforms to bypass German pharmacy markups.
For Investors and Strategic Acquirers: Roll-up economics work for aged garlic extract specialists because clinical trial infrastructure and backward integration into cultivation create defensible moats that commodity processors cannot replicate. Five-to-ten year viability hinges on telehealth platform partnerships and employer wellness program procurement consolidation. Monitor FDA NDI notification pathway delays as inflection signal for novel extract market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive supply from Illinois and Wisconsin facilities stabilizes margin against Chinese crop volatility. |
| Enteric-Coating Technology Investment | Pharmaceutical-grade capsule manufacturing enables hospital procurement committee specifications. |
| Telehealth Platform Partnership | Remote consultation bundling bypasses German Apotheke markups through automated replenishment. |
| Ayurvedic Co-Positioning Registration | FSSAI fortification guidelines open distinct regulatory pathways for traditional medicine claims. |
| Clinical Trial Endpoint Diversification | Immune support positioning circumvents EFSA cardiovascular claim restrictions across EU member states. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with supplement brand managers, pharmacy procurement leads, contract manufacturing executives, and regulatory affairs specialists. Secondary validation draws from FDA dietary supplement GMP filings, EFSA health claim registers, FSSAI fortification guidelines, and BIS quality standards documentation. Bottom-up segment sizing and top-down macroeconomic triangulation anchor volume and value estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions include product type, end user archetype, packaging format, and distribution channel. CAGRs derive from modeled adoption curves for employer wellness programs and telehealth-integrated subscription penetration. Forecast inputs incorporate allicin standardization protocol diffusion and enteric-coating manufacturing capacity expansion.
The model holds under stable regulatory enforcement and crop yield patterns; deviation in FDA NDI notification timelines or extreme weather events in Shandong growing regions would shift trajectory. Forecasts reflect documented assumptions about employer wellness mandate expansion and pharmacy counseling persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
North America Memory Supplements Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Activated Charcoal Supplement Market