
 Smart Stethoscopes Market | 2026-2036
Smart Stethoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Stethoscopes Market Intelligence
North America is narrowing its lead in smart stethoscope manufacturing capacity as assembly lines expand in Mexico and Costa Rica. Eko Health, Inc. leverages its FDA-cleared AI algorithms to anchor cardiac screening workflows across U.S. hospital networks. 3M sustains broad channel control through its Welch Allyn distribution arm, while Thinklabs Medical LLC specializes in precision digital transduction for research-intensive academic medical centers.
Smart stethoscopes integrate electronic acoustic sensors, digital signal processors, and wireless transmitters to capture, amplify, and analyze body sounds for clinical diagnosis or remote consultation. These devices typically operate at frequency ranges of 20 Hz to 1 kHz with signal-to-noise ratios exceeding 60 dB, enabling detection of subtle murmurs and pulmonary anomalies that analog models miss. Wireless stethoscopes command the fastest growth trajectory as Bluetooth Low Energy protocols and cloud-based auscultation archives displace tethered examination workflows. AI-enhanced technology segments capture disproportionate margin pools through subscription-based diagnostic support and automated murmur classification, while handheld devices remain the dominant device type due to physician familiarity and minimal workflow disruption.
FDA digital health pre-certification programs and HIPAA interoperability mandates shape product development roadmaps and market access timelines for connected diagnostic devices. The EU MDR and GDPR impose parallel conformity and data governance burdens on manufacturers seeking European market entry, while Japan's PMDA accelerates review pathways for AI-embedded telemedicine hardware. Stakeholders must weigh regulatory jurisdiction sequencing against R&D amortization schedules as software-enabled stethoscopes blur boundaries between medical device and software-as-a-service categories.
Market Dynamics
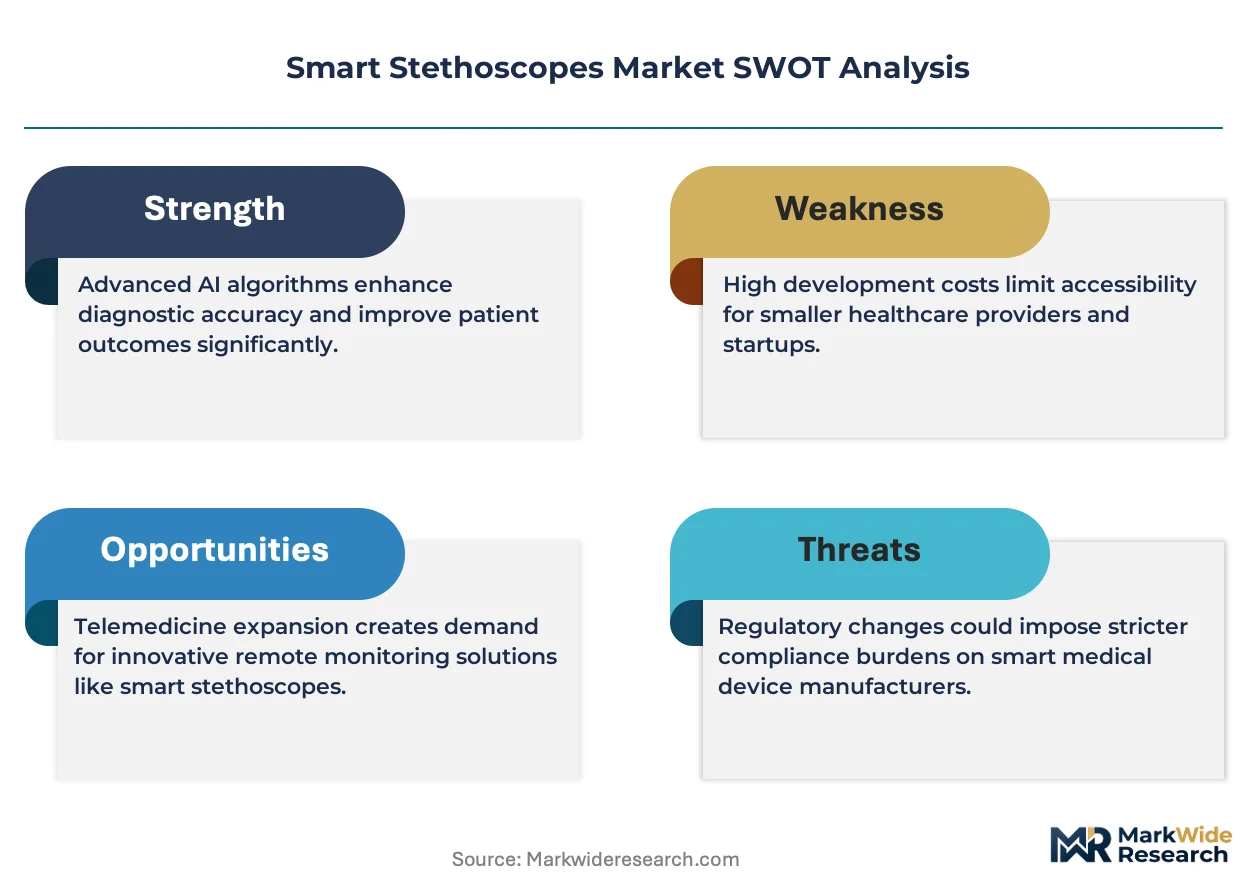
AI-enabled diagnostic algorithms are compressing the traditional physician-specialist referral chain by embedding cardiopulmonary screening capabilities directly into primary care workflows. This structural shift reconfigures value capture toward software subscription layers and away from hardware margins alone.
Growth Catalysts
- Telemedicine reimbursement parity:CMS policies in the United States now compensate remote auscultation at rates comparable to in-person examinations. This reimbursement framework accelerates hospital procurement of connected stethoscopes for virtual care networks.
- Bluetooth Low Energy protocol maturation:BLE 5.3 specifications enable real-time audio streaming with sub-20ms latency, satisfying clinical requirements for synchronous remote diagnosis without dedicated hardware dongles.
- Academic medical center research demand:Quantitative phonocardiography studies at institutions like Stanford and Johns Hopkins drive precision digital transduction requirements, creating pull for high-fidelity signal acquisition platforms.
Market Restraints
- Semiconductor supply concentration:MEMS microphone fabrication relies heavily on Taiwan-based foundry capacity, exposing manufacturers to geopolitical disruption risks and 18-24 month qualification timelines for alternative sources.
- EU MDR conformity costs:The 2017/745 Medical Device Regulation imposes clinical evidence requirements for software-enabled diagnostics that add €400,000-€800,000 per product variant to European market entry budgets.
- Analog stethoscope substitution resilience:Littmann Classic III models retain preference among cost-conscious clinicians in developing markets, limiting premium digital penetration below 15% in outpatient primary care settings.
Strategic Opportunities
- Rural India connectivity gaps:The Ayushman Bharat digital health mission creates demand for offline-capable auscultation devices with asynchronous cloud upload, addressing intermittent cellular coverage in tier-3 districts.
- AI-ECG convergence:Integration of single-lead ECG with phonocardiographic analysis enables atrial fibrillation detection during routine cardiac auscultation, expanding reimbursable screening indications.
- Direct-to-consumer channel emergence:Amazon and Best Buy health device marketplaces now carry FDA-cleared digital stethoscopes, bypassing traditional GPO procurement for concerned parents and home health aides.
Industry Challenges
- Algorithm validation workforce scarcity:Clinical data science roles combining cardiology domain expertise with machine learning engineering command 40% salary premiums over general health informatics positions, constraining AI product development velocity.
- EHR interoperability fragmentation:HL7 FHIR implementation varies across Epic, Cerner, and Meditech deployments, forcing device manufacturers to maintain 6-12 distinct integration codebases for health system customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Stethoscopes Market |
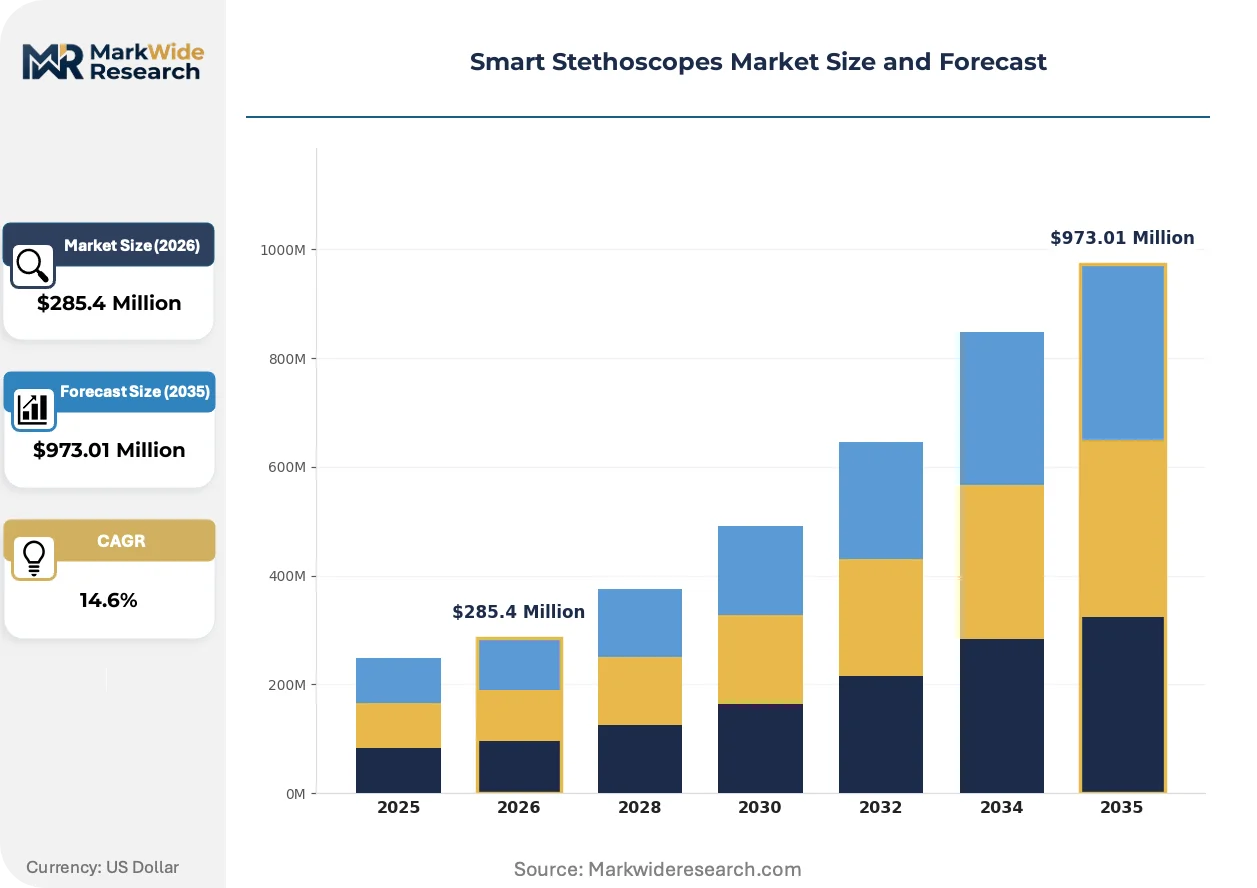
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $973.01 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Stethoscopes, Wireless Stethoscopes, Analog Stethoscopes, Software-Enabled Stethoscopes End User: Hospitals, Clinics, Home Healthcare, Emergency Services Technology: Bluetooth, Cloud-based, AI-Enhanced, Real-time Monitoring Device Type: Wearable Devices, Handheld Devices, Desktop Systems, Telemedicine Devices |
| Companies Covered | HD Medical, Inc., Solventum, Eko Health, Inc., Welch Allyn, American Diagnostic Corporation, 3M, eKuore, M3DICINE Pty Ltd., Thinklabs Medical LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Stethoscopes Market Strategic Shifts & Innovations
Signal processing architectures are migrating toward edge-computing configurations that reduce cloud dependency and enable real-time diagnostic feedback without network connectivity. This shift redefines hardware-software boundaries and creates new competitive dimensions around on-device inference efficiency.
Piezoelectric sensor arrays are displacing single-point electret microphones in premium device tiers. These multi-element configurations capture spatial acoustic signatures that analog stethoscopes cannot resolve. Cardiology departments at Cleveland Clinic and Mayo Clinic have adopted these platforms for murmur localization studies. The technology is migrating from research instrumentation into routine clinical workflows as manufacturing scales drive unit costs below $80 per sensor array.
FDA's 2023 Digital Health Pre-Certification Program 1.1 expands streamlined review pathways for AI-enabled auscultation software that demonstrates real-world performance monitoring capabilities. This regulatory innovation reduces time-to-market for algorithm updates from 180 days to 60 days for pre-certified organizations. European manufacturers are responding by establishing U.S. regulatory subsidiaries ahead of EU MDR transition completion, prioritizing FDA clearance sequencing.
Hospital procurement committees are consolidating vendor relationships around platforms offering integrated device fleets with unified fleet management dashboards. This buying-pattern compression disadvantages point-solution specialists lacking enterprise IT integration depth. The shift is most pronounced in United States IDN consolidation markets, where ten health systems control 35% of connected diagnostic device spending and demand API-standardized telemetry across cardiology, pulmonology, and primary care device categories.
Smart Stethoscopes Market Segmentation
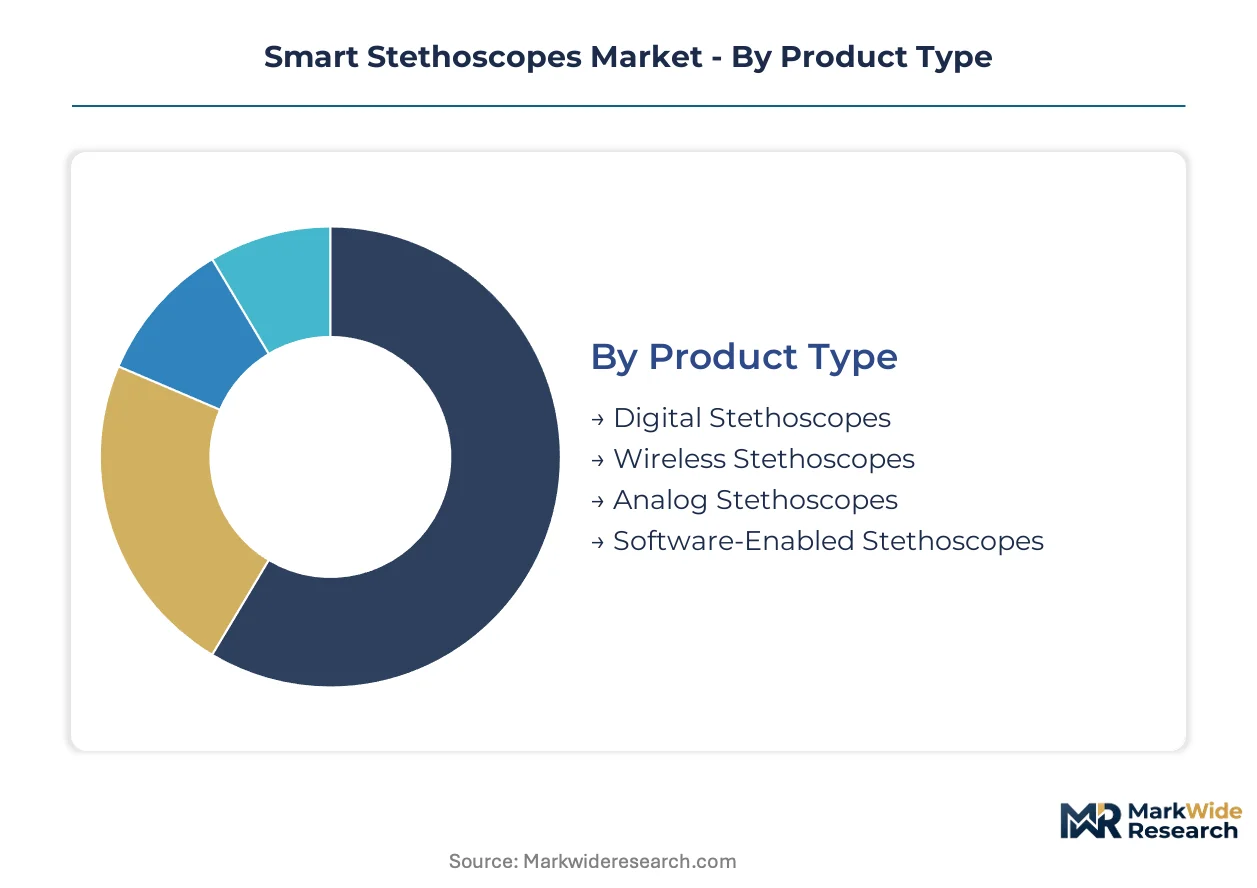
Segmentation in the smart stethoscopes market reveals how hardware specifications, connectivity protocols, and clinical deployment settings determine pricing power and customer loyalty. Manufacturers configure product portfolios across these dimensions to capture distinct margin pools from academic medical centers through home health networks.
Product Type:
Mature form factors coexist with emerging connectivity architectures as clinicians balance diagnostic fidelity against workflow integration demands.
- Digital Stethoscopes:Electronic acoustic sensors and digital signal processors amplify body sounds across 20 Hz to 1 kHz frequency ranges. Hospitals in the United States concentrate procurement for cardiology departments seeking murmur detection capabilities beyond analog sensitivity limits.
- Wireless Stethoscopes:Bluetooth Low Energy protocols enable real-time audio streaming with sub-20ms latency, eliminating tethered examination constraints. Academic medical centers drive demand for these platforms to support synchronous telemedicine consultations and remote precepting workflows.
- Analog Stethoscopes:Traditional acoustic designs retain preference in cost-sensitive primary care settings and developing markets where digital infrastructure remains limited.
- Software-Enabled Stethoscopes:AI-embedded algorithms for automated murmur classification and cloud-based auscultation archives create subscription revenue layers atop hardware sales.
Wireless stethoscopes retain volume leadership; software-enabled stethoscopes hold the steepest expansion curve.
End User:
Customer type determines purchasing authority complexity and integration requirements, from enterprise IT departments to individual consumers.
- Hospitals:Integrated delivery networks consolidate procurement around unified fleet management dashboards demanding API-standardized telemetry across cardiology, pulmonology, and primary care device categories.
- Clinics:Outpatient settings prioritize handheld familiarity and minimal workflow disruption, limiting premium digital penetration where Littmann Classic III models retain cost advantages.
- Home Healthcare:Direct-to-consumer channels through Amazon and Best Buy health device marketplaces bypass traditional GPO procurement for concerned parents and home health aides seeking FDA-cleared monitoring tools.
- Emergency Services:Field deployment requires ruggedized construction and offline-capable operation addressing intermittent cellular coverage in rural and disaster response scenarios.
Hospitals dominate absolute spending; home healthcare climbs the fastest as reimbursement parity expands reimbursable remote monitoring indications.
Technology:
Connectivity and intelligence layers differentiate margin capture between hardware-centric and software-subscription business models.
- Bluetooth:BLE 5.3 specifications satisfy clinical latency requirements for synchronous remote diagnosis without dedicated hardware dongles, anchoring the dominant wireless transmission standard.
- Cloud-based:Auscultation archives enable longitudinal patient monitoring and multi-specialist consultation workflows, though HIPAA interoperability mandates force manufacturers to maintain 6-12 distinct EHR integration codebases.
- AI-Enhanced:FDA-cleared algorithms for automated murmur classification compress the physician-specialist referral chain, embedding cardiopulmonary screening into primary care workflows with subscription-based diagnostic support revenue.
- Real-time Monitoring:Edge-computing configurations reduce cloud dependency and enable diagnostic feedback without network connectivity, addressing rural India connectivity gaps under the Ayushman Bharat digital health mission.
Bluetooth anchors installed base; AI-enhanced layers capture disproportionate margin expansion.
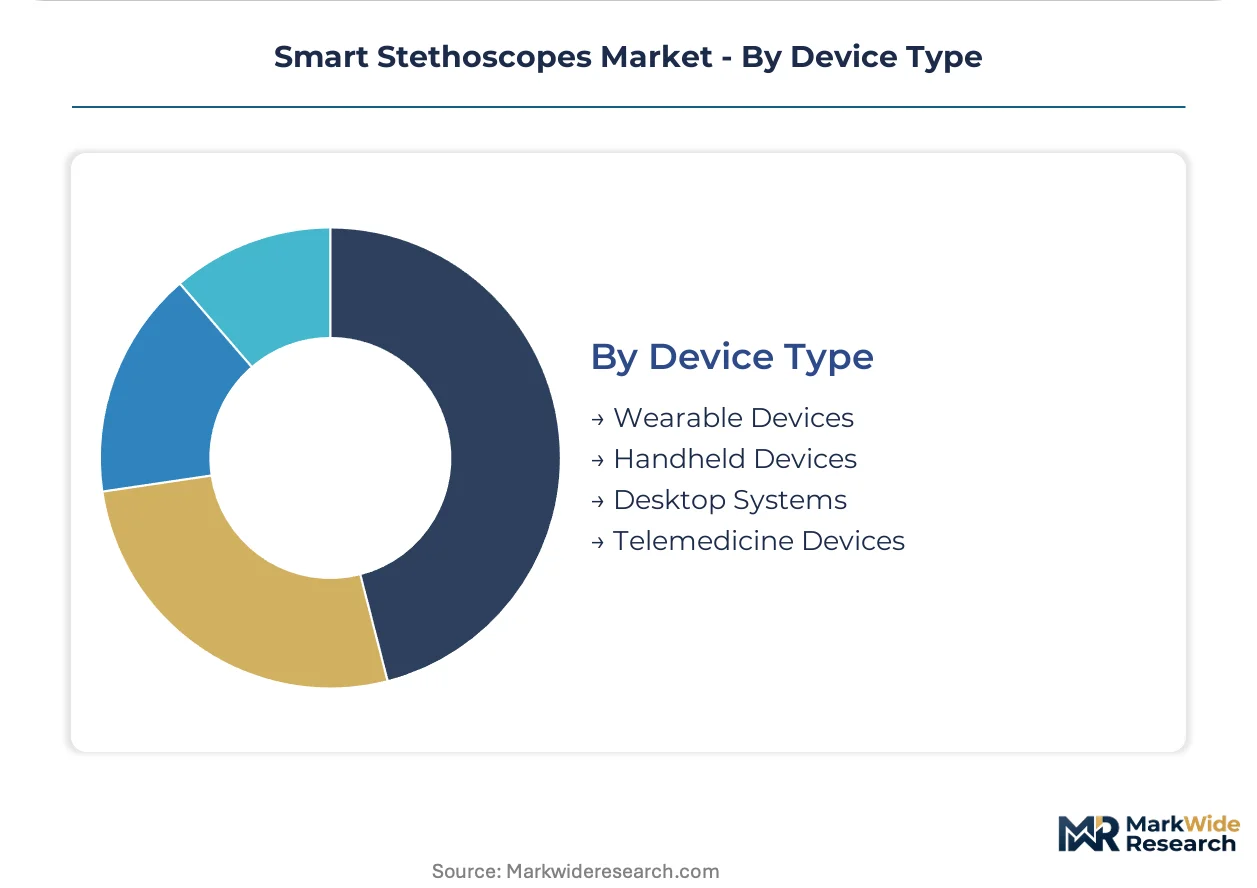
Device Type:
Physical form factors map to distinct clinical settings and user ergonomics, from continuous monitoring to episodic examination.
- Wearable Devices:Chest-worn sensor arrays enable longitudinal phonocardiography for quantitative cardiac monitoring beyond single-point auscultation.
- Handheld Devices:Physician familiarity and minimal workflow disruption sustain dominance in routine clinical examination, with piezoelectric sensor arrays now displacing electret microphones in premium tiers.
- Desktop Systems:Research-intensive academic medical centers deploy high-fidelity signal acquisition platforms for murmur localization studies at Cleveland Clinic and Mayo Clinic.
- Telemedicine Devices:Purpose-built configurations for virtual care networks incorporate single-lead ECG convergence enabling atrial fibrillation detection during routine cardiac auscultation.
Handheld devices command volume leadership; telemedicine devices gain share fastest on CMS reimbursement parity tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity for connected diagnostic devices concentrates in the United States, Germany, India, Japan, and China, with each jurisdiction deploying distinct regulatory frameworks and procurement incentives that shape local competitive dynamics.
United States
CMS reimbursement parity for remote auscultation accelerates hospital procurement of Bluetooth-enabled examination tools. FDA digital health pre-certification programs streamline AI algorithm updates for manufacturers maintaining real-world performance monitoring. The Greater Boston corridor hosts precision sensor development clusters serving academic medical centers at Massachusetts General and Brigham and Women's.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia drive demand for high-fidelity phonocardiography platforms. EU MDR conformity requirements impose clinical evidence burdens that favor established manufacturers with dedicated regulatory affairs teams. The Munich-Stuttgart industrial corridor concentrates MEMS microphone distribution infrastructure serving Central European device assembly.
India
Ayushman Bharat digital health mission procurement creates demand for offline-capable auscultation devices with asynchronous cloud upload. CDSCO medical device rules for software-enabled diagnostics establish conformity pathways distinct from hardware-only classifications. Bengaluru and Hyderabad clusters host firmware development centers supporting telemedicine hardware customization for tier-3 district hospital deployments.
Japan
PMDA accelerated review pathways for AI-embedded telemedicine hardware reduce time-to-market for algorithm-enhanced examination devices. METI funding for rural healthcare digitization subsidizes connected diagnostic tool procurement in prefectures with aging demographics. The Osaka-Kobe manufacturing belt maintains precision acoustic component fabrication for premium device tiers.
China
NMPA innovation approval channels for AI-assisted diagnostic devices enable faster market entry for phonocardiography algorithms with domestic clinical validation. Provincial hospital procurement consortia in Jiangsu and Guangdong consolidate purchasing power for connected examination device fleets. The Shenzhen electronics ecosystem supplies Bluetooth Low Energy module integration services at scale for regional device brands.
Smart Stethoscopes Market Key Industry Players
Medical technology conglomerates and precision sensor specialists split the market into distinct capability tiers. The vendor base organizes around three strategic archetypes: diversified health technology platforms with established distribution infrastructure, pure-play digital auscultation developers with algorithmic differentiation, and acoustic component specialists supplying transduction hardware across multiple device categories. Dominant competitive moves include strategic partnerships with telemedicine platform providers and backward integration into MEMS microphone supply chains.
Within the diversified platform tier, 3M and Solventum occupy positions anchored by established hospital procurement relationships and broad channel control. Eko Health, Inc. exemplifies the algorithm-centric archetype, with FDA-cleared AI positioning it within cardiac screening workflow integration. Thinklabs Medical LLC represents precision transduction specialization, serving research-intensive academic medical centers with high-fidelity signal acquisition requirements.
| Leading Market Players |
|---|
| HD Medical, Inc. |
| Solventum |
| Eko Health, Inc. |
| Welch Allyn |
| American Diagnostic Corporation |
| 3M |
| eKuore |
| M3DICINE Pty Ltd. |
| Thinklabs Medical LLC |
| Others |
Cost & Logistics Intelligence
Taiwan-based MEMS microphone foundry concentration anchors hardware cost structures and determines where margin pools accumulate downstream. Device manufacturers face 18-24 month qualification timelines for alternative sensor sources, entrenching pricing power with incumbent suppliers and compressing assembler margins on economy-tier products.
Pricing Analysis
FDA digital health pre-certification dictates the pricing tier structure across the smart stethoscope landscape. Three-tier pricing structure across premium, standard, and economy levels separates AI-embedded platforms with subscription SaaS from basic digital amplification models and legacy analog alternatives. Pricing pressure stems from EU MDR conformity costs adding substantial clinical evidence burdens for software-enabled variants. Academic medical centers demonstrate lowest price sensitivity due to research grant funding, while outpatient clinics in developing markets resist premium digital penetration.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and supply-chain finance facilities stabilize working capital for device assemblers facing long sensor qualification cycles. Component sourcing draws from Taiwan, China, and Japan for MEMS microphones, digital signal processors, and Bluetooth Low Energy modules. Single-source vulnerability in MEMS fabrication exposes manufacturers to geopolitical disruption. Distribution runs through hospital GPOs, Amazon health marketplaces, and direct academic medical center procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enabled diagnostic algorithms are compressing physician-specialist referral chains, creating a high-growth disruption justified by FDA's 2023 Digital Health Pre-Certification Program 1.1 slashing algorithm update review timelines.
For Market Incumbents: Build regulatory moats through FDA pre-certification enrollment and backward integration into MEMS microphone supply chains. Eko Health's algorithm-centric positioning demonstrates how AI workflow integration defends against hardware commoditization. 3M's Welch Allyn distribution arm shows channel control remains critical as hospital procurement committees consolidate vendor relationships around unified fleet management platforms. For New Entrants and Emerging Players: Rural India connectivity gaps under Ayushman Bharat represent the most penetrable entry point for offline-capable auscultation devices with asynchronous cloud upload. Direct-to-consumer channels through Amazon health marketplaces bypass entrenched GPO procurement for home health aides and concerned parents. Partner with telemedicine platform providers for virtual care network integration rather than competing for hospital IDN contracts. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-centric developers with FDA-cleared cardiac screening workflows and real-world performance monitoring capabilities. Long-term viability hinges on software subscription revenue layers atop hardware sales rather than transactional device margins. Watch for CMS reimbursement parity expansion signals as inflection indicators for telemedicine device demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Enrollment | Reduces algorithm update review timelines from 180 days to 60 days for enrolled organizations. |
| AI-ECG Convergence Development | Enables atrial fibrillation detection during routine cardiac auscultation, expanding reimbursable screening indications. |
| Hospital System Partnership | IDN consolidation markets demand API-standardized telemetry across cardiology and primary care device categories. |
| Software Companion Development | Subscription-based diagnostic support captures disproportionate margin pools beyond hardware sales alone. |
| Reimbursement Strategy | CMS remote auscultation parity accelerates procurement of connected stethoscopes for virtual care networks. |
Research Approach
Desk research of FDA 510(k) filings, CMS reimbursement databases, and hospital procurement records preceded structured interviews with cardiology department heads, biomedical engineers, GPO contracts managers, and telemedicine platform executives. Secondary validation drew from EU MDR technical documentation, PMDA review pathway disclosures, and CDSCO software-enabled diagnostic classifications. Bottom-up unit economics modeling triangulated against top-down health system digitization spending forecasts.
Assumptions held fixed include current FDA pre-certification program eligibility criteria and CMS reimbursement parity maintenance across the analysis window, while AI algorithm accuracy improvements and EU MDR transition timelines were varied parametrically. Segmentation dimensions modeled encompassed connectivity protocol, AI enhancement level, end-user setting, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to historical telemedicine device penetration patterns, with phonocardiography research demand and rural connectivity infrastructure buildout as key forecast inputs.
Practitioners should monitor FDA guidance evolution, EU MDR enforcement consistency, and Taiwan semiconductor supply stability for early signals. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Global Cardiac Restoration Systems Market