
 Medical Smart Stethoscopes Market | 2026-2036
Medical Smart Stethoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Smart Stethoscopes Market Insights
Semiconductor-grade MEMS microphones are consolidating as the dominant acoustic transducer in smart stethoscopes, displacing traditional piezoelectric crystals and cutting per-unit sensor costs by half while expanding frequency capture range. Eko Devices leverages vertical integration into cloud analytics to sustain recurring revenue from its provider subscriptions. Thinklabs Medical anchors its position through precision-engineered digital diaphragm technology that dominates high-fidelity cardiac auscultation segments. Welch Allyn competes on brand strength and hospital system channel control across integrated delivery networks.
Medical smart stethoscopes are electronic auscultation instruments incorporating digital signal processing, wireless connectivity, and machine learning algorithms to capture, amplify, record, and analyze heart and lung sounds with diagnostic-grade fidelity exceeding analog instruments by 40 dB in low-frequency response. Their primary purpose is to enable remote diagnosis, reduce inter-operator variability, and integrate physiological audio data into electronic health records. Bluetooth-enabled models occupy the largest installed base among wireless form factors, while AI-powered analysis segments attract the fastest-growing R&D allocation as cloud-based systems mature from novelty to clinical workflow standard. Smartphone-compatible stethoscopes currently lead direct-to-consumer channels but face margin pressure from OEM bundling strategies.
FDA premarket notification requirements under 510(k) pathways govern acoustic performance claims and algorithm diagnostic outputs, while HIPAA mandates shape data architecture decisions for cloud-connected devices. The EU MDR and CE marking frameworks impose additional clinical validation burdens on manufacturers seeking European market access. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring and decide whether to prioritize algorithm training on diverse population datasets or pursue faster regulatory clearance through narrow indication claims.
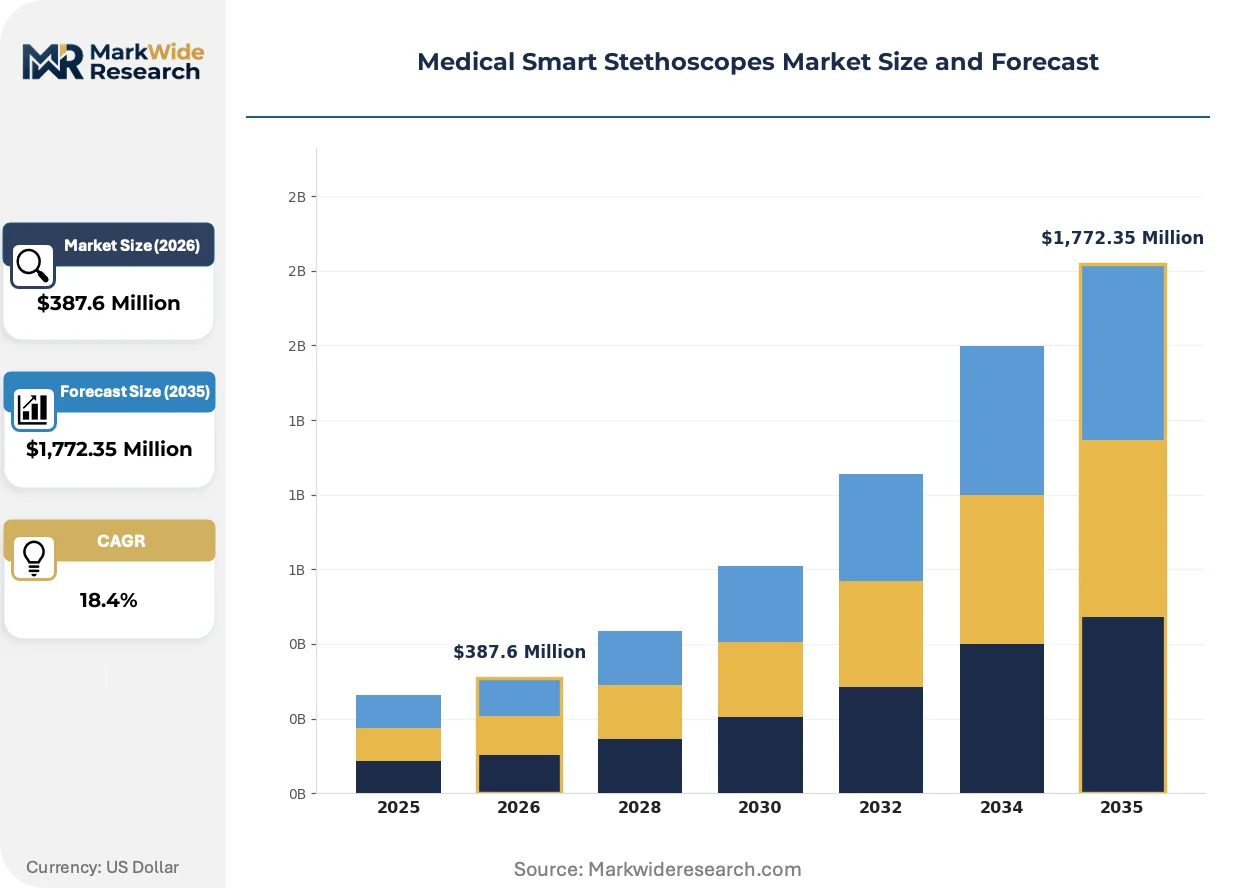
Market Dynamics
Hospital system digitization incentives and telehealth reimbursement codes are compressing replacement cycles for analog auscultation instruments, forcing manufacturers to restructure product roadmaps around wireless connectivity and algorithmic diagnostic outputs.
Growth Catalysts
- Telehealth reimbursement expansion:CMS billing codes for remote patient monitoring in the United States are reimbursing connected auscultation consultations at parity with in-person exams, accelerating hospital procurement of Bluetooth-enabled models.
- MEMS microphone maturation:Semiconductor foundries in Taiwan and South Korea are achieving yield rates above 90% for medical-grade acoustic sensors, halving per-unit transducer costs while extending frequency capture into infrasound ranges.
- FDA 510(k) pathway streamlining:The FDA's premarket notification framework for acoustic performance claims is compressing clearance timelines for algorithm-equipped stethoscopes, reducing regulatory friction for cloud-connected submissions.
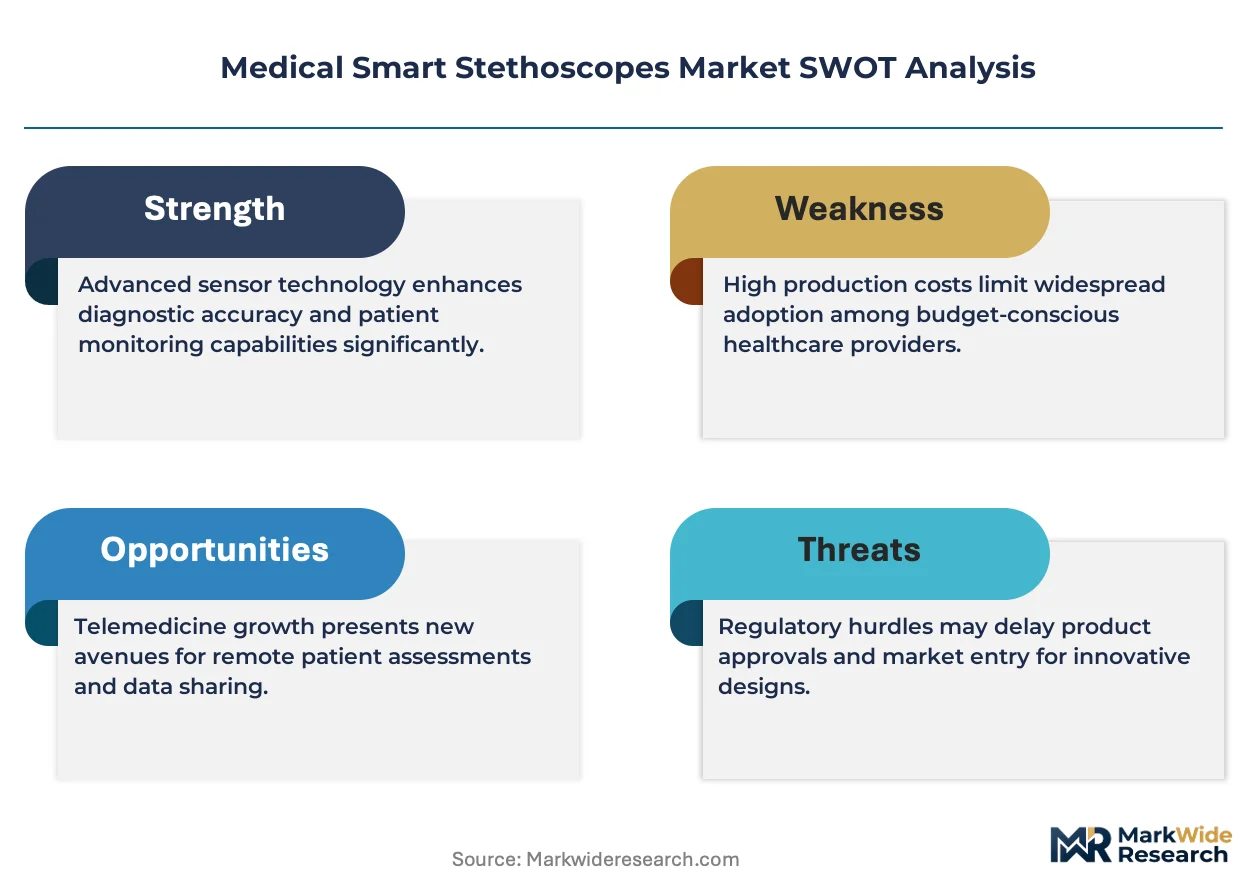
Market Restraints
- MEMS foundry concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control over 80% of advanced MEMS capacity, creating supply vulnerability for acoustic sensor procurement during geopolitical disruptions.
- EU MDR clinical validation burdens:The European Union's Medical Device Regulation imposes extended clinical evidence requirements on AI-diagnostic outputs, delaying market access for algorithm-dependent models by 18-24 months relative to acoustic-only devices.
- Smartphone acoustic substitution:Third-party microphone attachments paired with consumer handsets are capturing price-sensitive direct-to-consumer segments, compressing margins at the economy tier of dedicated digital stethoscopes.
Strategic Opportunities
- Rural India primary care digitization:The country's Ayushman Bharat Health and Wellness Centre program is equipping 150,000 rural clinics with connected diagnostic tools, creating volume demand for smartphone-compatible auscultation devices.
- AI-cardiology algorithm convergence:Integration of real-time murmur detection with automated ejection fraction estimation is enabling point-of-care cardiac screening in emergency departments without specialist availability.
- Subscription-based cloud analytics:Recurring revenue models for longitudinal heart sound monitoring are penetrating accountable care organizations seeking population health management tools for congestive heart failure cohorts.
Industry Challenges
- Interoperability with legacy EHR systems:HL7 FHIR implementation gaps in mid-tier hospital systems are forcing manual audio file uploads, degrading workflow integration and triggering user abandonment.
- Algorithm training dataset bias:Underrepresentation of valvular disease patterns in African and South Asian patient populations is producing diagnostic accuracy disparities that expose manufacturers to liability and regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Smart Stethoscopes Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Stethoscopes, Bluetooth Stethoscopes, Wireless Stethoscopes, Smartphone-Compatible Stethoscopes End User: Healthcare Professionals, Medical Students, Telehealth Providers, Emergency Responders Technology: Acoustic Technology, Electronic Technology, AI-Powered Analysis, Cloud-Based Systems Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Distributors |
| Companies Covered | 3M, American Diagnostic Corporation, Welch Allyn, Eko Devices, Cardionics, Thinklabs Medical, eKuore, HD Medical, Sonavi Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Smart Stethoscopes Market Trends and Innovations
Acoustic sensor miniaturization and edge computing deployment are converging to enable real-time cardiac analysis without cloud dependency, reshaping competitive differentiation around latency and data sovereignty rather than connectivity alone.
Semiconductor-grade MEMS microphones are rewriting the economics of diagnostic-grade auscultation. These silicon-fabricated transducers capture heart sounds across 20-2000 Hz with signal-to-noise ratios exceeding 60 dB. Cardiology departments in academic medical centers are standardizing on MEMS-equipped stethoscopes for telemedicine consultations. The technology is compressing the cost-performance frontier, enabling sub-$200 price points for FDA-cleared digital auscultation devices.
The FDA's evolving guidance on machine learning-enabled medical devices is creating regulatory clarity for adaptive algorithms. Premarket submission requirements now explicitly address continuous learning protocols and locked-model updates. Cloud-connected stethoscope manufacturers are responding by architecting frozen algorithm versions for 510(k) clearance while maintaining separate development branches for post-market performance improvements.
Hospital procurement committees are consolidating vendor relationships through integrated delivery network contracting. Single-source agreements covering diagnostic devices, software licenses, and analytics subscriptions are displacing point-product purchases. This concentration is most pronounced in United States health systems exceeding 50 hospitals, where standardization incentives override individual physician equipment preferences.
Medical Smart Stethoscopes Market Segmentation
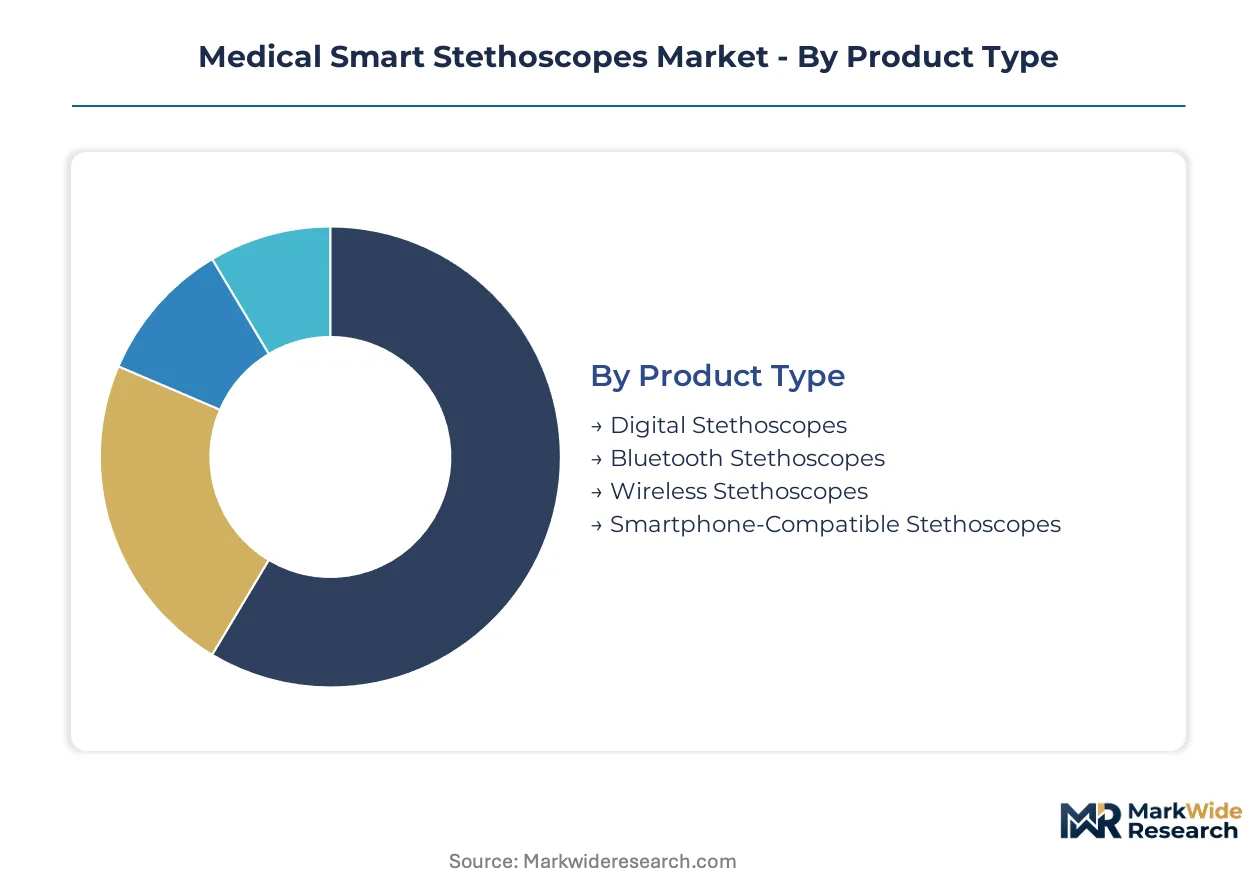
Smart stethoscope procurement decisions diverge sharply across clinical settings, with connectivity requirements and algorithmic sophistication driving distinct purchasing workflows. Understanding these segment boundaries enables manufacturers to align R&D investment with reimbursement pathways and channel economics.
Product Type:
Hospital procurement committees weigh acoustic fidelity against integration costs when selecting among wireless form factors, with connectivity standards and EHR compatibility dominating capital allocation decisions.
- Digital Stethoscopes:Standalone units with onboard amplification and digital recording store heart sound files locally for later EHR upload. Cardiology departments in academic medical centers standardize on these for their 40 dB low-frequency response advantage over analog instruments.
- Bluetooth Stethoscopes:Wireless audio streaming to tablets or workstations enables real-time telemedicine consultations without cable constraints. These occupy the largest installed base among connected models, driven by CMS reimbursement parity for remote patient monitoring in the United States.
- Wireless Stethoscopes:Broader connectivity protocols including Wi-Fi and proprietary hospital networks support enterprise deployment at scale. These integrate with existing infrastructure in integrated delivery networks exceeding 50 hospitals.
- Smartphone-Compatible Stethoscopes:Compact acoustic attachments leverage consumer handset processing power and display capabilities. Direct-to-consumer channels favor these for price accessibility, though OEM bundling strategies compress margins at the economy tier.
Bluetooth-enabled models lead on scale; smartphone-compatible configurations gain share fastest through primary care digitization programs.
End User:
Clinical workflow intensity and diagnostic accountability requirements shape feature prioritization across user categories, from high-stakes emergency decisions to educational skill acquisition.
- Healthcare Professionals:Physicians and nurses in hospital and clinic settings require FDA-cleared devices with validated algorithmic outputs for liability protection. These users drive demand for AI-powered murmur detection and automated documentation features.
- Medical Students:Training programs prioritize cost-effective digital auscultation tools with standardized sound libraries for comparative learning. Institutions bulk-purchase through educational distributors, creating volume concentration distinct from clinical procurement patterns.
- Telehealth Providers:Remote consultation platforms demand seamless audio transmission and cloud-based storage for asynchronous specialist review. Reimbursement code expansion for connected auscultation accelerates adoption in accountable care organizations.
- Emergency Responders:Field-deployable units with ruggedized construction and extended battery life support pre-hospital cardiac assessment. These users prioritize durability and rapid deployment over algorithmic sophistication.
Healthcare professionals anchor revenue concentration; telehealth providers expand most quickly as reimbursement frameworks mature.
Technology:
Sensor architecture and processing location decisions determine regulatory pathway complexity and recurring revenue potential for manufacturers.
- Acoustic Technology:Traditional diaphragm-and-tube designs enhanced with electronic amplification preserve familiar clinical ergonomics while adding digital recording. These serve price-sensitive segments and regulatory environments with limited AI validation infrastructure.
- Electronic Technology:Piezoelectric or MEMS transducers convert sound waves to electrical signals with extended frequency capture. MEMS-equipped models are consolidating as the dominant acoustic transducer, cutting per-unit sensor costs by half while expanding infrasound detection.
- AI-Powered Analysis:Machine learning algorithms trained on heart sound datasets enable real-time murmur classification and severity scoring. These attract the fastest-growing R&D allocation as cloud-based systems mature from novelty to clinical workflow standard.
- Cloud-Based Systems:Audio processing and longitudinal storage on remote servers enable population-scale analytics and algorithm updates. HIPAA mandates shape data architecture decisions for manufacturers serving United States health systems.
Electronic technology dominates unit economics; AI-powered analysis commands the steepest expansion trajectory as FDA guidance clarifies adaptive algorithm pathways.
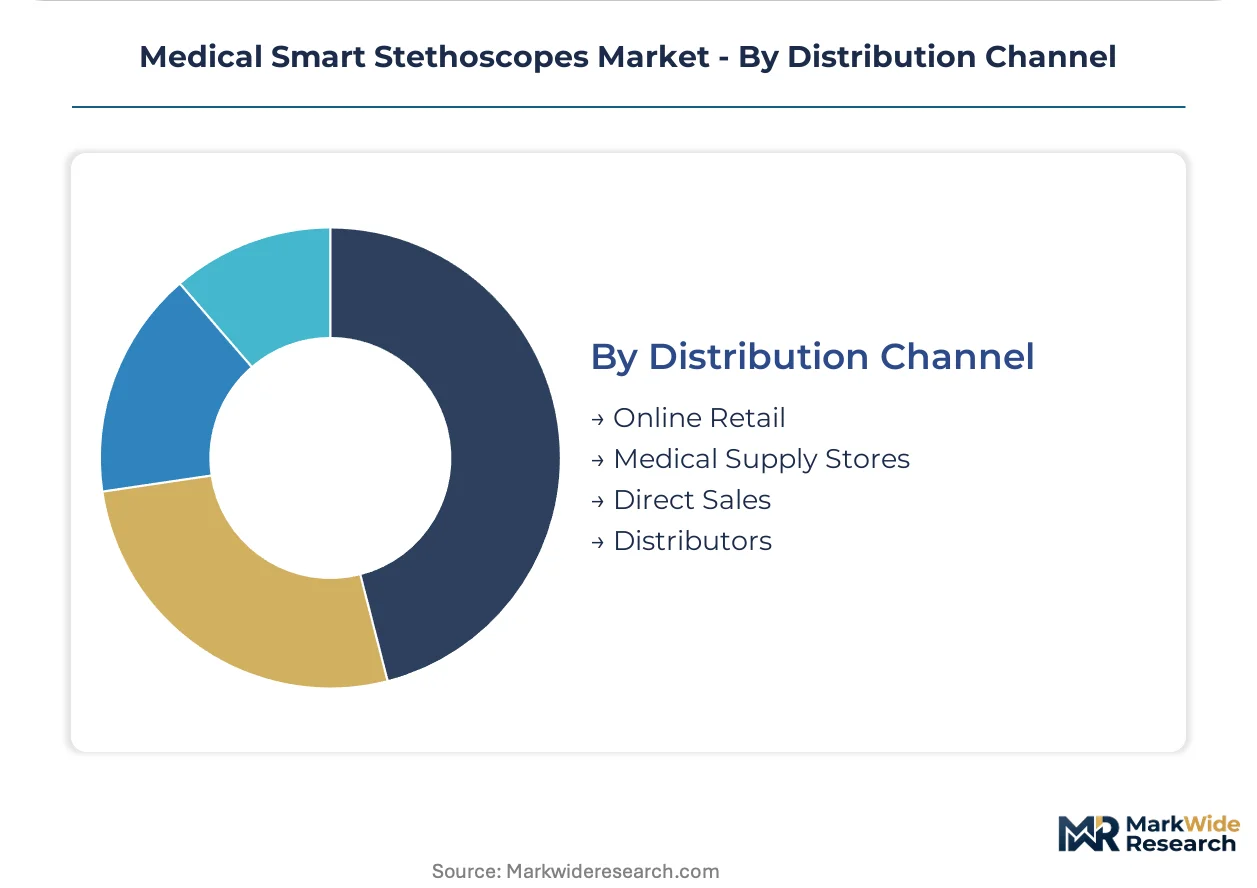
Distribution Channel:
Channel selection determines margin structure and customer relationship depth, with institutional procurement consolidating toward integrated vendor agreements.
- Online Retail:E-commerce platforms serve direct-to-consumer segments and small-practice purchasers with transparent pricing and rapid fulfillment. These channels capture smartphone-compatible stethoscope demand but lack clinical workflow integration support.
- Medical Supply Stores:Regional distributors with field sales representation provide hands-on demonstration and immediate availability for urgent replacement needs. These maintain relevance in mid-tier hospital systems with decentralized purchasing authority.
- Direct Sales:Manufacturer field teams negotiate enterprise agreements with integrated delivery networks and academic medical centers. Single-source contracts covering devices, software licenses, and analytics subscriptions displace point-product purchases in systems exceeding 50 hospitals.
- Distributors:Specialized medical device wholesalers manage logistics, regulatory documentation, and credit terms for international markets. These channels navigate EU MDR clinical validation burdens that delay algorithm-dependent models by 18-24 months relative to acoustic-only devices.
Direct sales capture the highest-value institutional contracts; online retail scales most rapidly in emerging market consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley clusters anchor digital health device innovation, while hospital digitization incentives and regulatory clarity concentrate demand in specific national markets. Procurement patterns diverge sharply between reimbursement-rich health systems and emerging market volume plays.
United States
Hospital system digitization incentives from CMS accelerate replacement of analog instruments in integrated delivery networks. FDA 510(k) pathway streamlining compresses clearance timelines for algorithm-equipped models, reducing regulatory friction for cloud-connected submissions. The Boston-Cambridge corridor concentrates AI-cardiology algorithm development for point-of-care screening tools.
Germany
Precision-engineered medical device manufacturing sustains demand for high-fidelity cardiac auscultation segments. EU MDR clinical validation burdens impose extended evidence requirements on AI-diagnostic outputs, delaying market access relative to acoustic-only devices. The Baden-Württemberg industrial cluster hosts MEMS sensor integration specialists serving diagnostic equipment manufacturers.
China
Domestic semiconductor foundries are scaling medical-grade MEMS microphone production to reduce import dependency for acoustic transducers. NMPA regulatory frameworks for AI-enabled diagnostic devices are evolving toward alignment with international clearance standards. Shenzhen hardware ecosystems enable rapid prototyping of smartphone-compatible auscultation attachments for price-sensitive segments.
India
The Ayushman Bharat Health and Wellness Centre program equips rural clinics with connected diagnostic tools, creating volume demand for smartphone-compatible devices. CDSCO regulatory pathways for electronic stethoscopes remain less burdensome than algorithm-validation requirements in Western markets. Karnataka's Bengaluru tech corridor anchors telehealth platform development integrating remote auscultation capabilities.
Japan
Aging demographics and specialist physician shortages drive adoption of AI-assisted cardiac screening in community hospitals. PMDA guidance on machine learning-enabled medical devices creates regulatory clarity for adaptive algorithm submissions. The Tokyo-Osaka medical device corridor concentrates distribution partnerships for Asia-Pacific market expansion.
Medical Smart Stethoscopes Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance capabilities and channel control in integrated delivery networks. The vendor base fragments across technology archetypes—semiconductor-integrated platforms, precision acoustic engineering specialists, and cloud-analytics subscription providers. Three strategic archetypes dominate: MEMS-vertically integrated players, algorithm-first digital health startups, and incumbent diagnostic device manufacturers with hospital system relationships. Competitive moves concentrate on M&A for AI talent acquisition and strategic partnerships for EHR interoperability.
Within the algorithm-first tier, Eko Devices and Thinklabs Medical exemplify divergent positioning strategies—one toward cloud analytics recurring revenue, the other toward precision-engineered acoustic fidelity. Welch Allyn anchors the incumbent manufacturer archetype with channel control across United States health systems. These three companies occupy positions spanning the technology-to-distribution spectrum without overlapping core competencies.
| Leading Market Players |
|---|
| 3M |
| American Diagnostic Corporation |
| Welch Allyn |
| Eko Devices |
| Cardionics |
| Thinklabs Medical |
| eKuore |
| HD Medical |
| Sonavi Labs |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees in integrated delivery networks exceeding 50 hospitals command three-tier pricing structure across premium, standard, and economy levels, with MEMS sensor cost trajectories compressing mid-tier margins fastest.
Pricing Analysis
MEMS microphone yield improvements at Taiwan Semiconductor Manufacturing and Samsung Foundry pass through to device manufacturers at roughly half prior sensor costs. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance status and algorithmic diagnostic capability. Cost compression in smartphone-compatible attachments intensifies because third-party microphone peripherals capture price-sensitive direct-to-consumer segments. Medical students and rural primary care programs exhibit highest price sensitivity; cardiology departments in academic medical centers show lowest sensitivity due to reimbursement parity for remote patient monitoring.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced MEMS fabrication, where two foundries control over four-fifths of medical-grade acoustic sensor capacity. Device assembly draws from China for smartphone-compatible housings, Mexico for North American market fulfillment, and Germany for precision-engineered digital diaphragm components. Tariff exposure on semiconductor inputs from East Asia threatens margin stability for manufacturers without captive supply arrangements. Distribution runs through specialized medical device wholesalers navigating EU MDR clinical validation burdens, direct sales teams capturing integrated delivery network contracts, and online retail for consumer-facing configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Smart Stethoscopes Market functions as a regulatory compounder where FDA 510(k) pathway streamlining for algorithm-equipped models accelerates demand concentration among cloud-connected device manufacturers.
For Market Incumbents: Anchor hospital system relationships through single-source contracts spanning devices, software licenses, and analytics subscriptions to defend against algorithm-first digital health startups. Deepen backward integration into MEMS sensor procurement to offset foundry concentration risk. Prioritize HL7 FHIR interoperability investment to prevent user abandonment from manual EHR upload friction. For New Entrants and Emerging Players: Capture the Ayushman Bharat Health and Wellness Centre program in rural India through smartphone-compatible form factors priced for volume procurement. Target emergency responder segments with ruggedized hardware where algorithmic sophistication matters less than durability and battery life. Pursue direct sales partnerships with telehealth platforms seeking asynchronous specialist review capabilities. For Investors and Strategic Acquirers: Hospital systems pursuing population health management tools are the most active acquirer in this space, seeking longitudinal heart sound monitoring capabilities for congestive heart failure cohorts. Long-term viability hinges on recurring revenue conversion from device sales to cloud analytics subscriptions. Watch for CDSCO regulatory pathway evolution in India as a signal for emerging market algorithm-validation standardization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | FDA clearance for AI-enhanced murmur detection unlocks CMS reimbursement parity and accelerates hospital procurement cycles. |
| CE Marking Pathway | EU MDR clinical validation for algorithmic outputs enables market access across German precision manufacturing clusters. |
| Hospital System Partnership | Integrated delivery network contracts displace point-product purchases and lock out competing vendors through standardization incentives. |
| Software Companion Development | Cloud analytics subscriptions convert one-time device revenue into recurring population health management income streams. |
| Reimbursement Strategy | Remote patient monitoring billing codes from CMS determine pricing power and procurement urgency across United States health systems. |
Research Methodology
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and telehealth platform operators grounds this analysis in clinical workflow realities. Secondary validation draws from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR submission documentation. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Segment-level outputs reflect product type, end user category, technology architecture, and distribution channel dynamics throughout the forecast period. CAGRs derive from algorithmic adoption curves, MEMS cost trajectories, and regulatory clearance velocity assumptions. Forecast inputs incorporate FDA guidance evolution on machine learning-enabled devices and CMS remote patient monitoring code expansion.
Geopolitical disruption to MEMS foundry operations, EU MDR implementation delays, and smartphone acoustic substitution acceleration are the dominant revision risks to modeled outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market