
 Connected Diagnostics Market | 2026-2036
Connected Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Diagnostics Market Outlook
Aftermarket service revenue is narrowing as hardware margins compress and vendors shift toward recurring platform fees. Medtronic leverages its installed base of cardiac devices to secure long-term monitoring contracts. Philips Healthcare anchors its position through enterprise imaging integration with remote diagnostic workflows. Abbott Laboratories differentiates via vertically controlled sensor manufacturing that reduces component dependency.
Connected diagnostics encompass distributed medical devices and software platforms that transmit physiological data through encrypted networks to centralized analysis systems, typically operating with latency thresholds under 500 milliseconds for real-time clinical alerts. Their primary purpose enables continuous patient surveillance outside traditional care settings while triggering automated clinical decision support. Point-of-Care Systems command the largest installed base due to emergency department throughput demands, though AI Analytics within the technology dimension captures expanding margin pools as payers condition reimbursement on predictive outcome documentation. Wearable Devices face stiffer regulatory scrutiny than Home Monitoring Devices, creating a bifurcation in go-to-market timelines between consumer-facing and clinically validated product tiers.
The FDA's software-as-a-medical-device guidance and HIPAA interoperability mandates jointly determine which platforms qualify for clinical reimbursement versus wellness categorization in the United States. The EU AI Act and MDR cybersecurity annexes impose additional conformity requirements on cloud-connected diagnostic systems seeking European market access. Stakeholders must decide whether to absorb multi-jurisdiction compliance costs or constrain geographic scope to single-regulatory-domain deployments.
Market Dynamics
The Connected Diagnostics Market pivots on a fundamental restructuring of reimbursement logic, where payers now predicate coverage on documented predictive outcomes rather than device deployment alone. This shift compresses hardware margins while elevating software platforms that demonstrate measurable clinical utility.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The FDA's SaMD guidance creates a streamlined approval pathway for algorithm-driven diagnostic tools, accelerating commercialization timelines for cloud-connected platforms in cardiology and diabetes management.
- Integrated Delivery Network Consolidation:Hospital systems across the United States are consolidating vendor relationships around single-platform solutions, creating pull-through demand for enterprise-scale remote monitoring deployments.
- AI-Powered Clinical Decision Support:Machine learning algorithms embedded in diagnostic workflows now enable real-time risk stratification, satisfying payer demands for outcome documentation while reducing emergency department readmissions.
Market Restraints
- Multi-Jurisdiction Compliance Burden:Simultaneous adherence to FDA SaMD requirements, EU AI Act conformity assessments, and MDR cybersecurity annexes forces vendors to absorb substantial regulatory overhead or forfeit market access.
- Component Supply Concentration:Specialized biosensor manufacturing concentrates in East Asian foundries, exposing device makers to geopolitical disruption and input cost volatility for MEMS-based physiological sensors.
- Latency Infrastructure Requirements:Real-time clinical alert thresholds under 500 milliseconds demand edge computing investments that many regional health systems lack capital to deploy.
Strategic Opportunities
- Underpenetrated Rural Health Networks:Federally Qualified Health Centers in the United States remain underserved by connected diagnostic platforms, presenting white space for telehealth-integrated remote monitoring solutions.
- EU AI Act Compliance Services:The conformity assessment mandate for high-risk AI medical devices creates adjacent revenue streams in regulatory consulting and automated documentation tooling.
- Wearable-Home Monitoring Convergence:Hybrid form factors combining consumer wearable aesthetics with clinical-grade validation are capturing patients who resist traditional medical device stigma.
Industry Challenges
- Interoperability Engineering Talent Scarcity:Health systems struggle to recruit engineers proficient in both HL7 FHIR standards and legacy EHR architectures, delaying platform integration timelines.
- Legacy Device Retrofit Complexity:Installed bases of non-connected diagnostic equipment require expensive hardware modifications or parallel data capture systems to achieve network integration.
- Algorithm Bias Validation:Demonstrating equitable performance across demographic subgroups demands expanded clinical trials that extend development cycles and inflate regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Diagnostics Market |
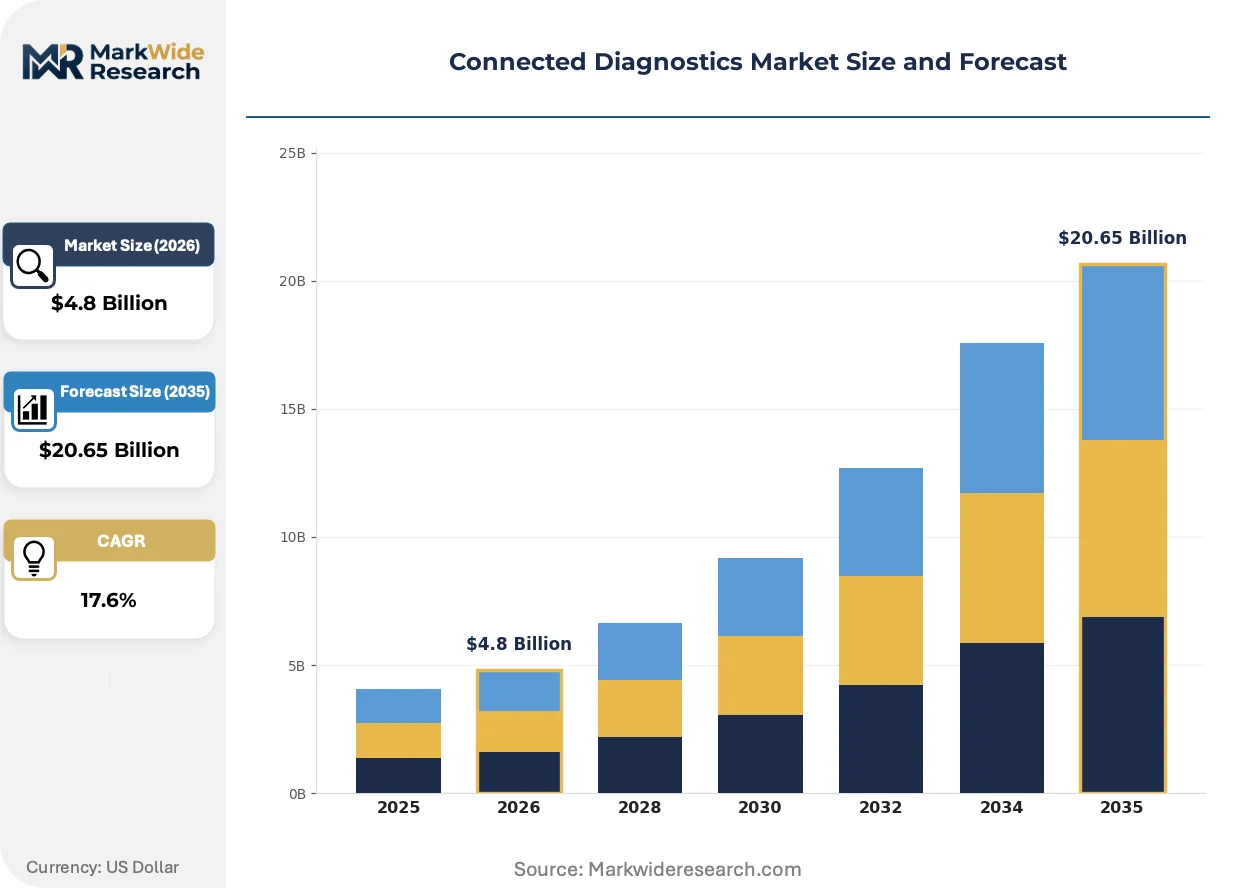
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Point-of-Care Systems, Home Monitoring Devices, Mobile Applications Technology: Telemedicine, Cloud Computing, AI Analytics, IoT Sensors End User: Healthcare Providers, Patients, Research Institutions, Insurance Companies Application: Chronic Disease Management, Health Monitoring, Lab Results Reporting, Data Analytics |
| Companies Covered | Medtronic, Philips Healthcare, Honeywell International, Abbott Laboratories, GE Healthcare, Siemens Healthineers, Cerner Corporation, IBM Watson Health, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Diagnostics Market Strategic Shifts
Algorithmic diagnostic capabilities are compressing the traditional hierarchy between centralized laboratories and distributed point-of-care devices, redistributing clinical authority toward edge-based analysis systems.
Edge AI inference engines are collapsing the latency gap between physiological signal capture and clinical alert generation. Cardiac monitoring platforms now deploy tensor processing units directly within implantable devices, enabling arrhythmia detection without cloud round-trips. Hospital emergency departments are adopting these systems to bypass network congestion during critical events.
EU AI Act risk classification mandates are restructuring product development roadmaps for cloud-connected diagnostic systems. High-risk algorithm categories now require conformity assessments from notified bodies before European market entry, forcing vendors to front-load clinical validation. Wearable device manufacturers with wellness-tier products face bifurcated compliance strategies to avoid reclassification.
Integrated delivery networks are unbundling hardware procurement from ongoing monitoring services, separating capital expenditure from operational budgets. This purchasing pattern favors platform vendors offering subscription-based clinical surveillance over traditional device sellers. The United States exhibits the most pronounced shift, where value-based care contracts incentivize longitudinal patient relationships over episodic device sales.
Connected Diagnostics Market Segmentation
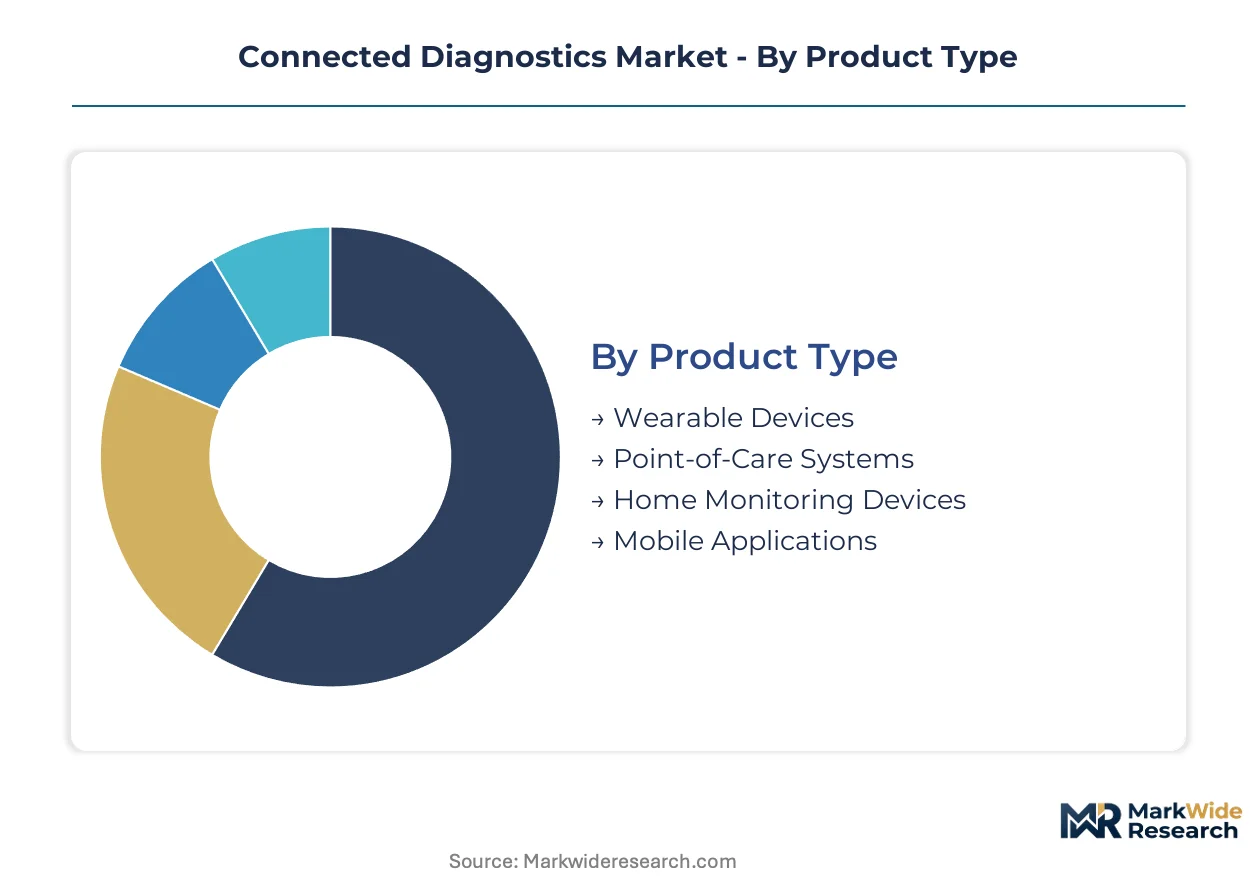
Connected diagnostics vendors structure their service portfolios around the intensity of ongoing clinical support each segment demands. Product lifecycle economics diverge sharply between hardware-centric and software-heavy categories, reshaping how companies allocate engineering resources and field service teams.
Product Type:
After-sales service intensity varies dramatically across form factors, with implantable and clinic-embedded systems requiring continuous calibration support while consumer-facing products rely on remote troubleshooting.
- Point-of-Care Systems:Emergency department throughput demands drive installed base concentration. These systems integrate multiplexed biosensors with encrypted data transmission to central laboratories. Demand concentrates in United States integrated delivery networks where throughput metrics determine capital allocation. FDA SaMD compliance requirements extend service contract durations.
- Wearable Devices:Continuous physiological monitoring through skin-contact biosensors enables ambulatory cardiac surveillance. Regulatory scrutiny from FDA and EU AI Act risk classifications creates bifurcated go-to-market timelines between wellness-tier and clinical-grade products. United States payers increasingly condition reimbursement on predictive outcome documentation.
- Home Monitoring Devices:Stationary diagnostic hubs connect patients to remote clinical teams through cellular or broadband links.
- Mobile Applications:Software-only platforms deliver algorithm-driven risk stratification through consumer smartphones.
By volume, Point-of-Care Systems leads. By growth pace, Wearable Devices is ahead.
Technology:
Margin architecture separates infrastructure-heavy modalities from algorithm-centric layers, with recurring platform fees concentrating in analytics while hardware-dependent segments face compressing unit economics.
- AI Analytics:Machine learning pipelines process physiological signals into clinical risk scores with documented predictive accuracy. These platforms capture expanding margin pools as United States payers mandate outcome documentation for reimbursement eligibility. EU AI Act high-risk classifications impose conformity assessment costs that favor established vendors.
- IoT Sensors:MEMS-based physiological capture devices transmit encrypted data through low-latency networks. East Asian foundry concentration for specialized biosensor manufacturing exposes supply chains to geopolitical disruption. Real-time clinical alert thresholds under 500 milliseconds demand edge computing infrastructure investments.
- Telemedicine:Synchronous video and asynchronous store-and-forward platforms connect patients with remote clinicians.
- Cloud Computing:HIPAA-compliant and GDPR-aligned data architectures enable centralized multi-tenant diagnostic processing.
By revenue concentration, AI Analytics dominates. By infrastructure investment intensity, IoT Sensors requires the heaviest capital deployment.
End User:
Procurement authority patterns fragment across budget ownership, with operational expenditure favoring subscription models and capital expenditure preserving traditional device purchasing.
- Healthcare Providers:Hospital systems and physician networks deploy enterprise-scale platforms for longitudinal patient surveillance. United States value-based care contracts incentivize these stakeholders toward subscription-based clinical monitoring over episodic device sales. Interoperability engineering talent scarcity delays HL7 FHIR integration timelines.
- Patients:Direct-to-consumer demand concentrates in chronic disease populations seeking reduced clinic visit burden. Hybrid form factors combining wearable aesthetics with clinical validation capture users resisting traditional medical device stigma. Out-of-pocket payment sensitivity shapes price elasticity.
- Insurance Companies:Payers predicate coverage on documented predictive outcomes, elevating platforms with measurable clinical utility.
- Research Institutions:Academic medical centers utilize connected diagnostics for decentralized clinical trial execution and real-world evidence generation.
By contract value, Healthcare Providers anchors revenue. By expansion velocity, Patients represents the steepest growth trajectory.
Application:
Clinical workflow integration depth determines platform stickiness, with embedded decision support commanding premium pricing against standalone data presentation tools.
- Chronic Disease Management:Diabetes, heart failure, and hypertension programs utilize continuous glucose monitors, implantable cardiac devices, and blood pressure telemetry. Hospital networks expand remote patient monitoring platforms for these populations. Algorithm bias validation demands across demographic subgroups inflate regulatory submission costs.
- Health Monitoring:Preventive surveillance platforms stratify asymptomatic populations for early intervention. Federally Qualified Health Centers in United States rural areas remain underserved, presenting white space for telehealth-integrated solutions. Wellness-tier products face stiffer regulatory scrutiny than clinically validated alternatives.
- Lab Results Reporting:Automated distribution of diagnostic findings to patients and care teams through secure portals.
- Data Analytics:Population-level aggregation of connected diagnostic outputs for health system quality improvement initiatives.
By installed base, Chronic Disease Management leads. By platform innovation rate, Health Monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks deploy connected diagnostics for longitudinal chronic disease management, while European health systems prioritize regulatory-compliant AI validation and German manufacturers emphasize edge computing integration for latency-sensitive cardiac alerts.
United States
Integrated delivery networks consolidate vendor relationships around single-platform solutions for remote patient monitoring. FDA software-as-a-medical-device guidance accelerates approval pathways for algorithm-driven diagnostic tools in cardiology and diabetes management. The Mayo Clinic in Rochester anchors enterprise imaging integration with remote diagnostic workflows.
Germany
Siemens Healthineers and regional hospital networks drive demand for AI-powered clinical decision support systems. EU AI Act high-risk classifications and MDR cybersecurity annexes impose conformity assessment requirements on cloud-connected diagnostic platforms. The Munich medical technology cluster concentrates edge AI inference engine development for implantable cardiac devices.
China
Hospital networks expand remote patient monitoring platforms for chronic disease populations in tier-one cities. NMPA medical device regulations and MIIT data localization requirements shape cloud architecture decisions for diagnostic platforms. The Shanghai Zhangjiang Hi-Tech Park hosts biosensor manufacturing facilities serving domestic and export markets.
Japan
Aging demographics and rural health access gaps accelerate adoption of home monitoring devices and telemedicine platforms. PMDA software medical device guidance and METI digital health initiatives support reimbursement qualification for predictive outcome documentation. The Kansai region around Osaka concentrates MEMS-based physiological sensor production.
United Kingdom
NHS long-term plan commitments expand remote monitoring for heart failure and chronic obstructive pulmonary disease patients. MHRA recognition of FDA-approved SaMD tools streamlines market entry for US-platform vendors. The Cambridge life sciences cluster advances algorithm bias validation research for equitable AI diagnostic performance.
Connected Diagnostics Market Competitive Environment
Capability concentration sits with integrated device-platform vendors; scale advantage sits with diversified health technology conglomerates. The market structure tiers around three strategic archetypes: implantable device specialists leveraging installed bases for recurring monitoring contracts, enterprise imaging vendors anchoring hospital system relationships, and vertically integrated sensor manufacturers controlling component supply chains. Dominant competitive moves include strategic partnerships for interoperability certification and portfolio diversification into AI analytics layers.
Within the integrated device-platform tier, Medtronic and Abbott Laboratories exemplify contrasting approaches to securing long-term monitoring revenue. Philips Healthcare occupies a position bridging enterprise imaging hardware with subscription-based clinical surveillance services. These three anchors represent the dominant competitive vectors: cardiac implantable ecosystems, vertically controlled biosensor supply, and hospital system platform consolidation.
| Leading Market Players |
|---|
| Medtronic |
| Philips Healthcare |
| Honeywell International |
| Abbott Laboratories |
| GE Healthcare |
| Siemens Healthineers |
| Cerner Corporation |
| IBM Watson Health |
| Koninklijke Philips |
| Others |
Value Chain & Pricing Dynamics
East Asian MEMS foundry concentration for specialized biosensors anchors cost structures across device tiers, pushing margin pools toward algorithm layers that escape component volatility. Contract structures bifurcate between capital-intensive hardware procurement and recurring platform fees, with integrated delivery networks unbundling these to shift budget ownership from capital to operational expenditure.
Pricing Analysis
Long-term service contracts dominate enterprise procurement, separating device capital expenditure from subscription-based clinical surveillance. Three-tier pricing structure across premium, standard, and economy levels reflects FDA SaMD certification grade and after-sales calibration intensity. Pricing pressure stems from hardware margin compression as vendors absorb multi-jurisdiction compliance costs. Federally Qualified Health Centers exhibit highest price sensitivity due to constrained operational budgets, while academic medical centers prioritize interoperability certification over unit cost.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit MEMS biosensor foundry expansion outside East Asia, concentrating specialized physiological sensor production in Taiwan, South Korea, and Japan. Supply chains draw from germanium substrates, precision photolithography equipment, and biocompatible packaging polymers. Single-source vulnerability concentrates in EUV lithography dependencies for next-generation edge AI inference chips. Distribution runs through hospital system GPO contracts and direct-to-patient cellular-enabled device fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive returns as interoperability certification becomes the gating factor for enterprise scale. The HL7 FHIR ecosystem shift from legacy EHR architectures creates winner-take-most dynamics for vendors achieving hospital system integration.
For Market Incumbents: Entrench installed base relationships through long-term monitoring contract extensions that bundle algorithm updates with hardware refresh cycles. Prioritize backward integration into MEMS biosensor manufacturing to reduce East Asian foundry exposure. Defend against emerging AI-native entrants by accelerating FDA SaMD submissions for predictive outcome documentation that payers now mandate.
For New Entrants and Emerging Players: Build out telehealth-integrated remote monitoring solutions for Federally Qualified Health Centers in United States rural networks, the most penetrable white space underserved by incumbent platforms. Target hybrid wearable-home monitoring convergence form factors that reduce patient stigma barriers. Pursue EU AI Act conformity assessment partnerships as a differentiated go-to-market angle for European market entry.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated device-platform vendors with captive biosensor supply and established hospital system relationships, the archetype best positioned for the platform economics inflection. Long-term viability hinges on recurring revenue share exceeding hardware transactional exposure. Watch FDA SaMD approval velocity as the signal indicating which algorithm layers achieve reimbursement qualification versus wellness-tier commoditization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission Acceleration | Streamlines algorithm-driven diagnostic approval pathways for cardiology and diabetes management platforms. |
| Hospital System Partnership | Secures integrated delivery network consolidation around single-platform remote monitoring deployments. |
| Backward Integration into MEMS Manufacturing | Reduces East Asian foundry dependency for specialized physiological sensors and biosensor components. |
| EU AI Act Conformity Assessment | Enables European market access for high-risk algorithm categories through notified body certification. |
| Software Companion Development | Extends implantable device ecosystems with AI-powered clinical decision support for longitudinal surveillance. |
Study Parameters
The analysis maps point-of-care systems, wearable devices, home monitoring hubs, and AI analytics platforms, each validated through biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads. Primary interviews with these stakeholders combined secondary sources including FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body conformity assessments. Bottom-up unit economics triangulated against top-down integrated delivery network spending patterns.
Assumptions held fixed include FDA SaMD guidance continuity, HIPAA interoperability mandate timelines, and EU AI Act risk classification thresholds; variables tested included reimbursement qualification velocity and MEMS foundry capacity expansion. Segmentation dimensions modeled encompass product form factor, technology layer, end-user procurement authority, and clinical application intensity. CAGRs derived from installed base growth curves and platform fee expansion trajectories across the analysis window, with edge computing infrastructure investment cycles and algorithm bias validation costs as key forecast inputs.
Stress conditions across FDA approval timelines, EU notified body capacity, and East Asian export control enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in payer reimbursement logic toward wellness-tier categorization or geopolitical disruption of MEMS supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Creatinine Test Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Elisa Tests Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global Fecal Occult Blood Tests Market