
 Asia-Pacific Cardiac Monitoring Market | 2026-2036
Asia-Pacific Cardiac Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cardiac Monitoring Market Outlook
A wide capability gap between capital-intensive multinationals and regional specialists is reorganizing competitive dynamics in Asia-Pacific cardiac monitoring. Medtronic leverages integrated manufacturing networks to sustain premium positioning across implantable monitor segments. Abbott Laboratories anchors its presence through diagnostic-to-interventional device portfolios that span hospital and ambulatory settings. MicroPort Scientific Corporation competes on localized cost structures and regulatory familiarity within China's domestic market.
Asia-Pacific cardiac monitoring encompasses electrophysiological sensing systems, implantable loop recorders, and telemetry platforms that capture heart rhythm data through surface electrodes, lead wires, or wireless transceivers for clinical diagnosis and longitudinal patient management. ECG Systems and Implantable Monitors command the largest installed bases, while Wearable Devices and Cloud-Based Solutions represent the fastest-expanding technology categories as home care and ambulatory surgical centers shift monitoring outside traditional hospital walls. Wireless Monitoring solutions are capturing margin pools through subscription-based remote patient management models that reduce readmission costs for arrhythmia and heart failure patients.
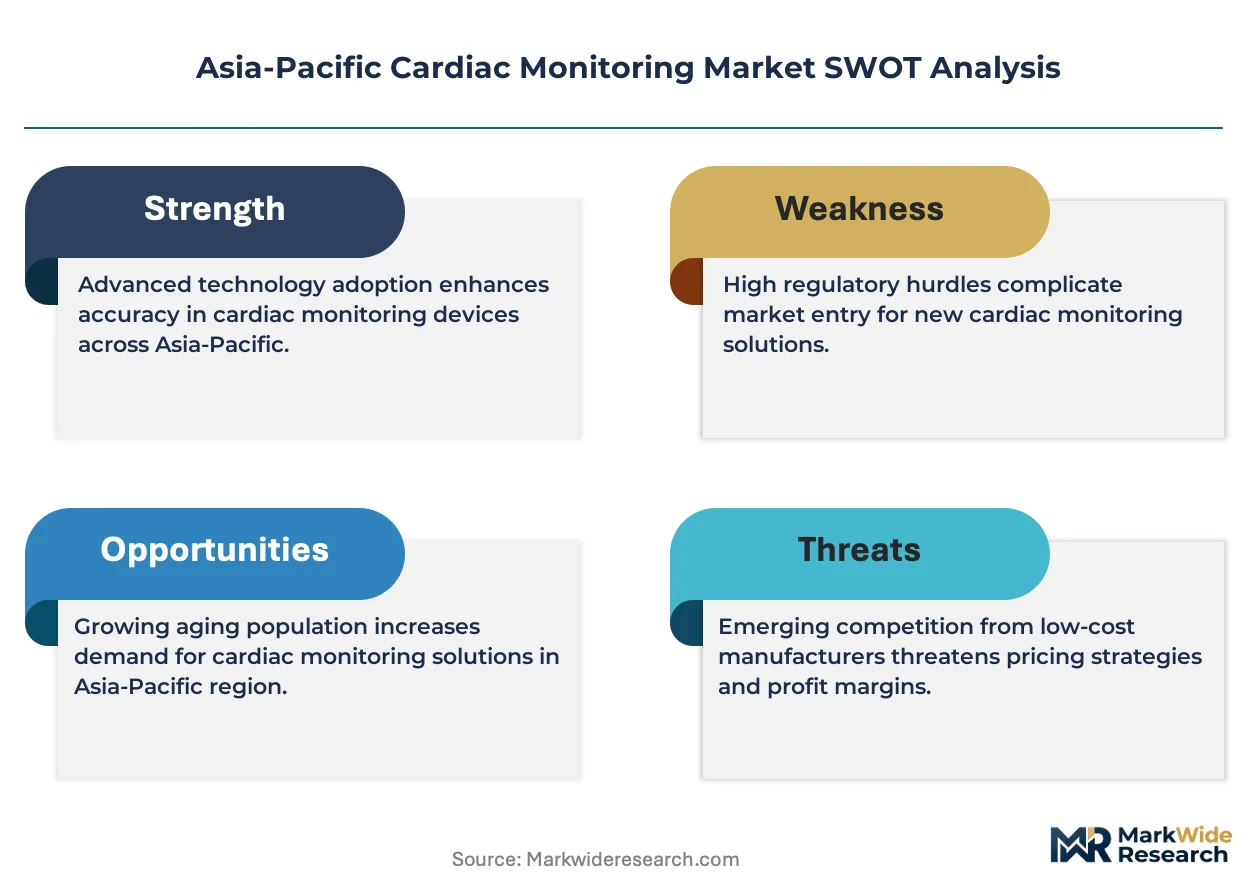
Japan's PMDA and Australia's TGA enforce stringent premarket approval pathways that shape product development timelines and clinical evidence requirements for device manufacturers seeking market access across the region. India's CDSCO and China's NMPA are harmonizing quality management standards with ISO 13485 frameworks, though local testing mandates still create fragmentation in registration protocols. Stakeholders must weigh regulatory compliance investments against the pace of reimbursement expansion for remote monitoring indications in Southeast Asian markets.
Market Dynamics
China's NMPA is compressing registration timelines for Class II cardiac devices while simultaneously tightening clinical evidence standards, forcing manufacturers to rebuild regulatory strategies around dual-track approval pathways that accommodate both domestic and import product lines.
Growth Catalysts
- India's PLI Scheme for Medical Devices:The production-linked incentive framework subsidizes capital equipment and component sourcing for cardiac monitor manufacturing, drawing assembly capacity away from import-dependent supply chains.
- Ambulatory Surgical Center Expansion:Southeast Asian healthcare systems are licensing standalone cardiac catheterization labs that require portable telemetry systems rather than fixed-installation ECG infrastructure.
- Cloud-Based Telemetry Platforms:These systems enable real-time arrhythmia detection outside hospital walls, aligning with Japan's reimbursement expansion for home-based cardiac rehabilitation programs.
Market Restraints
- Semiconductor Component Concentration:Discrete analog front-end chips for ECG signal processing concentrate in Taiwanese and South Korean foundries, exposing monitor assemblers to single-source supply risk.
- Biocompatibility Testing Bottlenecks:China's NMPA mandates local cytotoxicity and sensitization studies that add 8-14 months to implantable loop recorder registrations compared to FDA 510(k) pathways.
- Disposable Electrode Cost Volatility:
- Silver-silver chloride electrode prices fluctuate with precious metals markets, compressing margins on high-volume Holter monitor consumables.
Strategic Opportunities
- Indonesia's Archipelago Telemedicine Mandate:The Ministry of Health's directive for island-based cardiac screening creates first-mover advantage for satellite-connected wearable ECG devices with offline storage capabilities.
- AI-Enabled Arrhythmia Classification:Machine learning algorithms embedded in patch monitors reduce specialist interpretation burden, opening subscription revenue streams for software-as-a-service diagnostic support.
- Vietnam's Private Hospital Construction Wave:Ho Chi Minh City and Hanoi healthcare zones are awarding equipment tenders that bundle cardiac monitoring with IT infrastructure, favoring integrated solution providers.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time signal processing expertise for medical-grade ECG algorithms concentrates in Bangalore and Shenzhen, forcing manufacturers to compete for limited pools of FDA-experienced engineers.
- Legacy Hospital IT Integration:Tier-two Chinese hospitals operate on proprietary HL7 v2.x architectures that resist seamless data handoff to cloud-based cardiac monitoring platforms without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cardiac Monitoring Market |
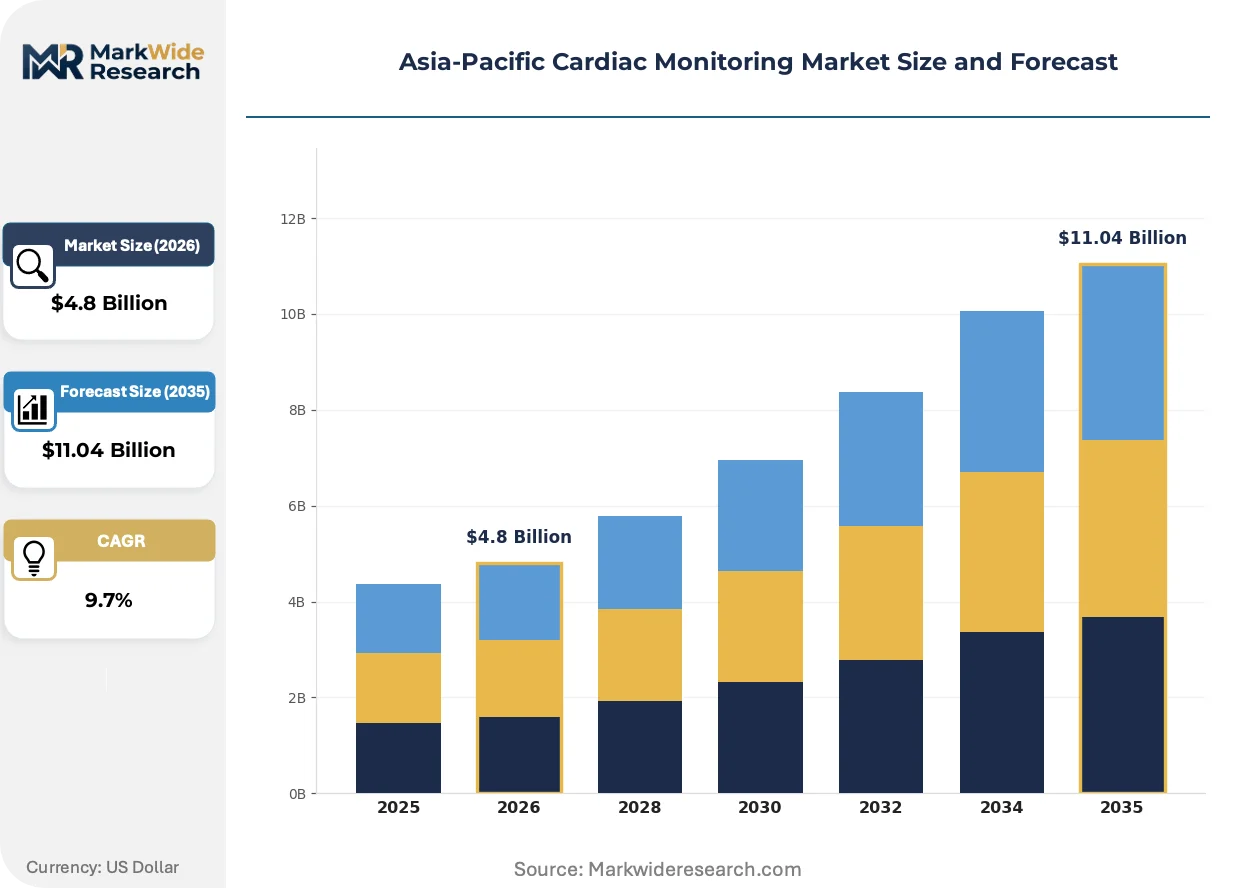
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Holter Monitors, Implantable Monitors, ECG Systems, Cardiac Event Monitors End User: Hospitals, Ambulatory Surgical Centers, Home Care, Diagnostic Laboratories Application: Arrhythmia Monitoring, Coronary Artery Disease, Heart Failure, Post-Operative Monitoring Technology: Wireless Monitoring, Telemetry Systems, Cloud-Based Solutions, Wearable Devices |
| Companies Covered | Medtronic, Abbott Laboratories, GE Healthcare, Philips Healthcare, Boston Scientific Corporation, Nihon Kohden Corporation, BIOTRONIK, MicroPort Scientific Corporation, Hill-Rom, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cardiac Monitoring Market Strategic Shifts
Digital biomarker extraction from continuous cardiac rhythm data is restructuring how payers evaluate cardiovascular disease management, shifting economic validation from device sales toward outcome-based remote monitoring contracts.
Patch-based ambulatory ECG monitors with solid-state electrodes are displacing traditional wired Holter systems in Australian cardiology practices. Regional diagnostic chains including Primary Health Care and Sonic Healthcare are standardizing on 14-day wearable patches for syncope workups. This displacement is collapsing the installed base of rental Holter equipment and redirecting capital budgets toward disposable consumable models.
Japan's PMDA revised its Software as a Medical Device guidance in 2023 to recognize machine learning-enabled arrhythmia detection algorithms as standalone diagnostic components. This regulatory clarification permits software updates to cleared devices without full re-registration, accelerating AI model iteration cycles for cardiac monitoring vendors. The change most directly affects implantable loop recorders with cloud-connected diagnostic engines.
Hospital procurement committees across Thailand and Malaysia are unbundling cardiac monitoring hardware from service contracts, separating device acquisition from technical support and data interpretation. This purchasing pattern favors regional distributors with localized repair capabilities over manufacturers with centralized service hubs. The shift is most visible in Bangkok's private hospital cluster, where equipment tenders now specify 4-hour response times for telemetry downtime.
Asia-Pacific Cardiac Monitoring Market Segmentation
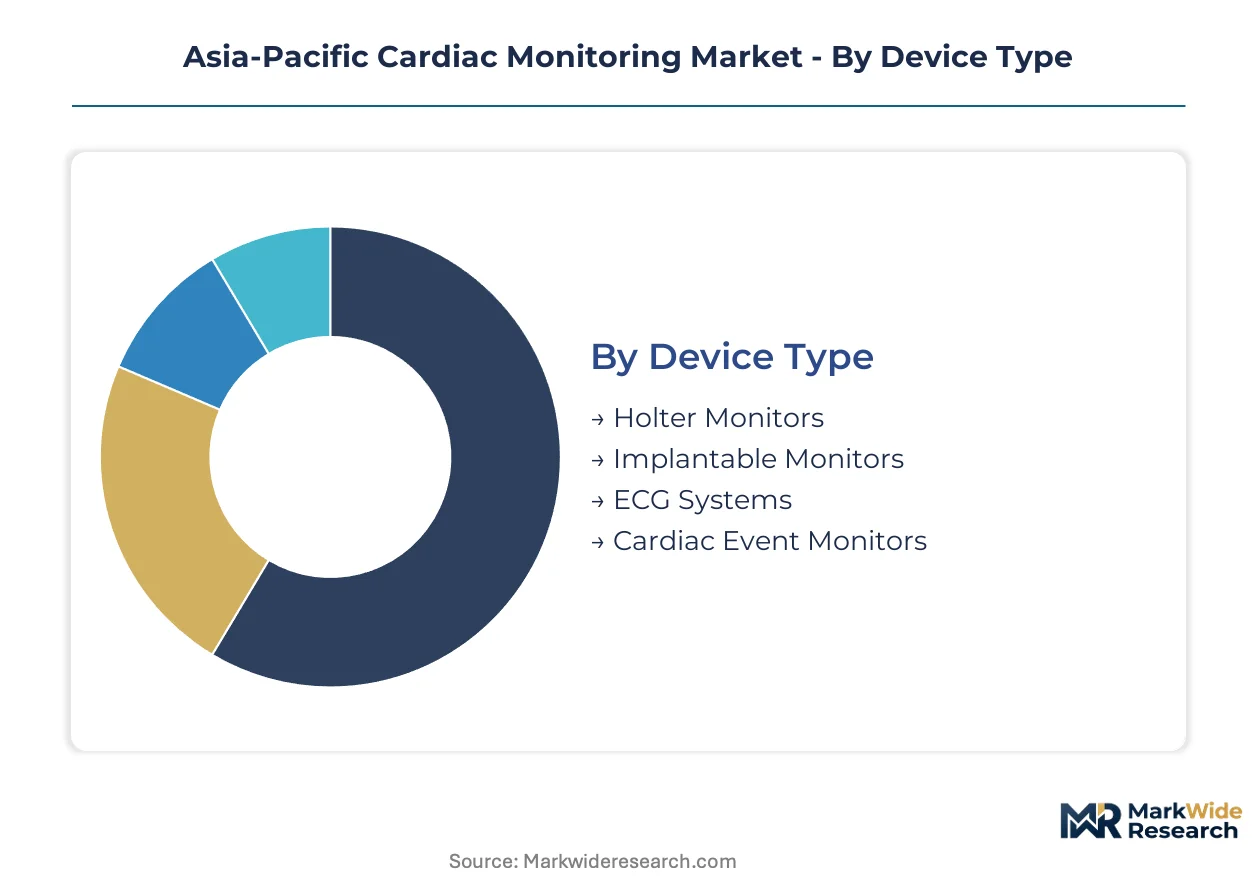
Cardiac monitoring technology spans multiple hardware configurations, care settings, and data transmission architectures. Each segmentation dimension carries distinct regulatory pathways and reimbursement profiles that shape vendor investment priorities across Asia-Pacific healthcare systems.
Device Type:
Japan's PMDA and China's NMPA apply divergent clinical evidence standards for implantable versus external devices, compressing approval timelines for surface-based systems while extending review periods for subcutaneous monitors.
- ECG Systems:Surface electrode arrays with 12-lead diagnostic capability remain the clinical gold standard for acute coronary syndrome detection. China's tier-one hospitals in Beijing and Shanghai drive replacement demand as aging infrastructure reaches end-of-service life.
- Implantable Monitors:Subcutaneous loop recorders with wireless telemetry capture arrhythmia episodes over multi-year monitoring windows. Australia's TGA reimbursement expansion for cryptogenic stroke workups accelerates volume in Sydney and Melbourne cardiology practices.
- Holter Monitors:Portable 24-48 hour ambulatory recorders with disposable electrode sets serve high-volume screening programs across India's public hospital network.
- Cardiac Event Monitors:Patient-activated or auto-trigger external devices capture transient symptoms for intermittent arrhythmia diagnosis in Southeast Asian diagnostic chains.
Established volume favors ECG Systems; emerging adoption favors Implantable Monitors.
End User:
Procurement authority concentrates differently across facility types — centralized tender boards govern public hospital purchasing while ambulatory chains negotiate directly with distributors.
- Hospitals:Integrated cardiology departments with catheterization labs require multi-parameter telemetry beds and centralized monitoring stations. Indonesia's Ministry of Health capital equipment budgets prioritize tertiary referral centers in Jakarta and Surabaya.
- Home Care:Post-discharge monitoring programs for heart failure patients use cellular-connected weight scales and blood pressure cuffs with ECG integration. Japan's reimbursement expansion for home-based cardiac rehabilitation creates subscription revenue pools for remote monitoring vendors.
- Ambulatory Surgical Centers:Standalone cardiac catheterization facilities in Thailand and Malaysia source portable telemetry systems rather than fixed-installation infrastructure.
- Diagnostic Laboratories:Regional chains including Primary Health Care and Sonic Healthcare standardize on 14-day wearable patches for syncope workups.
Capital concentration favors Hospitals; patient volume migration favors Home Care.
Application:
Clinical indication determines monitoring duration, data resolution requirements, and specialist interpretation burden.
- Arrhythmia Monitoring:Continuous rhythm surveillance for atrial fibrillation detection demands high-sampling-rate devices with automated classification algorithms. AI-enabled patch monitors reduce electrophysiologist interpretation burden in high-volume Australian practices.
- Heart Failure:Multi-parameter remote monitoring combining ECG, impedance, and activity sensors enables early decompensation detection. Cloud-based telemetry platforms with real-time alert systems align with Japan's reimbursement structures for chronic disease management.
- Coronary Artery Disease:Exercise tolerance testing and ischemia detection drive demand for stress ECG systems in China's expanding private hospital sector.
- Post-Operative Monitoring:Telemetry surveillance following cardiac surgery or catheter-based intervention requires seamless EMR integration in tier-two Chinese hospitals with proprietary HL7 v2.x architectures.
Procedure volume favors Arrhythmia Monitoring; reimbursement expansion favors Heart Failure.
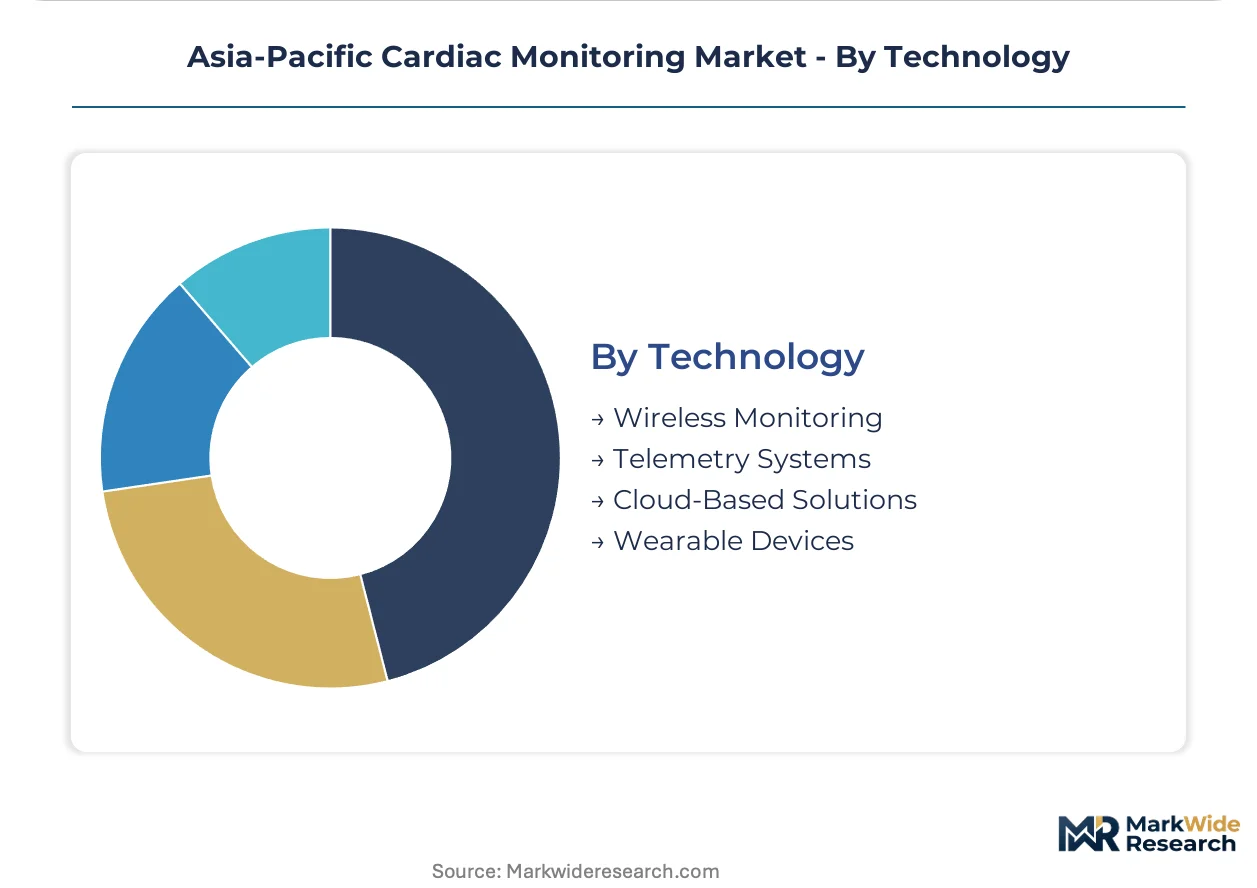
Technology:
Signal transmission architecture determines regulatory classification, cybersecurity requirements, and service revenue potential.
- Wearable Devices:Solid-state electrode patches with Bluetooth or cellular connectivity displace traditional wired Holter systems. Australian diagnostic chains are collapsing rental equipment bases and redirecting capital toward disposable consumable models.
- Cloud-Based Solutions:Centralized data repositories with machine learning-enabled arrhythmia classification enable software-as-a-service diagnostic support. Japan's PMDA Software as a Medical Device guidance permits algorithm updates without full re-registration, accelerating AI model iteration.
- Wireless Monitoring:Real-time telemetry with automated alert generation reduces nursing staff burden in high-acuity hospital settings.
- Telemetry Systems:Dedicated radio-frequency networks for inpatient cardiac surveillance remain standard in legacy hospital infrastructure across Southeast Asia.
Hardware replacement cycles favor Telemetry Systems; margin expansion favors Cloud-Based Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium pricing for implantable monitors while Vietnam absorbs cost-optimized telemetry systems, creating a pricing-power asymmetry that shapes vendor portfolio strategies across the region.
China
Beijing and Shanghai's tier-one hospitals drive replacement demand for aging ECG infrastructure as cardiovascular caseloads surge. NMPA's compressed Class II registration timelines accelerate domestic product launches. The Yangtze River Delta manufacturing corridor anchors MicroPort Scientific Corporation's cost-optimized production for regional export.
Japan
Tokyo and Osaka cardiology practices absorb premium-priced implantable loop recorders for cryptogenic stroke workups. PMDA's 2023 Software as a Medical Device guidance permits AI algorithm updates without full re-registration. The Kanto region's academic medical centers pilot subscription-based remote monitoring for heart failure patients.
India
Maharashtra and Karnataka's public hospital networks deploy high-volume Holter screening programs for rural cardiac outreach. CDSCO's harmonization with ISO 13485 quality frameworks streamlines import registrations. Gujarat's PLI-subsidized manufacturing zones attract assembly capacity for electrode and consumable production.
Australia
Sydney and Melbourne diagnostic chains standardize on 14-day wearable ECG patches for syncope workups. TGA's reimbursement expansion for ambulatory arrhythmia monitoring collapses rental Holter equipment bases. Primary Health Care and Sonic Healthcare redirect capital toward disposable consumable models.
Indonesia
Jakarta and Surabaya's tertiary referral centers absorb Ministry of Health capital equipment budgets for telemetry infrastructure. The archipelago telemedicine mandate creates demand for satellite-connected wearable ECG devices with offline storage. Island-based cardiac screening programs favor ruggedized hardware with extended battery life.
Asia-Pacific Cardiac Monitoring Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific cardiac monitoring landscape. Integrated multinationals sustain premium positioning through regulatory depth and clinical evidence libraries, while regional specialists capture share via localized cost structures and NMPA familiarity. Three archetypes dominate: capital-intensive globals with manufacturing networks, domestic champions with regulatory proximity, and mid-scale distributors with repair capabilities. Competitive moves concentrate on portfolio diversification across implantable-to-wearable segments and geographic expansion through distributor acquisition.
Within the integrated multinational tier, Medtronic and Abbott Laboratories occupy positions defined by diagnostic-to-interventional device portfolios spanning hospital and ambulatory settings. MicroPort Scientific Corporation exemplifies the domestic champion archetype, leveraging Zhengzhou-based manufacturing and NMPA regulatory familiarity to anchor China's implantable monitor segment. Among regional distributors, Nihon Kohden Corporation represents the service-anchored model with localized technical support networks across Southeast Asian markets.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| GE Healthcare |
| Philips Healthcare |
| Boston Scientific Corporation |
| Nihon Kohden Corporation |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| Hill-Rom |
| Others |
Value Chain & Pricing Dynamics
Japan's PMDA software-as-a-medical-device certification gates both supplier qualification and premium pricing tiers simultaneously, forcing manufacturers to maintain dual-track quality systems that separate subscription-based diagnostic platforms from basic hardware transactions.
Pricing Analysis
Configured-to-order implantable monitors with embedded AI classification engines command 40-60% premiums over standard telemetry systems without algorithmic interpretation. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical evidence depth and after-sales bundling intensity. Cost compression in consumable electrode segments is intensifying because silver-silver chloride price volatility transfers directly to Holter monitor margins. Public hospital procurement committees in India's Maharashtra state exhibit highest price sensitivity, while Japan's academic medical centers absorb premium positioning for cryptogenic stroke diagnostic pathways.
Supply Chain Analysis
Strategic stockpiling of analog front-end semiconductors dominates inventory strategy as Taiwanese and South Korean foundry concentration creates 26-32 week lead time exposure for ECG signal processing chips. Discrete analog components, lithium primary batteries, and biocompatible polymers draw from concentrated East Asian manufacturing corridors. Single-source vulnerability in wafer-level chip-scale packaging for implantable loop recorders threatens production continuity. Distribution runs through regional distributor networks with localized repair capabilities rather than manufacturer-direct service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in cloud-connected diagnostic platforms as hospital procurement committees unbundle hardware from service contracts across Thailand and Malaysia.
For Market Incumbents: Fortify regulatory depth through PMDA software update pathways and NMPA dual-track approval investments. Deepen backward integration into electrode manufacturing to offset silver-silver chloride cost volatility. Prioritize acquisition of regional distributors with 4-hour response time capabilities in Bangkok's private hospital cluster. For New Entrants and Emerging Players: Differentiate on AI-enabled arrhythmia classification algorithms that reduce electrophysiologist interpretation burden in high-volume Australian diagnostic chains. Target Indonesia's archipelago telemedicine mandate with satellite-connected wearable ECG devices featuring offline storage. Pursue software-as-a-service revenue models aligned with Japan's home-based cardiac rehabilitation reimbursement expansion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors possessing localized technical support networks across Southeast Asian markets. Five-to-ten year viability hinges on subscription revenue migration from device sales. Monitor NMPA Class II registration timeline compression as inflection indicator for domestic Chinese manufacturer competitive pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Medical-Device Certification | PMDA guidance permits AI algorithm updates without full re-registration, accelerating iteration cycles. |
| Hospital System Partnership | Equipment tenders in Ho Chi Minh City bundle cardiac monitoring with IT infrastructure, favoring integrated providers. |
| Reimbursement Strategy | Japan's expansion for home-based cardiac rehabilitation creates subscription revenue pools for remote monitoring vendors. |
| Manufacturing Scale-Up | India's PLI-subsidized zones attract electrode and consumable assembly capacity away from import-dependent chains. |
| Regulatory Approval Pathway | NMPA's compressed Class II timelines accelerate domestic product launches while tightening clinical evidence standards. |
Study Parameters
Cross-validation between hospital procurement database analysis and clinician interview transcripts anchors the qualitative findings across the Asia-Pacific cardiac monitoring landscape. Primary discussions with biomedical engineers, GPO contracts managers, electrophysiologists, and regulatory affairs leads combined with secondary validation from PMDA submission databases, NMPA registration filings, hospital tender records, and CMS-equivalent reimbursement schedules. Bottom-up installed base modeling and top-down healthcare expenditure allocation triangulate volume estimates.
Sensitivity analysis across device type, end-user facility tier, application indication, and technology transmission architecture informs the analytical framework over the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macro healthcare infrastructure investment patterns. Forecast inputs incorporate NMPA registration pipeline velocity and Japan's software-as-a-medical-device adoption curves.
Material uncertainties — semiconductor supply disruption, precious metals price spikes, and reimbursement policy reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline trajectories and hospital capital equipment replacement cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Global Stethoscope Market