
 Left Atrial Appendage (LAA) Closure Market | 2026-2036
Left Atrial Appendage (LAA) Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Left Atrial Appendage (LAA) Closure Market Foresight
CE marking under the EU Medical Device Regulation (MDR) is collapsing the window for smaller manufacturers seeking European market access, forcing portfolio rationalization among device firms. Boston Scientific Corporation leverages its Watchman platform and deep catheter lab relationships to sustain dominance in transcatheter delivery. Abbott Laboratories anchors its position through the Amplatzer franchise and integrated structural heart portfolios. AtriCure Inc. specializes in surgical and hybrid approaches, occupying a distinct niche that complements percutaneous alternatives.
Left atrial appendage closure refers to the mechanical or surgical occlusion of the LAA, a finger-like cardiac pouch where thrombus formation in atrial fibrillation patients elevates stroke risk; the procedure typically employs nitinol mesh implants delivered via transseptal catheter access or surgical excision, with device sizing determined by computed tomography or transesophageal echocardiography measurements of orifice diameter and landing zone depth. Transcatheter delivery dominates procedure volume due to shorter recovery times and expanding operator training programs, while surgical and hybrid modalities retain preference in concomitant cardiac surgery cases where sternotomy already occurs. The Watchman product category leads in installed base and clinical evidence generation, whereas LAmbre and Occlutech compete on cost positioning and anatomical adaptability in price-sensitive health systems.
FDA premarket approval and the EU MDR framework govern device safety and clinical evidence requirements, with both regulators demanding randomized trial data for novel LAA occluder designs that extend development timelines and capital requirements. Japan's PMDA maintains distinct pharmacovigilance reporting standards that shape post-market study obligations for manufacturers seeking reimbursement under the national health insurance system. Stakeholders must monitor evolving anticoagulation guidelines from cardiology societies, as shifts in medical therapy recommendations directly influence patient selection criteria and procedure volumes across delivery settings.
Market Dynamics
The LAA closure market pivots on Medicare reimbursement maturation in the United States, which has compressed the pathway from clinical trial completion to hospital adoption and created volume concentration in tertiary electrophysiology centers.
Growth Catalysts
- Transseptal catheter delivery:Shorter recovery times and expanding operator training programs are pulling procedure volume away from surgical alternatives.
- CE marking under EU MDR:Stricter clinical evidence requirements are filtering out marginal competitors and consolidating market access for established device portfolios.
- Computed tomography sizing protocols:Pre-procedural anatomical assessment is reducing implant mismatch rates and accelerating same-day discharge protocols.
Market Restraints
- Nitinol supply concentration:Raw material sourcing clusters in specialized metallurgical suppliers, exposing device manufacturers to input cost volatility and long lead times.
- FDA premarket approval timelines:Randomized trial mandates for novel occluder designs extend development cycles and capital lockup periods.
- Oral anticoagulant therapy:Direct oral anticoagulants retain preference in low-bleeding-risk patients, capping the addressable population for mechanical closure.
Strategic Opportunities
- Japan's national health insurance system:Reimbursement expansion under PMDA pharmacovigilance frameworks offers untapped volume potential for transcatheter devices.
- Hybrid operating suites:Convergence of surgical and percutaneous techniques is creating new procedure categories for combined atrial fibrillation ablation and LAA closure.
- India's CDSCO fast-track pathways:Accelerated approval mechanisms for cardiac implantables are opening price-sensitive volume markets.
Industry Challenges
- Transesophageal echocardiography expertise:Device deployment requires specialized imaging interpretation skills that concentrate in academic medical centers, limiting community hospital expansion.
- Post-market surveillance infrastructure:Long-term thromboembolic and bleeding outcome tracking demands registry investment that strains mid-cap manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Left Atrial Appendage (LAA) Closure Market |
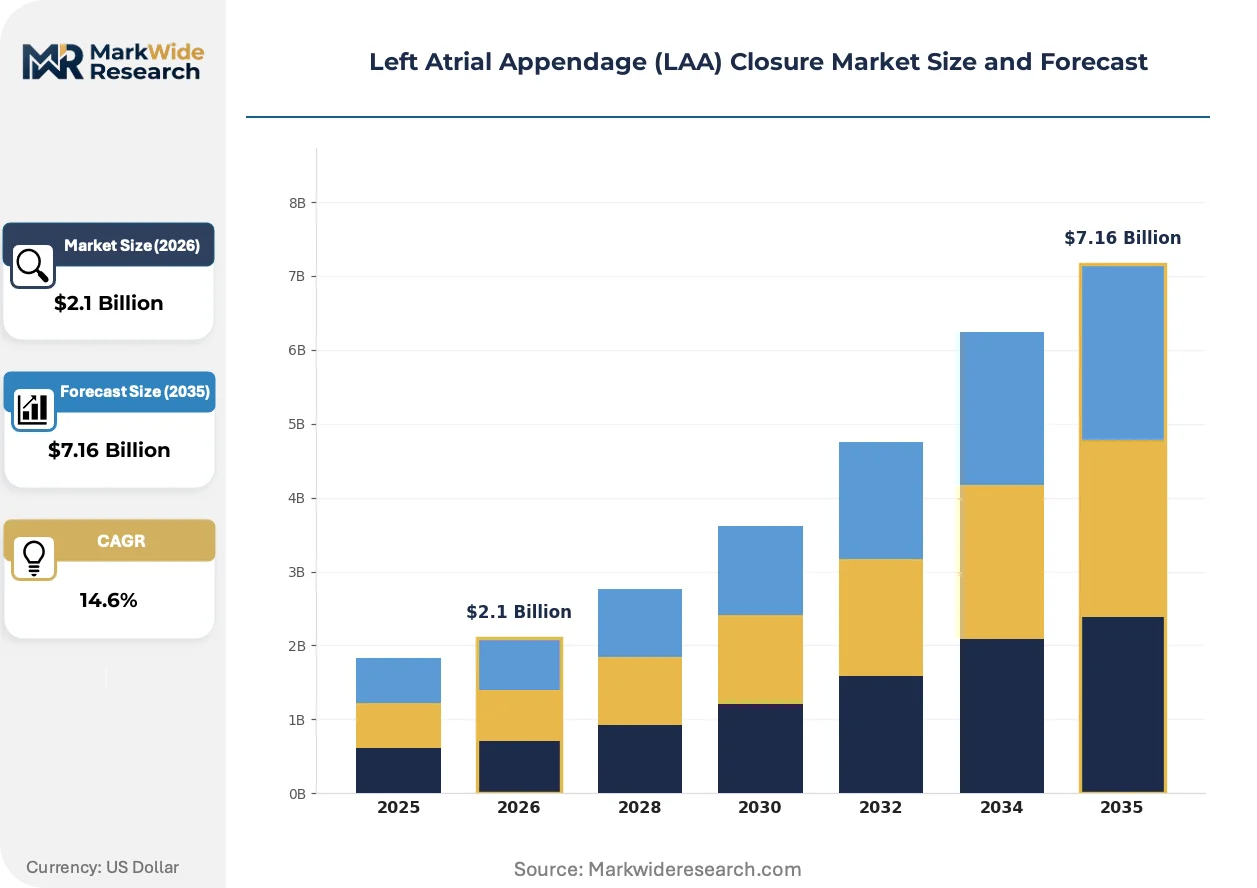
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Watchman, Amplatzer, LAmbre, Occlutech Delivery Mode: Transcatheter, Surgical, Hybrid, Percutaneous End User: Hospitals, Cardiac Centers, Clinics, Research Institutions Application: Atrial Fibrillation, Stroke Prevention, Heart Failure, Cardiovascular Procedures |
| Companies Covered | Boston Scientific Corporation, Abbott Laboratories, AtriCure Inc., Johnson & Johnson, Medtronic, Occlutech, Lifetech Scientific, Lepu Medical Technology, Cardia Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Left Atrial Appendage (LAA) Closure Market Shifts & Advancements
Device miniaturization and real-time intracardiac imaging integration are compressing procedure times and expanding the treatable anatomical spectrum beyond traditional orifice diameter constraints.
Self-expanding nitinol mesh designs with adaptive lobe configurations are supplanting fixed-dimension occluders in anatomically complex appendages. Electrophysiology labs in high-volume US hospital systems are adopting these platforms for cases with chicken-wing or cauliflower morphologies. The shift is compressing the competitive window for first-generation devices that lack landing zone flexibility.
EU MDR clinical evidence requirements are reshaping post-market study obligations across the European device sector. Manufacturers must now maintain active implant registries with minimum five-year follow-up protocols. Surgical occlusion devices face heightened scrutiny relative to transcatheter alternatives due to smaller existing evidence bases.
Hospital purchasing committees are consolidating supplier relationships around single-platform contracts that bundle devices, training, and complication coverage. Integrated delivery networks in the United States are displacing individual physician preference contracting. This concentration is most visible in Medicare-dependent health systems where episode-based cost accountability has tightened capital equipment decision-making.
Left Atrial Appendage (LAA) Closure Market Segmentation
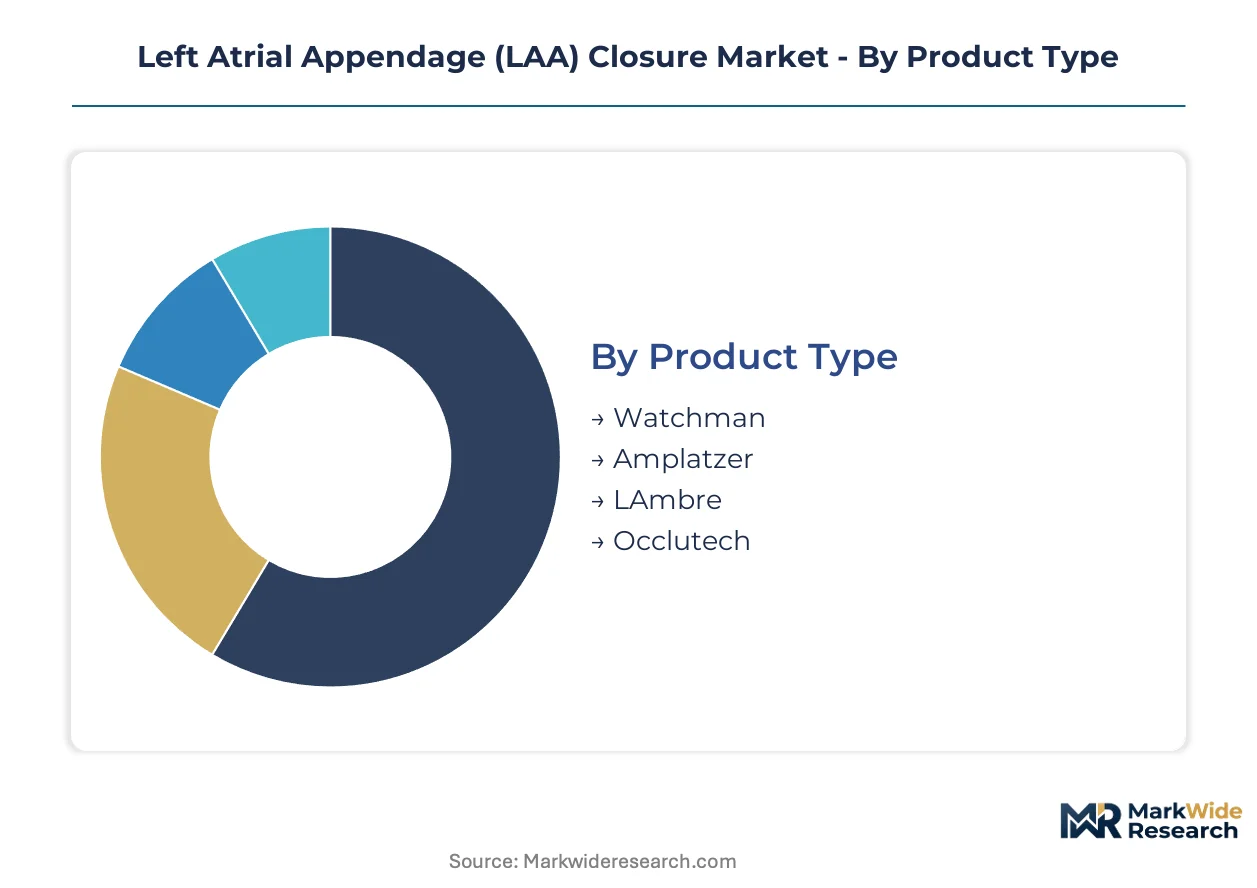
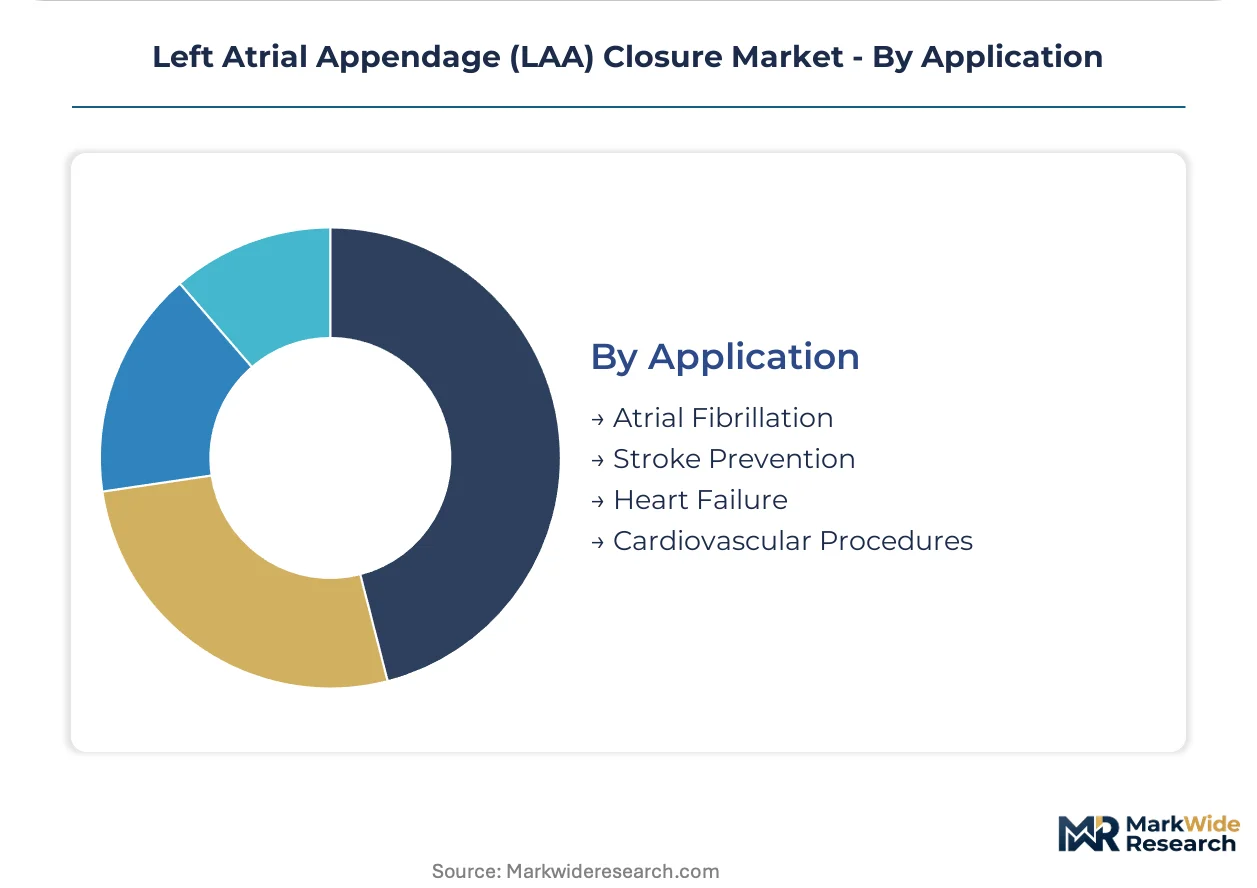
Segmentation in the LAA closure market reveals how procedure economics, anatomical complexity, and reimbursement pathways reshape competitive positioning across device categories and care settings. Distinct substitution pressures operate within each dimension, with transcatheter alternatives displacing surgical volumes and integrated delivery networks consolidating supplier relationships around single-platform contracts.
Product Type:
Substitution pressure from next-generation adaptive designs is compressing the competitive window for fixed-dimension occluders, particularly in anatomically complex appendages.
- Watchman:Self-expanding nitinol mesh with a fixed lobe-and-disc configuration. Demand concentrates in US tertiary electrophysiology centers where Medicare reimbursement maturation and deep catheter lab relationships sustain installed base dominance.
- Amplatzer:Dual-lobe design with proximal and distal retention discs. European cardiac centers favor this platform for cauliflower and chicken-wing morphologies where landing zone flexibility reduces implant mismatch rates.
- LAmbre:Adaptive lobe system with independent proximal and distal components. Price-sensitive health systems in Asia-Pacific markets select this platform for cost positioning against established alternatives.
- Occlutech:Nitinol mesh with adjustable waist diameter. Emerging markets with CDSCO fast-track pathways drive procurement volumes for this anatomically adaptable design.
Watchman retains volume leadership; LAmbre holds the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates same-day discharge protocols from extended recovery pathways, with reimbursement differentials reinforcing modality selection across hospital systems.
- Transcatheter:Transseptal catheter access with femoral vein entry. US electrophysiology labs favor this approach for standalone procedures where reduced recovery times align with episode-based cost accountability.
- Surgical:Sternotomy or thoracotomy with direct appendage excision or stapled closure. Concomitant cardiac surgery cases in German university hospitals retain this modality when sternotomy already occurs.
- Hybrid:Combined surgical and percutaneous techniques in integrated operating suites. Japanese academic medical centers pioneer this category for combined atrial fibrillation ablation and LAA closure.
- Percutaneous:Minimally invasive access without transseptal crossing. Niche applications in Indian cardiac centers with limited transesophageal echocardiography expertise.
Transcatheter commands the volume base; hybrid delivery is climbing the fastest.
End User:
Customer type concentration around integrated delivery networks is displacing individual physician preference contracting, with capital equipment decision-making tightening in Medicare-dependent systems.
- Hospitals:Tertiary and community hospital systems with electrophysiology programs. US hospital purchasing committees consolidate supplier relationships around bundled device-training-coverage contracts.
- Cardiac Centers:Dedicated structural heart and arrhythmia facilities. French cardiac centers concentrate transcatheter volumes where operator training programs exceed minimum case thresholds.
- Clinics:Outpatient settings with limited procedural capabilities. Pre-procedural screening and follow-up surveillance dominate this segment.
- Research Institutions:Academic medical centers with active implant registries. EU MDR five-year follow-up obligations concentrate post-market study investment here.
Hospitals retain volume leadership; cardiac centers are gaining share fastest.
Application:
Maturity differentiation separates guideline-supported indications from emerging use cases, with clinical evidence requirements governing expansion timelines.
- Atrial Fibrillation:Non-valvular atrial fibrillation with elevated stroke risk. US Medicare pathways and ESC guidelines anchor demand in this established indication.
- Stroke Prevention:Mechanical occlusion as anticoagulant alternative. German statutory health insurance reimbursement covers this application for contraindicated or intolerant patients.
- Heart Failure:Concomitant left atrial pressure management. Japanese PMDA pharmacovigilance frameworks shape post-market study design for this emerging category.
- Cardiovascular Procedures:Combined interventions including valve repair or ablation. Hybrid operating suites in Swiss university hospitals pioneer this procedural convergence.
Atrial fibrillation retains volume leadership; heart failure holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate procurement authority for LAA closure devices, while tertiary electrophysiology centers in Germany and Japan anchor procedure volume growth through established reimbursement pathways.
United States
Medicare reimbursement maturation and episode-based cost accountability drive hospital adoption of transcatheter LAA closure. FDA premarket approval requirements shape competitive entry timelines for novel occluder designs. Tertiary electrophysiology centers in Cleveland and Boston sustain the highest procedural volumes through deep catheter lab relationships.
Germany
Statutory health insurance coverage for stroke prevention in anticoagulant-intolerant patients sustains demand for mechanical closure alternatives. CE marking under EU MDR filters market access for device manufacturers lacking robust clinical evidence portfolios. University hospitals in Munich and Heidelberg concentrate surgical and hybrid procedure volumes for concomitant cardiac surgery cases.
Japan
PMDA pharmacovigilance frameworks and national health insurance reimbursement expansion create volume potential for transcatheter devices. Post-market study obligations with five-year follow-up protocols concentrate investment in academic medical centers. Tokyo and Osaka academic hospitals pioneer hybrid operating suite configurations combining atrial fibrillation ablation with LAA closure.
China
CDSCO fast-track pathways for cardiac implantables accelerate approval timelines for anatomically adaptable device designs. Price-sensitive procurement patterns in provincial hospital systems favor cost-positioned platforms against established alternatives. Shanghai and Beijing cardiac centers drive training program expansion for transseptal catheter delivery techniques.
India
CDSCO regulatory harmonization with international standards opens accelerated pathways for nitinol mesh occluders. Private hospital chains in Delhi and Mumbai expand electrophysiology programs to capture rising atrial fibrillation procedure volumes. Cost-tier positioning determines competitive outcomes in a market where out-of-pocket payment dominates device procurement decisions.
Left Atrial Appendage (LAA) Closure Market Competitive Landscape
Player mix skews toward diversified cardiovascular device conglomerates with integrated structural heart portfolios and specialized surgical occlusion firms occupying complementary niches. Market structure consolidates around three strategic archetypes: transcatheter platform leaders with deep catheter lab relationships, surgical occlusion specialists with hybrid operating suite expertise, and cost-positioned challengers leveraging regulatory fast-tracks in emerging markets. Dominant competitive moves include portfolio diversification into adjacent structural heart segments and geographic expansion through regulatory harmonization strategies.
Among US-based diversified device manufacturers, Boston Scientific Corporation and Abbott Laboratories anchor the transcatheter platform tier through established catheter lab networks and integrated structural heart portfolios. AtriCure Inc. occupies a distinct position within the surgical and hybrid occlusion archetype, complementing percutaneous alternatives through specialized approaches in concomitant cardiac surgery settings.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott Laboratories |
| AtriCure Inc. |
| Johnson & Johnson |
| Medtronic |
| Occlutech |
| Lifetech Scientific |
| Lepu Medical Technology |
| Cardia Inc. |
| Others |
Supply & Pricing Matrix
Adaptive nitinol mesh designs replacing fixed-dimension occluders are redrawing procurement geography toward Chinese and Indian metallurgical suppliers while compressing price premiums for anatomically rigid legacy platforms. This substitution dynamic concentrates bargaining power with specialized nitinol processors and forces tier-one manufacturers to renegotiate long-term offtake terms.
Pricing Analysis
Cost-plus contracts indexed to nickel and titanium spot markets govern raw material procurement for nitinol mesh occluders. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved platforms with five-year registry data from CE-marked alternatives and CDSCO fast-tracked devices. Cost compression in the economy tier is intensifying because provincial hospital systems in China and India consolidate purchasing around single-source agreements. Cardiac centers with episode-based accountability show least price sensitivity; community hospitals expanding electrophysiology programs exhibit highest.
Supply Chain Analysis
Inventory lead times for nitinol wire stock extend eighteen to twenty-four months due to vacuum arc remelting capacity constraints. Metallurgical processing clusters in the United States, Germany, and China supply superelastic nitinol feedstock. Device assembly draws from precision laser-cutting operations, polymer sheath extrusion, and sterilization validation services. Single-source vulnerability concentrates in vacuum arc remelting furnace operators. Distribution runs through hospital purchasing committees and GPO contracts rather than direct physician channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transseptal catheter expertise scarcity limits community hospital expansion and creates acquisition premiums for training-capable platforms. The gap between certified operator supply and procedure volume demand widens fastest in Medicare-dependent health systems.
For Market Incumbents: Secure catheter lab relationship exclusivity through bundled training-coverage contracts before CDSCO fast-tracked competitors establish Indian and Chinese reference sites. Add backward integration into nitinol wire processing to buffer raw material volatility. Defend against LAmbre and Occlutech cost positioning by accelerating same-day discharge protocol adoption in US tertiary centers. For New Entrants and Emerging Players: CDSCO accelerated approval pathways for cardiac implantables offer the most penetrable regulatory entry point for anatomically adaptable device designs. Target Indian private hospital chains in Delhi and Mumbai expanding electrophysiology programs with price-tiered positioning against established platforms. Build initial volume through provincial Chinese hospital systems before pursuing FDA premarket approval investment. For Investors and Strategic Acquirers: The market sits at a reimbursement-maturation phase that favors integrated structural heart portfolios with deep catheter lab networks over standalone device plays. Long-term viability hinges on five-year registry data generation capacity and post-market surveillance infrastructure. Acquisition targets should demonstrate active implant tracking systems and established operator training programs. Watch Japanese PMDA national health insurance reimbursement expansion as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Randomized trial mandates extend development timelines and capital requirements for novel occluder designs. |
| CE Marking Under EU MDR | Five-year follow-up registry obligations filter marginal competitors and consolidate market access. |
| Hospital System Partnership | Bundled device-training-coverage contracts displace individual physician preference in Medicare-dependent systems. |
| Software Companion Development | Real-time intracardiac imaging integration compresses procedure times and expands treatable anatomical spectrum. |
| Reimbursement Strategy | Medicare pathway maturation in US and PMDA expansion in Japan determine addressable patient population scale. |
Research Methodology
Desk research of FDA premarket approval filings, EU MDR technical documentation, PMDA pharmacovigilance reports, and hospital procurement databases preceded structured interviews with electrophysiology lab directors, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers. Primary fieldwork with device manufacturers and nitinol metallurgical suppliers was cross-validated against secondary sources including CMS Medicare claims data and structural heart registry publications. Bottom-up procedure volume estimates and top-down market sizing were triangulated for convergence.
Variance decomposition across product type, delivery mode, end user, and application segments shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume projections calibrated to reimbursement pathway maturation timelines and operator training program expansion rates. Forecast inputs incorporated anticoagulation guideline evolution from cardiology societies and nitinol raw material supply elasticity assumptions.
Underlying assumptions cover Medicare reimbursement stability, EU MDR enforcement consistency, and nitinol supply chain continuity, with deviation risk concentrated in oral anticoagulant therapy guideline shifts and transesophageal echocardiography expertise concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market