
 Europe Cardiac Arrhythmia Monitoring Devices Market | 2026-2036
Europe Cardiac Arrhythmia Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cardiac Arrhythmia Monitoring Devices Market Foresight
CE marking under the EU Medical Device Regulation is unwinding the competitive landscape for ambulatory cardiac monitoring systems. Abbott Laboratories leverages its vertically integrated electrophysiology portfolio to sustain leadership in implantable loop recorder technology. Medtronic PLC anchors its position through extensive clinical validation data and direct hospital contracting across Northern Europe. Koninklijke Philips NV differentiates via cloud-integrated diagnostic platforms that streamline arrhythmia detection workflows.
Cardiac arrhythmia monitoring devices comprise electrocardiographic recording systems designed to capture, store, and transmit cardiac electrical activity over extended durations, typically sampling at 128–1024 Hz with noise thresholds below 50 microvolts. These systems serve the primary commercial purpose of detecting intermittent rhythm disturbances that escape standard 12-lead electrocardiography, enabling clinicians to correlate symptoms with electrophysiological events. Implantable loop recorders command premium positioning due to their multi-year monitoring horizons and direct-to-physician telemetry capabilities, while wearable monitors capture the fastest expansion trajectory as consumer-grade photoplethysmography gains clinical acceptance. Home care settings represent an emerging margin pool where remote patient monitoring technology reduces hospital dependency for chronic arrhythmia surveillance.
The European Medicines Agency coordinates vigilance reporting for serious device malfunctions, while the EU Medical Device Regulation mandates unique device identification and enhanced clinical evidence requirements for Class IIa and above cardiac monitors. REACH compliance additionally governs the chemical composition of electrode adhesives and implantable device housings, constraining material sourcing options for manufacturers. Stakeholders must monitor evolving notified body capacity constraints and national reimbursement decisions for digital health integration as these factors will determine which monitoring modalities achieve scalable clinical adoption.
Market Dynamics
CE marking under the EU Medical Device Regulation is compressing certification timelines for ambulatory cardiac monitors, forcing manufacturers to consolidate clinical evidence portfolios and accelerate notified body engagements ahead of 2027 renewal deadlines.
Growth Catalysts
- Germany's DiGA Fast-Track:The Federal Institute for Drugs and Medical Devices expedites reimbursement for prescription digital health applications, accelerating wearable ECG adoption in outpatient cardiology.
- Remote Patient Monitoring:Hospital systems in France and the Netherlands deploy cloud-integrated diagnostic platforms to reduce readmission penalties under diagnosis-related group frameworks.
- REACH Electrode Compliance:Reformulated conductive adhesives eliminate skin irritants while maintaining signal fidelity, expanding long-term monitoring eligibility for pediatric and geriatric cohorts.
Market Restraints
- Notified Body Bottlenecks:Only 12 designated bodies remain authorized for Class IIa cardiac devices under MDR, extending conformity assessment timelines to 18-24 months.
- Lithium-Ion Supply Concentration:Implantable loop recorder manufacturers depend on Chinese-processed battery materials subject to export license volatility and carbon footprint disclosure mandates.
- Holter Monitor Substitution:Patch-based extended monitors capture 14-day recording windows previously requiring 48-hour Holter studies, eroding traditional device ASPs.
Strategic Opportunities
- Poland and Romania Expansion:Underpenetrated Eastern European markets lack established long-term monitoring reimbursement, creating first-mover advantage for direct-to-hospital contracting models.
- AI-Assisted Arrhythmia Detection:Machine learning algorithms embedded in wearable photoplethysmography reduce false-positive burden on electrophysiology departments, enabling scalable remote workforce deployment.
- EU Green Deal Alignment:Circular economy requirements for medical device recyclability incentivize modular monitor designs with replaceable batteries and biodegradable electrode components.
Industry Challenges
- Electrophysiology Talent Scarcity:Certified cardiac device specialists command premium compensation across Germany, France, and Italy, constraining technical support scalability for remote monitoring rollouts.
- Legacy EMR Integration:Proprietary data formats from implantable loop recorders require custom HL7 FHIR mapping to interface with hospital information systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cardiac Arrhythmia Monitoring Devices Market |
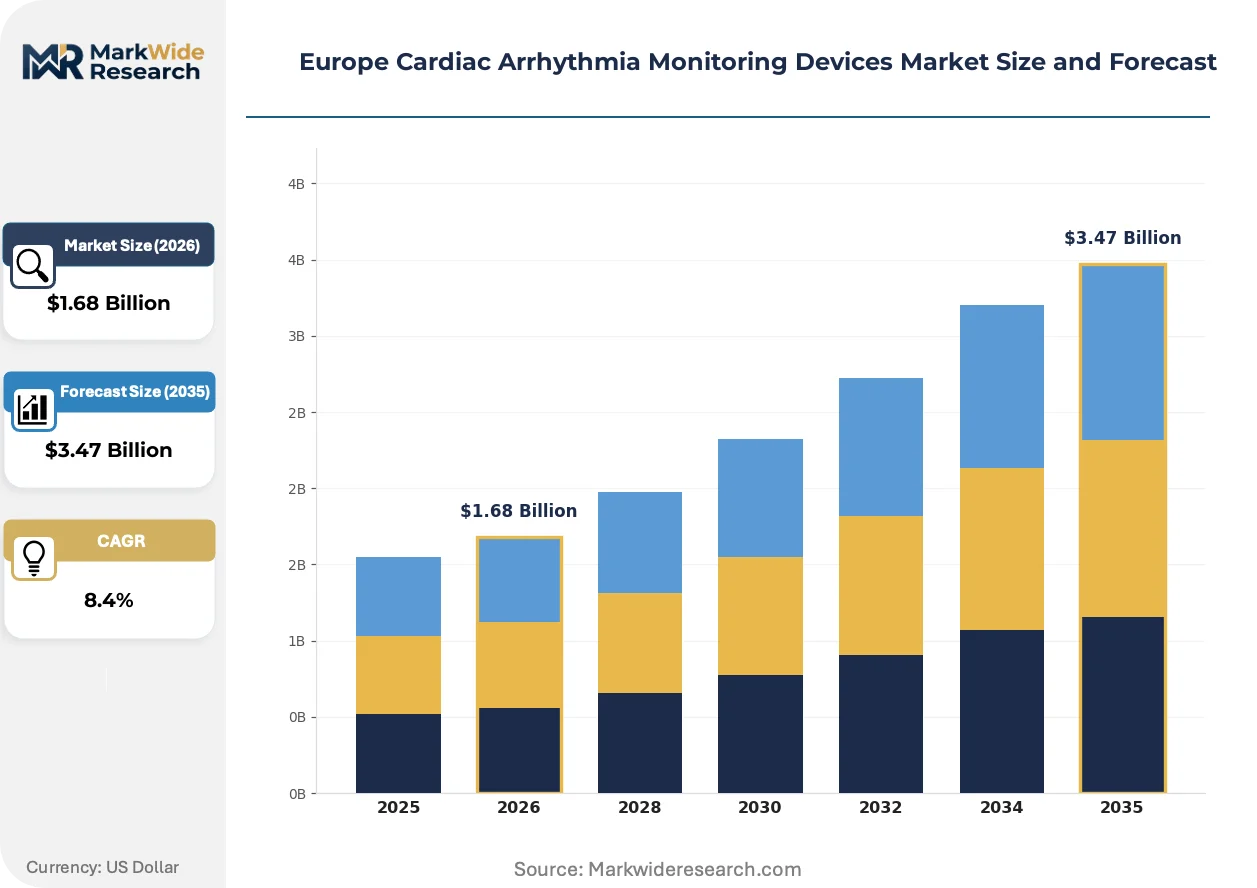
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Cardiac Event Monitors, Implantable Loop Recorders, Wearable Monitors End User: Hospitals, Clinics, Diagnostic Centers, Home Care Settings Technology: Wireless Monitoring, Mobile Health Applications, Remote Patient Monitoring, Cloud Computing Application: Heart Rate Monitoring, Arrhythmia Detection, Patient Management, Data Analysis |
| Companies Covered | Abbott Laboratories, Medtronic PLC, Koninklijke Philips NV, GE Healthcare, iRhythm Technologies Inc, ZOLL Medical Corporation, Biotronik Inc, Hill-Rom Holding Inc, Boston Scientific Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cardiac Arrhythmia Monitoring Devices Market Shifts & Advancements
Photoplethysmography-enabled consumer wearables are penetrating clinical workflows, compressing the boundary between prescription diagnostics and wellness tracking while forcing traditional manufacturers to defend hospital channel relationships.
Patch-based extended cardiac monitors are supplanting traditional Holter recorders in ambulatory settings. These adhesive-integrated systems capture 14-day continuous ECG streams without patient-managed electrodes. Cardiology departments in Sweden and Denmark prioritize patch platforms for cryptogenic stroke workups. The technology is compressing diagnostic timelines from weeks to days while reducing technician handling costs.
EU Medical Device Regulation unique device identification mandates are reshaping post-market surveillance obligations. Manufacturers must maintain electronic records linking individual devices to patient outcomes across 15-year retention horizons. Implantable loop recorders face the steepest compliance burden due to their multi-year dwell times and direct-to-physician telemetry architectures. Notified bodies in Germany and the Netherlands are prioritizing UDI-audited quality management systems in certification reviews.
Hospital procurement committees now bundle cardiac monitoring contracts with electrophysiology lab equipment purchases, unbundling standalone device vendors from preferred supplier lists. Integrated platform vendors capture multi-year agreements spanning diagnostic hardware, cloud analytics, and technician training. This concentration is most pronounced in France's public hospital networks and Belgium's university-affiliated cardiology centers.
Europe Cardiac Arrhythmia Monitoring Devices Market Segmentation
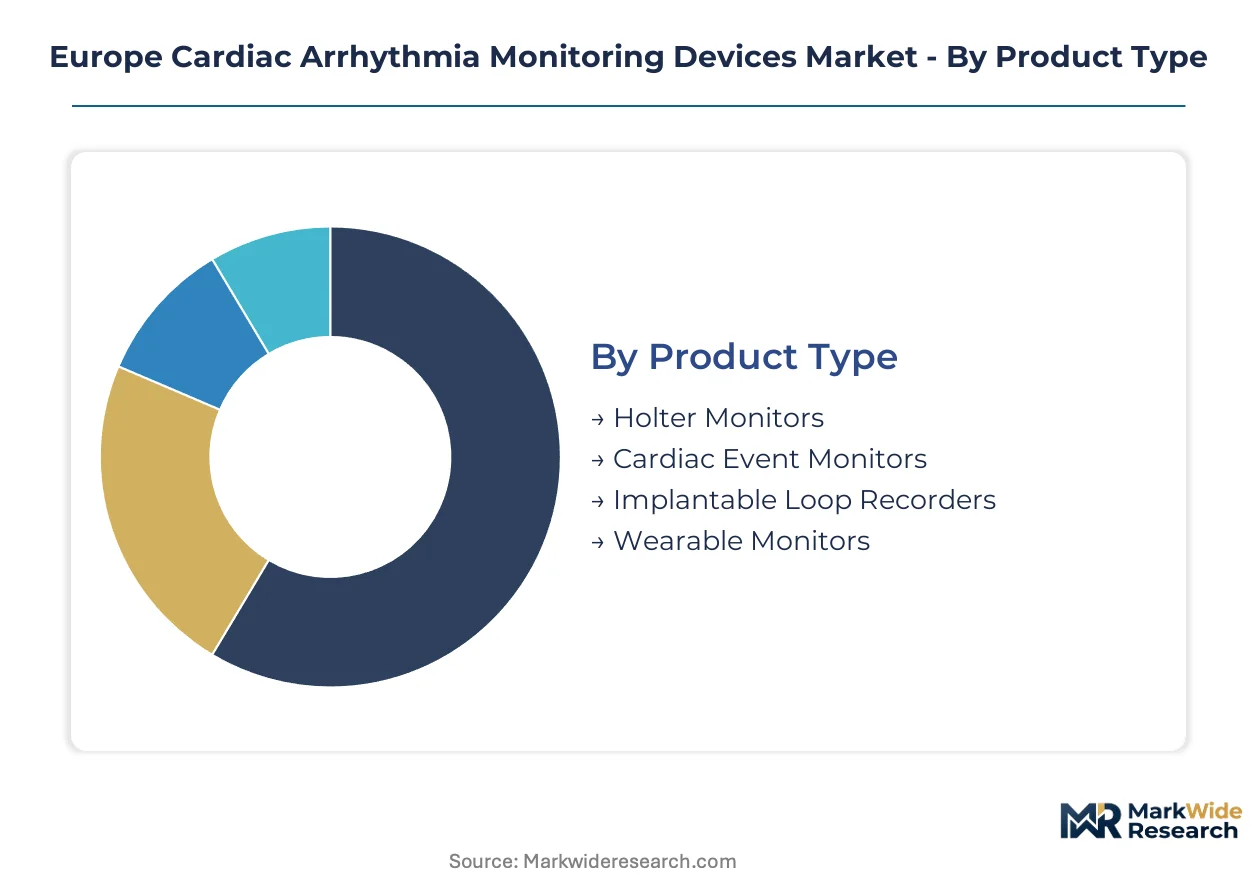
Segmentation in cardiac arrhythmia monitoring reveals how substitution pressures and reimbursement pathways reshape competitive positioning across device categories. Product-level distinctions increasingly blur as patch-based systems displace traditional form factors and cloud architectures unify previously separate technology silos.
Product Type:
Patch-based extended monitors are displacing legacy Holter systems across Western European outpatient cardiology, forcing incumbent manufacturers to defend installed bases through service bundling.
- Holter Monitors:Portable 24-48 hour continuous ECG recorders with 2-12 channel configurations and patient-managed electrode placement. German hospital procurement committees now bundle Holter services with implantable device follow-up contracts, compressing standalone hardware margins. Demand concentrates in budget-constrained Southern European markets where reimbursement favors established diagnostic codes over novel modalities.
- Implantable Loop Recorders:Subcutaneous devices sampling at 128-256 Hz with 2-3 year battery life and direct-to-physician cellular telemetry. French and Dutch electrophysiology departments prioritize these for cryptogenic stroke protocols, though CE marking under MDR extends certification timelines. The premium positioning depends on clinical validation data for atrial fibrillation burden quantification.
- Cardiac Event Monitors:Patient-activated or auto-triggered external recorders capturing symptomatic episodes.
- Wearable Monitors:Consumer-grade photoplethysmography devices gaining clinical acceptance through DiGA fast-track pathways.
Holter monitors anchor the volume base while wearable monitors gain share at the steepest rate.
End User:
Procurement concentration among integrated hospital networks is reshaping vendor access patterns, with cloud platform requirements filtering out standalone device suppliers.
- Hospitals:Academic medical centers and public hospital networks across France, Belgium, and Sweden that operate electrophysiology labs and implantation programs. These institutions demand HL7 FHIR interoperability and 15-year UDI-compliant record retention, favoring vendors with integrated diagnostic platforms over point-product manufacturers. Bundled contracting for hardware, analytics, and technician training now spans 3-5 year horizons.
- Home Care Settings:Remote patient monitoring deployments reducing hospital dependency for chronic arrhythmia surveillance. Dutch health insurers and German statutory sickness funds are piloting reimbursement for cloud-connected wearables in post-ablation monitoring, creating margin pools outside traditional hospital channels. REACH-compliant electrode adhesives expand eligibility for pediatric and geriatric cohorts in domiciliary use.
- Clinics:Outpatient cardiology practices and private diagnostic facilities.
- Diagnostic Centers:Independent testing facilities performing ambulatory ECG services.
Hospitals capture the majority of implantable device value while home care settings expand most quickly as reimbursement frameworks mature.
Technology:
Cloud architecture investments by incumbent vendors are consolidating previously fragmented technology stacks into unified monitoring ecosystems.
- Remote Patient Monitoring:Cloud-integrated platforms enabling continuous data transmission from patient-worn devices to clinical review centers. Hospital systems in the Netherlands deploy these to reduce readmission penalties under diagnosis-related group frameworks, with AI-assisted triage reducing electrophysiologist review burden. The technology requires GDPR-compliant data residency and EMA-coordinated vigilance reporting for serious malfunctions.
- Wireless Monitoring:Bluetooth Low Energy and proprietary radio protocols for device-to-hub connectivity.
- Mobile Health Applications:Smartphone-based patient interfaces for symptom annotation and device control.
- Cloud Computing:Scalable infrastructure for arrhythmia detection algorithm deployment and multi-site data aggregation.
Remote patient monitoring anchors current infrastructure investment while cloud computing climbs the fastest as AI-enabled detection workloads scale.
Application:
Workflow automation priorities in understaffed electrophysiology departments are elevating data analysis capabilities from supporting function to primary purchasing criterion.
- Arrhythmia Detection:Algorithmic identification of atrial fibrillation, ventricular tachycardia, and conduction abnormalities from continuous or triggered ECG streams. Swedish and Danish cardiology departments prioritize detection accuracy in cryptogenic stroke workups, where false-negative rates carry severe clinical consequences. Machine learning embedded in photoplethysmography is reducing false-positive burden, enabling scalable remote workforce deployment.
- Data Analysis:Post-processing tools for burden quantification, trend visualization, and EMR integration. Proprietary data formats from implantable loop recorders require custom mapping to hospital information systems, extending deployment timelines and creating switching costs. EU Green Deal circular economy requirements are incentivizing modular analytics architectures with replaceable components.
- Heart Rate Monitoring:Baseline rhythm surveillance and rate control assessment.
- Patient Management:Care coordination tools linking monitoring data to treatment decisions.
Arrhythmia detection commands the premium pricing tier while data analysis shows the steepest expansion trajectory as workflow integration demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, France, and the Netherlands dominate purchasing decisions, bundling cardiac monitoring contracts with electrophysiology lab equipment to lock in multi-year vendor relationships.
Germany
The Federal Institute for Drugs and Medical Devices operates the DiGA Fast-Track for prescription digital health applications, accelerating wearable ECG reimbursement in outpatient cardiology. Bavaria's university hospital networks in Munich and Erlangen anchor demand for implantable loop recorders with direct-to-physician telemetry capabilities.
France
Public hospital networks bundle cardiac monitoring procurement with electrophysiology lab equipment purchases, unbundling standalone device vendors from preferred supplier lists. ANSM vigilance reporting requirements tighten post-market surveillance for ambulatory ECG systems. The Paris-Île-de-France region concentrates cryptogenic stroke diagnostic protocols requiring 14-day continuous monitoring.
Netherlands
Health insurers pilot reimbursement for cloud-connected wearables in post-ablation monitoring, creating margin pools outside traditional hospital channels. Dutch hospital systems deploy remote patient monitoring to reduce readmission penalties under diagnosis-related group frameworks. The Randstad medical technology cluster in Amsterdam and Rotterdam drives cloud-integrated diagnostic platform adoption.
Sweden
Cardiology departments prioritize patch-based extended monitors for cryptogenic stroke workups, compressing diagnostic timelines from weeks to days. The Medical Products Agency mandates 15-year UDI-compliant record retention for implantable devices. Stockholm's Karolinska University Hospital anchors regional demand for AI-assisted arrhythmia detection workflows.
Poland
Underpenetrated Eastern European markets lack established long-term monitoring reimbursement, creating first-mover advantage for direct-to-hospital contracting models. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products extends CE marking timelines for Class IIa cardiac devices. Warsaw's private cardiology clinics represent emerging demand centers for wearable photoplethysmography systems.
Europe Cardiac Arrhythmia Monitoring Devices Market Competitive Landscape
Player mix skews toward vertically integrated electrophysiology specialists with captive telemetry infrastructure and cloud-native diagnostic platforms with modular analytics architectures. The competitive structure concentrates around three archetypes: implantable device manufacturers with multi-year clinical validation data, consumer wearable vendors penetrating clinical workflows through DiGA pathways, and integrated platform suppliers bundling hardware with AI-assisted detection software. Dominant competitive moves include strategic partnerships between patch-based monitor developers and hospital procurement committees, plus backward integration into cloud computing infrastructure to reduce third-party data residency costs.
Among US-based multinationals, Abbott Laboratories and Medtronic PLC occupy positions within the implantable loop recorder tier, their scale enabling sustained investment in MDR clinical evidence portfolios. Koninklijke Philips NV represents the integrated platform archetype, its Dutch origins aligning with Randstad hospital network procurement preferences. These three exemplify how regulatory compliance scale and direct hospital contracting capabilities determine competitive positioning under tightening EU Medical Device Regulation timelines.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| Koninklijke Philips NV |
| GE Healthcare |
| iRhythm Technologies Inc |
| ZOLL Medical Corporation |
| Biotronik Inc |
| Hill-Rom Holding Inc |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month notified body assessment timelines for Class IIa cardiac devices compress inventory turns and amplify pricing power for MDR-certified manufacturers with pre-committed production slots. This lead-time band concentrates procurement leverage among German and French hospital systems that can secure multi-year bundled contracts, while squeezing margins for smaller vendors facing recertification bottlenecks.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate implantable loop recorder procurement, transferring battery material volatility to hospital buyers while preserving manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels separates cloud-integrated platforms from standalone hardware and unbranded peripherals. Pricing pressure stems from patch-based extended monitors capturing 14-day recording windows at lower per-study costs than traditional Holter systems. Budget-constrained Southern European clinics exhibit highest price sensitivity; academic medical centers in Sweden and Denmark prioritize detection accuracy over unit cost.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production for implantable devices, while Germany and the Netherlands concentrate electrode adhesive formulation and cloud infrastructure hosting. Raw material dependencies span processed lithium carbonate, medical-grade silicone housings, and REACH-compliant conductive polymers. Single-source vulnerability in Chinese-processed battery materials exposes manufacturers to export license volatility and carbon footprint disclosure mandates. Distribution runs through direct hospital contracting with integrated platform vendors, bypassing traditional medical device distributors in France and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe cardiac arrhythmia monitoring devices market is experiencing high-growth disruption as AI-assisted photoplethysmography gains clinical acceptance through Germany's DiGA fast-track pathway, compressing traditional diagnostic timelines and reimbursement frameworks simultaneously.
For Market Incumbents: Compound defensive positioning through backward integration into cloud computing infrastructure and captive telemetry networks to reduce third-party data residency costs. Secure MDR clinical evidence portfolios ahead of 2027 renewal deadlines to exploit notified body bottlenecks constraining competitor certification timelines. Prioritize HL7 FHIR interoperability investments to deepen switching costs in French and Dutch hospital networks bundling procurement contracts. For New Entrants and Emerging Players: Differentiate on AI-assisted arrhythmia detection accuracy to reduce false-positive burden on understaffed electrophysiology departments. Target Poland and Romania's underpenetrated Eastern European markets where reimbursement frameworks remain undeveloped, enabling first-mover advantage through direct-to-hospital contracting models. Pursue DiGA fast-track designation for wearable ECG systems to bypass traditional hospital channel gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core cardiac monitoring divisions amid MDR compliance cost concentration. Five-to-ten year viability favors vertically integrated electrophysiology specialists with captive telemetry infrastructure over standalone hardware vendors. Monitor notified body capacity expansion decisions as the inflection indicator for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Pre-committed notified body engagement secures 18-24 month certification timelines ahead of 2027 MDR renewal deadlines. |
| Hospital System Partnership | Bundled contracting across France's public hospital networks locks in multi-year hardware, analytics, and training agreements. |
| Software Companion Development | AI-assisted triage algorithms reduce electrophysiologist review burden in Dutch remote patient monitoring deployments. |
| Reimbursement Strategy | DiGA fast-track designation unlocks statutory sickness fund coverage for wearable ECG in German outpatient cardiology. |
| Geographic Expansion | Direct-to-hospital models in Warsaw's private cardiology clinics bypass underdeveloped Polish reimbursement frameworks. |
Research Methodology
A standing panel of electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from EMA vigilance databases, BfArM DiGA registry filings, hospital procurement records, and notified body certification disclosures. Bottom-up device shipment estimates and top-down reimbursement expenditure analysis triangulated market sizing across product categories.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, end user setting, technology architecture, and application workflow. CAGRs derived from year-over-year growth rate progression analysis incorporating AI adoption curves, MDR implementation timelines, and reimbursement expansion patterns.
The analysis sits within stated boundaries; outcomes outside sustained DiGA reimbursement expansion or notified body capacity recovery would require recalibration. Forecasts reflect assumptions regarding lithium supply stability, REACH compliance cost trajectories, and electrophysiology workforce availability. Recalibration cycles align with material shifts in MDR enforcement intensity and national reimbursement decisions for digital health integration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market