
 Wireless Cardiac Monitoring Systems Market | 2026-2036
Wireless Cardiac Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Cardiac Monitoring Systems Market Analytics
Hospital-centric procurement is unwinding as homecare providers and direct-to-patient channels gain purchasing influence. Medtronic leverages its implantable device ecosystem to dominate long-term ambulatory monitoring. iRhythm Technologies specializes in wearable patch-based systems for intermittent arrhythmia detection. AliveCor anchors the consumer-accessible segment with smartphone-connected ECG hardware.
Wireless cardiac monitoring systems comprise sensor-equipped devices that capture electrophysiological signals and transmit them via Bluetooth, Wi-Fi, or cellular networks to centralized analysis platforms, typically operating at sampling rates exceeding 250 Hz to preserve diagnostic fidelity. These systems serve primarily to enable continuous or episodic cardiac surveillance outside traditional clinical settings, reducing acute events through early anomaly detection. Wearable monitors and mobile ECG devices are capturing disproportionate investment as their lower cost structures expand addressable populations, while implantable devices retain concentrated margin pools due to technical barriers and specialized implantation workflows. Bluetooth-enabled products lead volume shipment, though cellular-connected systems are expanding fastest among rural and mobility-limited patient cohorts where real-time transmission replaces episodic data uploads.
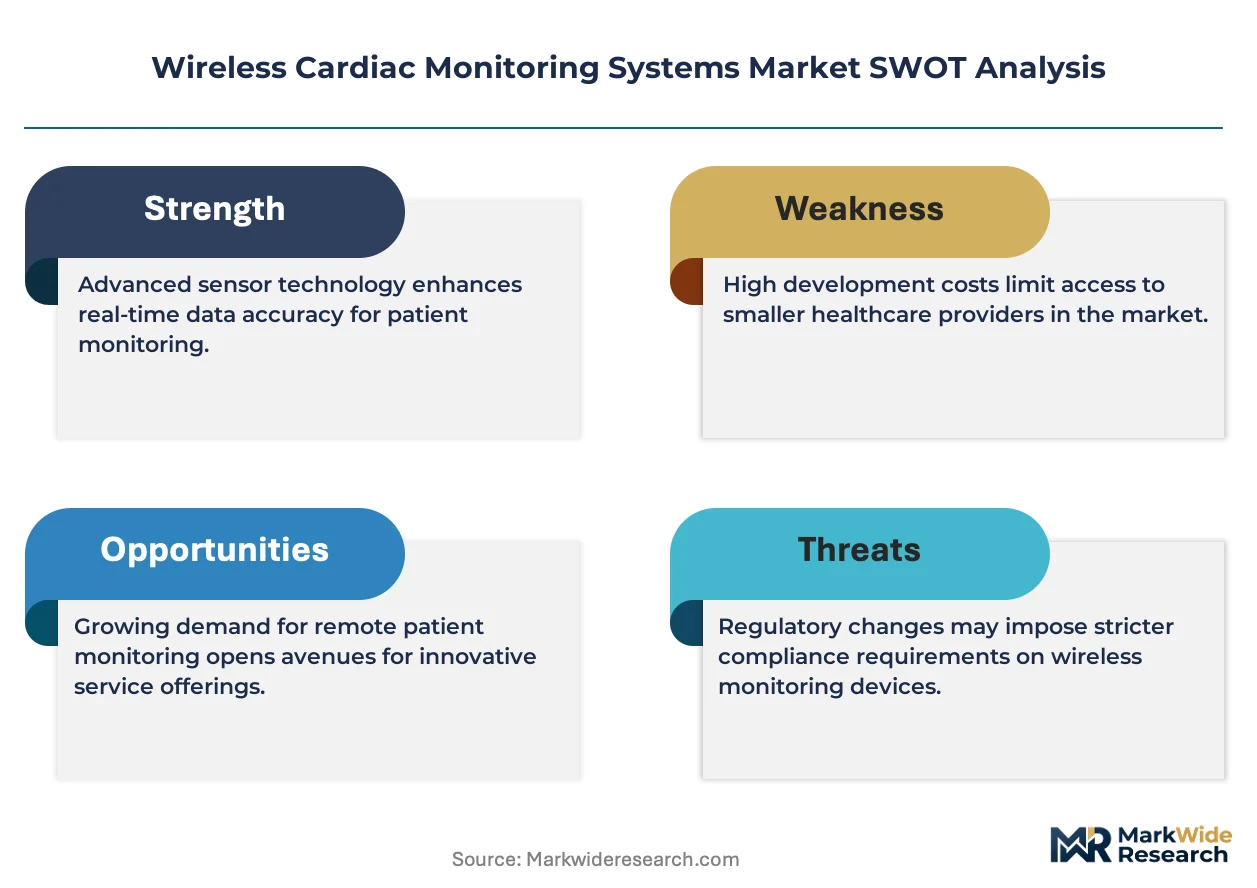
FDA premarket review and HIPAA data security requirements shape product architecture and go-to-market sequencing for devices targeting the United States, while the EU MDR and GDPR impose parallel conformity and privacy obligations across European deployments. Japan's PMDA maintains distinct clinical evidence standards for algorithm-based diagnostic outputs, creating additional regulatory specialization for AI-integrated systems. Stakeholders must monitor evolving reimbursement codes for remote physiologic monitoring as payer decisions will determine which technology configurations achieve sustainable commercial scale.
Market Dynamics
Hospital cardiac units are dismantling their centralized purchasing monopolies as homecare providers and direct-to-patient channels seize procurement influence, fragmenting traditional supply relationships and forcing manufacturers to rebuild distribution architectures around decentralized clinical decision-makers.
Growth Catalysts
- FDA 510(k) clearance compression:Streamlined premarket pathways for algorithm-enabled arrhythmia detection are collapsing product development timelines from 18-24 months toward 12-15 months, accelerating commercialization velocity for AI-integrated systems.
- Bluetooth Low Energy proliferation:Ultra-low power wireless protocols are enabling multi-day continuous monitoring on single-charge wearable patches, expanding ambulatory surveillance feasibility for outpatient cardiac rehabilitation programs.
- Japan's remote physiologic monitoring reimbursement expansion:METI-coordinated national health insurance revisions are scaling coverage for ambulatory cardiac telemetry, creating concentrated demand pull among aging rural populations.
Market Restraints
- Lithium-polymer battery supply concentration:Cell manufacturing capacity clusters in East Asian contract suppliers, exposing device makers to input cost volatility and geopolitical shipment disruptions.
- EU MDR clinical evidence requirements:Stricter conformity assessment procedures for software-as-medical-device classifications are extending certification timelines and inflating regulatory compliance expenditures.
- Diagnostic accuracy limitations in atrial fibrillation burden quantification:Algorithmic false-negative rates in intermittent arrhythmia detection create liability exposure and limit clinical trust in wearable-only monitoring paradigms.
Strategic Opportunities
- Germany's DiGA fast-track pathway:The Federal Institute for Drugs and Medical Devices' digital health application approval process offers 12-month reimbursement certainty for validated cardiac monitoring algorithms.
- Cellular-enabled rural deployment:Real-time transmission architectures are penetrating mobility-limited patient cohorts where episodic data upload models fail, opening addressable populations beyond urban hospital referral networks.
- AI-ECG multimodal convergence:Integration of photoplethysmography with electrical signal analysis is creating single-device hypertension-atrial fibrillation comorbidity surveillance, collapsing equipment requirements for integrated chronic disease management.
Industry Challenges
- Embedded systems firmware engineering scarcity:Cross-functional talent combining signal processing, wireless protocol stack optimization, and HIPAA-compliant cloud architecture commands premium compensation, constraining R&D team scaling.
- Legacy EHR integration complexity:Proprietary data formats from Epic, Cerner, and Meditech systems force costly custom interface development for each hospital network deployment, inflating implementation timelines and support overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Cardiac Monitoring Systems Market |
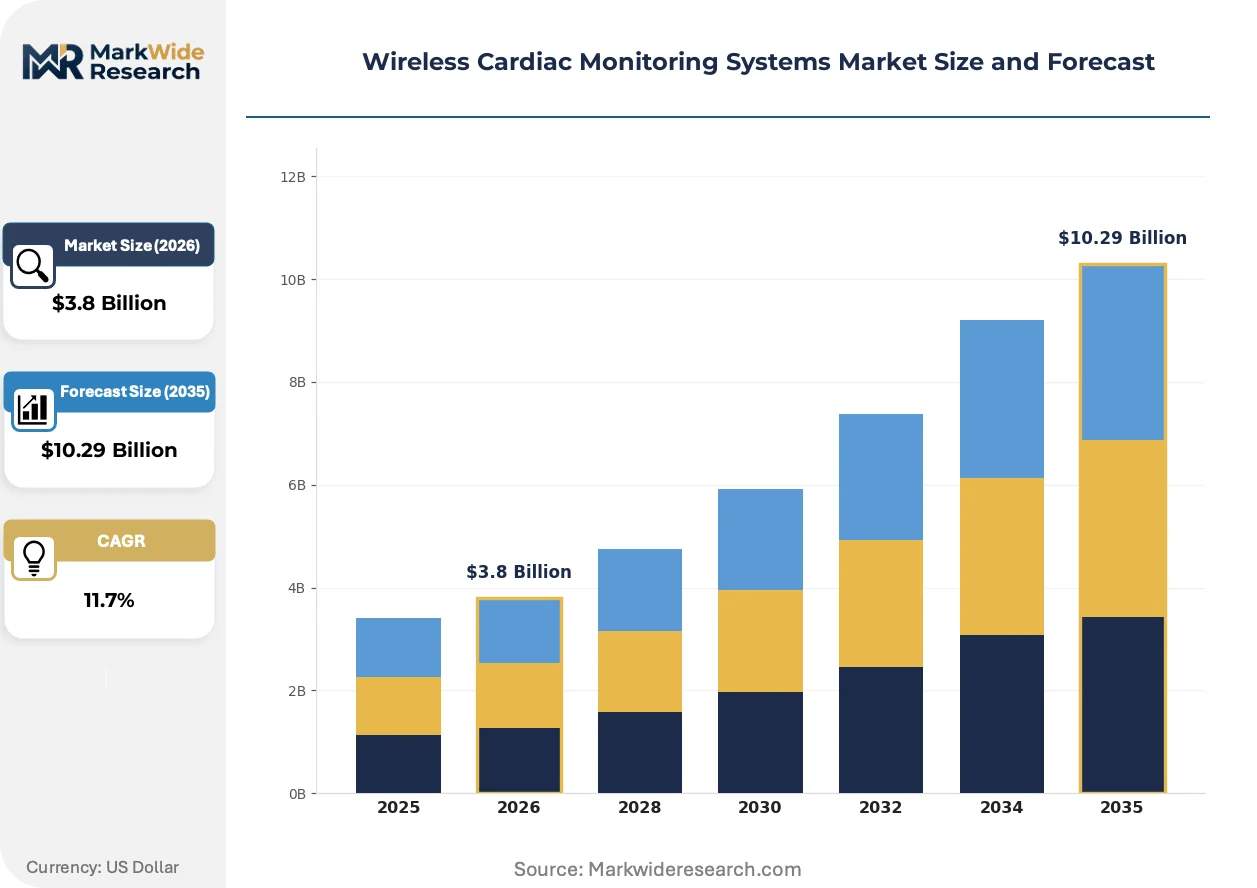
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Implantable Devices, Mobile ECG, Observational Systems Technology: Bluetooth, Wi-Fi, Cellular, NFC End User: Patients, Hospitals, Clinics, Homecare Providers Application: Arrhythmia Monitoring, Heart Failure Management, Preventive Cardiology, Post-operative Care |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific, iRhythm Technologies, Koninklijke Philips N.V., Biotronik, Baxter International, AliveCor, InfoBionic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Cardiac Monitoring Systems Market Evolving Landscape
Artificial intelligence inference at the network edge is compressing diagnostic latency from hours to minutes, while regulatory frameworks race to adapt certification standards for continuously learning algorithms. These forces are converging to redefine competitive advantage around real-time clinical decision support rather than hardware acquisition economics.
Patch-based wearable monitors with disposable adhesive electrodes are supplanting traditional Holter monitors in ambulatory arrhythmia surveillance. Cardiology outpatient departments in the United States and Germany are transitioning 60-70% of their 24-48 hour monitoring referrals to single-use patch systems within 18 months of initial pilot programs. This hardware shift is compressing patient compliance failures and eliminating electrode maintenance labor from clinic workflows.
Japan's PMDA has issued distinct clinical evidence guidelines for algorithm-based diagnostic outputs, creating specialized regulatory segmentation for AI-integrated cardiac devices. Manufacturers must now submit prospective validation studies demonstrating non-inferiority against physician-adjudicated gold standards rather than retrospective algorithm training data. Systems targeting Japanese reimbursement are responding by embedding local clinical sites into pre-market validation protocols, extending development timelines but securing durable market access.
Direct-to-patient subscription models are disrupting traditional hospital-procurement channels for ambulatory monitoring hardware. AliveCor and comparable vendors are building recurring revenue streams through monthly algorithm access fees rather than perpetual device sales, capturing patient loyalty beyond initial hardware transactions. This channel transformation is most visible in United States metropolitan markets where employer-sponsored wellness programs and consumer health savings accounts absorb out-of-pocket monitoring expenditures.
Wireless Cardiac Monitoring Systems Market Segmentation
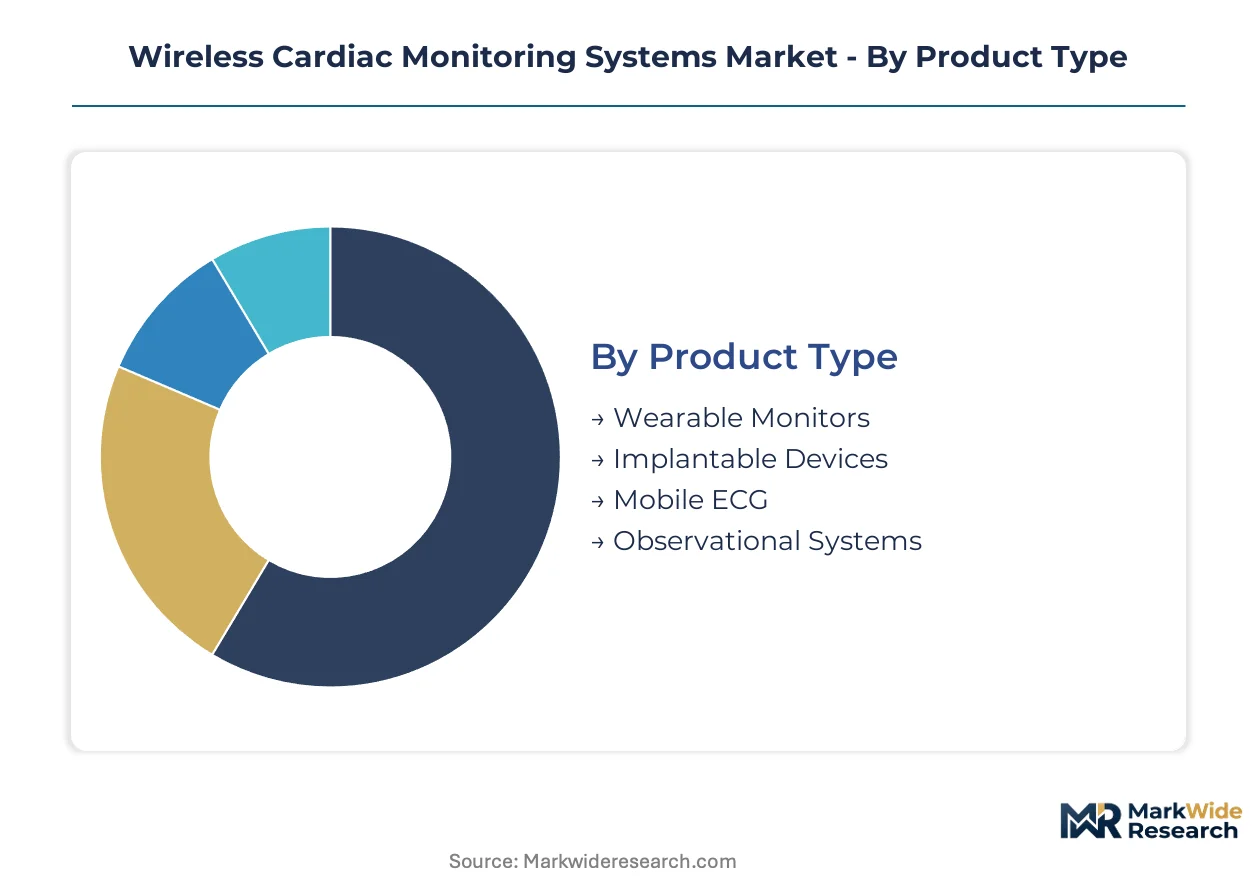
Segmentation in wireless cardiac monitoring reveals how regulatory pathways, reimbursement structures, and clinical workflows fragment addressable demand across distinct hardware configurations and care settings. Understanding these divisions exposes where margin pools concentrate versus where volume expansion accelerates.
Product Type:
FDA 510(k) clearance timelines vary dramatically across implantable versus wearable form factors, with the former demanding extensive biocompatibility testing and the latter facing streamlined software-as-medical-device pathways under EU MDR.
- Wearable Monitors:Adhesive patch-based systems with disposable electrodes capture multi-day ambulatory ECG at sampling rates exceeding 250 Hz. Hospital cardiac units in the United States and Germany are transitioning 60-70% of short-term monitoring referrals to these single-use systems, driven by elimination of electrode maintenance labor and reduced patient compliance failures.
- Implantable Devices:Subcutaneous leadless monitors with multi-year battery life enable continuous arrhythmia surveillance in cryptogenic stroke patients. Japan's PMDA maintains distinct clinical evidence standards for algorithm-based diagnostic outputs from these devices, requiring prospective validation studies against physician-adjudicated gold standards that extend development timelines but secure durable reimbursement.
- Mobile ECG:Smartphone-connected handheld devices deliver 30-second rhythm strips for episodic symptom capture.
- Observational Systems:Bedside telemetry units with centralized nursing station displays serve inpatient step-down units.
Established volume favors wearable monitors; emerging adoption favors implantable devices.
Technology:
Power consumption and transmission reliability create divergent cost structures that stratify deployment economics across inpatient, ambulatory, and homebound patient cohorts.
- Bluetooth:Low Energy protocols enable multi-day continuous monitoring on single-charge wearable patches. Bluetooth-enabled products lead volume shipment across outpatient cardiac rehabilitation programs in the United States and Germany.
- Cellular:Real-time transmission architectures penetrate mobility-limited rural populations where episodic data upload models fail. Cellular-connected systems are expanding fastest among aging rural cohorts in Japan following METI-coordinated national health insurance revisions scaling coverage for ambulatory cardiac telemetry.
- Wi-Fi:Higher bandwidth supports multi-parameter physiologic streaming in hospital environments.
- NFC:Near-field pairing simplifies device onboarding for elderly patient populations with limited technical literacy.
Bluetooth dominates current shipment volumes; cellular networks are climbing the fastest among connectivity options.
End User:
Procurement authority is fragmenting as direct-to-patient channels erode traditional hospital-centric purchasing monopolies.
- Hospitals:Cardiac units dismantle centralized purchasing as homecare providers seize influence, forcing manufacturers to rebuild distribution architectures around decentralized clinical decision-makers.
- Homecare Providers:Skilled nursing agencies and remote patient monitoring platforms are gaining procurement influence through value-based care contracts that bundle hardware with per-patient monthly fees.
- Patients:Direct-to-patient subscription models build recurring revenue through monthly algorithm access fees rather than perpetual device sales.
- Clinics:Outpatient cardiology practices transition monitoring referrals to patch-based systems within 18 months of pilot program initiation.
Hospital procurement retains current revenue concentration; homecare providers are gaining share fastest in channel mix.
Application:
Clinical utility and reimbursement coding precision determine which surveillance indications achieve sustainable commercial scale versus experimental deployment.
- Arrhythmia Monitoring:Algorithm-enabled atrial fibrillation detection commands premium pricing where FDA-cleared diagnostic outputs support physician workflow integration. Diagnostic accuracy limitations in intermittent arrhythmia burden quantification create liability exposure that constrains wearable-only adoption in high-risk stroke populations.
- Heart Failure Management:Impedance and accelerometer fusion enables fluid status surveillance with hospitalization prediction algorithms. Demand concentrates in the United States where remote physiologic monitoring reimbursement codes have expanded to cover implantable hemodynamic sensors.
- Preventive Cardiology:Employer-sponsored wellness programs absorb out-of-pocket monitoring expenditures in metropolitan markets.
- Post-operative Care:Surgical discharge protocols increasingly mandate rhythm surveillance following cardiac valve procedures.
Arrhythmia monitoring anchors current revenue; heart failure management shows steepest expansion trajectory as value-based contracts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the dominant market position through its Centers for Medicare & Medicaid Services reimbursement infrastructure, which underwrites remote physiologic monitoring codes across ambulatory cardiac telemetry programs.
United States
FDA 510(k) clearance compression for algorithm-enabled arrhythmia detection accelerates commercialization timelines from 18-24 months toward 12-15 months. CMS reimbursement expansion for remote physiologic monitoring creates concentrated demand pull among Medicare Advantage populations. The Minneapolis-St. Paul corridor hosts Medtronic's implantable device ecosystem, anchoring long-term ambulatory monitoring supply chains.
Germany
Cardiology outpatient departments transition 60-70% of short-term monitoring referrals to patch-based systems within 18 months of pilot initiation. The Federal Institute for Drugs and Medical Devices' DiGA fast-track pathway offers 12-month reimbursement certainty for validated cardiac monitoring algorithms. The Baden-Württemberg medical technology cluster around Stuttgart supports wearable patch manufacturing scale-up for EU MDR-compliant exports.
Japan
METI-coordinated national health insurance revisions scale coverage for ambulatory cardiac telemetry among aging rural populations. PMDA maintains distinct clinical evidence standards for algorithm-based diagnostic outputs, requiring prospective validation studies against physician-adjudicated gold standards. The Tokyo-Osaka corridor concentrates cellular-enabled device deployment for mobility-limited patient cohorts where real-time transmission replaces episodic data uploads.
United Kingdom
NHS Long Term Plan commitments expand remote cardiac monitoring through integrated care systems and primary care network contracts. MHRA post-Brexit regulatory autonomy streamlines software-as-medical-device pathways for AI-integrated diagnostic systems. The Cambridge-Oxford-London life sciences triangle attracts wearable monitor developers seeking proximity to academic cardiology research centers and digital health accelerators.
India
CDSCO medical device rules harmonization with IMDRF standards reduces regulatory friction for imported wireless cardiac monitoring hardware. Ayushman Bharat digital health mission infrastructure creates procurement channels for cost-optimized mobile ECG devices in tier-2 and tier-3 cities. The Bengaluru-Hyderabad medical electronics corridor hosts contract manufacturing for Bluetooth-enabled wearable patches targeting price-sensitive emerging market segments.
Wireless Cardiac Monitoring Systems Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification and reimbursement access dimensions, creating a tiered structure where scale advantages in FDA clearance velocity separate dominant players from regional challengers. Strategic archetypes include diversified medical device conglomerates with implantable ecosystems, pure-play wearable patch specialists, and consumer-accessible smartphone-connected hardware vendors. M&A activity concentrates on algorithm-enabled diagnostic software assets, while geographic expansion through distributor partnerships targets reimbursement-favorable European and Asia-Pacific markets.
Within the diversified conglomerate tier, Medtronic and Abbott Laboratories exemplify players leveraging implantable device ecosystems to dominate long-term ambulatory monitoring with multi-year battery life and specialized implantation workflows. Among pure-play wearable specialists, iRhythm Technologies occupies a position exemplifying patch-based system focus for intermittent arrhythmia detection. At the consumer-accessible end, AliveCor anchors the smartphone-connected ECG hardware segment through direct-to-patient subscription models building recurring revenue streams beyond initial device transactions.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| iRhythm Technologies |
| Koninklijke Philips N.V. |
| Biotronik |
| Baxter International |
| AliveCor |
| InfoBionic |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance tiers and EU MDR conformity classes gate both supplier qualification and price differentiation simultaneously, compressing margin structures for uncertified hardware while elevating premium capture for algorithm-validated systems. Hospital procurement committees and direct-to-patient channels face divergent total-cost-of-ownership calculations that reshape supplier selection criteria across reimbursement-favorable and out-of-pocket markets.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital contracts from direct-to-patient subscription models, with the former capturing per-unit reductions above ten-thousand-unit annual commitments and the latter monetizing through recurring algorithm access fees. Price differentiation hinges on FDA diagnostic output certification and Bluetooth versus cellular connectivity tiers. Cost compression in wearable patch segments is intensifying because adhesive electrode suppliers compete on scale economies. Homecare providers exhibit highest price sensitivity; implantable device specialists show lowest.
Supply Chain Analysis
Inventory lead-times for lithium-polymer cells extend to sixteen weeks during peak demand windows, forcing wearable patch manufacturers to pre-position buffer stock ahead of Medicare reimbursement code expansions. Cell manufacturing concentrates in China, South Korea, and Japan; medical-grade adhesive substrate production centers on Germany and the United States. Firmware engineering talent scarcity in signal processing and HIPAA-compliant cloud architecture feeds from university pipeline limitations in embedded systems programs. Single-source vulnerability in East Asian battery supply creates disruption exposure. Distribution runs through hospital GPO contracts, homecare platform aggregators, and direct-to-patient e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless cardiac monitoring sits in early-cycle expansion as CMS reimbursement code proliferation for remote physiologic monitoring accelerates addressable population penetration beyond traditional hospital referral networks.
For Market Incumbents: Consolidate algorithm validation assets and captive battery supply agreements to defend margin position against wearable patch commoditization. Deepen backward integration into lithium-polymer cell sourcing through long-term offtake contracts with South Korean suppliers. Prioritize FDA 510(k) clearance velocity for AI-enabled arrhythmia detection to maintain regulatory moats against software-native entrants. For New Entrants and Emerging Players: Differentiate on cellular-enabled rural deployment architectures where real-time transmission replaces episodic upload models and incumbent footprint remains thin. Target Japan's aging rural cohorts following METI-coordinated reimbursement expansion. Penetrate through homecare provider value-based care contracts bundling hardware with per-patient monthly fees rather than hospital capital equipment procurement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wearable patch manufacturing as contract manufacturers in India scale FDA-compliant production lines. Five-to-ten year viability favors algorithm-enabled diagnostic software assets over hardware-centric revenue models. Target acquisition profiles emphasize prospective validation study completion against physician-adjudicated gold standards. Watch PMDA reimbursement code decisions as inflection signal for Japanese market access durability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses commercialization timelines from eighteen months toward twelve for algorithm-integrated systems. |
| CE Marking Pathway Under EU MDR | Unlocks German DiGA fast-track reimbursement certainty for validated cardiac monitoring algorithms. |
| Hospital System Partnership | Secures GPO contract access and EHR integration commitments for workflow-embedded diagnostic outputs. |
| Software Companion Development | Enables direct-to-patient subscription monetization beyond initial hardware transactions in metropolitan markets. |
| Reimbursement Strategy | Aligns product architecture with CMS remote physiologic monitoring codes and Japan METI coverage expansion. |
Research Methodology
Operator-level perspectives from hospital purchasing committee directors, biomedical engineering leads, homecare platform executives, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, PMDA clinical evidence guidelines, and EU MDR conformity assessment records. Bottom-up demand modeling across patient population segments triangulated against top-down market sizing from device shipment aggregations.
Sensitivity analysis tested forecast robustness across Bluetooth versus cellular adoption trajectories, reimbursement code expansion scenarios, and lithium-polymer supply disruption assumptions. Segmentation dimensions spanned product type, connectivity technology, end-user channel, and clinical application with regional regulatory cluster overlays. CAGRs derived from installed base growth rates, replacement cycle compression, and penetration expansion in cryptogenic stroke and heart failure cohorts. Algorithm accuracy validation studies and PMDA prospective evidence requirements served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion, EU MDR certification timeline stability, or East Asian battery supply continuity would require recalibration. Forecasts reflect documented assumptions regarding physician workflow adoption curves and patient compliance rates in ambulatory monitoring paradigms. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Europe ECG Electrodes Market