
 North America Cardiac Monitoring Market | 2026-2036
North America Cardiac Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cardiac Monitoring Market Analytics
US medical device manufacturing is repositioning toward miniaturized sensor production for ambulatory cardiac care. Abbott Laboratories leverages its structural heart portfolio to anchor catheter-based monitoring solutions across integrated delivery networks. Medtronic PLC sustains deep R&D intensity in implantable loop recorders, while iRhythm Technologies Inc. specializes in AI-enabled patch electrocardiography for outpatient arrhythmia detection.
Cardiac monitoring encompasses the continuous or intermittent acquisition, transmission, and analysis of electrical and hemodynamic cardiac parameters through surface electrodes, implanted sensors, or photoplethysmographic optics, typically operating at sampling rates exceeding 250 Hz for diagnostic-grade resolution. These systems serve to detect rhythm disturbances, ischemic events, and hemodynamic deterioration before clinical decompensation. Wearable devices represent the fastest-expanding product category as optical PPG arrays and multi-lead ECG patches displace conventional Holter monitors in low-acuity settings, while telemetry and wireless monitoring technologies capture disproportionate margin pools through recurring software subscription revenue tied to cloud-based interpretation platforms.
FDA premarket notification requirements and HIPAA data security mandates shape product development cycles and channel economics for device manufacturers serving US healthcare systems. CMS national coverage determinations for remote cardiac monitoring directly influence provider procurement decisions and patient access thresholds. Stakeholders must track evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms and state-level telehealth parity legislation to anticipate reimbursement trajectory shifts.
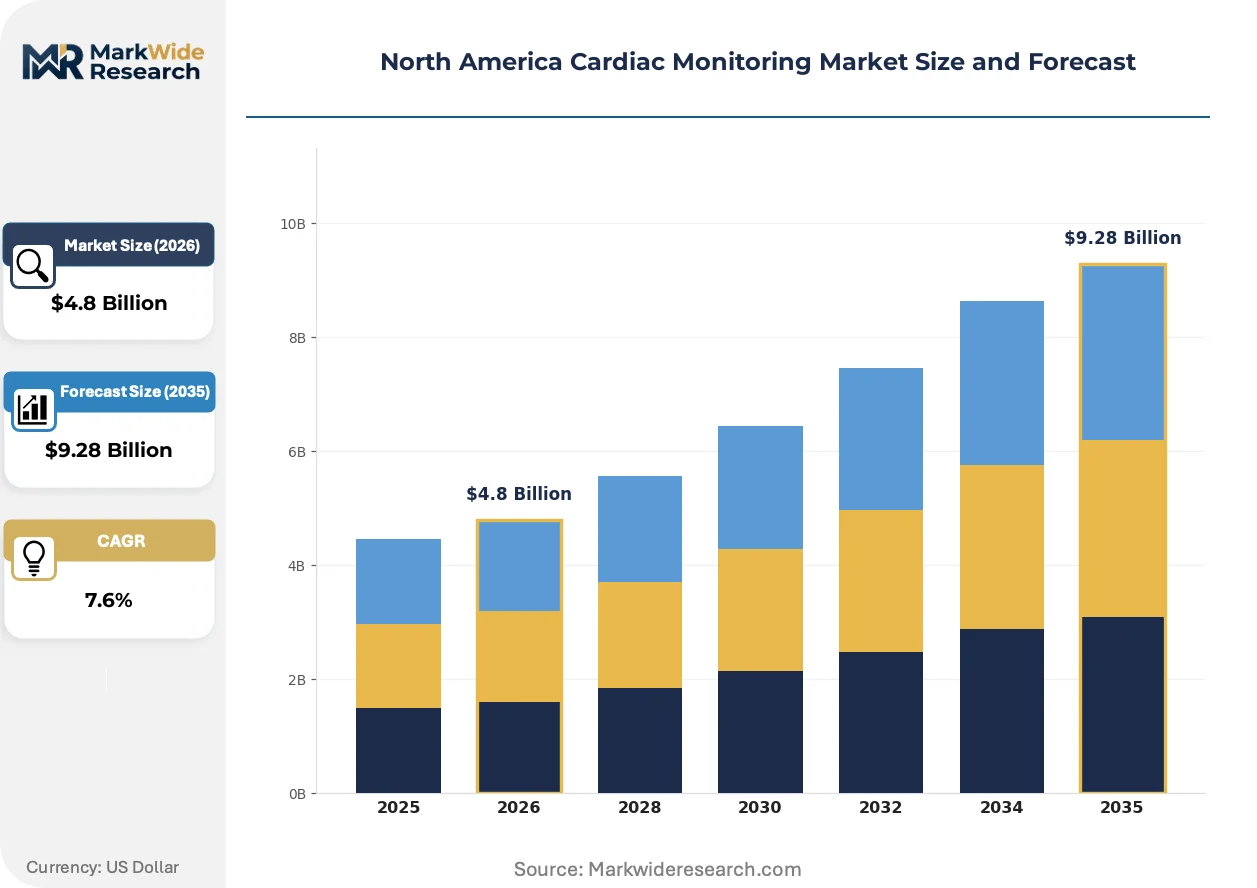
Market Dynamics
CMS reimbursement expansion for remote patient monitoring is restructuring procurement economics across US hospital systems and ambulatory networks. This policy lever is accelerating capital reallocation from bedside telemetry toward wearable and implantable ambulatory platforms.
Growth Catalysts
- CMS Remote Monitoring Reimbursement:National coverage determinations for cardiac telemetry outside traditional facility settings are expanding provider revenue streams and patient access thresholds.
- Optical PPG Arrays:Photoplethysmographic sensors embedded in consumer-accessible wearables are capturing arrhythmia data at diagnostic-grade sampling rates previously restricted to clinical Holter systems.
- Texas and California Hospital Networks:Integrated delivery networks in these states are deploying cloud-connected telemetry platforms that synchronize real-time cardiac data with electronic health record architectures.
Market Restraints
- FDA 510(k) Premarket Notification:Regulatory clearance timelines for AI-enabled diagnostic algorithms extend product development cycles and compress first-mover advantage windows.
- Semiconductor Foundry Concentration:Miniaturized sensor production depends on concentrated Asian contract manufacturing capacity, exposing supply continuity to geopolitical friction.
- Optical Artifact Vulnerability:Motion-induced signal degradation in PPG-based devices limits diagnostic reliability during high-activity patient states, constraining addressable clinical indications.
Strategic Opportunities
- Homecare Settings:Underpenetrated post-acute and chronic disease management environments present expansion vectors for patch-based ECG monitors with automated cloud interpretation.
- HIPAA-Compliant Cloud Platforms:Data security mandates are creating competitive moats for vendors with certified health information infrastructure and recurring software subscription models.
- AI-ECG Convergence:Machine learning classification algorithms trained on large-scale arrhythmia databases are enabling automated preliminary reads that reduce cardiologist interpretation burden.
Industry Challenges
- Electrophysiologist Interpretation Bottleneck:Specialist workforce scarcity constrains scalable analysis of high-volume ambulatory monitoring data streams.
- EHR Integration Complexity:Health system IT departments face multi-month implementation cycles to synchronize proprietary telemetry data formats with existing electronic record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cardiac Monitoring Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Implantable Loop Recorders, Event Monitors, Wearable Devices End User: Hospitals, Cardiology Clinics, Homecare Settings, Rehabilitation Centers Technology: Telemetry, Wireless Monitoring, Optical Technologies, Miniaturized Sensors Application: Arrhythmia Detection, Remote Patient Monitoring, Heart Failure Management, Postoperative Care |
| Companies Covered | Abbott Laboratories, Medtronic PLC, Boston Scientific Corporation, iRhythm Technologies Inc., BIOTRONIK, Koninklijke Philips N.V., General Electric Company, Baxter International Inc, Schiller AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cardiac Monitoring Market Evolving Landscape
Multi-lead ECG patches and implantable loop recorders are converging with artificial intelligence interpretation layers to automate arrhythmia detection workflows. This technological stack is compressing diagnostic latency and shifting clinical decision-making toward predictive rather than reactive models.
Photoplethysmographic optical sensors are integrating with accelerometer arrays and temperature compensation algorithms to maintain signal fidelity across ambulatory patient motion states. Outpatient cardiology clinics in the United States are adopting these hybrid sensing platforms for extended monitoring beyond traditional 24-48 hour Holter windows. The technology is integrating diagnostic-grade cardiac surveillance into consumer-accessible form factors that expand addressable patient populations.
FDA guidance documents on artificial intelligence-enabled medical devices are establishing predicate requirements for algorithm training datasets and performance validation protocols. Device manufacturers must demonstrate representative demographic coverage and prospective clinical validation to secure premarket clearance. Cardiac monitoring systems with embedded machine learning classifiers face heightened scrutiny relative to conventional rule-based detection algorithms.
Hospital procurement committees are consolidating vendor relationships around integrated platform solutions that combine hardware, cloud analytics, and EHR connectivity. Cardiology departments are displacing fragmented point solutions in favor of enterprise contracts with telemetry vendors offering end-to-end data infrastructure. This concentration dynamic favors established players with certified health information technology architectures and existing health system integration expertise.
North America Cardiac Monitoring Market Segmentation
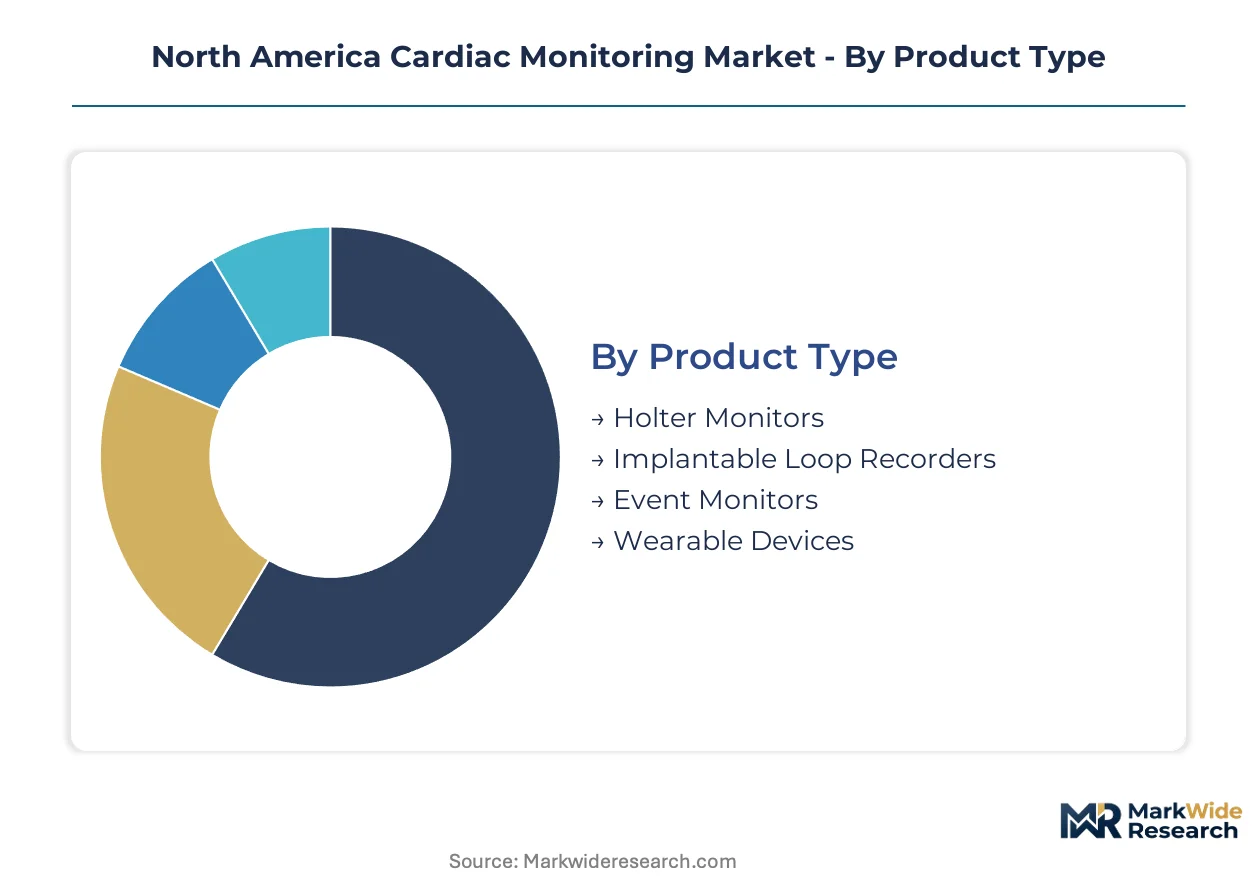
Cardiac monitoring procurement patterns diverge sharply across clinical environments, with reimbursement codes and integration requirements driving distinct technology preferences. Device specifications, sampling rates, and connectivity architectures must align precisely with end-user workflows to secure adoption.
Product Type:
Replacement cycles vary from 18-month consumer wearables to 5-year implantable systems, creating tiered revenue recognition patterns across manufacturer portfolios.
- Holter Monitors:Multi-lead ambulatory recorders with 24-48 hour recording windows remain the diagnostic standard for syncope workups. Demand concentrates in California cardiology clinics where extended monitoring protocols exceed typical wearable battery life.
- Implantable Loop Recorders:Subcutaneous devices with 2-3 year monitoring duration capture infrequent arrhythmias in cryptogenic stroke patients. Texas hospital networks prioritize these for stroke center certification requirements.
- Event Monitors:Patient-activated or auto-triggered external recorders bridge diagnostic gaps between Holter and implantable options.
- Wearable Devices:Patch ECG and wrist-worn PPG sensors with automated cloud transmission are displacing conventional monitors in low-acuity settings.
Volume placements concentrate in Holter Monitors; the faster expansion belongs to Wearable Devices.
End User:
Procurement authority and reimbursement pathways create four distinct customer archetypes with incompatible vendor qualification requirements.
- Hospitals:Integrated delivery networks demand enterprise telemetry platforms with real-time EHR synchronization and 24/7 monitoring center support. Texas and California health systems lead capital deployment for cloud-connected infrastructure.
- Cardiology Clinics:Outpatient practices prioritize patch-based monitors with automated preliminary interpretation to extend physician capacity.
- Homecare Settings:Post-acute and chronic disease management environments present expansion vectors for patient-friendly devices with CMS remote monitoring reimbursement.
- Rehabilitation Centers:Cardiac recovery facilities require motion-tolerant monitoring during supervised exercise protocols.
Revenue concentration sits with Hospitals; Homecare Settings are climbing the fastest as CMS policy shifts site of care.
Technology:
Component miniaturization and wireless protocol standardization are collapsing cost structures across sensing modalities.
- Telemetry:Bedside and ambulatory radio-frequency transmission systems with centralized monitoring stations remain essential for high-acuity environments. California hospital networks drive demand for seamless EHR integration.
- Wireless Monitoring:Bluetooth and cellular-enabled devices with cloud backhaul support asynchronous clinician review and patient-generated data workflows.
- Optical Technologies:Photoplethysmographic sensors in consumer-accessible form factors capture pulse rate and rhythm data at diagnostic-grade resolution.
- Miniaturized Sensors:MEMS-based accelerometer and temperature compensation arrays maintain signal fidelity during patient motion.
Installed base dominance belongs to Telemetry; Optical Technologies are gaining share fastest through consumer crossover applications.
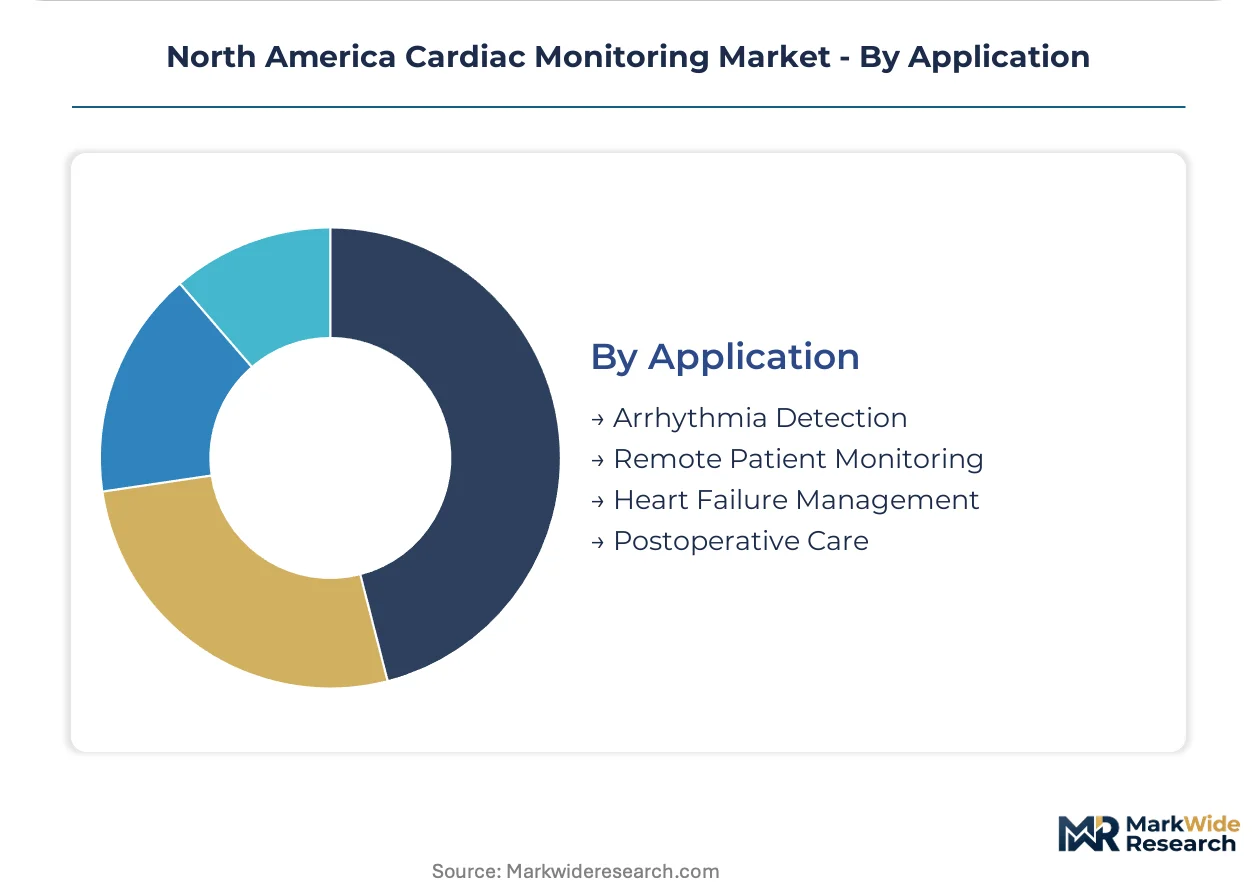
Application:
Clinical utility and reimbursement specificity determine technology selection across diagnostic and management use cases.
- Arrhythmia Detection:Atrial fibrillation screening and stroke prevention protocols drive the highest monitoring volume, with AI-enabled patch devices automating preliminary classification.
- Remote Patient Monitoring:CMS national coverage determinations for cardiac telemetry outside facility settings are expanding provider revenue streams and patient access thresholds.
- Heart Failure Management:Hemodynamic monitoring through implantable pressure sensors and wearable impedance measurements supports guideline-directed medical therapy titration.
- Postoperative Care:Surgical recovery units deploy continuous telemetry for early detection of ischemic events and rhythm disturbances.
Procedure volume concentrates in Arrhythmia Detection; Remote Patient Monitoring shows the steepest expansion trajectory as reimbursement policy matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in the southwestern United States anchor sensor supply chains for cardiac monitoring hardware. Texas Instruments and analog semiconductor foundries in Arizona feed miniaturized component demand across North American device assembly networks. Regional procurement patterns diverge sharply between integrated health systems and independent cardiology practices.
United States
Texas Medical Center in Houston and Stanford Health Care in California drive enterprise telemetry platform deployments. FDA 510(k) premarket notification requirements shape product development cycles for AI-enabled diagnostic algorithms. Minneapolis-St. Paul retains deep manufacturing heritage in implantable cardiac devices with Medtronic's operational headquarters anchoring regional R&D intensity.
California
Kaiser Permanente and Sutter Health networks prioritize cloud-connected EHR synchronization for ambulatory cardiac monitoring. CMS national coverage determinations for remote patient monitoring expand provider revenue streams across Sacramento and Los Angeles metropolitan clusters. Silicon Valley optical sensor startups supply photoplethysmographic arrays to wearable device manufacturers.
Texas
MD Anderson Cancer Center and Baylor Scott & White Health systems deploy stroke center certification protocols requiring implantable loop recorders. State-level telehealth parity legislation reduces reimbursement friction for rural cardiac monitoring access. Dallas-Fort Worth medical device distribution hubs coordinate logistics for southwestern hospital networks.
Canada
University Health Network in Toronto and McGill University Health Centre pilot AI-ECG convergence platforms for arrhythmia screening. Health Canada medical device licensing requirements align with FDA predicate standards while maintaining distinct post-market surveillance protocols. Montreal's wearable technology research institutes collaborate with Quebec cardiology clinics on patch-based monitoring validation.
Mexico
Guadalajara medical device manufacturing parks assemble subcomponents for US-bound cardiac monitors under maquiladora arrangements. COFEPRIS regulatory harmonization initiatives with FDA streamline import pathways for diagnostic equipment. Tijuana border zone electronics assemblers specialize in miniaturized sensor packaging for ambulatory monitoring devices.
North America Cardiac Monitoring Market Competitive Landscape
Global majors compete with regional champions across technology licensing and health system integration depth. The vendor base stratifies into three tiers: diversified medical technology conglomerates with structural heart portfolios, pure-play cardiac monitoring specialists with AI-enabled platforms, and contract manufacturers with miniaturized sensor expertise. Dominant competitive moves include strategic partnerships for EHR connectivity and portfolio diversification into remote patient monitoring software subscriptions.
Within the diversified conglomerate tier, Abbott Laboratories and Medtronic PLC exemplify integrated delivery network anchoring strategies through catheter-based and implantable monitoring solutions. iRhythm Technologies Inc. occupies a distinct position as a pure-play specialist in AI-enabled patch electrocardiography for outpatient arrhythmia detection. These three companies represent contrasting archetypes: platform breadth versus algorithmic specialization versus hardware-software convergence.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| Boston Scientific Corporation |
| iRhythm Technologies Inc. |
| BIOTRONIK |
| Koninklijke Philips N.V. |
| General Electric Company |
| Baxter International Inc |
| Schiller AG |
| Others |
Value Network & Pricing Analysis
CMS reimbursement compression for remote cardiac monitoring is forcing device manufacturers to unbundle hardware from software services, reshaping how suppliers structure component sourcing and margin capture across production tiers.
Pricing Analysis
Warranty and cloud interpretation service bundling separates premium telemetry vendors from economy-tier Holter manufacturers in the North America cardiac monitoring market. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, EHR integration depth, and AI-enabled diagnostic capability. Price differentiation stems from certification grade and vertical integration into sensor production. Cost compression in the economy tier is intensifying because Asian contract manufacturers compete on component volume. Homecare settings and rural clinics exhibit highest price sensitivity; integrated delivery networks in Texas and California demonstrate lowest sensitivity due to enterprise contract scale.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from Texas Medical Center and Kaiser Permanente networks, while distributor-mediated routes serve independent cardiology clinics. Miniaturized sensor production draws from Taiwan, South Korea, and Arizona semiconductor foundries. Raw material dependencies include silicon wafers, MEMS accelerometers, and photoplethysmographic optical arrays. Single-source vulnerability in advanced node semiconductor fabrication exposes continuity to geopolitical friction. Distribution runs through regional medical device hubs in Dallas-Fort Worth and Minneapolis-St. Paul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
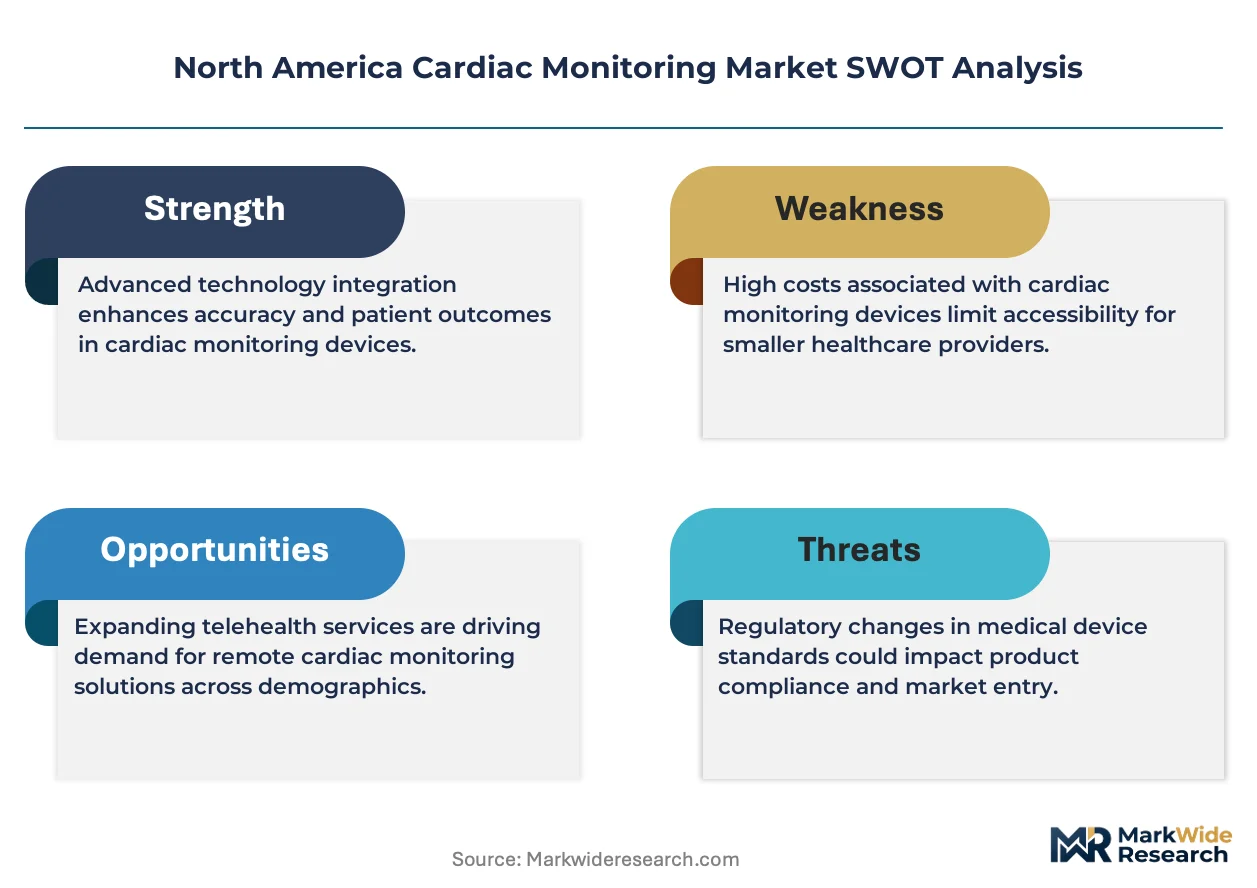
The North America cardiac monitoring market is consolidating around platform vendors with certified health information infrastructure, as FDA premarket notification timelines and EHR integration complexity force subscale players toward exit or acquisition.
For Market Incumbents: Extend cloud analytics subscription attach rates to implantable and patch-based portfolios before pure-play AI specialists capture outpatient arrhythmia detection share. Secure stroke center certification partnerships with Texas hospital networks to anchor implantable loop recorder demand. Deepen backward integration into MEMS sensor production to reduce Asian foundry exposure and defend margin position against optical PPG array commoditization. For New Entrants and Emerging Players: Capture post-acute homecare monitoring contracts in underserved rural markets where CMS remote patient monitoring reimbursement has expanded but incumbent presence remains thin. Target cardiology clinics seeking automated preliminary ECG interpretation to extend physician capacity without enterprise IT infrastructure. Pursue white-label partnerships with consumer wearable manufacturers seeking diagnostic-grade regulatory clearance. For Investors and Strategic Acquirers: Re-rating potential sits with AI-ECG convergence platforms given FDA guidance momentum on algorithm-enabled medical devices and electrophysiologist workforce scarcity. Long-term viability favors vendors with recurring software revenue exceeding hardware depreciation cycles. Target acquisition archetypes include patch-based monitor specialists with Health Canada licensing and Quebec validation partnerships. Watch CMS national coverage determination expansion for ambulatory telemetry as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI-Enabled Diagnostic Algorithm | Accelerates premarket clearance for machine learning classifiers trained on representative demographic datasets. |
| Hospital System Partnership for EHR Integration | Secures multi-year enterprise contracts with California integrated delivery networks requiring real-time data synchronization. |
| Software Companion Development for Patch Monitors | Enables automated cloud interpretation that reduces cardiologist review burden in outpatient settings. |
| Reimbursement Strategy for Remote Patient Monitoring | Aligns product positioning with CMS national coverage determinations expanding provider revenue streams. |
| CE Marking Pathway for Optical PPG Arrays | Facilitates cross-border commercialization into Canadian markets through Health Canada harmonization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America cardiac monitoring market analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and electrophysiologists combined with FDA 510(k) databases, CMS Medicare reimbursement files, and hospital procurement records. Bottom-up unit shipment modeling triangulated against top-down expenditure estimates from integrated delivery network capital budgets.
Product-type granularity modeled Holter monitors, implantable loop recorders, event monitors, and wearable devices separately, with technology-tier splits for telemetry, wireless monitoring, optical PPG, and miniaturized sensors across the analysis window. End-user segmentation captured hospitals, cardiology clinics, homecare settings, and rehabilitation centers with distinct procurement authority patterns. CAGRs derived from logistic adoption curves fitted to reimbursement policy phase-in schedules and health system IT upgrade cycles. Forecast inputs incorporated electrophysiologist workforce growth constraints and semiconductor foundry capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA artificial intelligence guidance evolution, CMS remote monitoring reimbursement expansion velocity, and geopolitical disruption to Asian sensor supply chains. Forecasts reflect documented assumptions regarding health system EHR upgrade timelines and state-level telehealth parity legislation adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Global Cardiac Restoration Systems Market