
 Europe Cardiac Monitoring Market | 2026-2036
Europe Cardiac Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cardiac Monitoring Market Foresight
A widening capability gap between capital-intensive implantable device manufacturers and agile wearable technology firms is rotating competitive advantage toward software-integrated platforms. Medtronic leverages its deep manufacturing scale across European production facilities to sustain leadership in implantable loop recorders. Abbott Laboratories anchors its position through diagnostic equipment specialization, while iRhythm Technologies competes aggressively in algorithm-driven ambulatory ECG analysis.
Cardiac monitoring encompasses the continuous or intermittent acquisition, processing, and transmission of electrophysiological data to detect arrhythmias, ischemia, or hemodynamic instability, typically operating via multi-lead ECG acquisition at sampling rates exceeding 250 Hz with wireless transmission to centralized telemetry stations. Wearable monitors and remote monitoring technology capture expanding margin pools as home-based arrhythmia detection shifts from hospital-centric delivery, while implantable devices retain premium pricing through extended monitoring duration and diagnostic yield superiority over external alternatives.
The EU Medical Device Regulation and CE marking framework administered by notified bodies across member states elevate clinical evidence thresholds for novel cardiac monitoring technologies, directly shaping product development timelines and market access pathways. Germany's Federal Institute for Drugs and Medical Devices and France's ANSM enforce national vigilance reporting that reinforces post-market surveillance obligations for connected cardiac devices. Stakeholders must weigh regulatory compliance investments against the pace of AI-enabled diagnostic algorithm deployment in ambulatory settings.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product development timelines while simultaneously elevating clinical evidence requirements for connected cardiac devices. This regulatory pressure is forcing manufacturers to restructure R&D investments and accelerate post-market surveillance capabilities.
Growth Catalysts
- Cloud-based telemetry platforms:Hospital networks in Germany and France are deploying centralized cardiac monitoring systems that enable real-time arrhythmia detection across distributed care settings.
- Remote patient monitoring programs:France's ANSM has streamlined vigilance reporting pathways for connected devices, reducing regulatory friction for ambulatory ECG deployments.
- Wearable algorithm sophistication:AI-enabled diagnostic tools for atrial fibrillation detection are achieving parity with traditional Holter monitoring in outpatient settings.
Market Restraints
- CE marking timeline compression:The MDR's expanded technical documentation requirements are extending notified body review cycles by 12-18 months for novel cardiac wearables.
- Sensor component concentration:MEMS-based ECG electrodes and wireless transmission modules rely heavily on East Asian semiconductor foundries, creating supply vulnerability.
- Reimbursement fragmentation:Germany's Federal Institute for Drugs and Medical Devices maintains distinct coding for implantable versus external monitors, limiting cross-category substitution.
Strategic Opportunities
- Home-based arrhythmia detection:Underpenetrated markets in Spain and Italy present expansion vectors for patch-based ECG monitors that bypass traditional hospital-centric delivery.
- EU AI Act compliance:Early alignment with high-risk medical device AI standards creates first-mover positioning for algorithm-driven diagnostic platforms.
- Telemedicine integration:Convergence of cardiac telemetry with video consultation platforms is opening subscription-based monitoring revenue streams in Nordic healthcare systems.
Industry Challenges
- Clinical data science talent scarcity:The intersection of electrophysiology expertise and machine learning engineering remains critically understaffed across European medical device R&D centers.
- Legacy hospital IT integration:Cloud-based cardiac monitoring platforms face interoperability friction with entrenched on-premise electronic health record systems in French and German hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cardiac Monitoring Market |
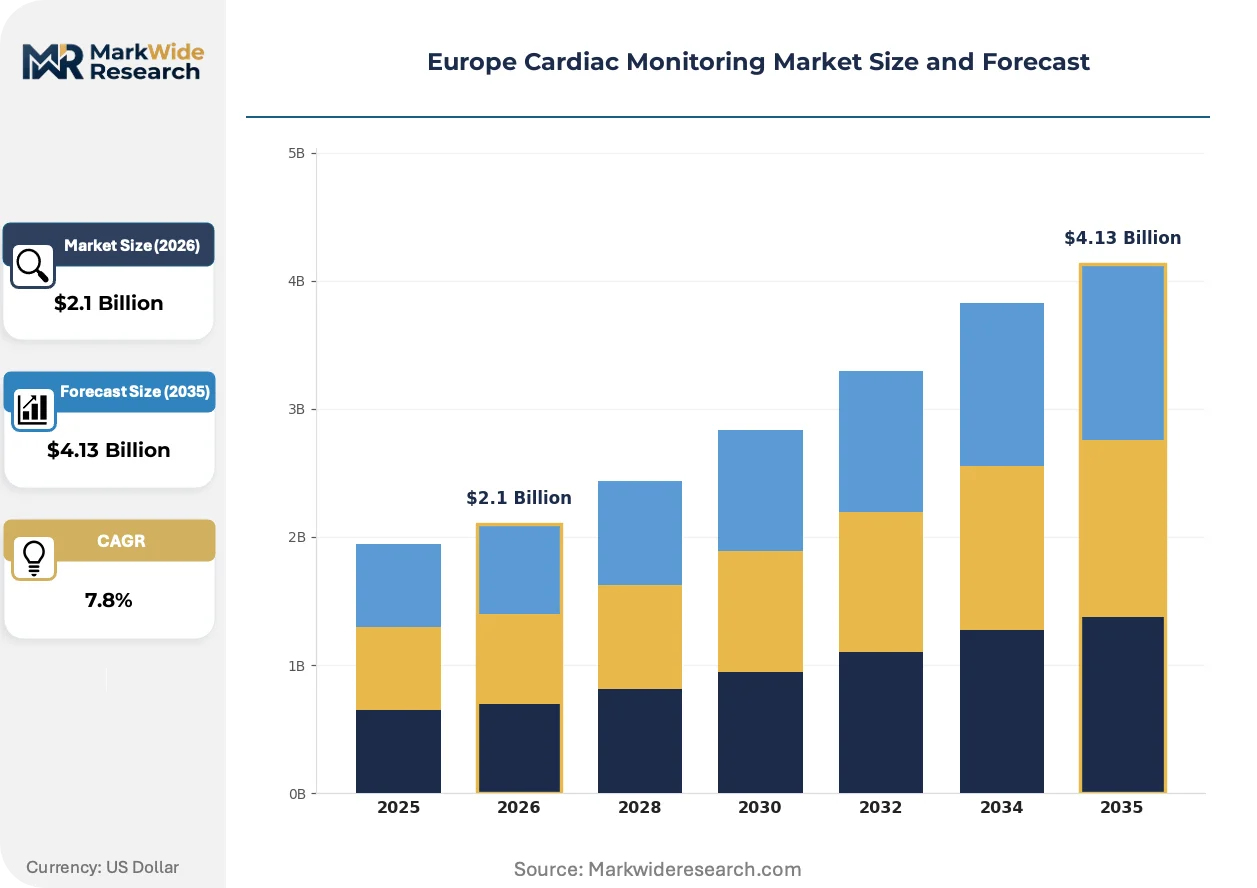
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Implantable Devices, Portable Monitors, Diagnostic Equipment End User: Hospitals, Clinics, Home Care, Telehealth Services Technology: ECG, Holter Monitoring, Electrophysiological Mapping, Remote Monitoring Application: Arrhythmia Management, Heart Failure Monitoring, Post-Operative Care, Preventive Care |
| Companies Covered | Abbott Laboratories, Medtronic, Boston Scientific Corporation, GE Healthcare, Koninklijke Philips N.V., Biotronik SE & Co KG, Hill-Rom Holdings, Schiller AG, iRhythm Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cardiac Monitoring Market Shifts & Advancements
Cardiac monitoring technology is splitting into two distinct performance tiers: premium implantable systems delivering extended diagnostic yield, and software-integrated wearables capturing ambulatory market share through algorithmic sophistication.
Multi-lead ECG acquisition at sampling rates exceeding 250 Hz is bifurcating the diagnostic pathway between acute hospital telemetry and outpatient arrhythmia screening. Cardiology departments in German university hospitals are adopting high-fidelity implantable loop recorders for cryptogenic stroke workups, while primary care networks in the Netherlands deploy single-lead wearables for population-scale atrial fibrillation screening. This technological divergence is compressing the middle tier of traditional Holter monitoring services.
REACH and RoHS substance restrictions are tightening material specifications for implantable cardiac device housings and electrode coatings. The European Chemicals Agency's expanded candidate list is forcing manufacturers to reformulate polymer biocompatibility profiles and revalidate long-term implant safety data. French and German notified bodies are prioritizing technical documentation reviews for devices demonstrating early compliance with these evolving substance restrictions.
Hospital procurement committees are unbundling device acquisition from long-term monitoring service contracts. Nordic healthcare regions are piloting per-patient-per-month pricing for remote cardiac monitoring, displacing capital expenditure models that dominated the 2010s. This purchasing evolution is most visible in Sweden's regional health authorities, where cloud telemetry platforms compete on total cost of ownership rather than hardware specifications alone.
Europe Cardiac Monitoring Market Segmentation
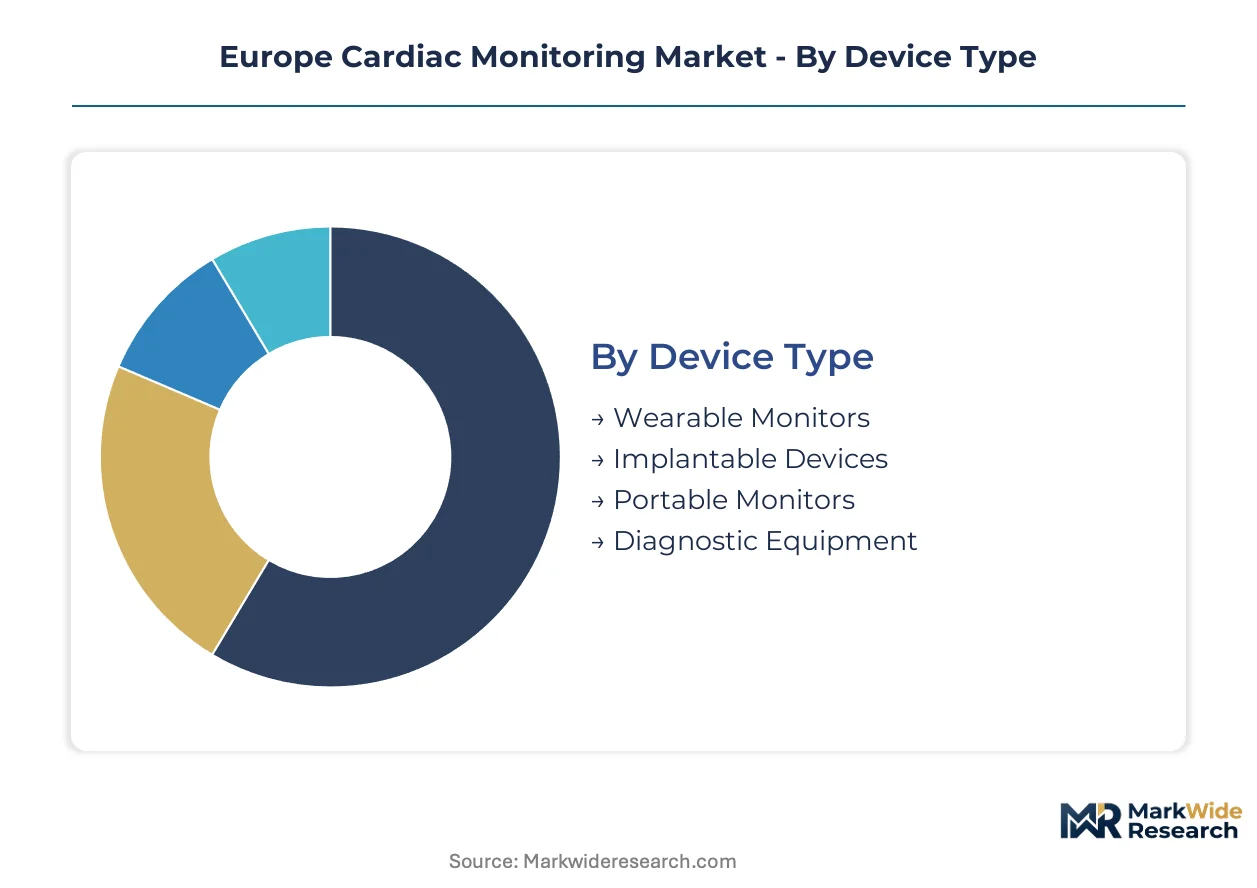
Cardiac monitoring technology fragments across hardware tiers, care settings, and diagnostic methodologies that compete for overlapping clinical indications. Substitution pressure between implantable precision and wearable convenience reshapes how manufacturers allocate R&D investment across the European regulatory landscape.
Device Type:
Wearable monitors face intensifying substitution pressure from algorithm-enhanced alternatives, while implantable devices defend their position through extended monitoring duration and diagnostic yield superiority.
- Implantable Devices:Miniaturized loop recorders and insertable cardiac monitors capture continuous electrophysiological data over multi-year periods. German university hospitals prioritize these devices for cryptogenic stroke workups where external monitoring fails to detect intermittent arrhythmias.
- Wearable Monitors:Patch-based ECG systems and wrist-worn devices leverage AI-enabled atrial fibrillation detection algorithms. Primary care networks in the Netherlands deploy single-lead wearables for population-scale screening programs that displace traditional Holter services.
- Portable Monitors:Handheld ECG devices enable point-of-care diagnostics in ambulatory settings across Spanish and Italian clinics.
- Diagnostic Equipment:Stationary systems for hospital telemetry stations concentrate in French and German cardiac catheterization laboratories.
Implantable devices anchor the volume base while wearable monitors gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital procurement from subscription-based home care models that bypass traditional infrastructure.
- Hospitals:Acute care facilities in Germany and France deploy centralized telemetry platforms enabling real-time arrhythmia detection across distributed wards. Cloud-based integration with electronic health records drives procurement decisions.
- Home Care:Patch-based monitors and smartphone-connected ECG devices serve aging populations in Nordic regions. Sweden's regional health authorities pilot per-patient-per-month pricing that displaces capital expenditure models.
- Clinics:Outpatient cardiology practices in Italy and Spain adopt portable monitors for same-day diagnostic workflows.
- Telehealth Services:Video consultation platforms in the Netherlands integrate cardiac telemetry for remote patient management programs.
Hospitals retain the largest installed base while home care demonstrates the steepest expansion trajectory.
Technology:
Application maturity divides established ECG modalities from emerging remote monitoring architectures that reconfigure care delivery geography.
- ECG:Multi-lead acquisition systems operating at sampling rates exceeding 250 Hz remain the diagnostic standard. French hospital networks maintain substantial investments in high-fidelity electrocardiography infrastructure.
- Remote Monitoring:Wireless transmission to centralized telemetry stations enables distributed arrhythmia surveillance. Germany's Federal Institute for Drugs and Medical Devices has streamlined vigilance reporting pathways for connected devices.
- Holter Monitoring:Traditional 24-48 hour ambulatory ECG services face compression from extended-wear patch alternatives.
- Electrophysiological Mapping:Three-dimensional cardiac mapping systems concentrate in specialized German and French electrophysiology centers.
ECG technology anchors current revenue while remote monitoring climbs the fastest.
Application:
Margin concentration follows diagnostic yield differentiation, with acute indications commanding premium pricing against preventive screening volumes.
- Arrhythmia Management:Atrial fibrillation detection and stroke prevention programs drive substantial device utilization. Algorithm sophistication in wearable platforms now achieves diagnostic parity with traditional monitoring for paroxysmal arrhythmia identification.
- Heart Failure Monitoring:Implantable hemodynamic sensors and pulmonary artery pressure monitors enable proactive therapeutic adjustment. German heart failure networks prioritize remote monitoring to reduce hospitalization frequency.
- Post-Operative Care:Telemetry surveillance following cardiac surgery concentrates in French and German tertiary centers.
- Preventive Care:Population-scale screening initiatives in the Netherlands and Sweden deploy low-cost wearables for asymptomatic atrial fibrillation detection.
Arrhythmia management anchors procedure volumes while heart failure monitoring expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium implantable device pricing in Germany exceeds comparable wearable monitor tariffs in Spain by substantial margins, reflecting divergent reimbursement frameworks and clinical evidence requirements across Western European healthcare systems.
Germany
University hospitals in Berlin and Munich drive demand for high-fidelity implantable loop recorders in cryptogenic stroke workups. The Federal Institute for Drugs and Medical Devices enforces stringent vigilance reporting for connected cardiac devices. The Baden-Württemberg medical technology cluster around Stuttgart hosts manufacturing facilities serving pan-European distribution networks.
France
Parisian cardiac catheterization laboratories anchor procurement volumes for stationary telemetry systems. ANSM has streamlined regulatory pathways for ambulatory ECG deployments under the national remote monitoring acceleration program. The Lyon-Grenoble corridor concentrates electrophysiology research centers developing next-generation mapping technologies.
Netherlands
Primary care networks deploy single-lead wearables for population-scale atrial fibrillation screening programs. The Dutch Healthcare Authority maintains distinct reimbursement codes for preventive versus diagnostic cardiac monitoring. The Eindhoven-Utrecht health technology corridor incubates algorithm-driven diagnostic platform startups.
Sweden
Regional health authorities pilot per-patient-per-month pricing models for cloud telemetry platforms serving aging rural populations. The Medical Products Agency aligns vigilance requirements with MDR post-market surveillance obligations. Stockholm's digital health cluster leads Nordic integration of cardiac telemetry with telemedicine consultation platforms.
Italy
Outpatient cardiology practices in Lombardy and Emilia-Romagna adopt portable monitors for same-day diagnostic workflows. The Italian Medicines Agency enforces CE marking documentation reviews that extend market access timelines for novel wearables. The Milan-Turin medical device corridor specializes in compact ECG hardware for clinic-based deployment.
Europe Cardiac Monitoring Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates commanding manufacturing scale across European production facilities. The vendor base stratifies across three tiers: implantable device specialists with deep electrophysiology expertise, diagnostic equipment manufacturers leveraging hospital procurement relationships, and algorithm-driven platform companies capturing ambulatory market share through software differentiation. Dominant competitive moves include strategic partnerships between hardware manufacturers and cloud infrastructure providers, plus portfolio diversification into adjacent remote patient monitoring verticals.
Within the implantable device tier, Medtronic and Boston Scientific Corporation exemplify manufacturing scale advantages, while Abbott Laboratories anchors the diagnostic equipment archetype through specialized cardiology portfolio positioning. iRhythm Technologies occupies a distinct position among algorithm-centric platform companies competing on AI-enabled diagnostic yield. These three entities collectively represent the competitive tension between hardware-integrated precision and software-driven accessibility reshaping European cardiac monitoring procurement patterns.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Biotronik SE & Co KG |
| Hill-Rom Holdings |
| Schiller AG |
| iRhythm Technologies |
| Others |
Supply & Pricing Matrix
CE marking administered by notified bodies across member states gates both supplier qualification and price differentiation simultaneously. Germany's Federal Institute for Drugs and Medical Devices and France's ANSM enforce documentation thresholds that compress margins for non-compliant manufacturers while enabling premium positioning for early MDR adopters.
Pricing Analysis
Customization-premium spreads separate configured-to-order implantable loop recorders from standard wearable monitors. The dominant pricing structure runs through tiered premium-standard-economy levels across device categories, with price differentiation hinging on CE marking tier and after-sales service bundling. Cost compression in the wearable segment is intensifying because algorithm commoditization erodes software-based premiums. Hospital procurement committees exhibit the least price sensitivity, while primary care networks in Southern Europe demonstrate acute cost consciousness.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for the MEMS-based ECG electrodes and wireless transmission modules that cardiac monitors require. The European supply chain draws from East Asian semiconductor foundries for sensor components, polymer biocompatibility formulations from German chemical suppliers, and final assembly across the Baden-Württemberg medical technology cluster. Single-source vulnerability concentrates in advanced MEMS electrode production. Distribution runs through pan-European hospital procurement networks and regional health authority tenders in the Nordics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among German hospital procurement committees into centralized GPO structures has shifted buyer power decisively toward volume aggregators. This fragmentation among purchasers compresses pricing flexibility for device manufacturers.
For Market Incumbents: Fortify cloud telemetry platform integration with entrenched electronic health record systems to raise switching costs for hospital networks. Deepen backward integration into AI-enabled diagnostic algorithm development to defend against software-centric challengers eroding the ambulatory monitoring tier.
For New Entrants and Emerging Players: Lead with patch-based ECG monitors targeting Spain and Italy's underpenetrated outpatient cardiology practices. The most penetrable segment sits in same-day diagnostic workflows at Italian clinics, accessed through distributor partnerships with established medical device wholesalers.
For Investors and Strategic Acquirers: EU AI Act high-risk medical device compliance reshapes the acquisition landscape toward algorithm-driven diagnostic platforms with early regulatory alignment. Long-term viability centers on software-integrated hardware models capable of subscription revenue conversion. The signal to monitor is ANSM vigilance pathway streamlining velocity for connected device categories.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation investment accelerates notified body review cycles for novel wearables. |
| Hospital System Partnership | Cloud telemetry integration with French and German EHR systems locks in multi-year service contracts. |
| Software Companion Development | AI-enabled atrial fibrillation algorithms achieve diagnostic parity with traditional Holter monitoring. |
| Reimbursement Strategy | Distinct coding for implantable versus external monitors in Germany shapes cross-category positioning. |
| Geographic Expansion | Per-patient-per-month pricing pilots in Sweden's regional health authorities displace capital expenditure models. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hospital procurement databases, and GPO contract disclosures. Electrophysiologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers provided operational perspective. Secondary validation drew from EMA device registrations, BfArM vigilance reports, ANSM market surveillance data, and CMS Medicare reimbursement schedules. Bottom-up demand modeling and top-down supply-side triangulation anchored volume estimates.
Segmentation dimensions modeled span device type, end user category, technology modality, and clinical application across the projection horizon. CAGRs derive from installed base expansion rates, replacement cycles, and pricing trajectory assumptions. Forecast inputs incorporate MDR implementation timelines, AI Act compliance milestones, and regional reimbursement code evolution.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or semiconductor supply stability would require recalibration. Forecasts reflect documented assumptions about cloud telemetry adoption curves and algorithm diagnostic yield progression. Recalibration cycles align with material shifts in notified body capacity, reimbursement framework updates, or supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Global Stethoscope Market