
 Arrhythmia Market | 2026-2036
Arrhythmia Market Size, Share, and Industry Trends Forecast 2026-2036
Arrhythmia Market Analysis
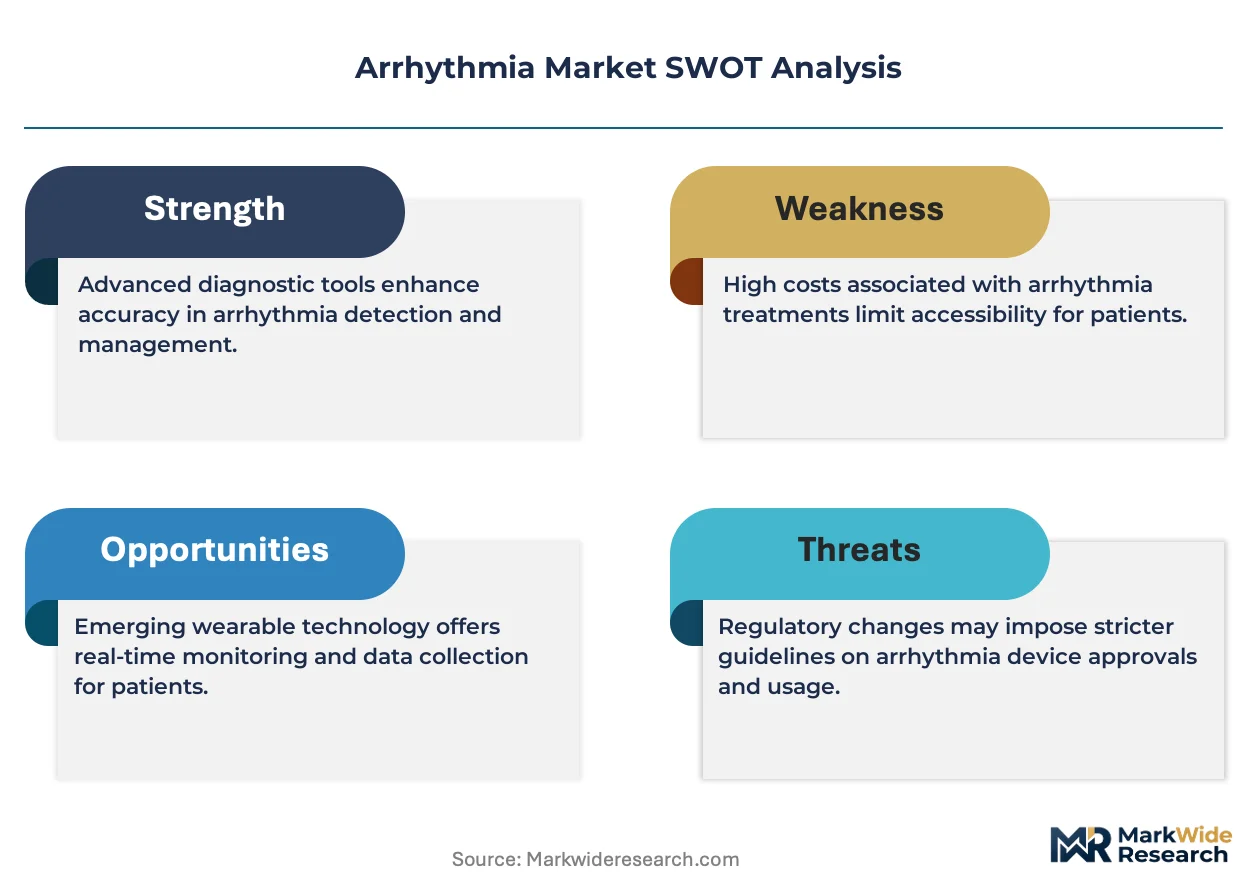
A shortage of board-certified electrophysiologists is collapsing procedural throughput at tertiary cardiac centers across multiple geographies. Medtronic leverages its integrated catheter and mapping ecosystem to capture recurring revenue from complex ablation workflows. Abbott Laboratories anchors its position through diversified pacing and monitoring portfolios that span inpatient and ambulatory settings. Boston Scientific competes aggressively in left atrial appendage closure and cryoablation platforms where hospital procurement committees prioritize clinical outcome data.
Arrhythmia encompasses disorders of cardiac electrical conduction characterized by abnormal heart rate, rhythm, or impulse propagation, diagnosed through surface electrocardiography, invasive electrophysiological study, or implantable loop recorders measuring activation sequences with millisecond precision. Pacemakers and defibrillators command the largest installed base of active implantable devices, generating sustained aftermarket revenue from battery replacements and remote monitoring subscriptions. Catheter-based ablation for atrial fibrillation represents the fastest-expanding procedural segment as cryoballoon and radiofrequency technologies displace long-term pharmaceutical management in symptomatic patients. Hospital end users concentrate capital investment in dedicated electrophysiology suites while ambulatory surgical centers capture lower-acuity diagnostic and device interrogation volumes.
FDA premarket approval requirements and the EU MDR framework impose substantial clinical evidence burdens on novel catheter and device submissions, extending development timelines but elevating barriers against undifferentiated entrants. The national pharmaceutical regulators in Japan and China enforce separate quality management system inspections that fragment certification pathways for multinational manufacturers. Stakeholders must monitor reimbursement decisions by CMS and Germany's Federal Joint Committee, as these determinations directly shape hospital willingness to adopt premium mapping technologies over conventional approaches.
Market Dynamics
Catheter-based ablation volumes are straining electrophysiology lab capacity at tertiary cardiac centers, forcing hospital systems to prioritize capital deployment toward integrated mapping platforms that compress procedure times and reduce fluoroscopy exposure.
Growth Catalysts
- EU MDR framework:The updated medical device regulation accelerates CE marking pathways for breakthrough cardiac monitors, enabling faster commercialization of next-generation implantable loop recorders across European markets.
- Ambulatory surgical centers:These facilities capture lower-acuity diagnostic and device interrogation volumes, diverting throughput from congested hospital electrophysiology suites and expanding accessible care points.
- Cryoballoon technology:Single-shot pulmonary vein isolation is displacing long-term pharmaceutical management in symptomatic atrial fibrillation patients, driving procedural volume expansion.
Market Restraints
- Platinum-iridium electrode costs:Raw material price volatility for catheter electrode alloys compresses gross margins on disposable ablation devices.
- Electrophysiologist concentration:Board-certified specialists cluster in United States, Germany, and Japan metropolitan corridors, leaving secondary markets underserved.
- FDA premarket approval timelines:Substantial clinical evidence requirements for novel catheter submissions extend development cycles by 18-36 months versus historical benchmarks.
Strategic Opportunities
- Remote monitoring subscriptions:Pacemaker and defibrillator manufacturers can capture recurring revenue streams through cloud-based transmission infrastructure and automated alert triage.
- India's cardiac device market:Underpenetrated implantable cardioverter-defibrillator penetration relative to epidemiological burden creates whitespace for volume-tier pricing strategies.
- Artificial intelligence integration:Machine learning algorithms applied to intracardiac electrogram analysis enable automated arrhythmia classification and procedural guidance assistance.
Industry Challenges
- Electrophysiology fellowship pipeline:Training program expansion lags procedural demand growth, constraining throughput at high-volume ablation centers.
- Legacy device interoperability:Hospital information systems struggle to integrate data streams from multigenerational pacemaker platforms with proprietary communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arrhythmia Market |
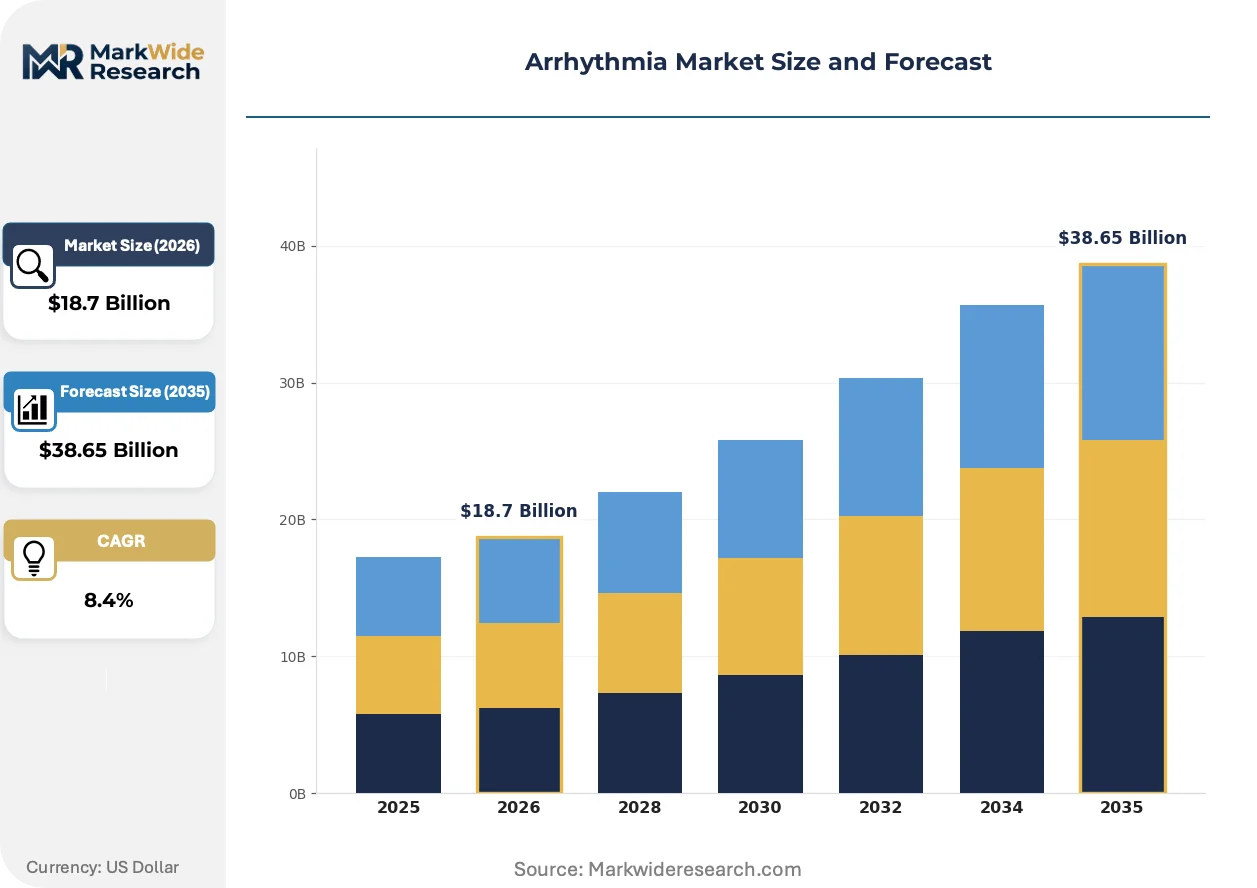
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Monitors, Catheters, Pacemakers, Defibrillators Therapy Area: Atrial Fibrillation, Ventricular Tachycardia, Bradycardia, Supraventricular Tachycardia End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific, GE Healthcare, Koninklijke Philips, Biotronik, Johnson & Johnson, iRhythm Technologies, AtriCure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arrhythmia Market Emerging Trajectories
Digital signal processing and wireless power transfer are converging to redefine form-factor constraints and patient compliance models across implantable cardiac rhythm management devices.
Leadless pacemaker technology is miniaturizing. These self-contained devices eliminate transvenous leads and their associated extraction risks. Electrophysiologists at high-volume United States centers are implanting leadless units in anticoagulated patients and those with prior device infections. The technology is miniaturizing procedural complexity and expanding candidacy to patients previously excluded from conventional systems.
Japan's PMDA has streamlined quality management system inspections for cardiac rhythm devices manufactured under ISO 13485 certification. This regulatory convergence reduces duplicate audit burdens for multinational manufacturers. Device sponsors with existing FDA approvals now achieve Japanese market entry 8-14 months faster than under legacy parallel review pathways.
Hospital procurement committees are consolidating vendor relationships around electrophysiology ecosystem providers. Mapping system, catheter, and remote monitoring bundling displaces point-product purchasing. Germany's Federal Joint Committee reimbursement stability for integrated ablation workflows accelerates this concentration at university hospitals and cardiac specialty networks.
Arrhythmia Market Segmentation
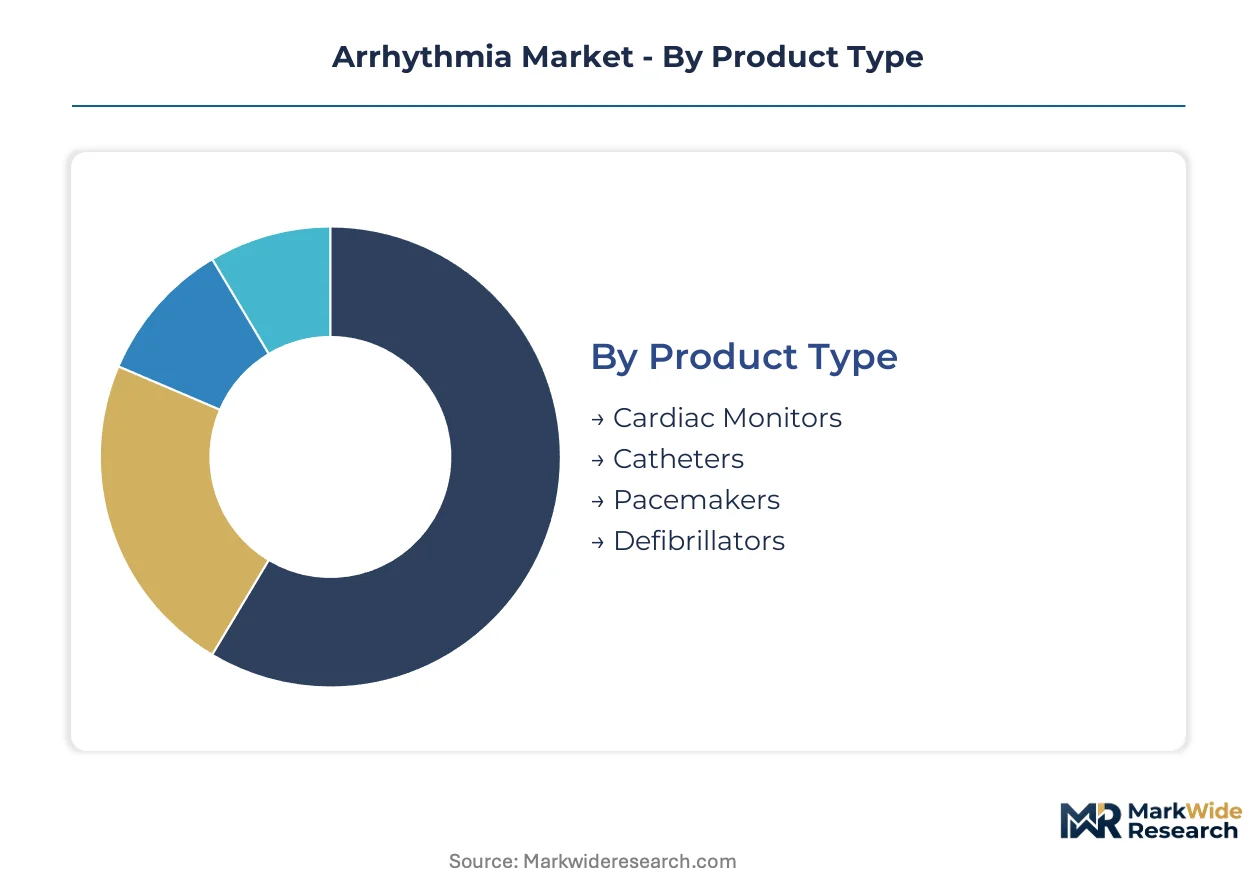
Arrhythmia treatment pathways diverge sharply across patient acuity, reimbursement structures, and procedural venue economics. Segmentation reveals how capital-intensive electrophysiology suites compete with distributed care models for diagnostic and therapeutic volumes.
Product Type:
FDA premarket approval timelines and EU MDR conformity assessments create divergent commercialization speeds across implantable versus disposable device categories.
- Cardiac Monitors:Implantable loop recorders and wearable patch electrodes capture subclinical arrhythmia episodes with extended monitoring windows. Demand concentrates in ambulatory settings across Germany and Japan where remote monitoring reimbursement codes incentivize long-term surveillance.
- Catheters:Radiofrequency and cryoballoon ablation catheters deliver targeted thermal energy to arrhythmogenic substrates. Tertiary cardiac centers in the United States prioritize single-shot pulmonary vein isolation platforms that compress procedure times and reduce fluoroscopy exposure.
- Pacemakers:Transvenous and leadless pacing systems restore chronotropic competence in bradycardia patients. Battery replacement cycles and remote monitoring subscriptions generate sustained aftermarket revenue streams for active device fleets.
- Defibrillators:Subcutaneous and transvenous implantable cardioverter-defibrillators terminate malignant ventricular arrhythmias through tiered antitachycardia pacing and high-energy shocks.
Established volume favors pacemakers; emerging adoption favors cardiac monitors.
Therapy Area:
Procedural complexity and recurrence risk stratify investment returns across arrhythmia phenotypes.
- Atrial Fibrillation:The most prevalent sustained arrhythmia drives catheter ablation volume expansion as cryoballoon technology displaces antiarrhythmic drug regimens in symptomatic patients. United States electrophysiology labs report capacity constraints from rising pulmonary vein isolation caseloads.
- Ventricular Tachycardia:Substrate mapping and ablation for scar-related arrhythmias demands advanced three-dimensional electroanatomic systems. Germany's university hospitals concentrate complex ischemic VT procedures requiring hemodynamic support.
- Bradycardia:Sinoatrial and atrioventricular conduction disorders sustain pacemaker implantation volumes through aging demographics.
- Supraventricular Tachycardia:Accessory pathway and atrioventricular nodal reentrant tachycardias yield high acute success rates with curative catheter ablation.
Atrial fibrillation commands capital deployment; ventricular tachycardia commands technical specialization.
End User:
Site-of-care economics and reimbursement differentials redistribute procedural volumes across facility types.
- Hospitals:Dedicated electrophysiology suites at tertiary cardiac centers handle complex ablation, device implantation, and extraction procedures. Japan's metropolitan hospital networks maintain the highest per-capita electrophysiologist density.
- Clinics:Device interrogation, programming, and follow-up visits migrate to cardiology office settings with integrated remote monitoring infrastructure.
- Home Care:Wearable monitors and patient-activated event recorders extend diagnostic capture beyond clinical encounters.
- Ambulatory Surgical Centers:Lower-acuity pacemaker implants and generator replacements exploit favorable site-of-service payment differentials in the United States.
Hospitals retain complex procedures; ambulatory surgical centers capture standardized implants.
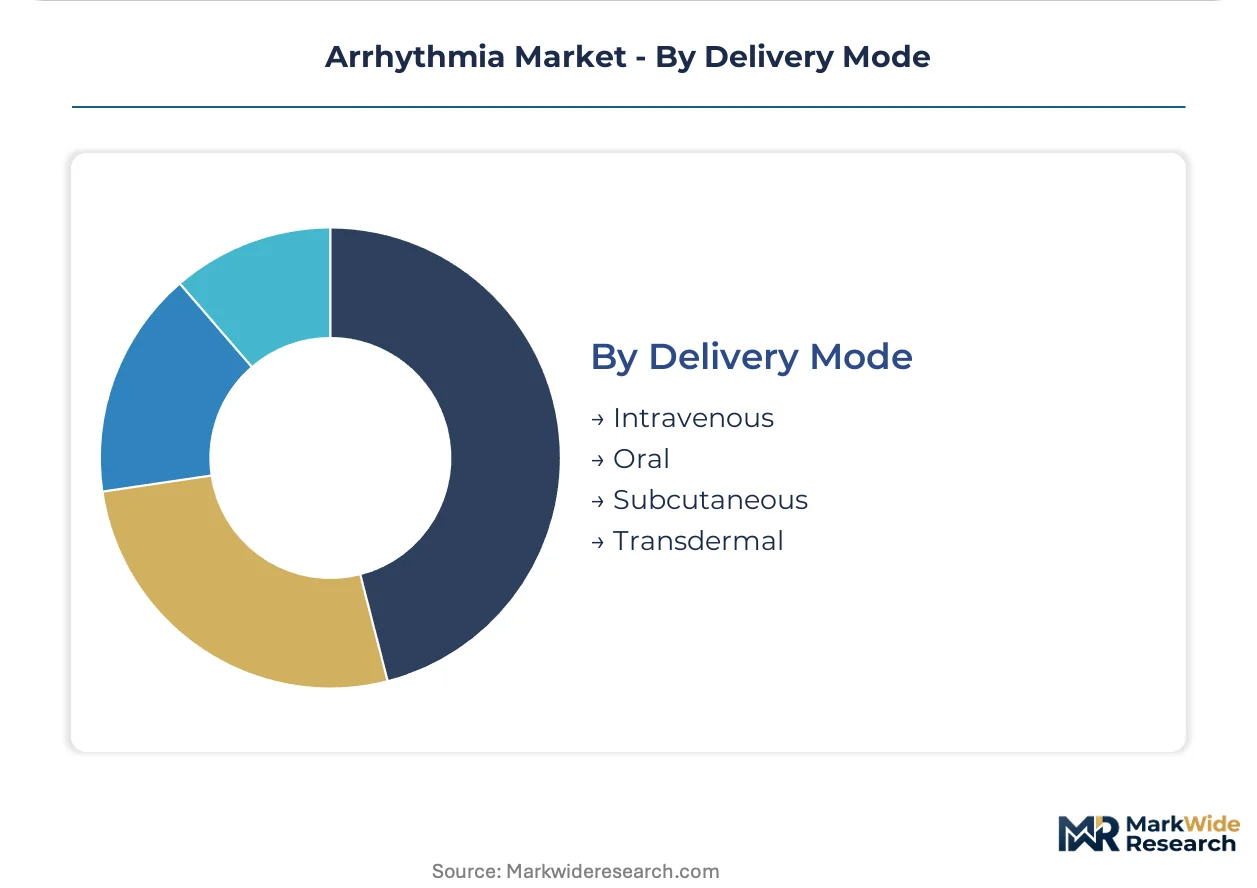
Delivery Mode:
Pharmacokinetic profiles and administration convenience determine adherence patterns in rhythm control strategies.
- Intravenous:Acute rate and rhythm control agents administered in monitored settings for hemodynamically unstable presentations.
- Oral:Chronic antiarrhythmic drug therapy faces adherence challenges and proarrhythmic risk profiles that drive catheter ablation candidacy.
- Subcutaneous:Anticoagulation for stroke prevention in atrial fibrillation uses subcutaneous direct oral anticoagulant alternatives.
- Transdermal:Patch-based drug delivery remains investigational for antiarrhythmic agents with narrow therapeutic indices.
Oral administration dominates chronic management; intravenous delivery anchors acute stabilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket pathways anchor procedural volume concentration in the United States, while Japan's PMDA streamlining and Germany's Federal Joint Committee reimbursement stability create parallel demand centers for advanced electrophysiology technologies.
United States
Tertiary cardiac centers in Cleveland Clinic and Mayo Clinic networks report electrophysiology lab capacity constraints from rising atrial fibrillation ablation volumes. CMS reimbursement codes for remote monitoring incentivize hospital investment in cloud-based device surveillance infrastructure. The Boston-Cambridge corridor concentrates wearable cardiac monitor development, with Massachusetts General Hospital piloting AI-integrated electrogram analysis platforms.
Germany
University hospital networks in Munich and Heidelberg maintain Europe's highest per-capita electrophysiologist density, supporting complex ventricular tachycardia substrate mapping procedures. The Federal Joint Committee's reimbursement stability for integrated ablation workflows accelerates capital deployment toward three-dimensional electroanatomic mapping systems. Baden-Württemberg's medical device manufacturing cluster supplies catheter electrode alloys to global disposable device producers.
Japan
Metropolitan hospital networks in Tokyo and Osaka achieve 8-14 month faster market entry for cardiac rhythm devices manufactured under ISO 13485 certification through streamlined PMDA quality management system inspections. Aging demographics drive pacemaker and defibrillator implantation volumes at rates exceeding population-adjusted benchmarks. The Kansai region concentrates domestic electrophysiology catheter production for Asia-Pacific distribution.
India
Underpenetrated implantable cardioverter-defibrillator penetration relative to ischemic heart disease burden creates volume-tier pricing opportunities for multinational manufacturers. CDSCO quality management system inspections enforce separate certification pathways that fragment market entry timelines. Maharashtra's Mumbai-Pune corridor anchors private hospital chain expansion of dedicated electrophysiology suites for medical tourism and domestic affluent patients.
China
NMPA medical device registration requirements impose extended clinical evidence burdens on novel catheter submissions, elevating barriers against undifferentiated market entrants. Provincial hospital networks in Beijing and Shanghai concentrate complex ablation procedural capacity amid national electrophysiologist training program expansion. The Yangtze River Delta medical device manufacturing base supplies domestic and export markets with pacemaker generator components.
Arrhythmia Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the arrhythmia device ecosystem. The upper tier commands bundled purchasing relationships across mapping systems, ablation catheters, and remote monitoring platforms. Three archetypes dominate: diversified medical technology conglomerates with cardiovascular divisions, pure-play electrophysiology specialists, and diagnostic monitoring-focused innovators. Competitive moves concentrate on ecosystem bundling to displace point-product purchasing and regulatory pathway optimization to compress market entry timelines.
Within the integrated conglomerate tier, Medtronic and Abbott Laboratories exemplify platform-scale positioning across implantable and interventional cardiac rhythm management. Boston Scientific occupies a specialist-to-integrated transition position through concentrated left atrial appendage closure and cryoablation platform development. Among diagnostic-focused innovators, iRhythm Technologies represents the wearable cardiac monitor archetype with cloud-native infrastructure for ambulatory arrhythmia detection.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| GE Healthcare |
| Koninklijke Philips |
| Biotronik |
| Johnson & Johnson |
| iRhythm Technologies |
| AtriCure |
| Others |
Supply Flow & Price Mechanics
Electrophysiology lab capacity utilization above 85 percent at tertiary United States cardiac centers concentrates purchasing power among hospital systems capable of multi-year mapping ecosystem contracts. This scale dynamic compresses price floors for disposable ablation catheters while elevating premiums for integrated platform vendors that bundle hardware, software, and remote monitoring subscriptions.
Pricing Analysis
United States procurement committees negotiate 15-25 percent lower unit costs on cryoballoon catheters compared to German university hospitals due to consolidated GPO purchasing volume. Three-tier pricing structure across premium mapping-integrated, standard diagnostic, and economy bare-metal electrode levels differentiates vendors by fluoroscopy reduction claims and procedural throughput guarantees. Cost compression in economy catheter tiers is intensifying because Chinese manufacturers are achieving CE marking under MDR accelerated pathways. Ambulatory surgical centers exhibit highest price sensitivity due to fixed site-of-service reimbursement ceilings, while Japanese metropolitan hospitals prioritize outcome-linked contracts over unit pricing.
Supply Chain Analysis
Platinum-iridium electrode alloy supply from South African mining concentrates and German precision metalworking districts creates single-source vulnerability for radiofrequency ablation catheter producers. Raw material dependencies span platinum-group metals from South Africa, catheter shaft polymers from Germany and Japan, and semiconductor components for mapping systems from Taiwan and South Korea. Tariff exposure on Chinese-sourced pacemaker generator housings is forcing inventory pre-positioning at regional distribution hubs. Distribution runs through hospital GPO contracts in the United States, direct tender awards in Germany, and specialized cardiac device distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrophysiologist training bottlenecks fragment service capacity across geographies, creating whitespace for differentiated clinical support models and regional partnership structures that incumbent platform vendors under-serve.
For Market Incumbents: Consolidate around electrophysiology ecosystem bundling to defend against point-product competitors winning catheter-only tenders. Acquire remote monitoring infrastructure capabilities to capture recurring revenue streams that offset disposable margin compression. Prioritize backward integration into platinum-iridium electrode supply to secure raw material cost stability against South African mining volatility. For New Entrants and Emerging Players: AI-integrated electrogram analysis services represent a service-layer gap where mapping platform incumbents under-serve mid-tier hospital systems lacking in-house signal processing expertise. Target India's underpenetrated ICD market with volume-tier pricing and localized clinical training partnerships. Pursue regulatory pathway optimization through PMDA streamlined quality management system inspections to achieve Japanese market entry ahead of conventional timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic monitoring innovators with cloud-native infrastructure over capital-intensive hardware platform vendors facing replacement cycle elongation. Long-term viability hinges on recurring revenue model transition and software-enabled service attachment. Watch electrophysiology fellowship program expansion rates as the inflection indicator for procedural throughput constraints easing or tightening.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | EU MDR breakthrough device designation accelerates next-generation cardiac monitor commercialization across European markets. |
| Hospital System Partnership | Multi-year electrophysiology suite contracts with Cleveland Clinic and Mayo Clinic networks lock out competitor mapping platforms. |
| Software Companion Development | AI-integrated electrogram analysis platforms enable automated arrhythmia classification at Massachusetts General Hospital pilot sites. |
| Reimbursement Strategy | CMS remote monitoring code alignment incentivizes cloud-based pacemaker surveillance infrastructure investment. |
| FDA Submission Acceleration | Premarket approval timeline compression for leadless pacemaker indications expands anticoagulated patient candidacy. |
Methodological Framework
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary fieldwork encompassed structured interviews with clinicians at tertiary cardiac centers in the United States, Germany, and Japan alongside procurement leads at integrated delivery networks. Secondary sources included FDA premarket approval filings, EU MDR conformity assessment databases, CMS reimbursement code determinations, and hospital capital expenditure disclosures. Bottom-up procedure volume modeling and top-down device shipment triangulation anchored market size estimation.
Variance decomposition across product type, therapy area, end user, and delivery mode segmentation dimensions enabled identification of growth contribution by category. CAGRs were derived from logistic diffusion curves fitted to historical implantation and ablation volumes, adjusted for electrophysiologist supply constraints and regulatory pathway timelines. Forecast inputs incorporated aging demographic projections, reimbursement stability indices, and catheter technology substitution rates for atrial fibrillation management.
Underlying assumptions cover electrophysiologist training pipeline expansion, platinum-iridium price stability, and MDR/CE marking pathway continuity, with deviation risk concentrated in regulatory inspection backlogs and raw material supply disruptions. Practitioners should keep alternative scenarios live as FDA premarket approval timelines and EU MDR notified body capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market