
 Smart Electronic Stethoscopes Market | 2026-2036
Smart Electronic Stethoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Electronic Stethoscopes Market Insights
The R&D-to-manufacturing capability gap between established health technology conglomerates and emerging digital diagnostics specialists is unwinding competitive hierarchies in this sector. 3M Health Care leverages its entrenched hospital supply chain relationships to sustain institutional market presence across North American cardiology departments. Eko Health, Inc. differentiates through machine learning algorithm development, positioning its software-integrated hardware as a clinical decision-support platform rather than commodity listening equipment. Thinklabs Medical LLC anchors its competitive stance on audiophile-grade acoustic engineering, occupying a premium niche among pediatric specialists who demand exceptional signal fidelity.
Smart electronic stethoscopes integrate amplified acoustic sensors with digital signal processing, wireless transmission protocols, and embedded analytical software to capture, filter, store, and share cardiopulmonary sounds at frequencies extending beyond traditional auscultation range. These instruments serve primary diagnostic and remote monitoring functions across clinical settings where real-time or asynchronous specialist consultation proves essential. Wireless stethoscopes command expanding share as telemedicine providers require untethered patient examination capabilities for remote cardiac and pulmonary assessment. Machine learning technology segments attract disproportionate R&D investment because algorithmic murmur detection and automated classification promise liability reduction and diagnostic standardization for general practitioners with limited cardiology training. Digital stethoscopes retain volume leadership in hospital emergency departments where immediate waveform visualization supports triage decisions.
The FDA governs smart electronic stethoscopes as Class II medical devices under 510(k) premarket notification pathways, with escalating scrutiny of software-as-medical-device claims for AI-enabled diagnostic features. The EU Medical Device Regulation imposes conformity assessment requirements through notified bodies, while the FDA's evolving guidance on artificial intelligence and machine learning in medical devices shapes product development roadmaps for manufacturers targeting dual-market approval. Stakeholders must monitor regulatory divergence between American and European software validation standards when allocating certification resources and predicting market access timelines.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around Bluetooth-enabled diagnostic platforms, compressing supplier diversity while elevating software-integrated hardware specifications in institutional tenders.
Growth Catalysts
- FDA 510(k) Pathway Evolution:Streamlined premarket notification for AI-augmented features accelerates clearance timelines for algorithm-enabled diagnostic tools.
- Telemedicine Infrastructure Expansion:Remote cardiac assessment protocols in United States integrated health systems drive wireless stethoscope deployment for asynchronous specialist consultation.
- Machine Learning Algorithm Maturation:Automated murmur detection capabilities reduce liability exposure for primary care physicians with limited cardiology specialization.
Market Restraints
- EU MDR Conformity Burden:Notified body assessment requirements for software-as-medical-device claims extend certification timelines and inflate compliance expenditure.
- Acoustic Sensor Supply Concentration:Precision MEMS microphone fabrication depends on concentrated Asian semiconductor foundry capacity.
- Signal Fidelity Cost Structure:Audiophile-grade analog-to-digital conversion components sustain premium pricing floors that exclude budget-constrained clinical settings.
Strategic Opportunities
- Pediatric Specialist Premium Segment:Exceptional frequency response requirements among neonatal cardiologists create defensible niche positioning for engineering-focused manufacturers.
- AI-Enabled Clinical Decision Support:Convergence of embedded edge computing with cloud-based algorithm training enables real-time diagnostic assistance at point-of-care.
- Direct-to-Consumer Channel Development:Remote patient monitoring reimbursement expansion opens subscription-based hardware-software bundles for chronic heart failure management.
Industry Challenges
- Interoperability Architecture Complexity:Integration with proprietary electronic health record systems demands customized HL7 FHIR implementation for each hospital network.
- Algorithm Validation Talent Scarcity:Clinical data science expertise combining cardiology domain knowledge with regulatory statistical methodology commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Electronic Stethoscopes Market |
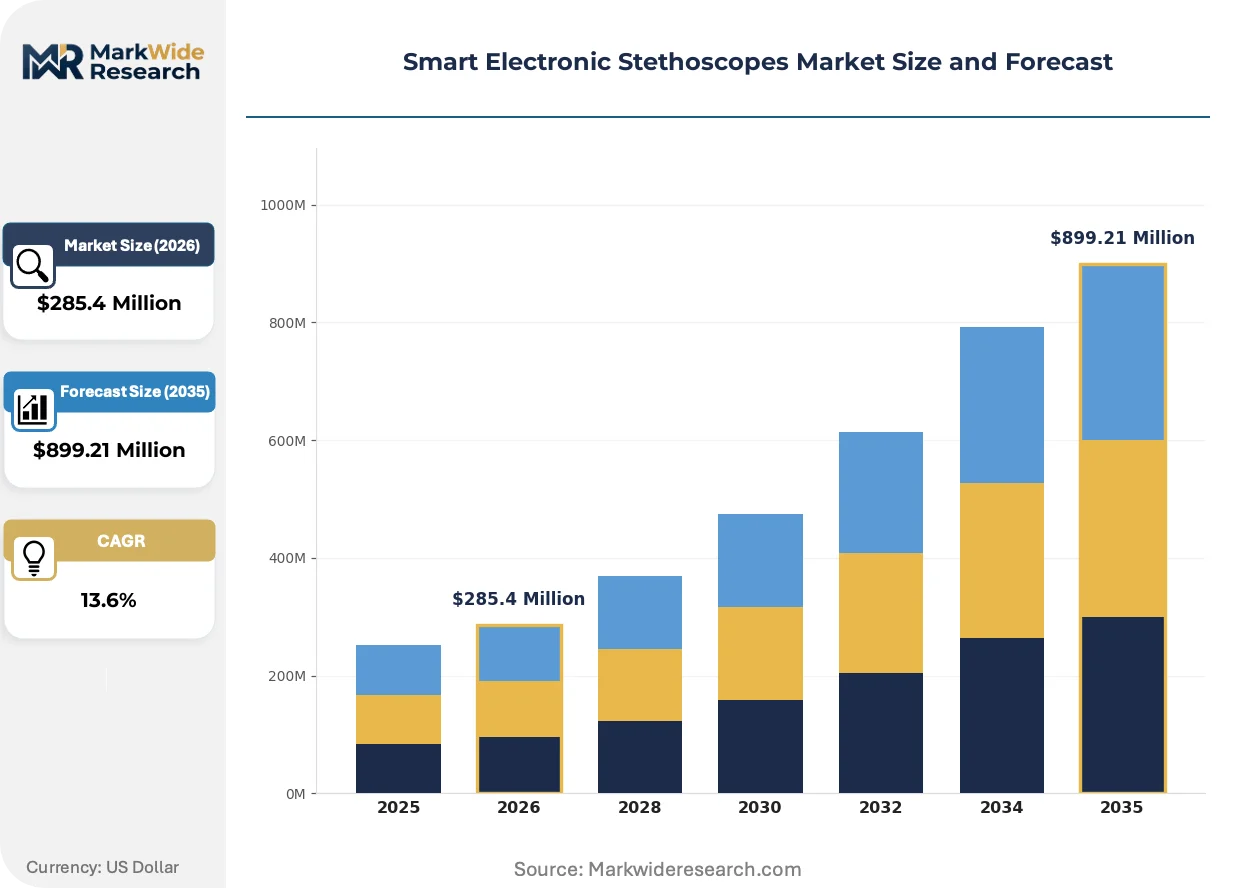
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $899.21 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Stethoscopes, Wireless Stethoscopes, Analog Stethoscopes, Electronic Earpieces End User: Clinics, Hospitals, Home Care, Telemedicine Providers Technology: Bluetooth, Wi-Fi, Noise Cancelling, Machine Learning Application: Cardiology, Pediatrics, General Practice, Emergency Care |
| Companies Covered | Solventum, Eko Health, Inc., Thinklabs Medical LLC, HD Medical, Inc., 3M Health Care, Welch Allyn, American Diagnostic Corporation, Cardionics, eKuore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Electronic Stethoscopes Market Trends and Innovations
Product architecture is separating into distinct performance tiers as clinical use cases diverge between emergency triage, remote monitoring, and specialist diagnostic precision.
Signal processing hardware is bifurcating between cost-optimized digital stethoscopes for high-volume emergency department deployment and premium acoustic engineering platforms serving pediatric cardiology specialists who demand extended frequency capture. Hospital procurement committees are segmenting tenders by clinical workflow rather than consolidating around single specifications. This technological stratification enables specialized vendors to defend margin positions without competing directly against conglomerate scale economies.
EU Medical Device Regulation software validation standards are diverging from FDA artificial intelligence guidance, forcing dual-market manufacturers to maintain parallel documentation systems and quality management procedures. The regulatory friction most acutely affects machine learning-enabled products where algorithm update protocols trigger re-certification requirements. European notified bodies are interpreting SaMD classification boundaries more conservatively than their American counterparts.
Institutional purchasing committees are unbundling hardware acquisition from software subscription licensing, reversing prior bundled procurement patterns. Cardiology department budgets now separate capital equipment from recurring algorithm access fees, shifting vendor revenue toward recurring streams. This financial restructuring is most advanced in United States integrated delivery networks with centralized supply chain governance.
Smart Electronic Stethoscopes Market Segmentation
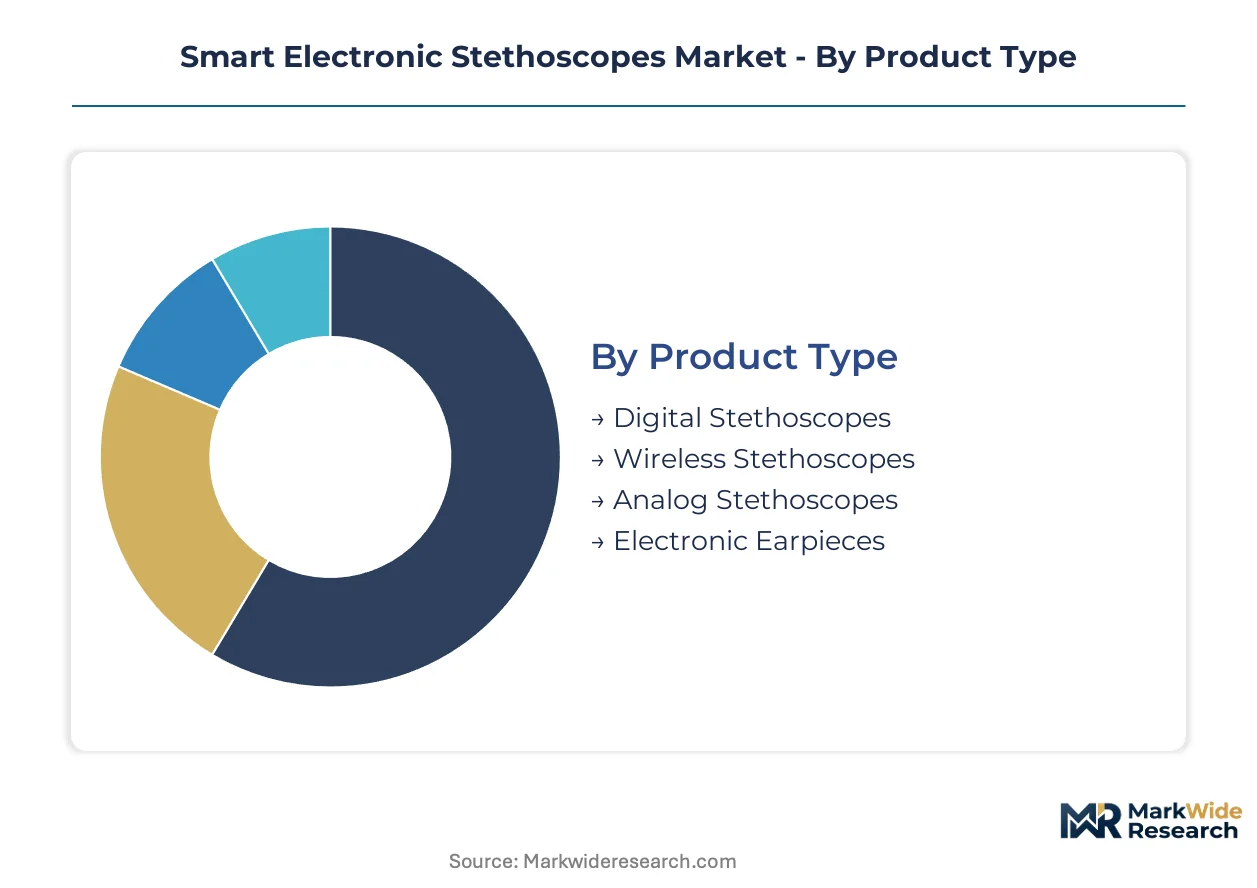
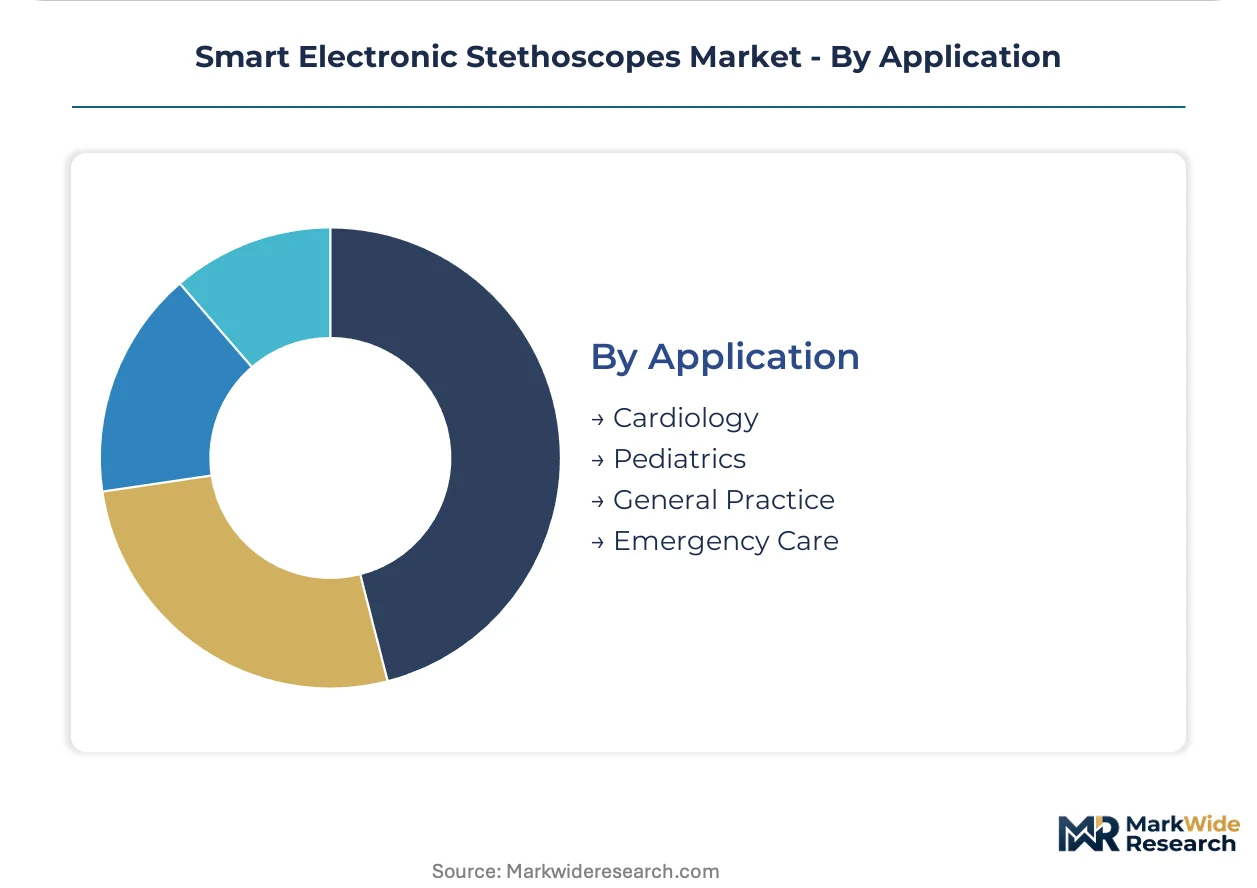
Smart electronic stethoscope segmentation reveals how clinical workflow divergence creates distinct performance tiers. Procurement committees now segment tenders by use case rather than consolidating specifications, enabling specialized vendors to defend margins without competing on conglomerate scale.
Product Type:
Wireless stethoscopes face intensifying substitution pressure from smartphone-connected peripherals, while analog legacy equipment confronts outright phase-out in institutional procurement.
- Digital Stethoscopes:Amplified acoustic sensors with integrated analog-to-digital conversion support immediate waveform visualization at triage stations. Hospital emergency departments in the United States concentrate procurement around these units for rapid cardiac assessment protocols.
- Wireless Stethoscopes:Bluetooth-enabled untethered examination capabilities serve telemedicine providers conducting remote cardiopulmonary assessment. United States integrated health systems prioritize these for asynchronous specialist consultation workflows where physical patient proximity is impractical.
- Analog Stethoscopes:Traditional acoustic designs persist in budget-constrained clinical settings and training environments.
- Electronic Earpieces:Modular listening attachments retrofit existing stethoscope bodies with digital amplification.
Digital stethoscopes retain volume leadership; wireless stethoscopes hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-rich institutional buyers from reimbursement-dependent outpatient operators.
- Hospitals:Centralized procurement committees negotiate bulk contracts for Bluetooth-integrated platforms with EHR connectivity. United States health system consolidation elevates software-integrated hardware specifications in institutional tenders.
- Telemedicine Providers:Asynchronous consultation platforms demand untethered patient examination capabilities for remote cardiac monitoring. Medicare reimbursement expansion for remote patient monitoring accelerates hardware deployment across United States virtual care networks.
- Clinics:Outpatient operators prioritize cost-optimized digital units for routine auscultation.
- Home Care:Chronic heart failure patients access subscription-based hardware-software bundles for self-monitoring.
Hospitals dominate absolute procurement volume; telemedicine providers are expanding most quickly.
Technology:
Application-specific requirements drive technology selection, with AI-augmented features commanding premium positioning.
- Machine Learning:Embedded algorithms enable automated murmur detection and classification, reducing diagnostic liability for primary care physicians with limited cardiology training. FDA 510(k) pathway evolution for AI-augmented features accelerates clearance timelines for algorithm-enabled tools.
- Bluetooth:Low-energy wireless protocols support untethered examination with minimal power consumption. Hospital procurement departments consolidate vendor relationships around these diagnostic platforms.
- Wi-Fi:Higher-bandwidth transmission enables real-time cloud-based algorithm processing.
- Noise Cancelling:Active acoustic filtering improves signal fidelity in high-ambient-noise clinical environments.
Bluetooth retains installation prevalence; machine learning claims the steepest R&D investment trajectory.
Application:
Frequency response requirements separate premium engineering tiers from cost-optimized emergency deployment.
- Cardiology:Extended frequency capture and waveform visualization support specialist diagnostic precision. United States cardiology departments prioritize connected workflows with EHR-integrated documentation.
- Pediatrics:Neonatal cardiologists demand exceptional signal fidelity across extended frequency ranges for murmur detection in low-amplitude cardiac signals. This creates defensible niche positioning for engineering-focused manufacturers.
- Emergency Care:Rapid triage decisions favor immediate waveform visualization over acoustic precision.
- General Practice:Algorithm-assisted classification reduces referral burden for non-specialist clinicians.
Cardiology commands premium pricing; pediatrics delivers the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement environments, with United States integrated health systems absorbing premium Bluetooth-integrated platforms while budget-constrained clinical settings in emerging economies prioritize cost-optimized digital units.
United States
Medicare reimbursement expansion for remote patient monitoring accelerates wireless stethoscope deployment across virtual care networks. FDA 510(k) pathway evolution for AI-augmented diagnostic features compresses clearance timelines for algorithm-enabled entrants. Boston and San Francisco metropolitan clusters concentrate digital health venture capital, driving machine learning algorithm development for clinical decision-support platforms.
Germany
Hospital procurement committees prioritize CE-marked diagnostic platforms with integrated EHR connectivity for cardiology department workflows. EU Medical Device Regulation conformity assessment through notified bodies extends certification timelines for software-as-medical-device claims. Baden-Württemberg industrial corridor hosts precision MEMS microphone fabrication facilities serving acoustic sensor supply chains.
China
Domestic telemedicine infrastructure expansion drives demand for smartphone-connected peripherals in tier-one city hospital networks. National Medical Products Administration governs smart electronic stethoscopes under Class II medical device registration pathways with escalating scrutiny of AI-enabled diagnostic features. Yangtze River Delta manufacturing clusters concentrate Bluetooth module assembly and analog-to-digital conversion component production.
Japan
Aging population demographics and rural healthcare access gaps propel remote cardiac assessment protocol adoption. Ministry of Economy, Trade and Industry promotes connected medical device standards harmonization with international frameworks. Kanto region Tokyo metropolitan area anchors digital health technology R&D investment for pediatric cardiology diagnostic precision.
India
Primary care physician liability reduction needs drive algorithm-assisted murmur detection adoption in outpatient clinic networks. Central Drugs Standard Control Organization regulates software-integrated hardware under medical device rules with evolving guidance on AI-enabled features. Karnataka state Bangalore technology corridor concentrates health technology startup development for cost-optimized diagnostic platforms.
Smart Electronic Stethoscopes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market structure. Conglomerate health technology divisions leverage entrenched hospital supply chain relationships to sustain institutional procurement presence. Digital diagnostics specialists differentiate through machine learning algorithm development and audiophile-grade acoustic engineering. Strategic moves concentrate on regulatory clearance acceleration and telemedicine platform partnership formation.
Within the integrated health technology tier, 3M Health Care and Welch Allyn exemplify scale-driven procurement consolidation strategies. Eko Health, Inc. occupies a position among machine learning algorithm developers targeting clinical decision-support positioning. Thinklabs Medical LLC represents engineering-focused specialists defending premium niche margins through exceptional signal fidelity capabilities.
| Leading Market Players |
|---|
| Solventum |
| Eko Health, Inc. |
| Thinklabs Medical LLC |
| HD Medical, Inc. |
| 3M Health Care |
| Welch Allyn |
| American Diagnostic Corporation |
| Cardionics |
| eKuore |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance tiers gate both component supplier qualification and end-product price positioning, compressing margin structures for uncertified Asian assembly houses while elevating premium capture for algorithm-validated manufacturers serving United States integrated health systems. This dual-gating mechanism concentrates pricing power among vendors with parallel American and European regulatory dossiers.
Pricing Analysis
Software subscription renewals and algorithm update contracts now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates AI-augmented clinical decision-support platforms from basic digital amplification units and legacy analog replacements. Pricing pressure stems from smartphone-connected peripheral substitution in telemedicine workflows. Budget-constrained outpatient clinics exhibit highest price sensitivity; neonatal cardiology departments demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of precision MEMS microphones and analog-to-digital conversion chips dominates inventory strategy as lead time volatility concentrates in Taiwanese semiconductor foundries. Component sourcing draws from China, South Korea, and Germany for Bluetooth modules, battery cells, and acoustic sensor substrates respectively. Single-source vulnerability sits with concentrated Asian MEMS fabrication capacity. Distribution runs through hospital GPO contracts and direct telemedicine platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA 510(k) algorithm validation protocols creates durable defensive moats, as switching costs for hospital procurement committees escalate with embedded EHR integration and clinician workflow retraining requirements.
For Market Incumbents: Compound hospital supply chain lock-in through backward integration into cloud-based algorithm training infrastructure, neutralizing emerging digital diagnostics specialists. Expand CE marking dossiers preemptively before EU MDR software validation standards diverge further from FDA guidance. Prioritize pediatric cardiology specialist retention through exceptional frequency response engineering. For New Entrants and Emerging Players: Algorithm-assisted murmur detection for primary care physicians in India's outpatient clinic networks represents the most penetrable white-space target, where liability reduction needs outpace incumbent coverage. Direct-to-consumer chronic heart failure monitoring subscriptions offer secondary entry path. Lead with reimbursement strategy expertise rather than hardware engineering. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across machine learning-enabled segments as edge computing commoditizes embedded processing. Five-to-ten year viability favors acquisition targets with validated clinical data sets and established FDA 510(k) clearance histories rather than hardware-only manufacturers. Watch for Medicare remote patient monitoring reimbursement expansion as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines for AI-augmented features compress competitive entry windows. |
| Hospital System Partnership | Integrated health system procurement consolidation elevates vendor relationship value. |
| Software Companion Development | Algorithm subscription revenue streams decouple from hardware replacement cycles. |
| CE Marking Pathway | EU MDR conformity assessment requirements extend certification timelines for dual-market manufacturers. |
| Reimbursement Strategy | Medicare remote patient monitoring expansion drives telemedicine provider hardware deployment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital procurement committees, biomedical engineers, telemedicine platform architects, and GPO contracts managers. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU notified body conformity assessment registers. Bottom-up unit economics triangulated against top-down health system expenditure patterns.
Across the analysis window, forecasts modeled product type segmentation by digital, wireless, and electronic earpiece architectures; technology tiers separating Bluetooth, machine learning, and noise cancelling implementations; and application workflows spanning cardiology, pediatrics, emergency care, and general practice. CAGRs derived from clinician adoption curve analysis and procurement committee tender volume trajectories. Algorithm validation timelines and reimbursement policy shifts served as key forecast inputs.
Underlying assumptions cover FDA 510(k) clearance velocity, EU MDR software validation stability, and MEMS microphone supply continuity, with deviation risk concentrated in regulatory divergence between American and European AI-enabled device standards. Revision becomes warranted when Medicare remote patient monitoring reimbursement thresholds cross expansion or contraction inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Global Cardiac Monitoring Market