
 Cardiac Catheterization Market | 2026-2036
Cardiac Catheterization Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Catheterization Market Intelligence
Manufacturing capacity expansion in China is tilting the supply landscape for specific catheter components and raw materials. Boston Scientific Corporation leverages its strong portfolio in interventional catheters to maintain a significant market position in coronary care. Medtronic differentiates through its comprehensive offerings in electrophysiology and structural heart disease solutions, competing on both advanced technology and extensive clinical support.
Cardiac catheterization involves introducing a thin, flexible tube, or catheter, through a blood vessel to the heart for diagnostic or therapeutic purposes. These medical devices often utilize advanced fluoropolymer coatings like PTFE to ensure low friction and high biocompatibility during complex procedures. While diagnostic catheters form a foundational market segment, interventional catheters for applications like coronary angiography represent a higher-value and faster-growing category. Growth in specialized electrophysiology catheters is also notable, driven by rising arrhythmia cases globally.
Regulatory oversight from bodies like the US FDA and China's NMPA mandates rigorous pre-market approval processes for all new catheter systems. In Europe, the Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance requirements, directly influencing product development timelines and costs. Stakeholders must now navigate the dual pressures of accelerating technological innovation in areas like robotics while demonstrating clear cost-effectiveness to healthcare providers and payers.
Market Dynamics
The market's structure is being redefined by the integration of diagnostic imaging, such as Optical Coherence Tomography, directly into therapeutic catheters. This shift responds to pressure from healthcare payers and regulators for single-procedure efficiencies and improved patient safety, fundamentally altering product design and clinical workflows.
Growth Catalysts
- Aging Demographics:The large, aging population in countries like Germany, combined with high national healthcare expenditure, creates sustained demand for coronary and structural heart procedures that utilize advanced cardiac catheters.
- Advanced Imaging Integration:The incorporation of technologies like Optical Coherence Tomography and intravascular ultrasound into catheters enhances diagnostic precision, leading to better procedural planning and improved clinical outcomes.
- Ambulatory Surgical Center Expansion:A procedural volume shift towards ambulatory surgical centers is expanding catheter use, as these facilities offer a cost-effective and convenient alternative to hospitals for appropriate patient cases.
Market Restraints
- Stringent Regulatory Hurdles:Europe's Medical Device Regulation imposes stricter clinical evidence and post-market surveillance requirements, significantly increasing development timelines and costs for new catheter systems entering the EU market.
- High Input Material Costs:Reliance on specialized materials like advanced fluoropolymers and high-purity metals creates vulnerability to price volatility and supply chain disruptions for these critical raw components.
- Non-Invasive Diagnostic Advances:The improving capabilities of non-invasive imaging, such as cardiac computed tomography angiography, can defer or eliminate the need for purely diagnostic catheterization in certain patient populations.
Strategic Opportunities
- Robotic-Assisted Systems:The development of robotic catheter systems offers opportunities for enhanced procedural precision, stability, and reduced radiation exposure for clinicians, opening a new high-value market segment.
- Electrophysiology and Mapping:Integrating advanced 3D mapping systems with specialized electrophysiology catheters provides an opportunity to address the growing global prevalence of complex cardiac arrhythmias like atrial fibrillation.
- Healthcare Infrastructure in China:Expanding hospital infrastructure and increasing insurance coverage in China present a vast opportunity for both diagnostic and interventional catheter products, particularly outside of Tier 1 cities.
Industry Challenges
- Specialized Clinician Training:The rising complexity of interventional procedures, especially with new technologies for structural heart disease, creates a training bottleneck and a shortage of highly skilled interventional cardiologists.
- Cost-Effectiveness Demonstration:Stakeholders must provide extensive clinical and economic evidence to convince healthcare providers and payers of the value of new, higher-priced catheter technologies over established standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Catheterization Market |
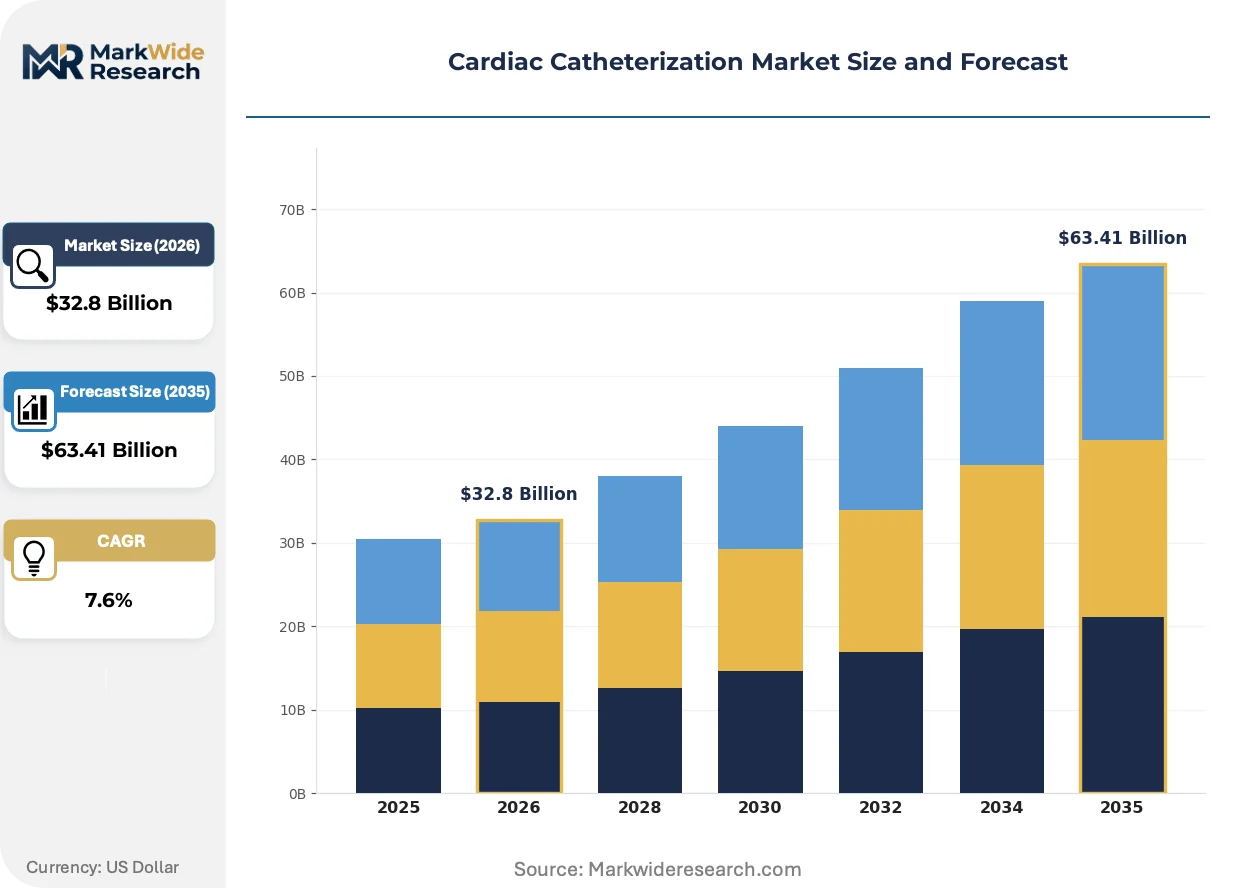
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $63.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Catheters, Interventional Catheters, Electrophysiology Catheters, Hemodynamic Monitoring Catheters, Balloon Catheters Application: Coronary Angiography, Peripheral Angioplasty, Electrophysiological Mapping, Structural Heart Disease, Valvuloplasty End User: Cardiac Care Centers, Specialty Clinics, Research Institutes, Academic Hospitals, Ambulatory Surgical Centers Technology: Balloon Angioplasty, Intravascular Ultrasound, Optical Coherence Tomography, Fractional Flow Reserve, Directional Atherectomy |
| Companies Covered | Abbott Laboratories, Medtronic, Boston Scientific Corporation, Johnson & Johnson, B. Braun Melsungen AG, Terumo Corporation, Siemens Healthineers, Cardinal Health, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Catheterization Market Strategic Shifts & Innovations
The fusion of data analytics, robotics, and material science is pushing cardiac catheters beyond simple conduits into intelligent therapeutic platforms. This evolution prioritizes procedural accuracy, reduced invasiveness, and better clinical data capture for post-procedure analysis and quality improvement.
Miniaturized sensors and micro-electromechanical systems are being embedded into catheter tips to provide real-time physiological data, such as pressure and blood flow. Interventional cardiology departments are adopting these smart catheters for complex coronary interventions to improve decision-making during procedures. This integration of sensing and therapy is collapsing the time and distinction between the diagnostic and therapeutic stages of a patient's care pathway.
Europe's Medical Device Regulation has introduced a Unique Device Identification system requirement for all medical devices, including cardiac catheters. This mandate enforces cradle-to-grave traceability, improving post-market surveillance and allowing for more efficient recall management by manufacturers and health authorities. The entire supply chain, from component suppliers to distributors, is most affected, forcing investment in new inventory and data systems to ensure compliance.
Hospital procurement for high-volume catheters is shifting from individual device purchases towards bundled agreements that include clinical support, training, and inventory management services. This model disrupts the traditional transactional relationship, favoring large vendors who can offer a service wrap around the product. This trend is most visible in the United States and Germany, where large hospital networks leverage their purchasing power to demand greater value.
Cardiac Catheterization Market Segmentation
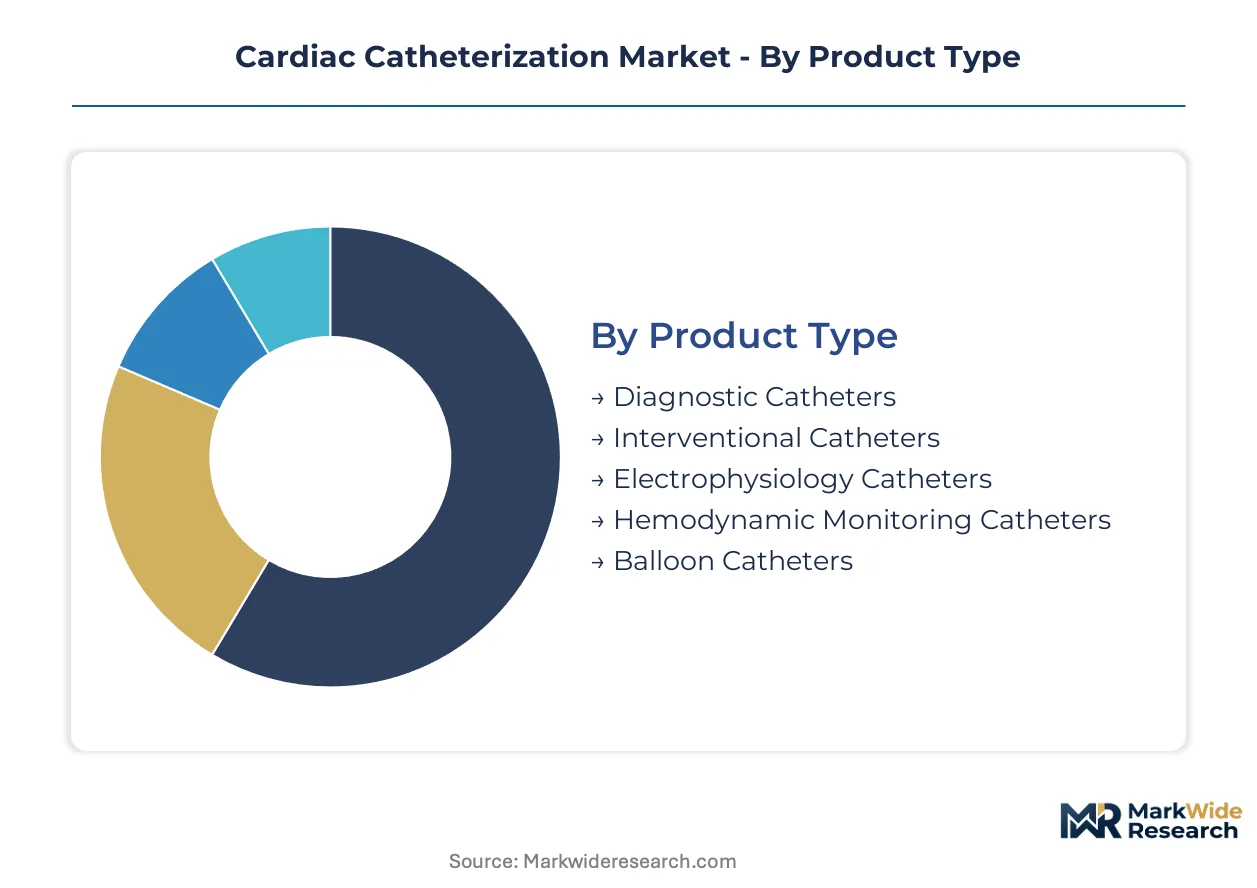
The cardiac catheterization market segments reflect diverse product functionalities, procedural applications, end-user environments, and technological underpinnings. Understanding these distinct categories provides clarity on demand drivers, competitive landscapes, and innovation pathways across the cardiovascular care continuum. Each segment contributes uniquely to patient diagnosis and treatment outcomes.
Product Type:
The product type segment encompasses a spectrum of devices ranging from mature diagnostic tools to advanced interventional and electrophysiology systems.
- Interventional Catheters:These devices are designed for therapeutic procedures, delivering stents, balloons, or other devices to treat blockages or structural defects within the heart and blood vessels. Demand is concentrating in Germany due to its large aging population and high national healthcare expenditure on coronary interventions.
- Electrophysiology Catheters:Specialized catheters precisely map and ablate cardiac tissue responsible for arrhythmias, often integrating advanced 3D mapping systems. Rising global arrhythmia cases, particularly atrial fibrillation, drive significant demand for these sophisticated devices.
- Diagnostic Catheters:These flexible tubes are introduced into the heart chambers or coronary arteries to measure pressures, collect blood samples, or inject contrast dye for imaging purposes. They form a foundational segment for initial cardiac assessment.
- Hemodynamic Monitoring Catheters:Devices like pulmonary artery catheters are utilized to measure blood pressure and flow dynamics within the heart and great vessels for critical care management.
- Balloon Catheters:Often used in angioplasty, these catheters feature an inflatable balloon at their tip to widen narrowed arteries, restoring blood flow.
Diagnostic catheters retain volume leadership; interventional catheters hold the steepest expansion curve.
Application:
Application-specific demand for cardiac catheterization devices is driven by the prevalence of various cardiovascular conditions.
- Coronary Angiography:This diagnostic procedure uses catheters to visualize the coronary arteries, often to detect blockages or narrowing caused by coronary artery disease. It represents a high-volume application globally due to widespread heart disease.
- Structural Heart Disease:Interventions for structural heart conditions, such as transcatheter aortic valve replacement (TAVR) or patent foramen ovale (PFO) closure, utilize highly specialized catheters for complex repairs. The rising incidence of these conditions in aging populations, particularly in Europe, drives demand.
- Peripheral Angioplasty:Catheters are employed to widen narrowed or obstructed arteries outside of the heart, commonly in the legs or arms, to improve blood flow.
- Electrophysiological Mapping:This application involves using electrophysiology catheters to create detailed electrical maps of the heart, pinpointing the source of arrhythmias.
- Valvuloplasty:Catheters with balloons are used to open stiffened heart valves, improving blood flow and reducing symptoms in patients with valvular stenosis.
Coronary angiography procedures represent a significant volume, while structural heart disease interventions are experiencing rapid growth.
End User:
The distribution of cardiac catheterization procedures across different end-user settings reflects varied operational models and patient care priorities.
- Ambulatory Surgical Centers:These facilities offer a cost-effective and convenient alternative for appropriate, less complex cardiac catheterization procedures, expanding their procedural volume. Their efficiency attracts patients seeking outpatient care.
- Academic Hospitals:These large institutions handle the most complex cardiac catheterization cases, serve as training grounds for interventional cardiologists, and conduct significant cardiovascular research. They require a comprehensive range of catheter products.
- Cardiac Care Centers:Dedicated facilities providing specialized cardiovascular diagnosis and treatment, often equipped for a broad spectrum of catheter-based interventions.
- Specialty Clinics:Smaller, focused clinics that perform specific types of cardiac catheterization procedures, often referring complex cases to larger hospitals.
- Research Institutes:Organizations primarily focused on advancing cardiovascular science and developing new catheter technologies and techniques.
Academic hospitals continue to manage the most complex cases, while ambulatory surgical centers are gaining procedural volume for routine interventions.
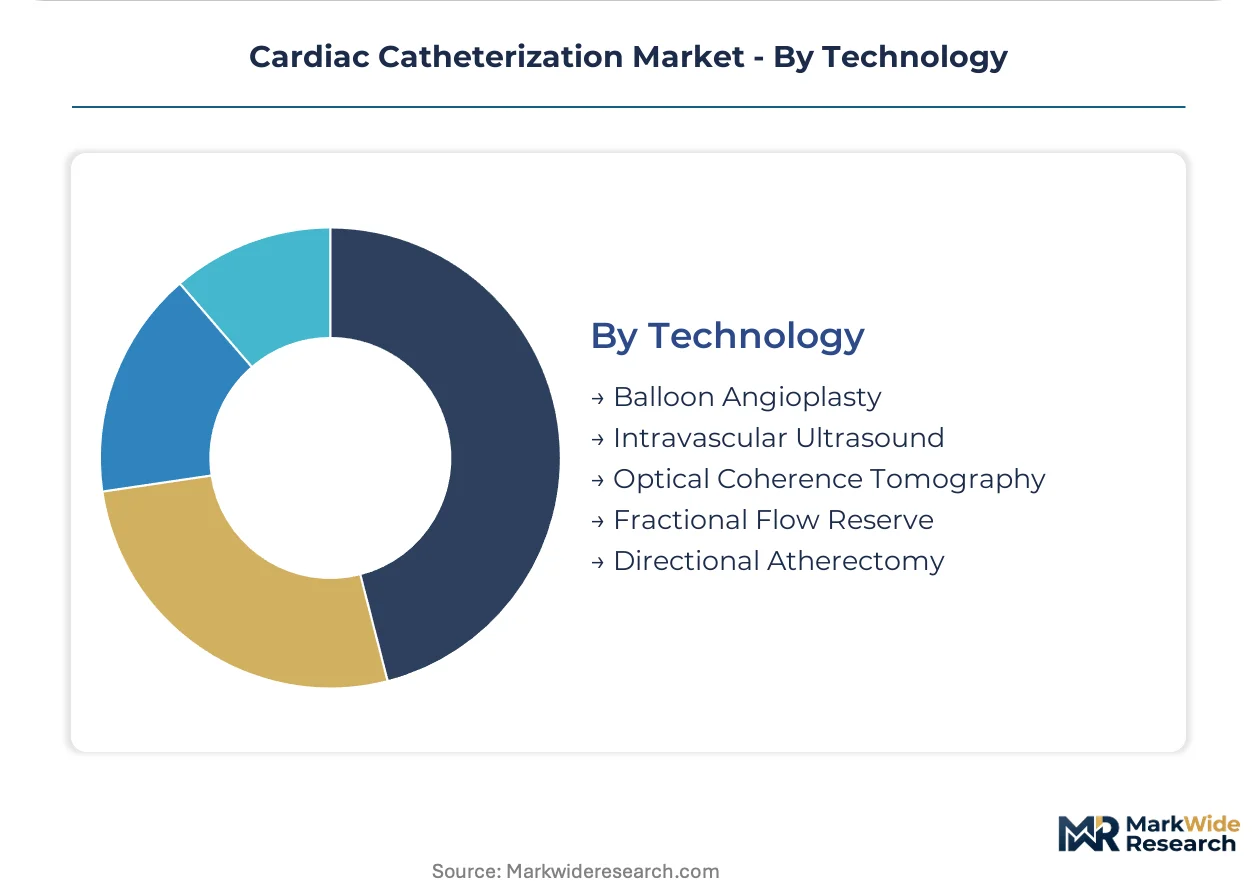
Technology:
Technological advancements within cardiac catheterization focus on improving diagnostic precision and therapeutic efficacy.
- Optical Coherence Tomography:This high-resolution imaging technology is integrated into catheters to provide detailed cross-sectional views of coronary arteries, enhancing diagnostic accuracy and guiding stent placement. Its integration directly improves procedural outcomes.
- Intravascular Ultrasound:Catheter-based ultrasound imaging provides real-time visualization of arterial walls and plaque morphology, assisting clinicians in assessing lesion severity and optimizing interventional strategies. This technology provides critical information for complex cases.
- Balloon Angioplasty:A well-established technology using inflatable balloons to mechanically open narrowed or blocked blood vessels, often followed by stent implantation.
- Fractional Flow Reserve:This physiological measurement, obtained via a specialized catheter, assesses the severity of coronary artery blockages by measuring pressure differences across a stenosis.
- Directional Atherectomy:A technique employing a catheter with a rotating blade or burr to remove atherosclerotic plaque from arterial walls, restoring blood flow.
Optical Coherence Tomography and intravascular ultrasound are increasingly integrated into interventional procedures, enhancing real-time decision-making.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity expansion in China is tilting the supply landscape for specific catheter components and raw materials. This shift influences global distribution patterns and cost structures. Key regions demonstrate varied demand and regulatory environments for cardiac catheterization products.
Germany
Germany's large aging population and high national healthcare expenditure drive sustained demand for coronary and structural heart procedures. The Medical Device Regulation (MDR) imposes stringent clinical evidence and post-market surveillance requirements for new devices. Munich and Berlin are centers for medical device innovation, fostering new catheter technologies and advanced interventional techniques.
China
Expanding hospital infrastructure and increasing insurance coverage fuel demand for both diagnostic and interventional catheter products in China. China's NMPA mandates rigorous pre-market approval processes for new catheter systems entering the market. Shanghai and Shenzhen host significant medical device manufacturing and R&D hubs, attracting investment in advanced medical technologies.
United States
A large aging population and advanced healthcare infrastructure create sustained demand for cardiac catheterization procedures. The US FDA regulates all new catheter systems through rigorous pre-market approval and post-market surveillance. Boston and Minneapolis are critical innovation clusters for interventional cardiology devices, driving significant technological advancements.
Japan
Japan's rapidly aging demographic necessitates increased cardiac interventions, boosting demand for advanced catheterization devices. Japan's PMDA oversees strict regulatory pathways for medical device approval, ensuring product safety and efficacy. Tokyo and Osaka serve as major hubs for advanced medical technology development and adoption in the cardiovascular sector.
Cardiac Catheterization Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical raw materials and sub-assemblies. The market structure exhibits a tiered consolidation, with a few large players dominating the high-value interventional and electrophysiology segments. Strategic archetypes include diversified medical device giants, specialized cardiology solution providers, and niche component manufacturers. Portfolio diversification and strategic partnerships are dominant competitive moves among the larger entities.
Within the advanced interventional cardiology solutions segment, Medtronic exemplifies comprehensive offerings in electrophysiology and structural heart disease. Boston Scientific Corporation anchors a strong portfolio in interventional catheters, maintaining significant market position in coronary care. Abbott Laboratories, a diversified medical technology company, represents another major player offering a broad range of cardiac catheterization products. These entities leverage extensive clinical support and technological innovation to differentiate their offerings in a competitive landscape.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Siemens Healthineers |
| Cardinal Health |
| Teleflex Incorporated |
| Others |
Cost & Logistics Intelligence
China's expanding manufacturing capacity for catheter components and raw materials exerts downward pressure on global pricing for certain sub-assemblies. This shift influences cost structures and market entry points for device manufacturers.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure for new catheter systems, demanding significant clinical evidence for premium valuation. Pricing predominantly follows a value-based model, particularly for advanced interventional and electrophysiology devices. Price differentiation stems from technological innovation, robust clinical outcomes, and comprehensive after-sales service. Pricing pressure intensifies as healthcare payers prioritize cost-effectiveness and single-procedure efficiencies. Ambulatory surgical centers demonstrate higher price sensitivity compared to academic hospitals managing complex cases.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly common for procurement of high-volume catheters. Geographic supply concentration for critical raw materials like advanced fluoropolymers and high-purity metals centers in Asia and specialty chemical manufacturers in Europe. The market relies heavily on specialized components sourced from a limited number of suppliers. Commodity price volatility for these inputs represents a structural supply chain risk. Distribution runs through large vendors offering bundled agreements and direct sales channels to hospitals and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiac catheterization market experiences a shift in buyer power as large hospital networks leverage their purchasing scale. This trend favors vendors capable of offering bundled services and integrated solutions.
For Market Incumbents:
Entrench market leadership through continuous investment in robotic-assisted systems and advanced imaging integration R&D. Develop comprehensive clinical evidence demonstrating superior patient outcomes and cost-effectiveness to counter non-invasive diagnostic advances. Leverage extensive clinical support and technological innovation to differentiate offerings, ensuring strong market positioning against emerging threats and regulatory shifts.
For New Entrants and Emerging Players:
Pursue niche opportunities within specialized electrophysiology catheters or structural heart disease interventions, focusing on unmet clinical needs. Target underpenetrated geographies like China's Tier 2 and 3 cities where hospital infrastructure is expanding. A go-to-market strategy emphasizing cost-effective solutions for appropriate patient cases in ambulatory surgical centers can create market access.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized cardiology solution providers with strong intellectual property in robotics and integrated imaging. Focus on companies demonstrating clear pathways for regulatory approval and robust post-market surveillance capabilities under stricter regulations like the MDR. The signal to watch is the adoption rate of new, integrated diagnostic-therapeutic catheter systems within major hospital networks. Macroeconomic, regulatory, or technological deviation would prompt revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotics and AI Integration | Enhances procedural precision and reduces radiation exposure for clinicians during complex interventions. |
| Advanced Imaging Integration | Improves diagnostic accuracy and guides precise stent placement, leading to better patient outcomes. |
| Electrophysiology Catheter Development | Addresses the rising global prevalence of complex cardiac arrhythmias like atrial fibrillation effectively. |
| China Market Penetration | Captures demand from expanding hospital infrastructure and increasing insurance coverage outside Tier 1 cities. |
| Value-Based Contracting | Aligns product offerings with payer demands for cost-effectiveness and improved patient care pathways. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings and quantitative market sizing. The study incorporates insights from interventional cardiologists, hospital procurement managers, medical device engineers, and regulatory affairs specialists. Secondary validation draws from FDA filings, NMPA reports, industry association publications, and academic research papers, triangulating data through bottom-up and top-down approaches.
The calibration approach integrates quantitative models with qualitative insights to project market dynamics across the analysis window. The analytical framework segments the market by product type, application, end-user, technology, and regional market dynamics. Compound annual growth rates are derived from historical trends and future projections, incorporating key forecast inputs like procedure volumes and technological adoption rates.
Sensitivities concentrate around regulatory changes and economic shifts impacting healthcare expenditure. Forecasts reflect documented assumptions regarding technological advancements and market acceptance of new catheter systems. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market