
 Cardiac Ultrasound Systems Market | 2026-2036
Cardiac Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Ultrasound Systems Market Analysis
Outpatient cardiology clinics is expanding their share of cardiac ultrasound procurement as healthcare systems shift diagnostic volumes away from inpatient settings. GE Healthcare leverages its installed base of premium cart-based systems to sustain recurring service revenue across integrated delivery networks. Philips Healthcare differentiates through advanced 3D transesophageal imaging platforms that occupy the high-acuity segment of cardiac surgery centers. Siemens Healthineers competes on computational ultrasound architectures that reduce exam times in high-throughput hospital environments.
Cardiac ultrasound systems are diagnostic imaging devices that employ high-frequency sound waves, typically operating at 2-15 MHz, to generate real-time visualizations of cardiac structures, valve mechanics, and hemodynamic function for clinical assessment and intervention planning. Their primary purpose is to enable non-invasive evaluation of heart anatomy and physiology across acute, chronic, and perioperative care settings. Portable ultrasound systems are capturing the fastest growth trajectory as emergency departments and satellite clinics prioritize mobility over traditional cart-based footprints. Handheld ultrasound is maturing rapidly with probe-to-smartphone connectivity, though margin pools remain concentrated in premium 3D echocardiography systems deployed in tertiary cardiac centers. Doppler technology and transesophageal approaches anchor the highest-value application tiers, particularly for intraoperative monitoring and complex congenital defect evaluation.
The FDA governs 510(k) and De Novo pathways for cardiac ultrasound devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for transesophageal and contrast-enhanced systems entering European markets. Japan's PMDA maintains distinct approval standards for AI-integrated diagnostic software that manufacturers must navigate separately from hardware certifications. Stakeholders should monitor how divergent regulatory timelines for software-as-medical-device classifications will reshape competitive entry strategies across major markets.
Market Dynamics
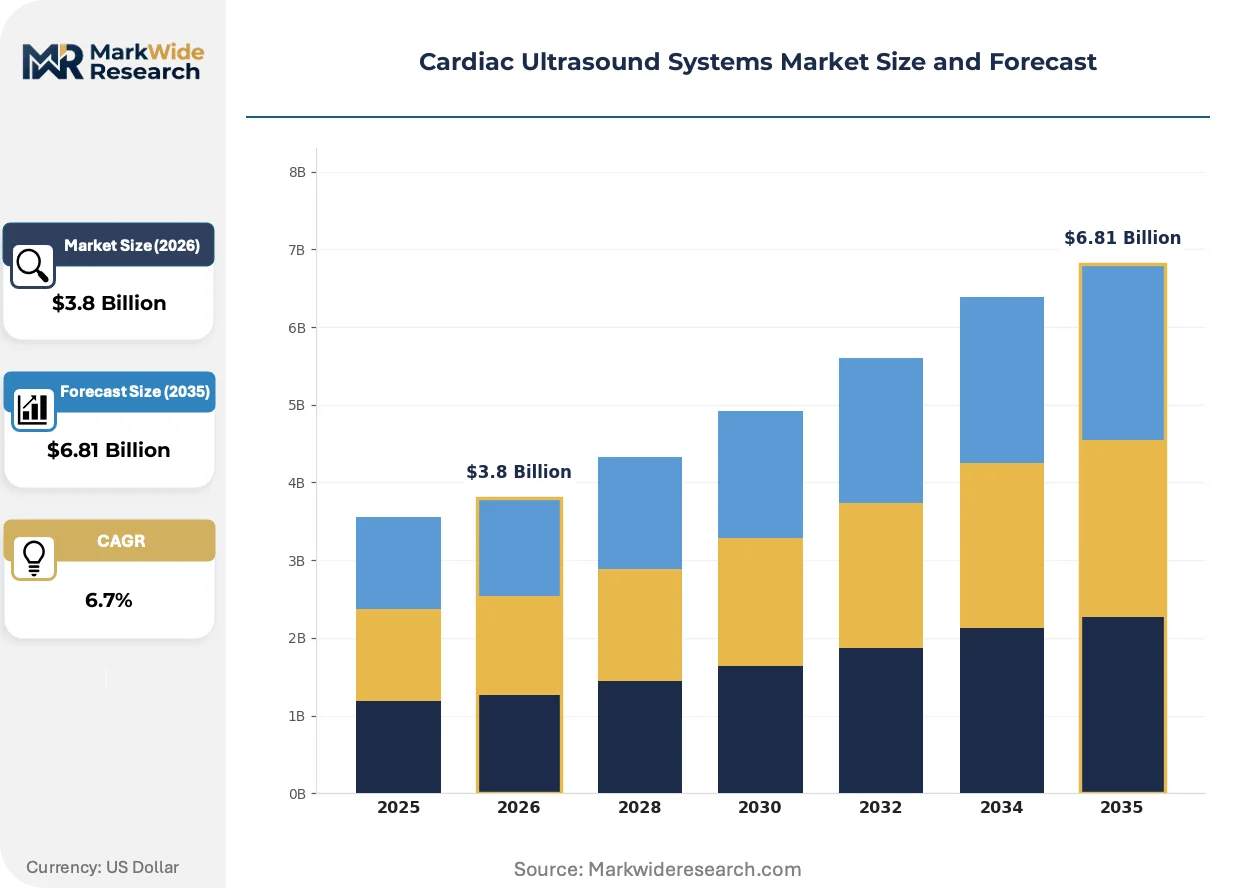
Hospital consolidation and point-of-care decentralization are creating simultaneous pulls toward premium 3D systems in tertiary hubs and handheld devices at the periphery. This bifurcation is fragmenting vendor go-to-market strategies across integrated delivery networks and independent cardiology practices.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements for transesophageal systems are accelerating R&D investment in safer probe designs and automated image acquisition protocols.
- Handheld probe-to-smartphone connectivity:Emergency departments in Germany and satellite clinics across the United States are deploying these systems for rapid triage and bedside assessment.
- Japan's PMDA AI software pathway:Distinct approval standards for diagnostic algorithms are creating dedicated product development tracks separate from hardware certifications.
Market Restraints
- Transducer manufacturing concentration:Precision piezoelectric crystal supply chains cluster in specialized East Asian foundries, creating single-source vulnerability for high-frequency cardiac probes.
- FDA 510(k) backlog variability:Fluctuating review timelines for AI-enabled ultrasound software create revenue recognition uncertainty and pipeline compression.
- CT coronary angiography substitution:Advances in low-dose computed tomography are capturing intermediate-risk chest pain evaluations previously routed to stress echocardiography.
Strategic Opportunities
- Rural United States cardiology deserts:Federally qualified health centers in Mississippi, Alabama, and rural Texas lack on-site echocardiography capacity, creating demand for tele-mentored handheld deployment.
- Contrast-enhanced echocardiography expansion:Microbubble agent approvals for liver and renal imaging are cross-pollinating cardiac perfusion protocols in European academic centers.
- Cloud-native image archiving:Vendor-neutral PACS integration is enabling multi-site cardiac imaging networks in Germany's hospital reform consolidation zones.
Industry Challenges
- Sonographer workforce scarcity:Specialized cardiac imaging technologist training programs in the United States and Germany produce insufficient graduates to match expansion of portable system fleets.
- Legacy cart-based system interoperability:Decades-old DICOM implementations in hospital radiology departments resist seamless integration with AI-augmented handheld workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Ultrasound Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Handheld Ultrasound, 2D Ultrasound, 3D Ultrasound Technology: Doppler Technology, Echocardiography, Contrast Ultrasound, Transesophageal End User: Hospitals, Cardiology Clinics, Imaging Centers, Emergency Departments Application: Heart Valve Imaging, Blood Flow Analysis, Congenital Heart Defects, Cardiac Stress Testing |
| Companies Covered | Canon Medical Systems, Fujifilm Holdings, GE Healthcare, Esaote, Samsung Medison, Philips Healthcare, Mindray Medical International, Chison Medical Imaging, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Ultrasound Systems Market Emerging Trajectories
Computational architectures and AI-augmented acquisition are compressing exam durations while expanding operator independence. These shifts are redistributing value capture from hardware manufacturers toward software and service layers.
Artificial intelligence-enabled automated view recognition is overtaking manual probe manipulation in high-throughput hospital environments. Emergency medicine residents and internal medicine hospitalists are adopting these systems for independent bedside assessment without waiting for cardiology consultation. This capability compression is enabling same-shift discharge decisions and reducing unnecessary telemetry admissions.
The FDA's evolving De Novo pathway for AI-enabled diagnostic software is extending product development timelines for algorithm developers. Manufacturers must now generate prospective clinical validation datasets that exceed historical 510(k) predicate comparisons. Transesophageal echocardiography platforms with integrated AI guidance are experiencing the most pronounced timeline extensions as reviewers demand robust failure-mode analyses.
Point-of-care purchasing committees are consolidating procurement authority previously distributed across radiology and cardiology departments. Integrated delivery networks in the United States are unbundling service contracts from hardware acquisitions, forcing vendors to compete on discrete maintenance pricing. Germany's cardiac imaging network consolidation is accelerating this shift toward centralized equipment standardization and multi-year performance guarantees.
Cardiac Ultrasound Systems Market Segmentation
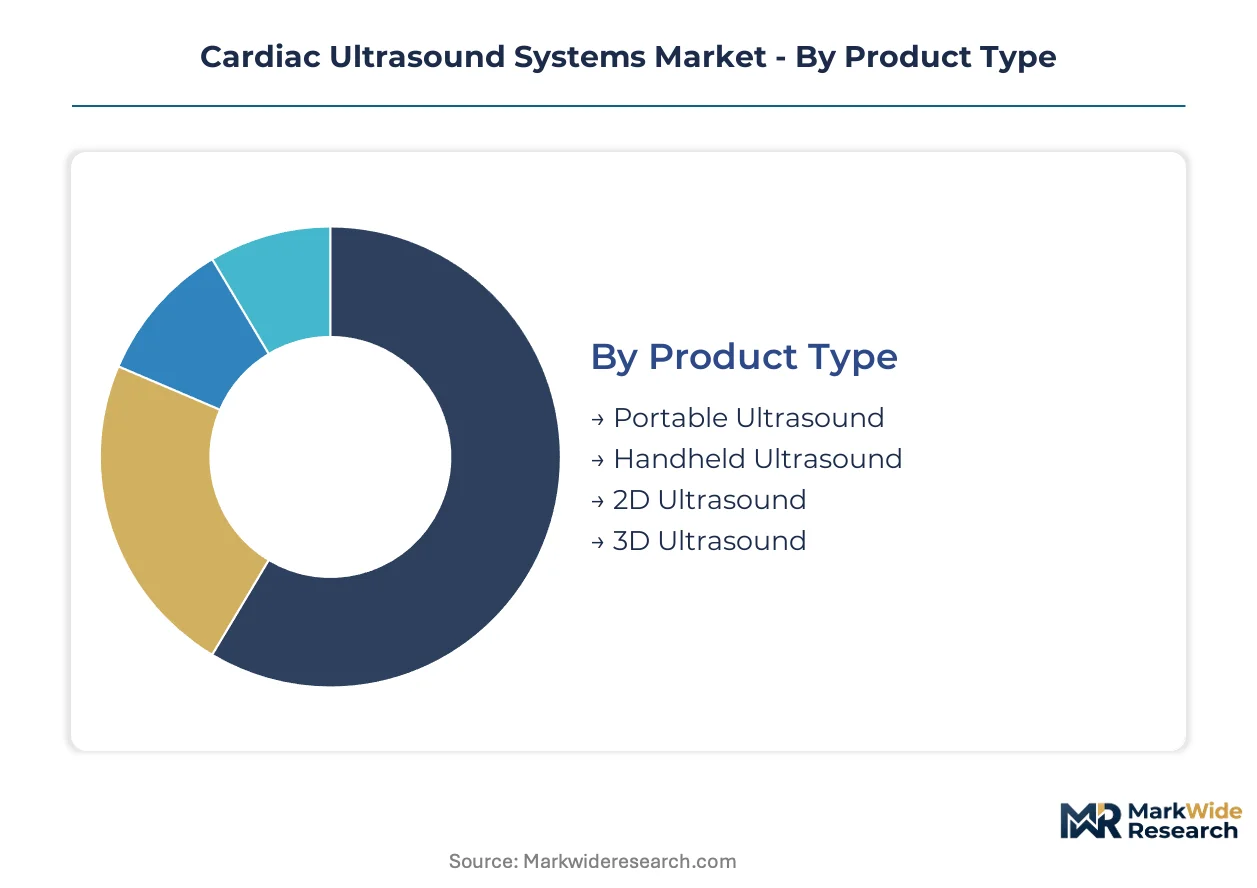
Cardiac ultrasound segmentation reveals how regulatory pathways, clinical workflows, and capital allocation priorities fragment demand across hardware form factors and imaging modalities. Understanding these divides clarifies where FDA 510(k), EU MDR, and Japan PMDA certification burdens concentrate.
Product Type:
Portable and handheld systems face lighter FDA premarket review compared to 3D platforms with AI-integrated acquisition, while cart-based 2D systems occupy the middle tier of regulatory complexity.
- Portable Ultrasound:Battery-powered units with integrated displays and probe storage, typically 5-12 kg, designed for bedside transport within hospital wards. Demand concentrates in United States emergency departments and Germany's consolidating cardiac imaging networks, where point-of-care decentralization is accelerating procurement.
- Handheld Ultrasound:Probe-to-smartphone or probe-to-tablet configurations under 1 kg, leveraging computational offloading to host devices. Mississippi, Alabama, and rural Texas federally qualified health centers are deploying these for tele-mentored echocardiography in cardiology deserts.
- 2D Ultrasound:Conventional grayscale imaging systems forming the installed base backbone.
- 3D Ultrasound:Volumetric acquisition platforms requiring substantial computational hardware and specialized transducer arrays.
2D Ultrasound sits at the top of the volume ranking, with Handheld Ultrasound climbing the fastest.
Technology:
Cost tiers separate commodity Doppler implementations from premium transesophageal platforms, with contrast agents adding recurring consumable revenue streams.
- Doppler Technology:Frequency-shift detection for blood flow velocity quantification, including pulsed-wave, continuous-wave, and color Doppler variants. High-throughput United States hospitals prioritize computational architectures that compress exam durations through automated Doppler trace analysis.
- Transesophageal:Multiplane probe systems inserted into the esophagus for posterior cardiac structure visualization without rib or lung interference. EU MDR's stricter clinical evidence requirements for these invasive probes are accelerating R&D investment in safer designs across European academic centers.
- Echocardiography:Foundational cardiac ultrasound modality encompassing all acoustic imaging of heart structures.
- Contrast Ultrasound:Microbubble-enhanced perfusion imaging using stabilized gas-filled spheres for endocardial border delineation.
Echocardiography sits at the top of the volume ranking, with Contrast Ultrasound gaining share fastest as microbubble approvals cross-pollinate from liver to cardiac protocols.
End User:
Customer type determines procurement authority concentration, with integrated delivery networks unbundling service contracts and independent practices prioritizing capital efficiency.
- Hospitals:Tertiary cardiac centers and community hospitals with dedicated cardiology departments. Germany's national hospital reform initiatives are consolidating equipment standards across multi-site imaging networks, favoring vendors offering multi-year performance guarantees.
- Cardiology Clinics:Outpatient-focused practices performing diagnostic echocardiography without inpatient admission capacity. These settings are expanding procurement share as United States healthcare systems shift diagnostic volumes away from hospital-based delivery.
- Imaging Centers:Dedicated radiology or cardiovascular imaging facilities serving referred patients.
- Emergency Departments:Acute care entry points requiring rapid triage capabilities.
Hospitals sit at the top of the volume ranking, with Cardiology Clinics climbing the fastest as ambulatory site-of-care migration accelerates.
Application:
Maturity curves separate well-established valve assessment from emerging AI-augmented stress protocols, with congenital evaluation requiring specialized pediatric expertise.
- Heart Valve Imaging:Structural and functional assessment of native and prosthetic valves, including stenosis severity quantification and regurgitation characterization. United States cardiac surgery centers are driving demand for advanced 3D transesophageal platforms that enable intraoperative monitoring.
- Congenital Heart Defects:Evaluation of septal defects, valve malformations, and complex anatomy in pediatric and adult congenital populations. Specialized children's hospitals and academic centers in Germany and Japan maintain dedicated protocols requiring high-frequency transducers and extended exam durations.
- Blood Flow Analysis:Hemodynamic quantification across chambers and great vessels.
- Cardiac Stress Testing:Exercise or pharmacologically induced imaging for ischemia detection.
Blood Flow Analysis sits at the top of the volume ranking, with Congenital Heart Defects climbing the fastest as specialized referral networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cardiac ultrasound manufacturing footprints as the FDA's De Novo pathway for AI-enabled software extends timelines while the EU MDR imposes parallel clinical evidence burdens, pushing some assembly toward jurisdictions with clearer premarket navigation.
United States
Emergency departments and federally qualified health centers in Mississippi, Alabama, and rural Texas are deploying handheld probe-to-smartphone systems for tele-mentored echocardiography. The FDA governs 510(k) and De Novo pathways, with evolving premarket review timelines for AI-integrated acquisition creating revenue recognition uncertainty. Greater Boston and the Pacific Northwest host concentrated clusters of algorithm developers facing extended validation requirements.
Germany
National hospital reform initiatives are consolidating equipment standards across multi-site cardiac imaging networks, favoring vendors offering multi-year performance guarantees. The EU Medical Device Regulation imposes stricter clinical evidence requirements for transesophageal systems entering European markets. Bavaria and North Rhine-Westphalia anchor the highest concentration of tertiary cardiac centers driving premium 3D platform procurement.
Japan
Specialized children's hospitals and academic centers maintain dedicated congenital heart defect protocols requiring high-frequency transducers and extended exam durations. The PMDA maintains distinct approval standards for AI-integrated diagnostic software that manufacturers navigate separately from hardware certifications. The Kanto region around Tokyo concentrates the largest installed base of advanced echocardiography systems.
China
Domestic manufacturers are capturing share in portable and handheld segments as hospital procurement prioritizes capital efficiency in community healthcare settings. The NMPA governs medical device registration with separate pathways for imported versus domestically produced systems. The Yangtze River Delta and Pearl River Delta host the primary manufacturing clusters for piezoelectric crystal assemblies and transducer fabrication.
United Kingdom
Outpatient cardiology clinics are expanding procurement share as NHS England shifts diagnostic volumes toward ambulatory settings. The MHRA operates post-Brexit regulatory frameworks that maintain alignment with EU MDR clinical evidence standards while streamlining certain conformity assessment routes. London and the Southeast concentrate private imaging center investment in contrast-enhanced perfusion protocols.
Cardiac Ultrasound Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium 3D platform vendors sustaining concentrated positions in tertiary cardiac surgery centers while handheld specialists penetrate point-of-care decentralization. The vendor base organizes around three archetypes: diversified imaging conglomerates with full modality portfolios, ultrasound pure-plays with computational differentiation, and emerging Asian manufacturers competing on capital efficiency. Dominant competitive moves include unbundling service contracts from hardware acquisitions and forming multi-year performance guarantee arrangements with consolidating integrated delivery networks.
Within the diversified imaging conglomerate tier, GE Healthcare and Philips Healthcare occupy positions sustained by installed base leverage and recurring service revenue across integrated delivery networks. Siemens Healthineers anchors the computational architecture vector with reduced exam time value propositions for high-throughput hospital environments. Among Asian manufacturers, Mindray Medical International exemplifies capital-efficient portable system penetration into community hospital and clinic settings.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Fujifilm Holdings |
| GE Healthcare |
| Esaote |
| Samsung Medison |
| Philips Healthcare |
| Mindray Medical International |
| Chison Medical Imaging |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
Sonographer workforce concentration in the United States and Germany creates labor-cost differentials that widen pricing-tier spreads between premium 3D systems and handheld alternatives. These specialized cardiac imaging technologist training programs produce insufficient graduates to match portable system fleet expansion, forcing vendors to absorb training costs into premium-tier pricing while economy-tier handheld devices compete on capital efficiency alone.
Pricing Analysis
Distributor margins on portable ultrasound systems compress pricing power at the channel layer, particularly for mid-tier battery-powered units sold through integrated delivery networks. Three-tier pricing structure across premium 3D transesophageal platforms, standard cart-based systems, and economy handheld devices separates vendors by certification grade and after-sales service bundling. Pricing pressure stems from CT coronary angiography substitution in intermediate-risk chest pain evaluations, forcing stress echocardiography vendors toward value-based contracting. Emergency departments exhibit highest price sensitivity due to capital constraints, while tertiary cardiac surgery centers remain least sensitive given intraoperative monitoring requirements.
Supply Chain Analysis
Dual-sourcing requirements for precision piezoelectric crystals compel manufacturers to qualify multiple East Asian foundries despite concentration risks. Transducer fabrication draws from specialized foundries in China, Japan, and South Korea, with raw material dependencies spanning high-purity lead zirconate titanate, specialized ceramic substrates, and medical-grade encapsulation polymers. Single-source vulnerability for high-frequency cardiac probes constitutes the dominant supply chain risk, compounded by tariff exposure on precision electronics. Distribution runs through direct OEM relationships with hospital purchasing committees and GPO contracts, bypassing traditional distributor layers in consolidated integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac ultrasound manufacturing presents a geographic-arbitrage opportunity between the FDA's extended De Novo timelines in the United States and the EU MDR's parallel clinical evidence burdens, favoring jurisdictions with clearer premarket navigation for algorithm developers.
For Market Incumbents: Hedge transducer supply exposure by qualifying secondary foundry capacity in South Korea and Taiwan, reducing dependence on single-source East Asian piezoelectric crystal suppliers. Invest in automated image acquisition protocols to offset sonographer workforce scarcity in high-throughput hospital environments. Prioritize CE marking pathway acceleration for transesophageal platforms under EU MDR's stricter clinical evidence requirements.
For New Entrants and Emerging Players: Capture federally qualified health center demand in Mississippi, Alabama, and rural Texas through tele-mentored handheld deployment partnerships. Target cardiology deserts with probe-to-smartphone configurations under 1 kg, leveraging computational offloading to minimize hardware costs. Pursue direct-to-clinic sales models that bypass consolidated hospital purchasing committees.
For Investors and Strategic Acquirers: Diversified imaging conglomerates with full modality portfolios are the most active acquirers in this space, seeking computational ultrasound specialists to fill capability gaps. Long-term viability hinges on software-as-medical-device revenue streams overtaking hardware margins. Monitor FDA 510(k) backlog variability as the critical inflection signal for algorithm developer revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | AI-enabled diagnostic software requires prospective clinical validation datasets exceeding historical predicate comparisons. |
| CE Marking Pathway | EU MDR imposes stricter clinical evidence requirements for transesophageal systems entering European academic centers. |
| Hospital System Partnership | Germany's national hospital reform consolidates equipment standards across multi-site cardiac imaging networks. |
| Software Companion Development | Automated view recognition enables emergency medicine residents to perform independent bedside assessment. |
| Reimbursement Strategy | Shift toward ambulatory site-of-care migration expands outpatient cardiology clinic procurement authority. |
Methodological Framework
Multiple input streams — regulatory filing analysis, hospital procurement database review, and primary stakeholder interviews — were reconciled to construct market estimates. Conversations with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and cardiac sonographers informed demand-side validation. Secondary sources encompassed FDA 510(k) clearances, EU MDR technical documentation, PMDA approval records, and CMS Medicare reimbursement data. Bottom-up unit economics and top-down macroeconomic triangulation cross-validated segment-level projections.
Historical shipment trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, technology tier, end-user category, and application area dimensions. CAGRs were derived from fitted trend analysis adjusted for regulatory timeline uncertainty and technology substitution effects. Forecast inputs included transducer manufacturing capacity constraints, sonographer workforce graduation rates, and AI software validation pipeline density.
Underlying measurement precision varies by segment; portable and handheld system forecasts carry tighter precision than emerging AI-augmented 3D platforms where regulatory pathways remain unsettled. Projections reflect assumptions regarding FDA review timeline normalization and EU MDR conformity assessment streamlining. Deviation in transducer supply chain concentration or PMDA AI software pathway evolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market