
 Telemedicine Workstations Market | 2026-2036
Telemedicine Workstations Market Size, Share, and Industry Trends Forecast 2026-2036
Telemedicine Workstations Market Insights
The EU Green Deal and associated CSRD reporting obligations is broadening procurement criteria for healthcare technology across European hospital systems. Philips Healthcare leverages its integrated imaging heritage to anchor premium workstation lines in radiology-heavy configurations. AMD Telemedicine specializes in ruggedized portable units that sustain field deployment across military and disaster-response settings. Epic Systems Corporation dominates EMR-native workflows, embedding telemedicine modules directly into provider operating rhythms.
Telemedicine workstations comprise purpose-built computing and peripheral assemblies engineered for clinical-grade video capture, real-time data transmission, and secure patient interaction, typically integrating 4K cameras, electronic stethoscopes, and FDA-cleared diagnostic peripherals within wheeled or fixed enclosures. These systems serve the commercial purpose of replicating in-person clinical encounters through synchronous audiovisual links while maintaining HIPAA-compliant data handling and audit trails. Desktop workstations occupy the mature volume tier where hospital IT standardization drives replacement cycles, whereas integrated solutions capture expanding margin pools as health systems consolidate vendor relationships around single-platform ecosystems. Portable units represent the fastest-growing configuration as homecare services and mobile clinic deployments multiply.
FDA cybersecurity guidance, HIPAA privacy rules, and the EU MDR collectively shape hardware design mandates, software validation requirements, and cross-border data governance for workstation manufacturers seeking multi-regional market access. India's CDSCO medical device rules and BIS electronics standards impose additional localization and testing obligations for imported systems. Stakeholders must monitor evolving reimbursement codes and interoperability certification timelines to align product roadmaps with purchasing authority shifts.
Market Dynamics
Federal telehealth parity mandates in the United States are compressing procurement cycles for rural hospital networks while simultaneously tightening FDA cybersecurity validation requirements for connected diagnostic peripherals.
Growth Catalysts
- Reimbursement Parity Mandates:Medicare and Medicaid telehealth parity rules in the United States eliminate financial disincentives for virtual care delivery, accelerating workstation deployment across rural critical access hospitals.
- India's Ayushman Bharat Digital Mission:Government-funded telemedicine infrastructure programs at district health centers create concentrated demand for integrated diagnostic workstations with local language interfaces.
- 4K Clinical Video Standardization:Hardware vendors embed broadcast-grade imaging sensors to meet radiology-grade visualization requirements for remote specialist consultations.
Market Restraints
- Semiconductor Supply Concentration:GPU and image signal processor sourcing from Taiwan and South Korea creates vulnerability for manufacturers building real-time video encoding capabilities.
- FDA 510(k) Cybersecurity Burden:Pre-market submission requirements for connected medical devices extend validation timelines and inflate engineering overhead for software-defined peripherals.
- Tablet-Based Substitutes:Consumer-grade mobile devices with detachable diagnostic peripherals capture price-sensitive primary care segments that do not require FDA-cleared enclosures.
Strategic Opportunities
- Home-Based Chronic Care:Medicare reimbursement for remote patient monitoring creates white space for portable workstations with integrated biometric sensors in post-acute settings.
- EU AI Act Compliance Services:Manufacturers can bundle conformity assessment documentation with workstation sales to European hospital systems facing algorithmic transparency mandates for diagnostic decision support.
- Cloud-Native Architecture Convergence:Edge computing platforms are converging with zero-trust security frameworks to enable workstation-as-a-service models that reduce capital expenditure barriers for small clinic buyers.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time operating system development for FDA-cleared devices requires specialized skill sets concentrated in medical device hubs like Minneapolis and San Diego.
- Legacy EMR Integration Complexity:Health systems running on-premise Epic or Cerner deployments demand custom API development for seamless telemedicine workflow embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemedicine Workstations Market |
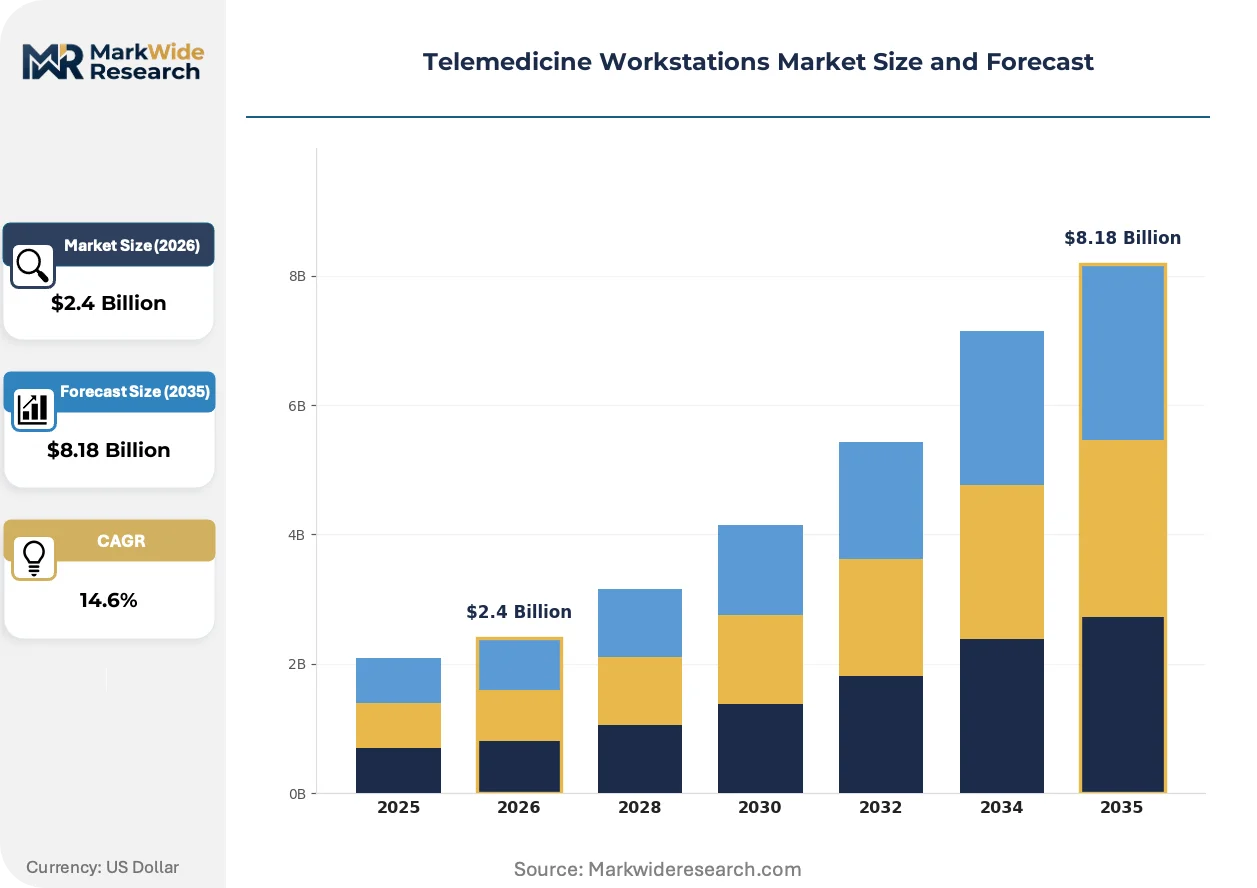
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Workstations, Portable Units, Integrated Solutions, Carts Technology: Video Conferencing, Remote Monitoring, Health Data Exchange, EMR Integration End User: Hospitals, Clinics, Homecare Services, Telehealth Providers Application: Consultation, Diagnosis, Patient Monitoring, Follow-Up Care |
| Companies Covered | Philips Healthcare, GE Healthcare, Siemens Healthineers, AMD Telemedicine, GlobalMed, Medtronic, Oracle Cerner, Epic Systems Corporation, Polycom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemedicine Workstations Market Trends and Innovations
Clinical-grade video architecture is displacing consumer conferencing standards while regulatory frameworks harden around algorithmic transparency and data sovereignty.
Multi-spectral imaging sensors are converging with AI-powered diagnostic assistance to enable remote dermatology and wound assessment workflows. Rural health networks in the United States are piloting these configurations for specialist shortage mitigation. The structural consequence is converging with traditional telepresence boundaries, compressing the gap between synchronous consultation and asynchronous diagnostic review.
The EU AI Act's risk classification system for medical decision support algorithms is mandating conformity assessment procedures for workstation-embedded diagnostic software. Manufacturers must now document training data provenance and algorithmic performance across demographic subgroups. Radiology-heavy configurations face the steepest compliance burden, driving consolidation around vendors with established notified body relationships.
Hospital procurement departments are unbundling after-sales service contracts from hardware acquisition, favoring third-party technical support providers with multi-vendor certification. Integrated solution vendors face margin compression as buyers separate maintenance spend from capital equipment budgets. This pattern is most visible in German hospital networks undergoing digital transformation funding cycles.
Telemedicine Workstations Market Segmentation
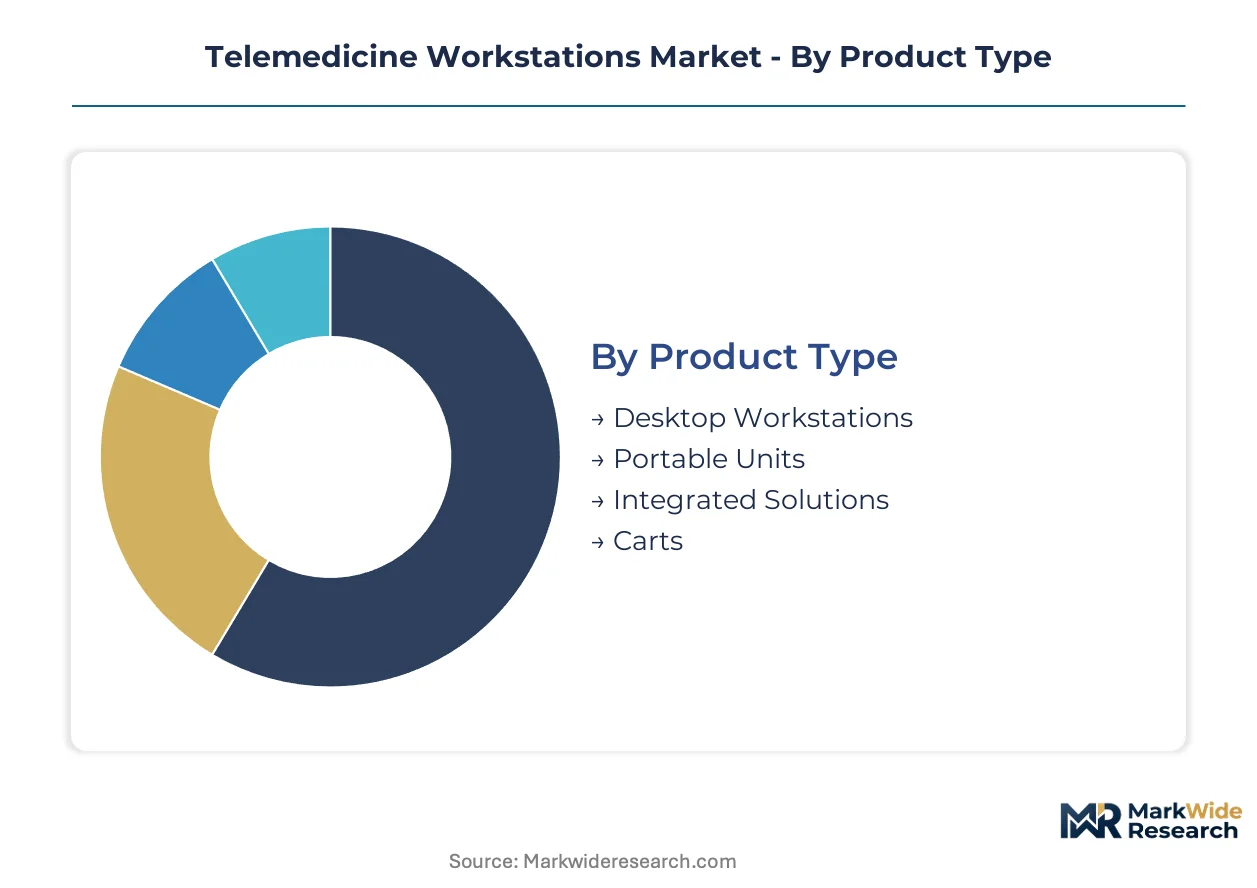
Telemedicine workstation procurement splits sharply between standardized hospital IT deployments and specialized configurations for field medicine. Understanding these fault lines reveals where vendor consolidation and margin compression concentrate.
Product Type:
Standardization dominates high-volume hospital contracts while customization commands premium positioning in mobile and integrated deployments.
- Desktop Workstations:Fixed-location computing assemblies with 4K clinical cameras and FDA-cleared diagnostic peripherals housed in antimicrobial enclosures. Hospital IT standardization in the United States drives replacement cycles through bulk purchasing agreements with integrated delivery networks.
- Portable Units:Ruggedized battery-powered systems with collapsible form factors engineered for military triage and disaster response. AMD Telemedicine anchors this tier with field-hardened configurations; India's district health centers under Ayushman Bharat Digital Mission represent concentrated procurement demand.
- Integrated Solutions:Single-vendor ecosystems bundling hardware, software, and EMR connectivity.
- Carts:Wheeled enclosures with height-adjustable mounts for shared-department deployment.
Most installed capacity flows through Desktop Workstations. Expansion is steepest in Portable Units.
Technology:
Cost tiers separate commodity video infrastructure from regulated data exchange and EMR-native workflows.
- Video Conferencing:Clinical-grade audiovisual stacks with broadcast sensors and noise-canceling arrays replacing consumer-grade platforms. 4K standardization for radiology-grade remote consultation drives sensor procurement from Taiwan and South Korea.
- Remote Monitoring:Continuous biometric capture with edge computing and cellular backhaul for post-acute settings. Medicare reimbursement codes for chronic care management create concentrated demand in United States home health agencies.
- Health Data Exchange:Interoperability middleware for cross-platform patient record transmission.
- EMR Integration:Native workflow embedding within Epic or Cerner operating rhythms.
Volume concentrates in Video Conferencing infrastructure. Remote Monitoring climbs the fastest as reimbursement shifts toward value-based chronic care.
End User:
Customer type determines procurement authority structure and compliance burden intensity.
- Hospitals:Acute care systems with capital equipment committees and multi-year vendor contracts. German hospital networks undergoing digital transformation funding cycles unbundle service contracts from hardware acquisition.
- Clinics:Smaller facilities with constrained IT staff and price-sensitive procurement. Tablet-based substitutes with detachable peripherals capture this tier where FDA-cleared enclosures are not mandated.
- Homecare Services:Post-acute and hospice providers deploying portable units for remote patient monitoring.
- Telehealth Providers:Virtual-first care organizations with cloud-native architecture requirements.
Procurement volume centers on Hospitals. Homecare Services is gaining share fastest as Medicare expands remote monitoring reimbursement.
Application:
Maturity gradients separate established synchronous consultation from emerging diagnostic and monitoring workflows.
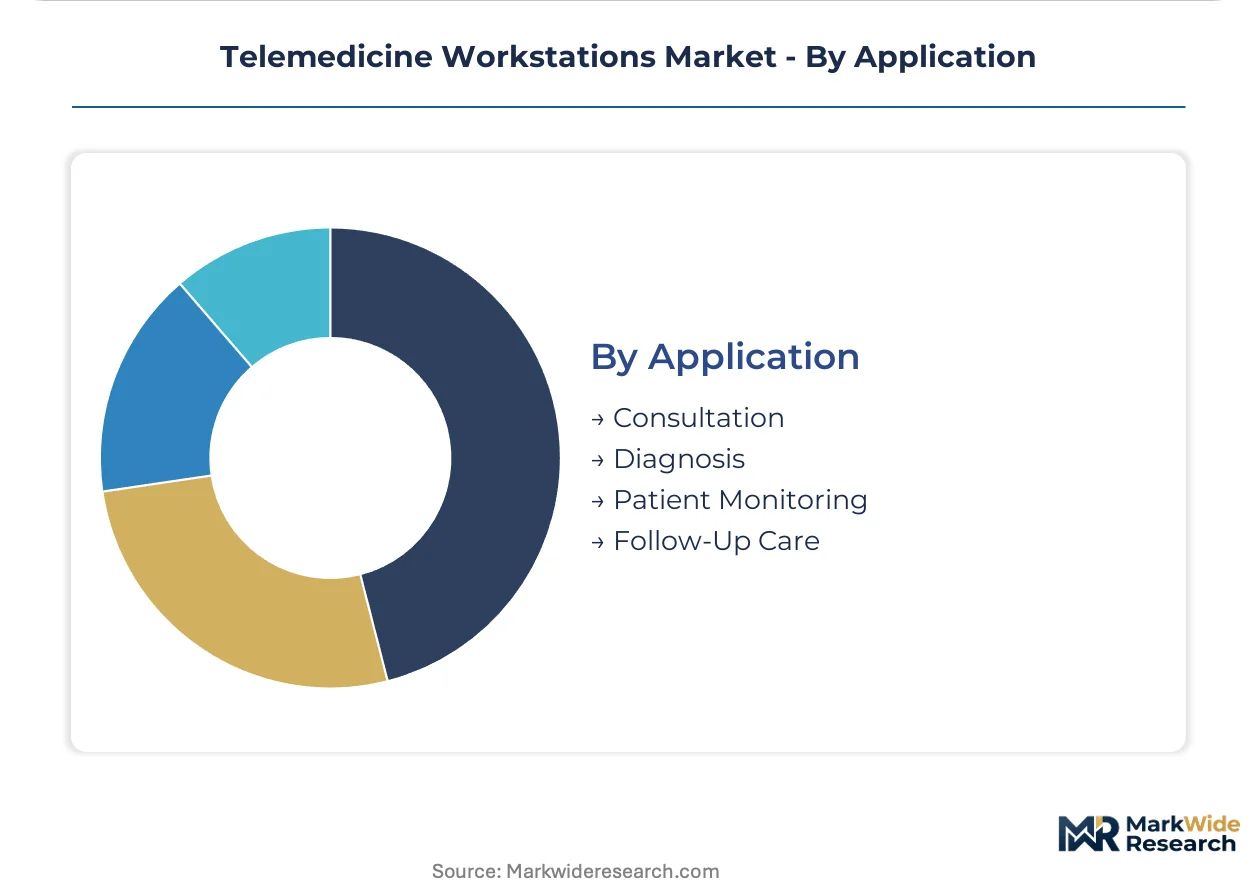
- Consultation:Real-time specialist encounters for rural hospital networks facing physician shortages. United States critical access hospitals deploy these configurations under federal telehealth parity mandates.
- Diagnosis:AI-assisted remote assessment with multi-spectral imaging for dermatology and wound care. EU AI Act conformity requirements impose documentation burdens for algorithmic transparency across demographic subgroups.
- Patient Monitoring:Continuous vital sign tracking with automated alert escalation.
- Follow-Up Care:Post-discharge check-ins and medication adherence verification.
Deployment density peaks in Consultation workflows. Diagnosis expands most quickly as imaging sensors converge with regulatory-hardened AI assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telemedicine workstation manufacturing traces its commercial origins to post-war American medical imaging innovation, with early clinical video systems emerging from Minneapolis and San Diego defense-electronics clusters before spreading to European precision-engineering centers and Asian electronics manufacturing hubs.
United States
Federal telehealth parity mandates and Medicare reimbursement expansion drive procurement across rural critical access hospitals. FDA cybersecurity guidance for connected medical devices tightens hardware validation requirements for domestic manufacturers. Minneapolis and San Diego retain concentrated embedded firmware talent pools serving FDA-cleared device development.
Germany
Hospital networks undergoing digital transformation funding cycles unbundle service contracts from hardware acquisition, compressing integrated vendor margins. EU MDR and EU AI Act conformity requirements impose documentation burdens for diagnostic decision support algorithms. Baden-Württemberg precision-engineering clusters supply broadcast-grade imaging sensor housings for radiology-grade configurations.
India
Government-funded telemedicine infrastructure under Ayushman Bharat Digital Mission creates concentrated workstation demand at district health centers. CDSCO medical device rules and BIS electronics standards impose localization and testing obligations for imported systems. Karnataka and Telangana electronics manufacturing corridors attract assembly investment for regional market access.
China
Domestic hospital system modernization and rural healthcare network expansion generate procurement volume for cost-optimized configurations. NMPA medical device registration and MIIT cybersecurity certification shape product design mandates for market entry. Yangtze River Delta electronics manufacturing clusters supply image signal processors and 4K camera modules.
Japan
Aging population demographics and specialist physician shortages accelerate telemedicine workstation deployment in community hospitals. PMDA quality management system requirements and JIS standards govern hardware reliability specifications. Kanto region medical device manufacturers integrate broadcast-grade video with traditional imaging equipment heritage.
Telemedicine Workstations Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and EMR integration depth. The vendor base separates into three tiers: imaging heritage conglomerates with radiology-grade configurations, EMR-native workflow specialists, and ruggedized field-deployment fabricators. Consolidation pressures concentrate around integrated solution vendors facing procurement unbundling, while portable unit specialists capture homecare expansion. Dominant competitive moves include strategic partnerships for interoperability certification and portfolio diversification into cloud-native service models.
Within the imaging heritage tier, Philips Healthcare and Siemens Healthineers exemplify premium positioning through radiology-heavy workstation configurations. AMD Telemedicine occupies a distinct field-deployment archetype with ruggedized portable units engineered for military and disaster-response settings. Epic Systems Corporation represents EMR-native workflow dominance, embedding telemedicine modules directly into provider operating rhythms rather than competing as standalone hardware vendors.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Siemens Healthineers |
| AMD Telemedicine |
| GlobalMed |
| Medtronic |
| Oracle Cerner |
| Epic Systems Corporation |
| Polycom |
| Others |
Pricing and Supply Chain Analysis
Rural critical access hospitals in the United States anchor procurement volume through bulk purchasing agreements with integrated delivery networks, compressing price points across standardized desktop configurations while premium integrated solutions command margin through EMR-native workflow bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates radiology-grade integrated solutions from FDA-cleared desktop assemblies and tablet-based substitutes without certification. Price differentiation rests on cybersecurity validation tier and after-sales service bundling, with German hospital networks unbundling maintenance contracts to intensify cost compression. Pricing pressure stems from procurement committee standardization mandates, while clinics exhibit highest price sensitivity and academic medical centers show lowest.
Supply Chain Analysis
Freight costs for precision imaging sensors from Taiwan and South Korea amplify landed cost volatility for manufacturers assembling real-time video encoding capabilities. GPU and image signal processor sourcing draws from Yangtze River Delta and Karnataka electronics corridors, with embedded firmware talent concentrated in Minneapolis and San Diego medical device hubs. Single-source vulnerability in Taiwan semiconductor foundries threatens production continuity. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with FDA cybersecurity guidance for connected medical devices creating recurring compliance demand that locks in vendor relationships across replacement cycles.
For Market Incumbents: Anticipate margin compression from procurement unbundling in German hospital networks by deepening certification investment for EU AI Act conformity documentation. Vertical integration into edge computing platforms defends against cloud-native workstation-as-a-service entrants. FDA 510(k) submission expertise remains the critical moat. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass GPO contract barriers that protect established vendors in hospital procurement. India's district health centers under Ayushman Bharat Digital Mission represent the most penetrable geography, with local language interface customization as the decisive go-to-market angle. Portable units for homecare services offer white-space expansion. For Investors and Strategic Acquirers: Health system IT consolidators are the most active acquirer in this space, seeking embedded firmware capabilities and notified body relationships for EU market access. Long-term viability hinges on algorithmic transparency infrastructure for diagnostic decision support. Watch Medicare remote patient monitoring reimbursement code expansion as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Pre-market validation for connected peripherals accelerates hospital procurement cycles under federal parity mandates. |
| EU AI Act Conformity Bundling | Documentation services reduce compliance burden for radiology-heavy configurations in German hospital networks. |
| Hospital System Partnership | Epic-native workflow embedding captures integrated delivery network standardization decisions. |
| Software Companion Development | Cloud-native architecture enables workstation-as-a-service models for small clinic buyers. |
| Reimbursement Strategy | Medicare remote monitoring codes unlock portable unit demand in United States home health agencies. |
Research Methodology
Coverage spans the United States, Germany, India, China, and Japan, with primary inputs from each market combining structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and telehealth platform operators alongside secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body documentation, and hospital procurement records. Bottom-up shipment estimates triangulate against top-down expenditure analysis.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon, modeling workstation configurations by product type, technology tier, end-user scale, and application maturity. CAGRs derive from segment-specific adoption curves weighted against reimbursement timeline visibility and regulatory certification backlogs. Forecast inputs include semiconductor supply lead times and interoperability certification queue lengths.
FDA guidance revision, EU AI Act enforcement timing, and Medicare reimbursement code expansion are the dominant revision risks that could accelerate or compress deployment trajectories. Forecasts reflect documented assumptions about regulatory stability and supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Online Therapy Services Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Asia-Pacific Ehealth Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
US Virtual Visits Market
Telemedicine
Global Telemedicine Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
5G Telemedicine Platform Market