
 Global Cardiac Restoration Systems Market | 2026-2036
Global Cardiac Restoration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Restoration Systems Market Foresight
Polyester is decoupling from ventricular assist device construction as manufacturers shift toward bioabsorbable polymers that reduce thrombogenic risk and eliminate permanent foreign body retention. Edwards Lifesciences Corporation leverages its transcatheter expertise to anchor premium positioning in valve regeneration segments. Medtronic plc sustains broad manufacturing scale across electrotherapy and wireless monitoring platforms. Abbott Laboratories differentiates through integrated diagnostic-to-therapy workflows that span cardiac resynchronization therapy devices and implantable monitoring systems.
Cardiac restoration systems encompass implantable and percutaneous devices, engineered tissues, and electrophysiological instruments designed to recover or replace native myocardial function following ischemic injury, chronic failure, or structural degeneration. These systems typically incorporate biocompatible polymers, biological scaffolds, or electronic pulse generators operating at 2–8 volts with hermetic titanium enclosures rated for multi-year implantation. Ventricular assist devices occupy the largest revenue pool due to established reimbursement and Bridge-to-Transplant indications, while stem cell therapy segments represent the fastest-expanding category as clinical trials advance autologous cardiomyocyte regeneration protocols. Cardiac patches manufactured via 3D printing are capturing margin concentration where patient-specific anatomical matching commands premium pricing against standard off-the-shelf configurations.
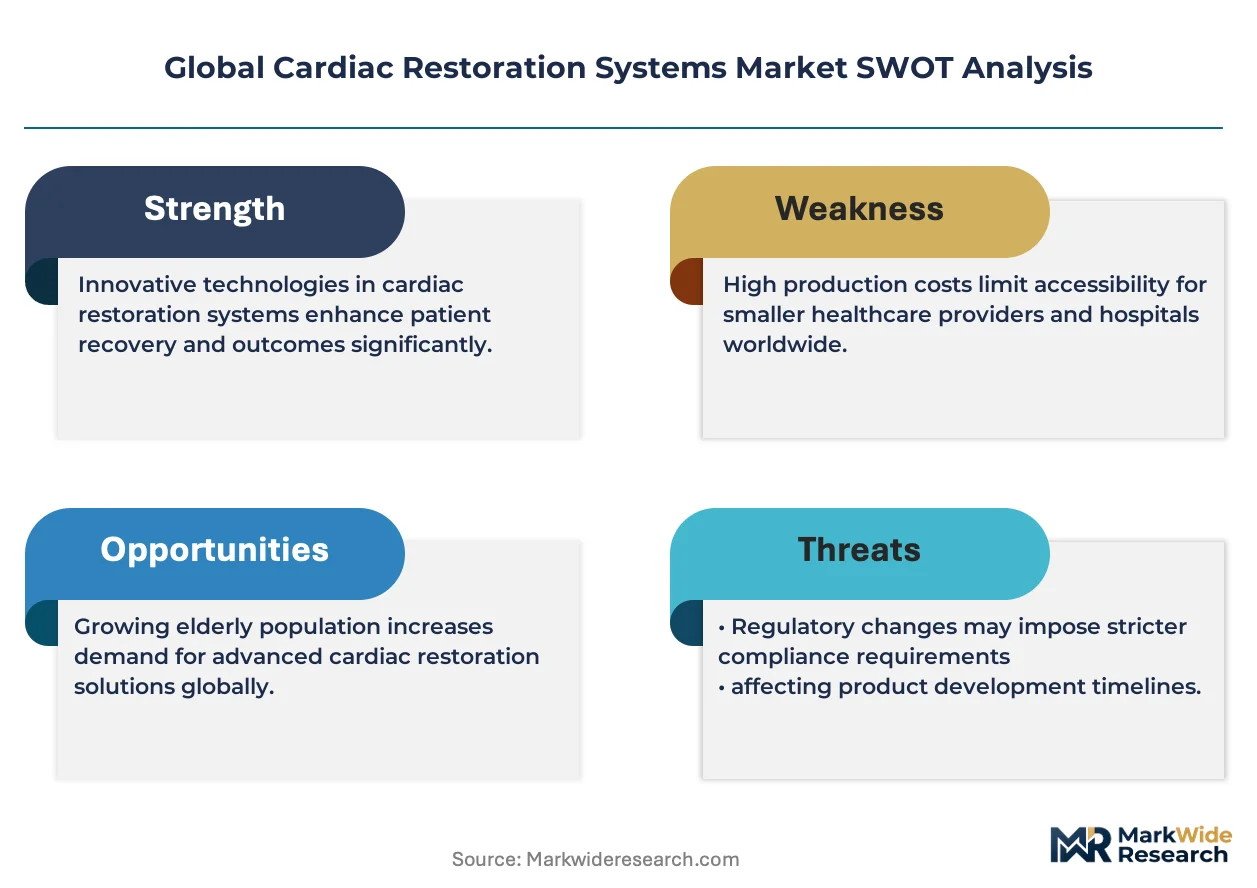
FDA premarket approval pathways and EMA Medical Device Regulation conformity assessments govern product commercialization, with both agencies intensifying scrutiny of bioabsorbable material degradation profiles and long-term biocompatibility data. The EU AI Act and FDA software-as-medical-device guidance are extending compliance burdens to wireless monitoring systems that incorporate machine learning algorithms for arrhythmia prediction. Stakeholders must monitor evolving evidentiary standards for regenerative medicine products where randomized controlled trial requirements are tightening faster than manufacturing scale-up timelines.
Market Dynamics
Bioabsorbable polymers are restructuring competitive positioning in cardiac restoration as manufacturers abandon permanent synthetic substrates in favor of degradable scaffolds that eliminate long-term thrombogenic complications and foreign body response.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for ventricular assist devices and regenerative therapies compress time-to-market for novel cardiac patches and stem cell delivery systems.
- Japan's super-aging demographic:METI reimbursement expansion for destination therapy indications drives procedural volume in specialized cardiac centers across Tokyo, Osaka, and Nagoya clusters.
- 3D bioprinting of patient-specific cardiac patches:Additive manufacturing platforms enable anatomical matching that commands premium pricing against standard configurations in German and US hospital procurement.
Market Restraints
- Platinum-iridium electrode cost volatility:Supply concentration in South African and Russian mining operations exposes electrophysiological device margins to raw material price swings.
- EMA MDR clinical evidence requirements:Expanded biocompatibility surveillance for bioabsorbable degradation products extends approval timelines beyond manufacturing scale-up capacity.
- Mechanical circulatory support durability limits:Five-year device lifespan ceilings create substitution pressure from heart transplantation and emerging xenotransplantation protocols.
Strategic Opportunities
- India's underserved heart failure population:CDSCO streamlined medical device registration and PLI scheme manufacturing incentives open access to 1.4 million annual cardiovascular mortality cases.
- Wireless monitoring-AI convergence:Machine learning algorithms embedded in implantable cardiac monitors enable predictive arrhythmia intervention before decompensation.
- Brazil's ANVISA regulatory harmonization:Mutual recognition agreements with FDA and EMA reduce redundant testing burdens for multinational manufacturers entering Latin America's largest healthcare market.
Industry Challenges
- Biomaterials toxicology expertise scarcity:Limited talent pools for polymer degradation kinetic modeling and chronic inflammation assessment constrain R&D throughput.
- ISO 10993-18 chemical characterization backlog:Third-party testing laboratory capacity shortages delay regulatory submission packages for novel scaffold compositions.
- Hospital IT integration complexity:Legacy electronic health record architectures resist seamless incorporation of real-time cardiac implant data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Restoration Systems Market |
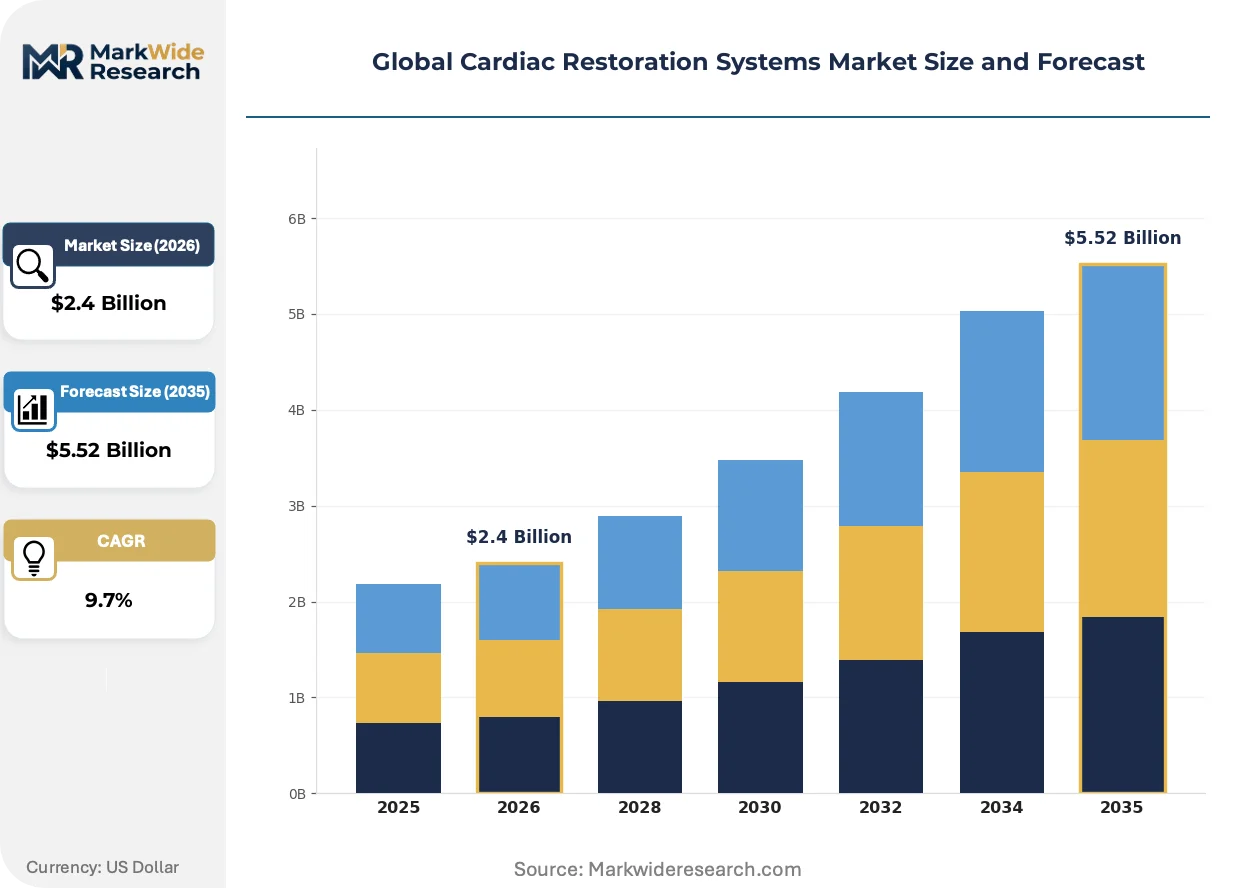
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventricular Assist Devices, Artificial Hearts, Cardiac Patches, Biodegradable Stents, Cardiac Resynchronization Therapy Devices Technology: 3D Printing, Bioabsorbable Materials, Stem Cell Therapy, Electrotherapy, Wireless Monitoring Application: Heart Failure Treatment, Myocardial Infarction Repair, Arrhythmia Management, Valve Regeneration, Tissue Engineering End User: Cardiovascular Clinics, Research Institutes, Specialized Cardiac Hospitals, Rehabilitation Centers, Diagnostic Labs |
| Companies Covered | Abbott Laboratories, Edwards Lifesciences Corporation, Artivion, Inc., BioVentrix, Inc., ANCORA HEART, INC., NeoChord, Inc., Medtronic plc, Boston Scientific Corporation, AtriCure, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Restoration Systems Market Shifts & Advancements
Digital biomarker integration and regenerative material science are converging to redefine therapeutic endpoints in cardiac care, shifting success metrics from symptom management toward measurable myocardial functional recovery.
Electrospun polycaprolactone-gelatin composite scaffolds are absorbing market share in cardiac patch applications as specialized cardiac hospitals in Germany and Japan prioritize substrates that remodel into native extracellular matrix within 18-24 months. The technology eliminates permanent foreign body retention that drives late complications in polyester-based alternatives. Manufacturers embedding angiogenic growth factors within these matrices are capturing premium positioning in Bridge-to-Recovery protocols.
EU AI Act risk classification rules are extending compliance burdens to wireless cardiac monitoring systems that incorporate machine learning for arrhythmia prediction. Device manufacturers must now document algorithm training datasets and performance drift monitoring protocols alongside traditional hardware safety dossiers. US-based electrophysiology platforms face parallel FDA software-as-medical-device guidance requiring premarket submissions for AI-enabled diagnostic outputs.
Hospital procurement committees are consolidating vendor relationships around integrated diagnostic-to-therapy workflows rather than discrete device categories. Cardiac resynchronization therapy devices bundled with implantable hemodynamic monitors command preferential contracting terms against standalone product offerings. This concentration is most visible in US integrated delivery networks and German hospital federations where total cost-of-ownership models dominate capital allocation decisions.
Global Cardiac Restoration Systems Market Segmentation
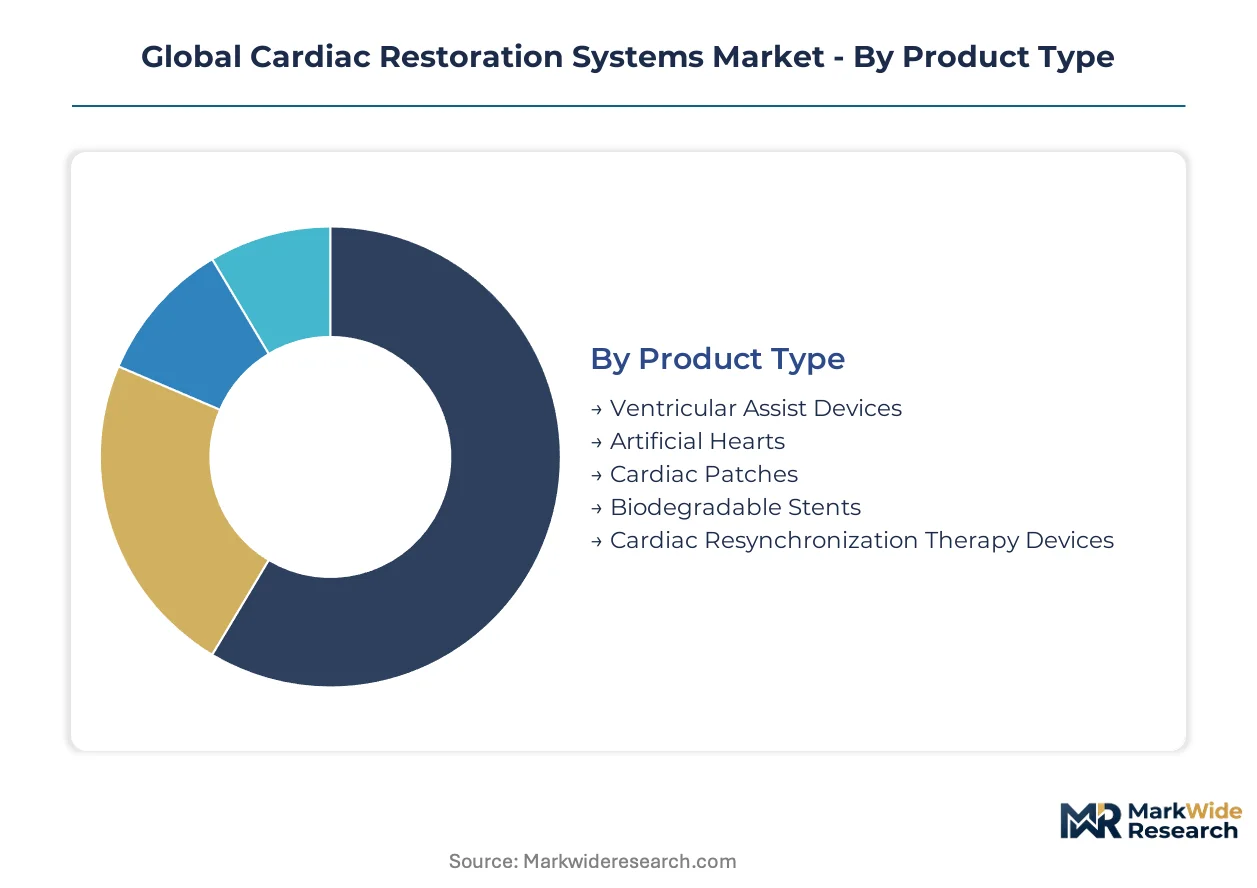
Cardiac restoration systems fragment across four intersecting dimensions that determine procurement patterns, reimbursement pathways, and manufacturing scale requirements. Product type and technology selections drive capital intensity, while application and end-user categories dictate regulatory complexity and clinical evidence standards.
Product Type:
Ventricular assist devices anchor volume procurement through established Bridge-to-Transplant protocols, while cardiac patches command premium pricing where patient-specific anatomical matching justifies higher reimbursement.
- Ventricular Assist Devices:Implantable mechanical pumps delivering 5–10 liters per minute blood flow via continuous-flow centrifugal or axial rotor designs. Demand concentrates in specialized cardiac hospitals across the United States and Germany where destination therapy reimbursement frameworks support multi-year implantation cycles.
- Cardiac Patches:Engineered scaffolds manufactured from electrospun polycaprolactone-gelatin composites or decellularized extracellular matrix, designed to restore ventricular wall integrity post-myocardial infarction. German and Japanese hospital federations prioritize these substrates for Bridge-to-Recovery protocols where bioresorption eliminates long-term foreign body complications.
- Artificial Hearts:Biventricular replacement systems with percutaneous power transfer and transcutaneous energy coils.
- Biodegradable Stents:Coronary scaffolds fabricated from poly-L-lactic acid or magnesium alloys that degrade within 12–24 months.
- Cardiac Resynchronization Therapy Devices:Biventricular pacemakers with left ventricular lead placement for dyssynchrony correction.
Today's leader: Ventricular Assist Devices. Tomorrow's challenger: Cardiac Patches.
Technology:
Electrotherapy and wireless monitoring dominate procedural volume through established implantation workflows, while bioabsorbable materials and stem cell platforms attract R&D investment for functional myocardial regeneration.
- Electrotherapy:Cardiac rhythm management via implantable pulse generators operating at 2–8 volts with hermetic titanium enclosures and platinum-iridium electrodes. Cardiovascular clinics in the United States and Japan deploy these systems for arrhythmia management where device longevity and battery replacement intervals determine total cost-of-ownership calculations.
- Wireless Monitoring:Implantable hemodynamic sensors with Bluetooth Low Energy or proprietary radiofrequency transmission to external receivers. Integrated delivery networks in Germany and the United States bundle these with resynchronization devices for predictive heart failure intervention before acute decompensation.
- 3D Printing:Additive manufacturing of patient-specific cardiac patches via extrusion or stereolithography of photocurable hydrogels.
- Bioabsorbable Materials:Degradable polymers including polycaprolactone, polyglycolic acid, and tyrosine-derived polycarbonates.
- Stem Cell Therapy:Autologous or allogeneic cardiomyocyte progenitor delivery via direct myocardial injection or scaffold seeding.
Volume concentration: Electrotherapy. Margin expansion: Wireless Monitoring.
Application:
Heart failure treatment absorbs the majority of device placements through chronic management protocols, whereas tissue engineering and valve regeneration represent emerging categories where regenerative endpoints command differentiated pricing.
- Heart Failure Treatment:Chronic mechanical circulatory support, resynchronization therapy, and hemodynamic monitoring for reduced ejection fraction patients. Specialized cardiac hospitals in Japan and the United States drive procedural volume where super-aging demographics and reimbursement expansion for destination therapy indications sustain implantation growth.
- Myocardial Infarction Repair:Acute post-infarction ventricular reconstruction via patch implantation or regenerative scaffold placement. German cardiovascular centers prioritize early intervention protocols where infarct zone remodeling prevents progressive dilated cardiomyopathy.
- Arrhythmia Management:Ablation, pacing, and defibrillation for atrial and ventricular rhythm disorders.
- Valve Regeneration:Percutaneous or surgical restoration of native valve function via tissue engineering or transcatheter repair.
- Tissue Engineering:In vitro cultivation of cardiac constructs for implantation or drug screening applications.
Established revenue base: Heart Failure Treatment. Steepest expansion trajectory: Tissue Engineering.
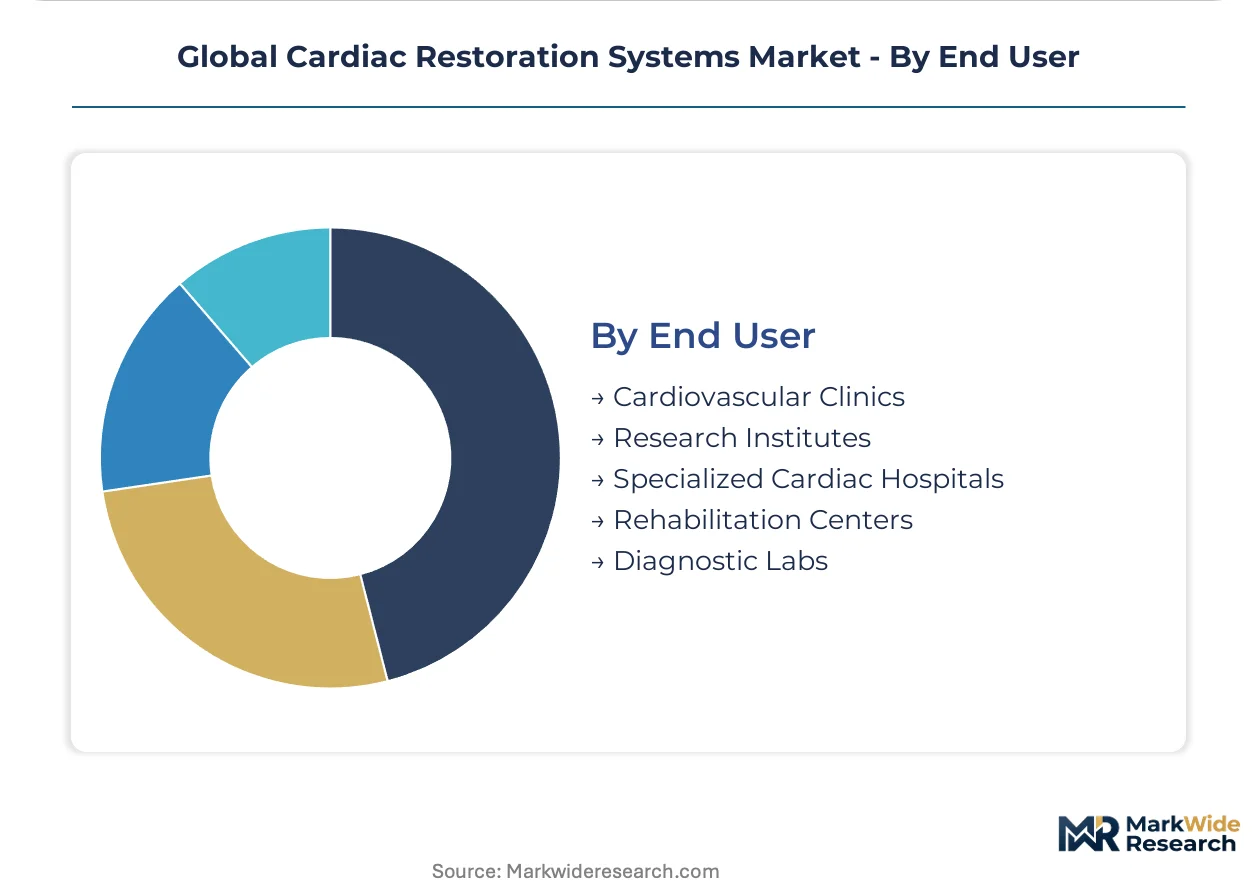
End User:
Specialized cardiac hospitals control premium device procurement through integrated diagnostic-to-therapy workflows, while cardiovascular clinics and rehabilitation centers concentrate volume for electrophysiological and monitoring applications.
- Specialized Cardiac Hospitals:Tertiary referral centers with catheterization laboratories, electrophysiology suites, and cardiothoracic surgical capabilities. United States and German hospital federations consolidate vendor relationships around bundled device contracts where total cost-of-ownership models favor integrated diagnostic-to-therapy platforms.
- Cardiovascular Clinics:Ambulatory facilities focused on diagnostic evaluation, device follow-up, and chronic disease management. Japanese and United States outpatient settings drive wireless monitoring adoption where remote patient management reduces emergency department utilization.
- Research Institutes:Academic medical centers and contract research organizations conducting clinical trials for regenerative therapies.
- Rehabilitation Centers:Post-acute facilities managing device optimization and patient conditioning.
- Diagnostic Labs:Imaging and biomarker testing facilities supporting pre-implantation assessment.
Procurement authority: Specialized Cardiac Hospitals. Volume growth: Cardiovascular Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic anchors global procedural innovation in cardiac restoration, with its destination therapy protocols influencing reimbursement frameworks worldwide. Specialized cardiac hospitals in Germany and Japan replicate these clinical pathways while adapting to local regulatory environments. Manufacturing scale concentrates where aging demographics intersect with established electrophysiology infrastructure.
United States
FDA Breakthrough Device Designation accelerates premarket review for ventricular assist devices and regenerative patches, compressing time-to-market for novel submissions. Destination therapy reimbursement expansion under CMS national coverage determinations sustains multi-year implantation cycles in tertiary centers. The Texas Medical Center and Cleveland Clinic clusters drive procedural volume through integrated diagnostic-to-therapy workflows.
Germany
EMA Medical Device Regulation conformity assessments govern bioabsorbable scaffold commercialization, with expanded biocompatibility surveillance extending approval timelines. Hospital federations in Baden-Württemberg and Bavaria consolidate vendor relationships around bundled device contracts where total cost-of-ownership models dominate capital allocation. Berlin and Heidelberg academic centers prioritize Bridge-to-Recovery protocols using electrospun polycaprolactone-gelatin composites.
Japan
METI reimbursement expansion for destination therapy indications drives procedural volume in specialized cardiac centers. PMDA regulatory harmonization with FDA pathways accelerates product registration for multinational manufacturers. The Tokyo-Osaka-Nagoya hospital clusters concentrate ventricular assist device placements where super-aging demographics sustain implantation growth.
India
CDSCO streamlined medical device registration and PLI scheme manufacturing incentives open access to underserved heart failure populations. The country's national pharmaceutical regulator aligns with ISO 13485 quality management standards for implantable device approval. Maharashtra and Karnataka medical device manufacturing corridors attract contract manufacturing for bioabsorbable polymer scaffolds.
Brazil
ANVISA regulatory harmonization through mutual recognition agreements with FDA and EMA reduces redundant testing burdens for market entry. The national health surveillance agency prioritizes electrophysiological device registration where hospital procurement committees favor established multinational suppliers. São Paulo and Rio de Janeiro cardiac centers concentrate Bridge-to-Transplant procedural volume.
Global Cardiac Restoration Systems Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand from discrete device categories into integrated diagnostic-to-therapy platforms. The vendor base stratifies across three tiers: diversified medical technology conglomerates with electrophysiology scale, specialized cardiac surgery device manufacturers, and emerging regenerative medicine platforms. Strategic archetypes include integrated workflow bundlers, patient-specific manufacturing specialists, and bioabsorbable materials innovators. M&A activity and technology licensing agreements represent the dominant competitive moves, with manufacturers acquiring polymer degradation expertise and wireless monitoring algorithms.
Among diversified medical technology conglomerates, Abbott Laboratories, Medtronic plc, and Edwards Lifesciences Corporation exemplify the integrated workflow archetype. Abbott Laboratories occupies a position spanning diagnostic-to-therapy platforms. Medtronic plc represents broad manufacturing scale across electrotherapy and monitoring segments. Edwards Lifesciences Corporation anchors premium positioning in structural heart applications. These three entities sit within the tier that commands preferential contracting terms from US integrated delivery networks and German hospital federations.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Artivion, Inc. |
| BioVentrix, Inc. |
| ANCORA HEART, INC. |
| NeoChord, Inc. |
| Medtronic plc |
| Boston Scientific Corporation |
| AtriCure, Inc. |
| Others |
Supply & Pricing Matrix
Bioabsorbable polymer manufacturing transitions are compressing production economics while concentrating supply leverage among specialized chemical producers in Germany and Japan. These substrate shifts simultaneously elevate R&D amortization burdens and reduce per-unit material costs as scale efficiencies emerge in electrospun scaffold production.
Pricing Analysis
Platinum-iridium electrode cost pass-through from South African and Russian mining operations directly pressures electrophysiological device margins. Pricing stratifies across premium, standard, and economy tiers where FDA Breakthrough Device Designation commands certification premiums against standard CE-marked alternatives. Cost compression in standard-tier ventricular assist devices is intensifying because German hospital federations consolidate procurement around total cost-of-ownership models. Cardiovascular clinics exhibit highest price sensitivity due to reimbursement constraints, while specialized cardiac hospitals absorb premium positioning for patient-specific cardiac patches.
Supply Chain Analysis
Polycaprolactone and polyglycolic acid supply rests on German and Japanese specialty chemical producers with limited qualified alternatives. Raw material dependencies span platinum-iridium alloys for electrodes, hermetic titanium enclosures, and tyrosine-derived polycarbonates for bioabsorbable matrices. Single-source vulnerability in electrospun scaffold precursor chemicals exposes manufacturers to regulatory restriction risks under REACH and ECHA substance authorization protocols. Distribution runs through specialized cardiac hospital procurement committees and cardiovascular clinic group purchasing organizations with consolidated vendor contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where demand is concentrating toward patient-specific anatomical matching and bioabsorbable material specifications that command durable pricing power.
For Market Incumbents: Acquire polymer degradation kinetic modeling capabilities to defend against emerging regenerative medicine platforms. Secure backward integration into electrospun scaffold precursor supply through captive production facilities in Baden-Württemberg or Bavaria manufacturing corridors. Hospital IT integration complexity and ISO 10993-18 testing backlogs threaten incumbent throughput advantages without direct biomaterials toxicology expertise control.
For New Entrants and Emerging Players: Launch via direct-to-specialized-cardiac-hospital contracting models bypassing legacy GPO relationships. Target India's underserved heart failure population where CDSCO streamlined registration and PLI scheme incentives reduce barrier-to-entry against established multinational suppliers. Wireless monitoring-AI convergence applications in Japanese cardiovascular clinics offer the most penetrable white-space for algorithm-native entrants without hardware manufacturing heritage.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap bioabsorbable materials specialists with EMA MDR dossiers in progress but pre-revenue commercial scale. Long-term viability over the next decade hinges on successful Bridge-to-Recovery protocol adoption displacing permanent mechanical circulatory support. Watch FDA software-as-medical-device guidance enforcement intensity as inflection indicator for AI-enabled cardiac monitor platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerated review compresses time-to-market for novel bioabsorbable scaffolds against standard PMA pathways. |
| Hospital System Partnership | Bundled diagnostic-to-therapy contracts with Cleveland Clinic or Texas Medical Center clusters secure preferential procurement positioning. |
| CE Marking Pathway Investment | EMA MDR conformity assessment preparation prevents approval timeline extension beyond manufacturing scale-up capacity. |
| Software Companion Development | AI-enabled arrhythmia prediction algorithms embedded in implantable monitors trigger EU AI Act risk classification compliance requirements. |
| Reimbursement Strategy | CMS national coverage determination alignment for destination therapy indications sustains multi-year implantation cycle economics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned biomedical engineers at specialized cardiac hospitals, GPO contracts managers, regulatory affairs leads at scaffold manufacturers, and clinicians managing Bridge-to-Transplant protocols. Secondary validation drew from FDA premarket approval databases, EMA MDR submission records, hospital procurement contracts, and CMS Medicare reimbursement filings. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored market size estimation.
Segment-weighting approaches distributed value across product type, technology platform, application indication, and end-user facility tier. Modeled dimensions included electrotherapy versus regenerative material science, specialized cardiac hospital versus cardiovascular clinic procurement authority, and Bridge-to-Transplant versus Bridge-to-Recovery clinical protocols. CAGRs were derived from procedural volume trajectories and pricing evolution assumptions across the projection horizon. Forecast inputs incorporated METI reimbursement expansion schedules and PMDA-FDA harmonization pathway progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA MDR clinical evidence requirement tightening or platinum-iridium supply disruption scenarios. Projections reflect documented assumptions regarding bioabsorbable scaffold adoption curves and wireless monitoring penetration rates. Regulatory submission delays, biomaterials toxicology expertise scarcity, and xenotransplantation protocol advancement warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market