
 Rheumatic-Heart Disease Management Market | 2026-2036
Rheumatic-Heart Disease Management Market Size, Share, and Industry Trends Forecast 2026-2036
Rheumatic-Heart Disease Management Market Analytics
The WHO resolution on rheumatic heart disease elimination is decoupling treatment access from pure commercial pharmaceutical channels and embedding penicillin prophylaxis into national immunization-style programs. Pfizer leverages its long-standing benzathine penicillin manufacturing scale to supply these bulk procurement schemes across endemic regions. Novartis anchors its position through cardiovascular portfolio breadth spanning secondary prophylaxis to advanced heart failure management. Johnson & Johnson competes in surgical intervention through its suture and mechanical valve product lines serving cardiac surgery centers in Africa and South Asia.
Rheumatic-Heart Disease Management encompasses the clinical protocols, pharmaceutical interventions, surgical procedures, and longitudinal monitoring systems used to prevent, treat, and mitigate complications from rheumatic fever-induced valvular damage, with penicillin-based secondary prophylaxis representing the cornerstone pharmacological specification requiring intramuscular administration every three to four weeks. The primary commercial purpose centers on reducing progression to severe valvular disease, heart failure, and premature mortality in predominantly young populations across low- and middle-income settings. Medications dominate current value generation through sustained benzathine penicillin demand and emerging adjunctive therapies, while surgical devices capture concentrated margin pools in tertiary referral centers performing valve repair and replacement. Diagnostic tools represent the fastest-growing structural segment as echocardiography-based screening programs expand to detect subclinical disease in school-aged populations.
FDA standards for cardiovascular device safety, WHO Essential Medicines List inclusion criteria for penicillin formulations, and national regulatory frameworks in endemic countries collectively shape product registration pathways and procurement eligibility for rheumatic heart disease interventions. EMA guidelines on antibiotic manufacturing quality and pharmacovigilance requirements influence supplier qualification for international tender programs serving endemic regions. Stakeholders must monitor how domestic manufacturing incentives and local production mandates in high-burden countries reshape supply chain configurations and intellectual property access terms for essential cardiac medicines.
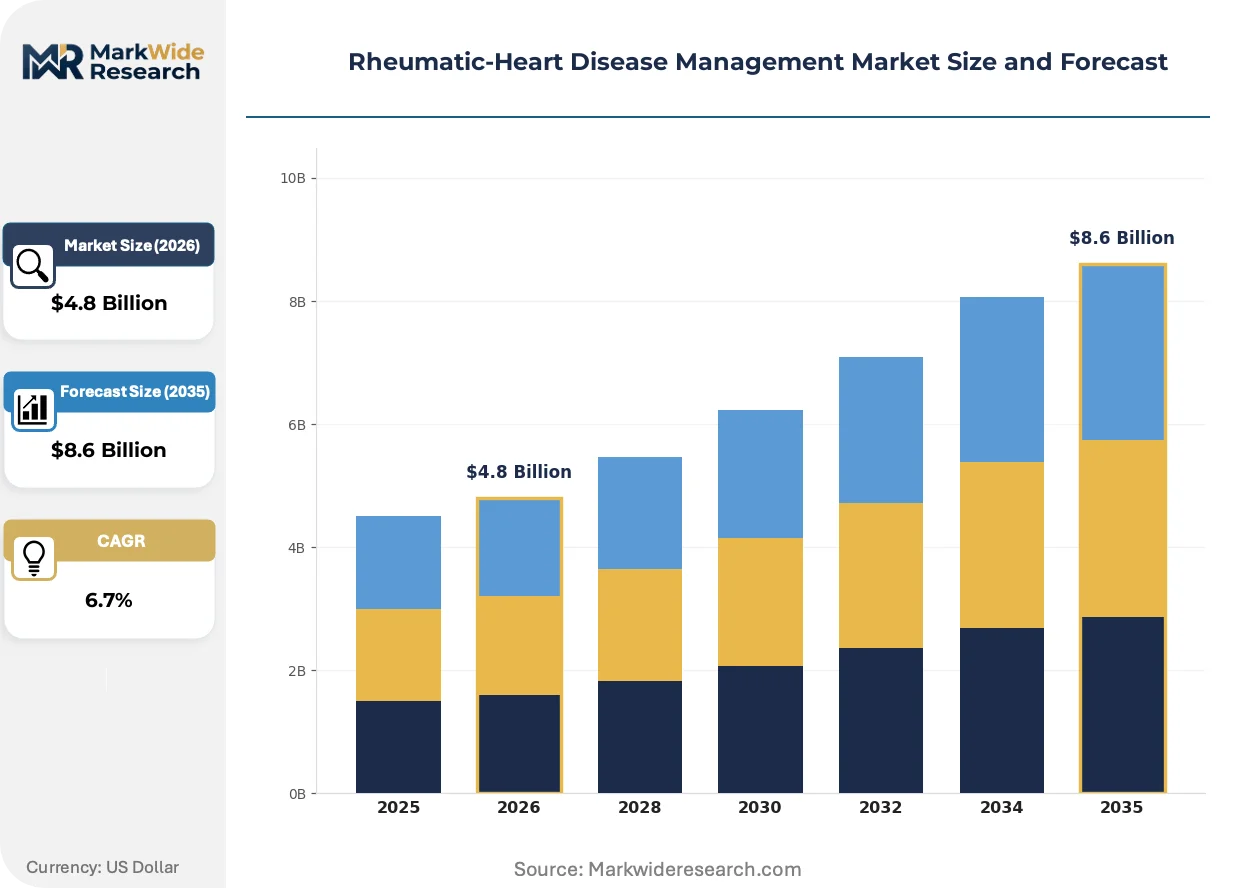
Market Dynamics
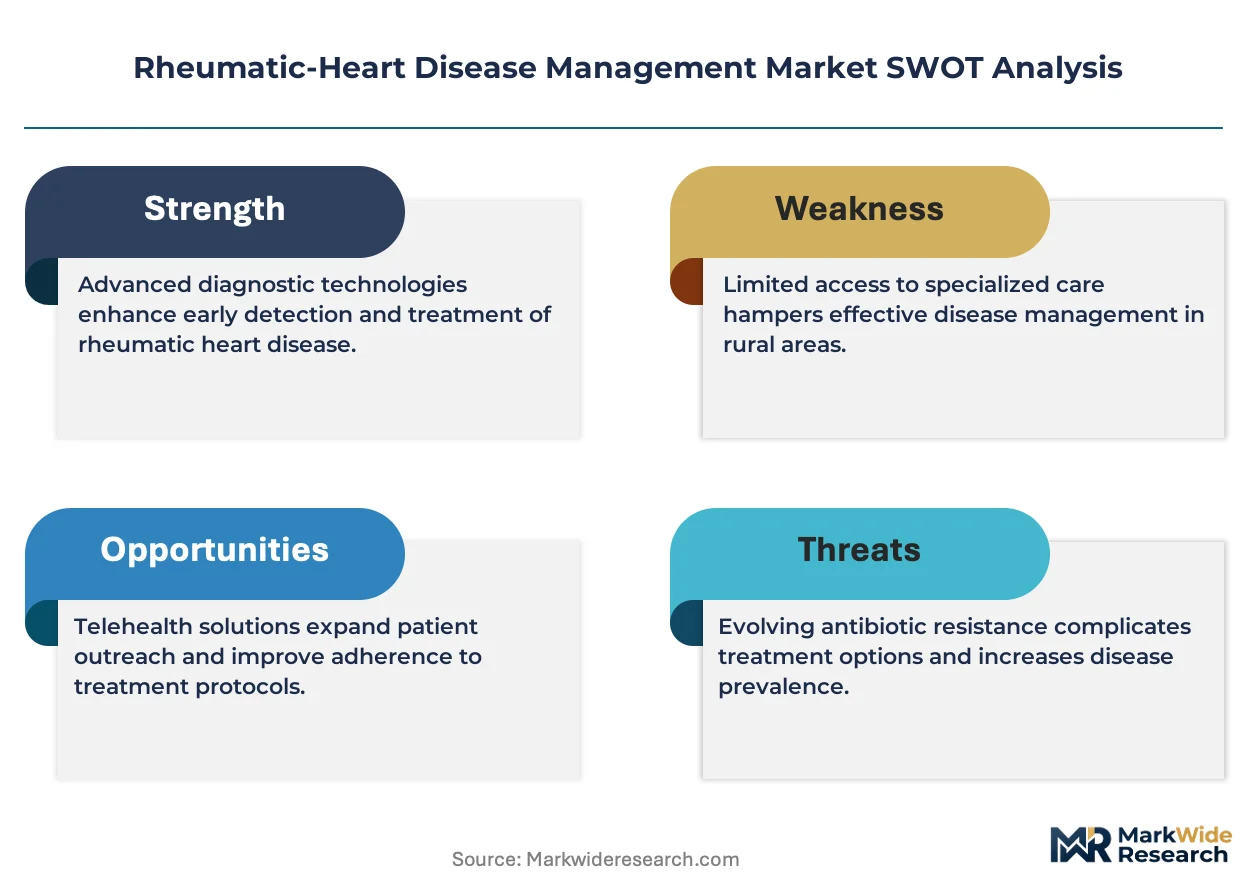
Penicillin supply concentration and WHO Essential Medicines List procurement mandates are restructuring competitive access in rheumatic heart disease management, embedding long-acting antibiotic prophylaxis into national health system infrastructure across endemic regions.
Growth Catalysts
- WHO Resolution WHA71.14:The 2018 resolution commits member states to eliminate rheumatic heart disease through coordinated secondary prophylaxis programs, embedding benzathine penicillin into routine immunization-style delivery systems.
- Point-of-care echocardiography:Portable ultrasound devices enable school-based screening in Uganda, Kenya, and Fiji, expanding case detection beyond tertiary cardiac centers into primary health networks.
- India's state cardiac surgery networks:Government-funded valve repair programs in Tamil Nadu, Kerala, and Maharashtra create sustained surgical device demand and structured referral pathways for advanced disease.
Market Restraints
- Benzathine penicillin supply fragility:Manufacturing concentrates among three qualified suppliers globally, creating vulnerability to stockouts when any single facility faces quality compliance actions.
- Cold chain requirements:Intramuscular penicillin formulations require 2-8°C storage through last-mile distribution, complicating deployment in rural Ethiopia and northern Nigeria where refrigeration infrastructure remains sparse.
- Cardiac surgeon density:Sub-Saharan Africa operates below 0.5 cardiothoracic surgeons per million population, constraining surgical intervention capacity regardless of device availability or funding.
Strategic Opportunities
- Oral streptococcus vaccine development:Group A streptococcal vaccine candidates in Phase II trials offer primary prevention potential that would displace decades-long secondary prophylaxis dependency.
- Tele-echocardiography networks:Cloud-connected handheld ultrasound enables remote specialist interpretation in Pacific Island nations, extending diagnostic reach without deploying cardiologists to each atoll.
- India's PLI scheme for pharmaceuticals:Production-linked incentives for active pharmaceutical ingredient manufacturing could shift benzathine penicillin supply toward domestic Indian production, reducing import dependency.
Industry Challenges
- Community health worker training:Intramuscular injection administration requires supervised competency certification, yet workforce turnover in rural Mozambique and Zambia erodes program continuity.
- Valve repair skill transfer:Rheumatic valve repair techniques demand specialized training distinct from degenerative valve surgery, with limited fellowship pathways in African and South Asian surgical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rheumatic-Heart Disease Management Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Devices, Diagnostic Tools, Rehabilitation Services End User: Cardiology Clinics, Hospitals, Home Care Settings, Rehabilitation Centers Treatment Method: Medication Therapy, Surgical Intervention, Regular Monitoring, Lifestyle Modification Age Group: Pediatrics, Adolescents, Adults, Geriatrics |
| Companies Covered | F. Hoffmann-La Roche, Pfizer, Abbott Laboratories, Johnson & Johnson, GlaxoSmithKline, Novartis, AstraZeneca, Eli Lilly and Company, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rheumatic-Heart Disease Management Market Evolving Landscape
Digital diagnostic platforms and decentralized care models are compressing the pathway from disease detection to treatment initiation, while regulatory harmonization efforts streamline essential medicine registration across endemic regions.
Handheld echocardiography is decentralizing rheumatic heart disease screening from hospital-based pediatric cardiology departments to school health programs and primary care clinics. Ministries of health in Fiji and Samoa deploy these devices through nurse-led screening campaigns. This technology is compressing the interval between subclinical valve damage detection and prophylaxis initiation from months to weeks.
EMA's updated guidelines on antibiotic pharmacovigilance and batch release testing are elevating documentation requirements for suppliers to international tender programs. Manufacturers serving WHO-prequalified procurement channels must now submit enhanced stability data and post-market surveillance reports. African national regulatory agencies are aligning domestic registration requirements with these EMA standards, accelerating qualified supplier consolidation.
Community-based adherence support programs are displacing facility-centric prophylaxis delivery in high-burden settings. Village health teams in Uganda and community health workers in Brazil now track injection schedules through mobile health applications, replacing paper-based appointment systems. This shift is most visible in rural districts where transportation barriers previously drove 40-percent dropout from secondary prophylaxis regimens.
Rheumatic-Heart Disease Management Market Segmentation
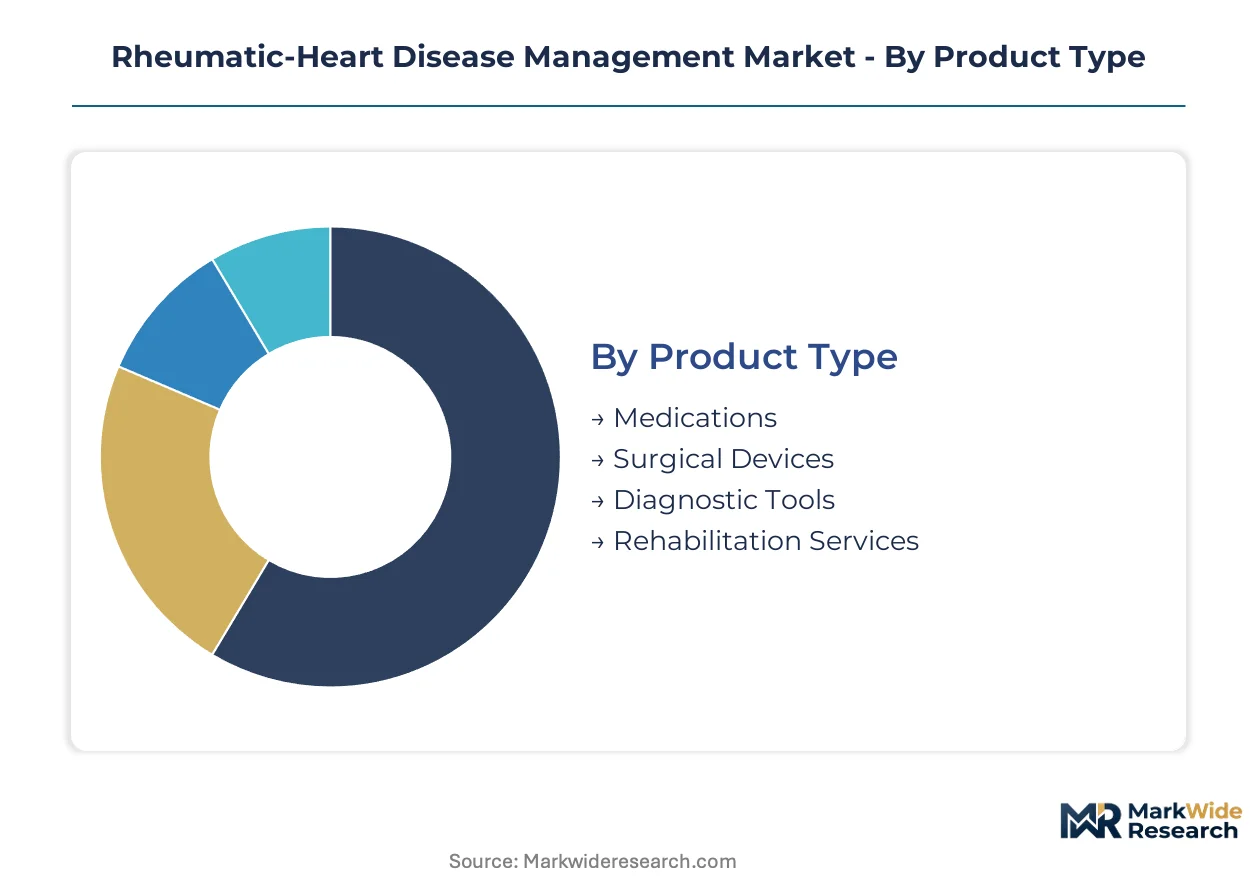
Rheumatic heart disease management requires coordinated interventions spanning prevention, acute treatment, and lifelong monitoring. Segmentation reveals how pharmaceutical supply chains, surgical capacity constraints, and diagnostic technology deployment shape competitive positioning across endemic regions.
Product Type:
Supply concentration in benzathine penicillin manufacturing dominates value capture, while device segments fragment across specialized cardiac centers.
- Medications:Benzathine penicillin G constitutes the backbone of secondary prophylaxis, requiring intramuscular administration every three to four weeks to prevent recurrent streptococcal infections. Procurement concentrates in India, where government-funded national programs absorb bulk volumes for pediatric and young adult populations. Cold chain requirements and WHO prequalification standards limit qualified suppliers to three global manufacturers.
- Surgical Devices:Mechanical valves, annuloplasty rings, and suture systems serve tertiary cardiac surgery centers performing valve repair and replacement. Demand clusters in Tamil Nadu, Kerala, and Maharashtra, where India's state-funded cardiac surgery networks create sustained procurement volumes. Surgeon density constraints in Sub-Saharan Africa suppress addressable market expansion regardless of device availability.
- Diagnostic Tools:Echocardiography systems and handheld ultrasound devices enable subclinical disease detection in school-based screening programs.
- Rehabilitation Services:Cardiac rehabilitation protocols support post-surgical recovery and heart failure management in structured program settings.
Medications absorb the bulk of installed capacity; Diagnostic Tools are expanding most quickly.
End User:
Facility type determines reimbursement pathways, referral complexity, and the feasible intensity of longitudinal patient management.
- Hospitals:Tertiary cardiac centers manage advanced valvular disease, surgical intervention, and complex heart failure cases. India's state-level cardiac surgery networks and academic medical centers in South Africa anchor device demand and specialist training pipelines.
- Cardiology Clinics:Urban specialty clinics coordinate secondary prophylaxis initiation and echocardiography-based disease monitoring.
- Home Care Settings:Community health worker programs in Uganda and Brazil now administer intramuscular penicillin and track adherence through mobile health applications.
- Rehabilitation Centers:Structured cardiac rehabilitation facilities support functional recovery following surgical intervention.
Hospitals command the highest per-patient revenue intensity; Home Care Settings are climbing the fastest as decentralized delivery models displace facility-centric care.
Treatment Method:
Method selection follows disease stage progression, with pharmaceutical prophylaxis dominating early-stage management and surgical intervention capturing advanced cases.
- Medication Therapy:Secondary prophylaxis with benzathine penicillin prevents recurrent rheumatic fever and disease progression. WHO Essential Medicines List procurement mandates and national immunization-style programs in Fiji, Samoa, and India embed this method into routine health system infrastructure.
- Surgical Intervention:Valve repair and replacement procedures address severe valvular damage, with mechanical valve implantation preferred in younger patients.
- Regular Monitoring:Echocardiography-based surveillance tracks disease progression and guides prophylaxis continuation decisions.
- Lifestyle Modification:Patient education and secondary prevention counseling complement pharmaceutical interventions.
Medication Therapy accounts for the greatest patient volume; Surgical Intervention generates the highest per-procedure margin contribution.
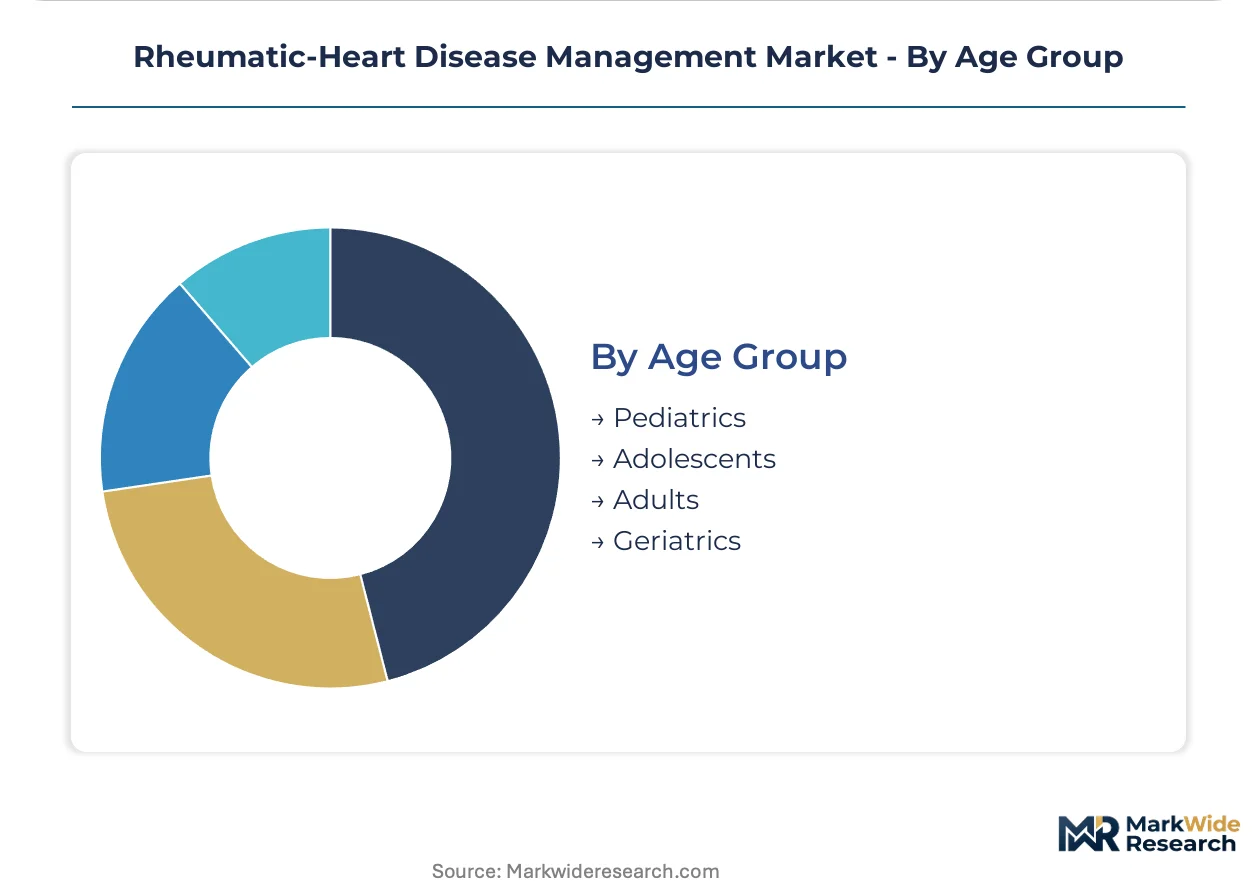
Age Group:
Disease burden concentrates in younger populations, with clinical presentation and intervention strategy varying sharply across developmental stages.
- Pediatrics:School-aged children represent the primary target for screening programs and secondary prophylaxis initiation. Uganda, Kenya, and Fiji deploy handheld echocardiography through nurse-led school health campaigns to detect subclinical valve damage.
- Adolescents:Transition-age youth require adherence support as they assume self-management responsibility for injection schedules.
- Adults:Young adults in endemic regions often present with established valvular damage requiring surgical evaluation.
- Geriatrics:Older patients with long-standing disease may develop heart failure requiring complex medical management.
Pediatrics captures the dominant share of screening and prophylaxis program investment; Adolescents present the steepest adherence challenge and intervention dropout risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chennai anchors surgical capacity expansion through Tamil Nadu's state-funded cardiac surgery network, while Mumbai's pharmaceutical corridor supplies benzathine penicillin across endemic regions.
India
State cardiac surgery networks in Tamil Nadu, Kerala, and Maharashtra generate sustained device demand for valve repair procedures. CDSCO regulates benzathine penicillin manufacturing quality under WHO prequalification alignment. Mumbai's pharmaceutical cluster hosts active pharmaceutical ingredient production expanding under PLI scheme incentives.
Brazil
Community health worker programs in São Paulo and Minas Gerais administer intramuscular penicillin through mobile health tracking systems. ANVISA oversees import licensing for cardiac surgical devices serving public hospital networks. Rio de Janeiro's tertiary cardiac centers anchor valve replacement surgery capacity for the Southeast region.
Uganda
School-based screening campaigns deploy handheld echocardiography through nurse-led health teams in Kampala and surrounding districts. The national pharmaceutical authority coordinates cold chain distribution for penicillin prophylaxis programs. Mulago National Referral Hospital concentrates surgical expertise for advanced valvular cases.
Fiji
Pacific Island health ministries integrate rheumatic heart disease elimination into national immunization-style delivery systems. WHO technical guidance shapes procurement standards for benzathine penicillin tenders. Suva's colonial-era hospital infrastructure supports regional cardiac surgery referrals from Samoa and Tonga.
South Africa
Academic medical centers in Cape Town and Johannesburg train cardiothoracic surgeons for Sub-Saharan referral networks. The national health department embeds secondary prophylaxis into primary care protocols. Groote Schuur Hospital pioneers rheumatic valve repair techniques adapted for resource-limited settings.
Rheumatic-Heart Disease Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across manufacturing scale and regulatory qualification tiers. Three qualified suppliers dominate benzathine penicillin production globally, creating concentrated supply-side control. Strategic archetypes span multinational pharmaceutical manufacturers with cardiovascular portfolios, specialized cardiac device suppliers, and diagnostic technology developers. Competitive moves center on manufacturing capacity expansion for WHO prequalification and strategic partnerships with national procurement programs.
Within the multinational pharmaceutical tier, Pfizer and Novartis occupy positions shaped by manufacturing scale and cardiovascular portfolio breadth. Pfizer anchors benzathine penicillin supply chains through established production infrastructure serving endemic regions. Novartis represents portfolio diversification across secondary prophylaxis coordination and advanced heart failure management pathways.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Pfizer |
| Abbott Laboratories |
| Johnson & Johnson |
| GlaxoSmithKline |
| Novartis |
| AstraZeneca |
| Eli Lilly and Company |
| Bayer |
| Others |
Value Network & Pricing Analysis
Benzathine penicillin active pharmaceutical ingredient costs cascade through WHO prequalification tiers into national procurement contracts, with cold chain logistics expenses layering atop manufacturing premiums to stratify final delivered prices across endemic regions.
Pricing Analysis
Outcome-linked procurement contracts anchor pricing to patient adherence rates and stockout prevention guarantees rather than pure unit volume. Three-tier pricing structure across WHO-prequalified, nationally registered, and non-registered supplier tiers reflects certification grade and batch release documentation depth. Cost compression in economy-tier penicillin is intensifying because Indian domestic manufacturers leverage PLI scheme subsidies to undercut import landed costs. Government procurement officers in high-burden countries exhibit acute price sensitivity, while tertiary cardiac centers purchasing surgical devices prioritize reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from WHO and national regulators require qualified suppliers to maintain redundant manufacturing lines across India, Italy, and the United States. Benzathine penicillin production draws from fermentation-derived 6-aminopenicillanic acid, specialized sterile filling capacity, and temperature-controlled packaging materials. Single-source vulnerability concentrates in the final sterile injectable finishing stage, where only two facilities hold concurrent WHO and EMA approvals. Distribution runs through government medical stores in endemic countries, with last-mile cold chain deployment via district health offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side manufacturing capacity constraints prop pricing power for qualified benzathine penicillin suppliers, creating durable margin pools even as procurement volumes expand under WHO elimination targets.
For Market Incumbents: Hedge against oral streptococcal vaccine displacement by deepening backward integration into penicillin API production in India under PLI scheme incentives. Secure exclusive supply agreements with state cardiac surgery networks before domestic device manufacturers achieve CDSCO quality certification. Prioritize cold chain infrastructure partnerships in Ethiopia and northern Nigeria to lock in last-mile distribution control. For New Entrants and Emerging Players: Handheld echocardiography with cloud-connected interpretation offers entry into Uganda's school-based screening programs, where incumbent device makers lack localized service networks. Target Pacific Island ministries of health in Fiji and Samoa pursuing tele-echocardiography networks without deploying cardiologists to each atoll. Pursue joint development agreements with community health worker platforms in Brazil to embed diagnostic tools into mobile health tracking systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap cardiac device specialists with established surgeon training pipelines in Tamil Nadu and Kerala. Long-term viability rests on valve repair technique differentiation rather than mechanical valve commodity positioning. Watch Group A streptococcal vaccine Phase III trial readouts as the signal to assess secondary prophylaxis market displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks access to government-funded penicillin tenders across endemic regions. |
| Domestic API Manufacturing Scale-Up | CDSCO-aligned production in Mumbai corridor reduces import dependency under PLI incentives. |
| Tele-Echocardiography Platform Integration | Extends diagnostic reach in Pacific Island nations without specialist deployment. |
| Surgeon Training Fellowship Expansion | Builds valve repair capacity in Groote Schuur Hospital network across Sub-Saharan Africa. |
| Community Health Worker Partnership | Secures adherence tracking infrastructure in Uganda and Brazil mobile health ecosystems. |
Research Methodology
Independent corroboration across procurement officers at India's state cardiac surgery networks, CDSCO regulatory affairs specialists, and WHO Essential Medicines List technical officers underwrites the qualitative findings. Primary interviews with hospital purchasing committees, biomedical engineers at Mulago National Referral Hospital, and GPO contracts managers complemented secondary validation through FDA filings, EMA antibiotic manufacturing guidance, ClinicalTrials.gov vaccine trial registries, and national health department procurement databases. Bottom-up patient volume estimates triangulated against top-down pharmaceutical consumption data from customs records and WHO prequalification supply reports.
Comparable historical periods anchored the projection horizon to pre-pandemic baselines and post-resolution implementation trajectories. The analytical framework modeled segmentation across product type, end user facility tier, treatment method, and age group, with regional regulatory cluster as an additional dimension. CAGRs derived from spline interpolation between anchor points, incorporating benzathine penicillin stockout frequency data and echocardiography deployment rates as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including Group A streptococcal vaccine regulatory approval timelines and geopolitical disruptions to cold chain infrastructure. Forecasts reflect assumptions about sustained WHO funding commitments and national immunization-style program continuity. Deviation in penicillin manufacturing facility compliance actions or vaccine trial efficacy readouts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Cardiac Rhythm Management Market