
 Global Cardiac Monitoring Market | 2026-2036
Global Cardiac Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Monitoring Market Foresight
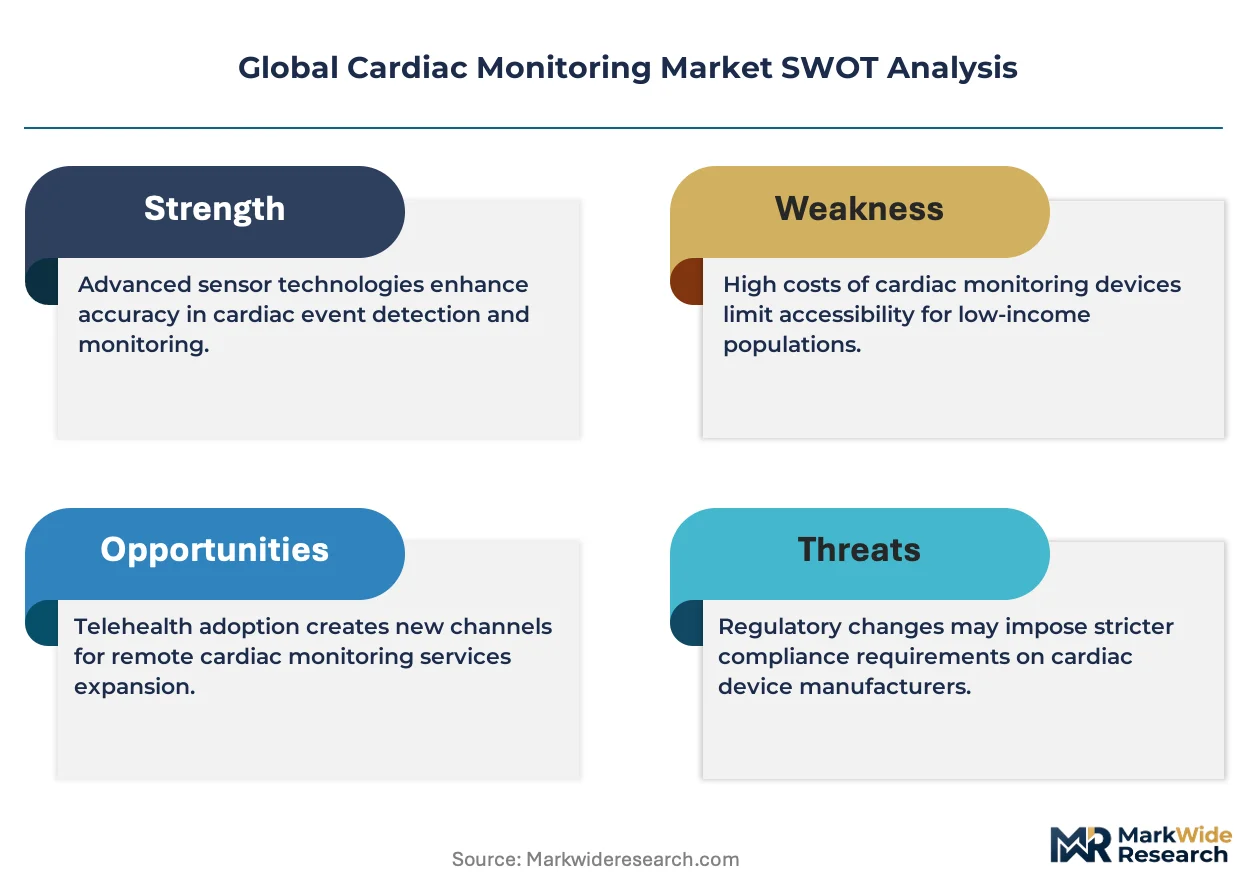
Buyer concentration among integrated hospital networks is hardening as health systems consolidate purchasing decisions across multiple facilities. Medtronic leverages its implanted device portfolio to anchor long-term service contracts with these consolidated buyers. Abbott competes through wearable ECG specialization that appeals to outpatient-focused delivery models. GE Healthcare sustains diagnostic equipment relationships that extend into cardiac monitoring adjacencies.
Cardiac monitoring encompasses systems that capture, record, and transmit electrical and hemodynamic cardiac data through surface electrodes, implanted sensors, or optical transducers, typically sampling at 250-1000 Hz for diagnostic-grade resolution. These systems serve the clinical purpose of detecting rhythm disturbances, ischemic events, and hemodynamic deterioration before irreversible damage occurs. Mobile cardiac telemetry and wearable ECG devices represent the fastest-expanding product categories as reimbursement shifts favor outpatient surveillance over inpatient observation. Electrocardiography technology dominates installed base value while photoplethysmography gains ground in consumer-accessible applications. Telemedicine providers constitute the most rapidly growing end-user channel as remote patient monitoring programs mature.
The FDA's cybersecurity premarket guidance and the EU MDR's clinical evidence requirements for active implantable devices shape product development timelines and market access conditions. Japan's PMDA streamlines approval pathways for AI-integrated diagnostics, creating regulatory arbitrage opportunities for algorithm-enabled monitoring systems. Stakeholders must weigh capital allocation between implanted hardware platforms and software-centric remote monitoring services as payment models continue fragmenting across geographies.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing vendor margins while elevating service contract value. The FDA's 2023 cybersecurity premarket guidance for connected medical devices is forcing manufacturers to reallocate R&D budgets toward software validation and post-market surveillance infrastructure.
Growth Catalysts
- Japan's PMDA AI diagnostic pathway:Streamlined approval for algorithm-integrated cardiac monitors accelerates commercialization timelines for machine-learning-enabled arrhythmia detection systems.
- Ambulatory surgical centers:Medicare reimbursement expansion for outpatient cardiac telemetry is redirecting capital expenditure from inpatient telemetry beds toward portable monitoring platforms.
- Photoplethysmography miniaturization:Optical sensor integration into consumer wearables is expanding addressable patient populations beyond clinically diagnosed cardiac patients.
Market Restraints
- EU MDR clinical evidence burden:Active implantable device classification demands extended follow-up studies, stretching regulatory timelines for new pacemaker-integrated monitors.
- Semiconductor foundry concentration:Taiwan-based fabrication capacity constraints create supply vulnerability for application-specific integrated circuits powering implantable loop recorders.
- Bluetooth Low Energy interference:Unlicensed spectrum congestion in hospital environments degrades real-time data transmission reliability for wireless patch monitors.
Strategic Opportunities
- Germany's DiGA fast-track:Digital health application reimbursement creates immediate payment pathway for prescription-grade ECG smartphone apps.
- Telemedicine platform integration:Remote patient monitoring vendors seek embedded cardiac data streams to differentiate chronic disease management subscriptions.
- India's PLI medical device scheme:Production-linked incentives for domestic manufacturing reduce landed cost for entry-level Holter monitors targeting price-sensitive hospital chains.
Industry Challenges
- Firmware validation talent scarcity:FDA cybersecurity guidance demands specialized embedded software engineers capable of threat modeling for Class III device architectures.
- Legacy EHR interoperability:Proprietary data formats from incumbent monitoring systems resist seamless integration with cloud-native analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Monitoring Market |
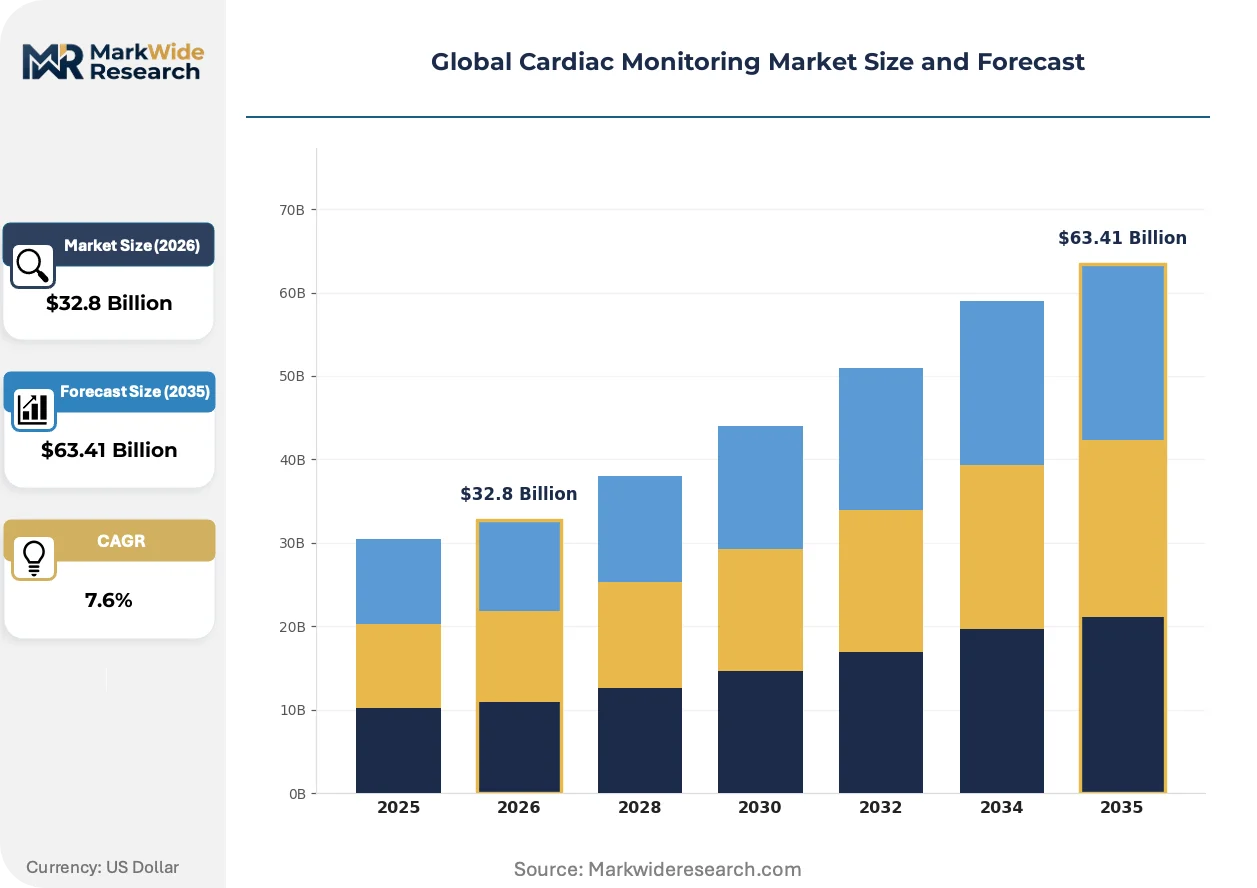
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $63.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitor, Event Monitor, Implantable Loop Recorder, Mobile Cardiac Telemetry, Wearable ECG Device Technology: Electrocardiography, Photoplethysmography, Ultrasound, Impedance Cardiography, Bioimpedance Analysis Application: Arrhythmia Detection, Ischemic Heart Disease Monitoring, Heart Failure Management, Blood Pressure Regulation, Sleep Apnea Monitoring End User: Cardiology Clinics, Diagnostic Laboratories, Specialized Medical Centers, Rehabilitation Facilities, Telemedicine Providers |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Koninklijke Philips NV, GE Healthcare, BIOTRONIK, iRhythm Technologies, ZOLL Medical Corporation, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Monitoring Market Shifts & Advancements
Cardiac monitoring hardware is dissolving into software-defined platforms where algorithm performance supersedes sensor specifications in purchasing decisions. This shift elevates data science capabilities alongside traditional device engineering.
Multi-lead ECG patch technology is converging with continuous blood pressure estimation algorithms. Cardiology departments in Germany and Japan are piloting these combined hemodynamic-rhythm monitors for post-discharge heart failure patients. The convergence is compressing the distinction between diagnostic and monitoring device categories, forcing vendors to recalibrate regulatory submission strategies.
The FDA's updated cybersecurity premarket guidance mandates software bill of materials disclosure and vulnerability management plans for all network-connected cardiac devices. Manufacturers must now embed over-the-air update capabilities and documented threat mitigation protocols. Implantable device portfolios face the steepest compliance burden given their 10-15 year field lifespans.
Integrated delivery networks are consolidating cardiac monitoring procurement across multiple facilities under centralized value analysis committees. This concentration shifts negotiation leverage toward multi-year service agreements encompassing device provision, remote monitoring staffing, and outcomes accountability. The United States exhibits the most advanced form of this purchasing transformation, with several hundred-hospital systems standardizing on single-vendor telemetry platforms.
Global Cardiac Monitoring Market Segmentation
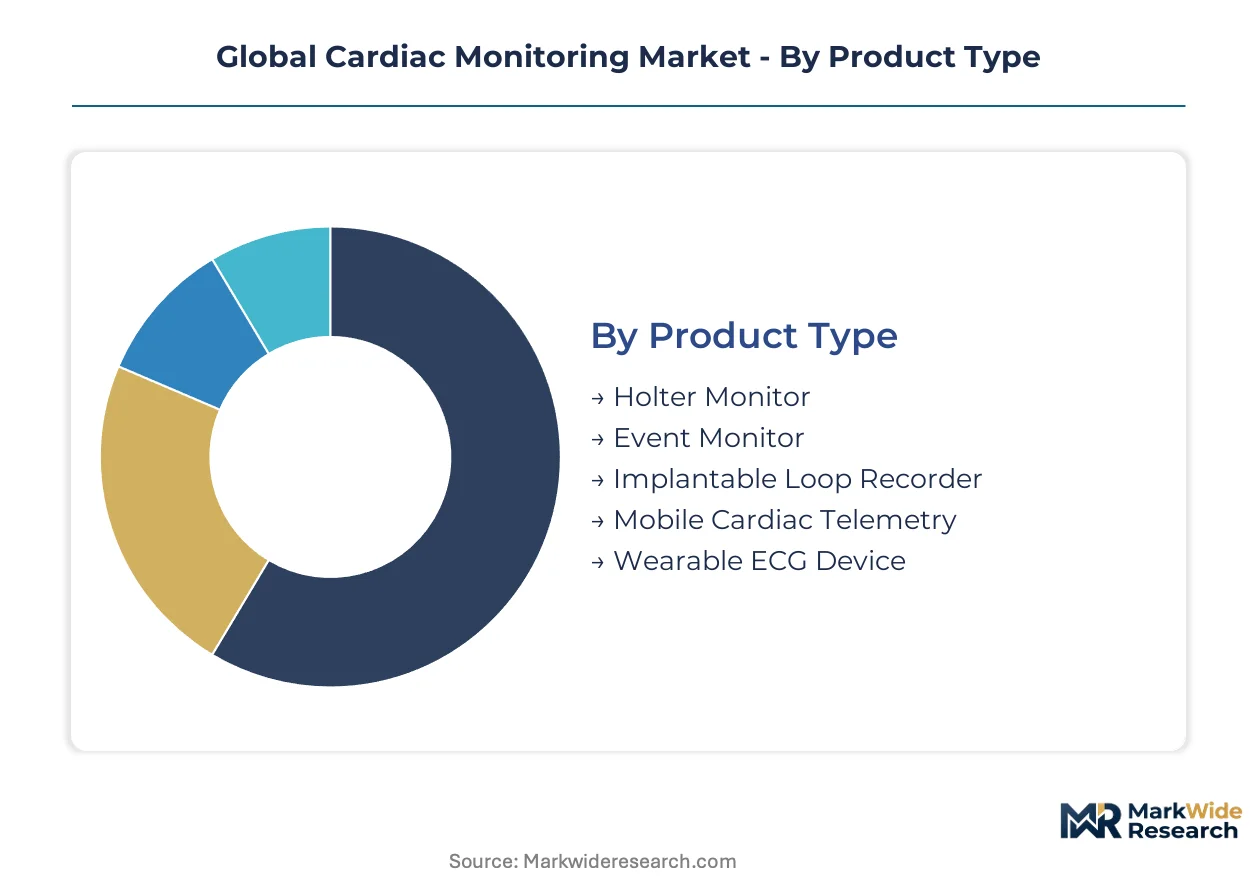
Cardiac monitoring segmentation reveals how supply-side specialization fragments across hardware platforms, sensor modalities, and care delivery settings. Vendor portfolios concentrate in segments where regulatory pathways and reimbursement codes align with manufacturing capabilities.
Product Type:
Supply concentration tilts toward vendors with integrated manufacturing of both implantable and surface-electrode systems.
- Holter Monitor:Ambulatory ECG recorder capturing 24-48 hours of continuous rhythm data through 3-12 lead configurations. Demand clusters in Germany and Japan where outpatient cardiac surveillance reimbursement supports 72-hour extended monitoring protocols.
- Event Monitor:Patient-activated or auto-triggered device recording symptomatic episodes via external electrodes or wrist-worn sensors. Cardiology clinics in the United States deploy these for cryptogenic stroke workups where intermittent arrhythmia suspicion drives diagnostic yield requirements.
- Implantable Loop Recorder:Subcutaneous device with 2-3 year battery life for unexplained syncope monitoring.
- Mobile Cardiac Telemetry:Real-time cellular-transmitted ECG with automated arrhythmia detection algorithms.
- Wearable ECG Device:Consumer-accessible optical or single-lead electrical sensors integrated into watches or patches.
Holter monitors absorb the bulk of installed capacity; mobile cardiac telemetry is expanding most quickly.
Technology:
Cost tier differentiation separates premium diagnostic-grade systems from economy consumer wellness devices.
- Electrocardiography:Gold-standard electrical potential measurement through skin electrodes at 250-1000 Hz sampling rates. Hospital procurement in the United States and Japan prioritizes 12-lead diagnostic resolution for emergency department chest pain protocols.
- Photoplethysmography:Optical volumetric measurement using LED and photodiode pairs to detect blood volume changes. Wearable manufacturers in Germany leverage PPG miniaturization for prescription-grade remote patient monitoring under DiGA reimbursement pathways.
- Ultrasound:Transthoracic or transesophageal echocardiography for structural and functional cardiac assessment.
- Impedance Cardiography:Thoracic electrical bioimpedance for stroke volume and cardiac output estimation.
- Bioimpedance Analysis:Whole-body or segmental impedance for fluid status and body composition monitoring.
Electrocardiography retains the dominant share of diagnostic revenue; photoplethysmography is climbing the fastest as optical sensors penetrate prescription and consumer channels simultaneously.
Application:
Volume concentration follows chronic disease prevalence and acute event detection protocols across hospital systems.
- Arrhythmia Detection:Rhythm disturbance identification spanning atrial fibrillation, ventricular tachycardia, and conduction abnormalities. Integrated delivery networks in the United States consolidate telemetry procurement for early warning systems reducing in-hospital cardiac arrest incidence.
- Ischemic Heart Disease Monitoring:ST-segment analysis and symptom correlation for myocardial ischemia surveillance. Japanese cardiology departments deploy continuous monitoring for post-PCI patients under PMDA-streamlined AI diagnostic pathways.
- Heart Failure Management:Hemodynamic and rhythm monitoring for decompensation prediction.
- Blood Pressure Regulation:Continuous or ambulatory pressure estimation alongside cardiac rhythm data.
- Sleep Apnea Monitoring:Nocturnal oxygen saturation and arrhythmia correlation for sleep-disordered breathing.
Arrhythmia detection commands the largest procedure volume; heart failure management is gaining share fastest as remote monitoring programs mature.
End User:
Customer type fragmentation reflects reimbursement bifurcation between facility-based and distributed care models.
- Cardiology Clinics:Outpatient specialty practices performing diagnostic workups and device implantation. Germany's outpatient cardiac telemetry reimbursement expansion redirects capital toward portable monitoring platforms in these settings.
- Diagnostic Laboratories:Centralized testing facilities processing Holter and event monitor data. United States-based networks face margin compression as integrated delivery networks internalize interpretation services.
- Specialized Medical Centers:Tertiary referral institutions managing complex electrophysiology cases.
- Rehabilitation Facilities:Post-acute care settings monitoring cardiac recovery and exercise tolerance.
- Telemedicine Providers:Virtual care platforms embedding cardiac data streams into chronic disease subscriptions.
Cardiology clinics absorb the bulk of diagnostic device placement; telemedicine providers are expanding most quickly as remote patient monitoring programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in Taiwan anchors cardiac monitoring hardware supply chains, while algorithm development clusters concentrate in Boston, Tel Aviv, and Tokyo. Regulatory divergence across FDA, PMDA, and EU MDR jurisdictions fragments product approval timelines.
United States
Integrated delivery networks consolidate telemetry procurement across hundreds of hospitals under centralized value analysis committees. FDA's 2023 cybersecurity premarket guidance mandates software bill of materials disclosure for connected devices. The Boston-Cambridge corridor houses algorithm development clusters for machine-learning-enabled arrhythmia detection.
Germany
Outpatient cardiac telemetry reimbursement expansion redirects capital from inpatient beds toward portable monitoring platforms. The DiGA fast-track creates immediate payment pathways for prescription-grade ECG smartphone applications. Baden-Württemberg's medical technology cluster advances photoplethysmography miniaturization for remote patient monitoring.
Japan
Aging demographics drive demand for ambulatory monitoring systems in cardiology departments managing post-PCI patients. PMDA streamlines approval pathways for AI-integrated diagnostics, accelerating commercialization of algorithm-enabled systems. Tokyo's Kanto region hosts electrophysiology device development centers serving domestic and export markets.
India
Price-sensitive hospital chains seek entry-level Holter monitors as cardiac disease prevalence rises. The PLI medical device scheme offers production-linked incentives for domestic manufacturing, reducing landed costs. Gujarat and Maharashtra industrial corridors attract assembly operations for export-oriented cardiac monitoring hardware.
Switzerland
Swissmedic maintains stringent clinical evidence requirements for active implantable devices that shape European regulatory benchmarks. Precision manufacturing heritage supports sensor miniaturization for implantable loop recorders. The Zurich-Basel corridor concentrates R&D operations for hemodynamic monitoring algorithms.
Global Cardiac Monitoring Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue algorithm-centric service models that decouple revenue from hardware shipment. The vendor base stratifies across implantable device incumbents, diagnostic imaging conglomerates, and telemetry-specialized newcomers. Three archetypes dominate: diversified medtech conglomerates with implanted device portfolios, diagnostic equipment manufacturers extending into monitoring adjacencies, and pure-play remote monitoring vendors. Competitive moves concentrate on multi-year service contract anchoring and cybersecurity validation infrastructure buildout.
Within the diversified medtech tier, Medtronic and Abbott exemplify contrasting strategic positions. Medtronic leverages its implanted device heritage to anchor long-term service agreements with consolidated hospital networks. Abbott competes through wearable ECG specialization aligned with outpatient-focused delivery models. Among diagnostic imaging conglomerates, GE Healthcare sustains equipment relationships that extend into cardiac monitoring adjacencies.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Koninklijke Philips NV |
| GE Healthcare |
| BIOTRONIK |
| iRhythm Technologies |
| ZOLL Medical Corporation |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Embedded software engineering talent scarcity in Boston and Tel Aviv widens pricing spreads between FDA-validated Class III devices and economy-tier Holter monitors. Labor-cost differentials for firmware security specialists translate into tiered product positioning across premium diagnostic platforms and entry-level hospital procurement.
Pricing Analysis
Volume concentrates in economy-tier Holter monitors while margins accrue to premium mobile cardiac telemetry systems with embedded AI diagnostics. Price differentiation rests on FDA cybersecurity validation tier and bundled remote monitoring service levels. Cost compression in standard-tier wearable ECG devices is intensifying because semiconductor foundry constraints elevate application-specific integrated circuit costs. Integrated delivery networks exhibit lowest price sensitivity for multi-year service contracts; price-sensitive hospital chains in India prioritize landed cost over algorithm performance.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network procurement while distributor networks serve cardiology clinics and diagnostic laboratories. Taiwan anchors semiconductor fabrication for implantable loop recorder ASICs; Germany and Japan concentrate precision sensor manufacturing. Raw material dependencies include silicon wafers, lithium primary batteries, and medical-grade polymers. Single-source vulnerability in Taiwan-based foundry capacity creates supply risk for wireless patch monitor chipsets. Distribution runs through GPO contracts in the United States and direct manufacturer relationships in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm-enabled cardiac monitoring is displacing hardware-centric revenue models as photoplethysmography and AI diagnostics reshape purchasing criteria away from sensor specifications.
For Market Incumbents: Deepen cybersecurity validation infrastructure to defend service contract anchoring against pure-play remote monitoring entrants. Invest in backward integration into ASIC design to mitigate Taiwan foundry concentration risk. Prioritize FDA software bill of materials compliance as a competitive moat given 10-15 year implantable device field lifespans.
For New Entrants and Emerging Players: Launch via telemedicine platform partnerships to bypass capital-intensive hospital procurement consolidation. Target India's price-sensitive hospital chains with domestically assembled Holter monitors under PLI scheme incentives. Pursue Germany's DiGA fast-track pathway for prescription-grade ECG smartphone applications as the most penetrable reimbursement channel.
For Investors and Strategic Acquirers: The window for entry favors algorithm-specialist firms with FDA breakthrough device designation momentum. Long-term viability centers on software-defined platforms where recurring revenue decouples from hardware shipment cycles. Watch PMDA AI diagnostic approval velocity as the signal for algorithm-centric valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Premarket software bill of materials disclosure accelerates hospital procurement security clearance timelines. |
| Hospital System Partnership | Multi-year service contracts with integrated delivery networks lock out competitor telemetry platform displacement. |
| CE Marking Pathway | EU MDR clinical evidence requirements for active implantable devices demand extended follow-up study investment. |
| Software Companion Development | Over-the-air update capabilities satisfy FDA post-market surveillance mandates for 10-15 year implant lifespans. |
| Reimbursement Strategy | Medicare outpatient telemetry expansion redirects capital from inpatient beds toward portable monitoring platforms. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and PMDA approval databases, complemented by interviews with electrophysiologists, hospital value analysis committee members, biomedical engineers, and GPO contracts managers. Secondary sources included CMS Medicare reimbursement schedules, hospital procurement databases, and semiconductor trade flow data. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Cross-referencing historical pricing trajectories with panel input from cardiology department heads shaped the forecast framework. Segmentation dimensions modeled include product type, sensor technology, application indication, and end-user channel. CAGRs derived from weighted average of historical volume trends and forward-looking reimbursement policy shifts. Industry-specific inputs incorporated PMDA AI diagnostic approval velocity and integrated delivery network consolidation trajectories throughout the forecast period.
The model assumes a particular technology adoption path; alternative pathways for photoplethysmography algorithm accuracy would alter the outlook for optical sensor penetration in prescription channels. Forecasts reflect assumptions regarding FDA cybersecurity guidance enforcement consistency and Taiwan foundry capacity expansion. Periodic stress-testing of base assumptions is recommended given semiconductor supply vulnerability and regulatory timeline variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market