
 Smart Shower Market | 2026-2036
Smart Shower Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Shower Market Intelligence
Leasing and service-based financial models for smart home technology in large-scale developments is reconfiguring the competitive landscape for smart shower manufacturers. This shift allows property managers to adopt advanced systems without significant initial capital expenditure. Kohler Co. leverages its extensive distribution network and brand recognition in the premium residential market. Aqualisa specializes in digital shower innovations for the United Kingdom and European markets, focusing on ease of installation and reliability.
A smart shower is an electro-mechanical bathing system combining digital controls, thermostatic valves, and flow rate sensors. These systems maintain water temperature with high precision, often within one degree, to enhance safety and comfort while optimizing water usage. Among technology types, IoT enabled systems with mobile app integration represent the fastest-growing category. While the residential end-user segment constitutes the largest volume, the hospitality sector provides significant opportunities for integrated systems with higher average selling prices.
Regulatory frameworks significantly influence product design and market access. In the United States, the EPA's WaterSense program encourages water efficiency, while in Europe, CE marking is essential for all electronic components, including smart controls. These regulations compel manufacturers to meet stringent safety and conservation standards. The critical path forward for vendors involves navigating the balance between advanced IoT functionality and ensuring robust user data privacy and cybersecurity protocols.
Market Dynamics
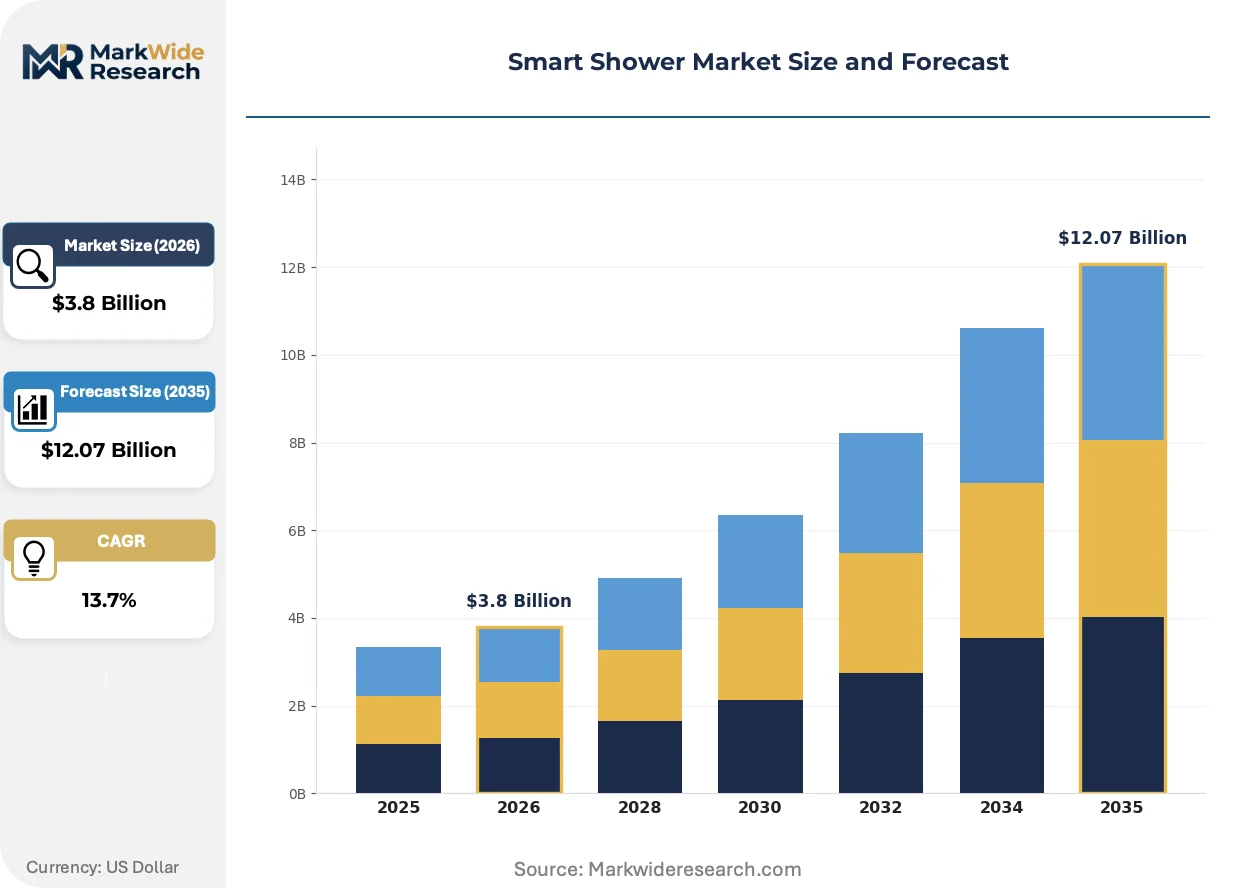
The convergence of water conservation mandates and the demand for personalized wellness experiences serves as the central structural force in the smart shower market. This dynamic is most pronounced in the high-end residential and hospitality sectors, where IoT integration is redefining user expectations and operational efficiency.
Growth Catalysts
- IoT and App Integration:The incorporation of IoT technology allows for personalized user profiles, remote operation via mobile applications, and voice control, significantly enhancing the user experience and product appeal.
- Water Conservation Regulations:Governmental programs, such as the EPA's WaterSense label in the United States, incentivize the adoption of water-efficient fixtures, creating a strong regulatory tailwind for smart showers designed to optimize consumption.
- Hospitality Sector Demand:Hotels and resorts are adopting smart showers to reduce operational costs through water and energy savings while offering a premium, tech-forward amenity to attract and retain guests.
Market Restraints
- High Initial Cost:The premium price point for smart shower systems, including installation, remains a significant barrier to mass-market adoption when compared to conventional shower fixtures.
- Data Privacy Concerns:The collection of user data through IoT-enabled devices raises consumer concerns regarding privacy and the potential for cybersecurity breaches, which can deter adoption.
- Component Sourcing:A reliance on specialized electronic components, including high-precision thermostatic mixing valves and flow sensors, creates vulnerability to supply chain disruptions and price volatility.
Strategic Opportunities
- Healthcare and Assisted Living:Developing systems with enhanced safety features like scald protection and automated assistance offers a significant opportunity in facilities for the elderly and mobility-impaired.
- Smart Home Ecosystem Integration:Deepening integration with major smart home platforms and voice assistants can create a more seamless, automated user experience, driving adoption among tech-savvy homeowners.
- Emerging Market Penetration:Targeting high-end residential projects in fast-growing urban centers in the Middle East and Southeast Asia presents a key geographic expansion opportunity for manufacturers.
Industry Challenges
- System Interoperability:Ensuring seamless functionality across a fragmented landscape of smart home protocols and platforms presents a persistent technical challenge for manufacturers.
- Complex Compliance Pathways:Navigating the diverse and stringent regulatory requirements for electronics and plumbing, such as CE marking in Europe, complicates product development and market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Shower Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Showers, Smart Controls, Temperature Sensors, Water Use Monitors Installation Type: Wall Mounted, Ceiling Mounted, Portable Units, Integrated Systems End User: Residential, Hospitality, Fitness Centers, Healthcare Facilities Technology: IoT Enabled, Voice Control, Mobile App Integration, Automated Settings |
| Companies Covered | TOTO LTD., Aqualisa, Kohler Co., ThermaSol, Dornbracht AG & Co. KG, Moen Incorporated, LIXIL Corporation, Grohe, Roca Sanitario S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Shower Market Strategic Shifts & Innovations
Product evolution is shifting smart showers from standalone luxury items into integral components of connected home wellness and sustainability ecosystems. This transition is driven by advancements in sensor technology, evolving data privacy regulations, and new financial models for technology adoption in large-scale properties.
Advanced sensor fusion combines data from thermostatic, flow rate, and sometimes even user presence detectors to deliver precise environmental control. High-end residential builders and luxury hospitality developers are the primary adopters of these sophisticated systems. The focus of product development is migrating from simple digital temperature setting to AI-driven predictive pre-heating and personalized water usage profiles that learn user preferences over time.
Europe's General Data Protection Regulation (GDPR) is a prominent policy shaping product design for connected devices. This framework compels manufacturers to embed stringent data protection and privacy-by-design principles into their IoT-enabled systems and companion applications. The IoT-enabled product category is most affected, requiring vendors to invest in secure cloud architecture and provide users with transparent control over personal data.
Service-based financial models are altering procurement patterns for smart technology in large-scale developments. This change disrupts the traditional one-time hardware sale through plumbing distributors, with property management firms and developers entering long-term service agreements instead. The shift is most visible in new multi-family residential projects in the United States and major hotel chain upgrades across Europe.
Smart Shower Market Segmentation
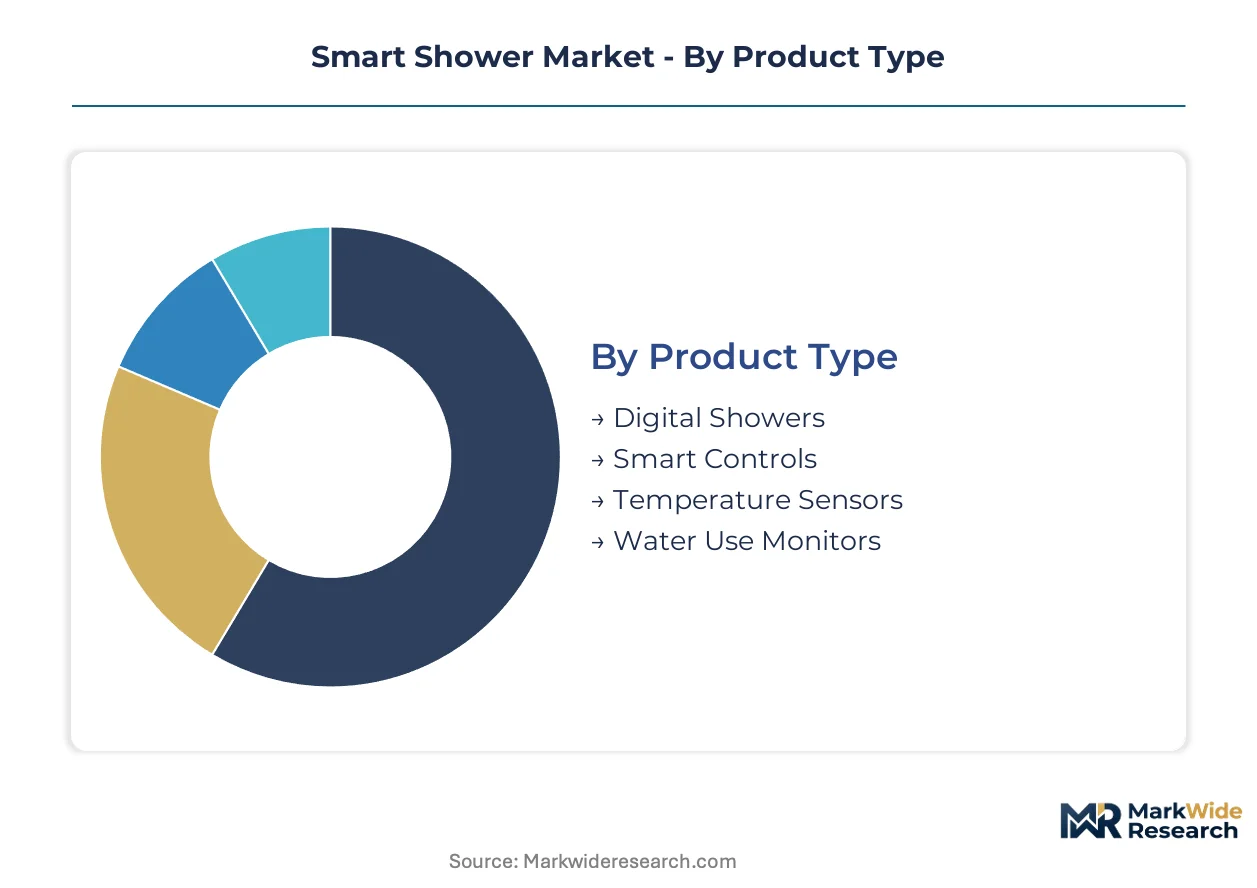
The Smart Shower Market's intricate structure reflects diverse product functionalities, installation methods, end-user applications, and underlying technological frameworks. Understanding these distinct segments is crucial for manufacturers to tailor product development and market strategies effectively. Each segment presents unique adoption drivers and competitive dynamics.
Product Type:
Product types exhibit varying refresh cycles, with software-driven smart controls and IoT modules evolving at a faster pace than the more durable electro-mechanical components. This distinction influences inventory management and product upgrade strategies for vendors.
- Digital Showers:These systems integrate electronic controls with thermostatic valves to deliver precise temperature and flow management. Demand concentrates in high-end residential projects in Germany and the United States, driven by luxury and water efficiency mandates.
- Smart Controls:Standalone or integrated digital interfaces provide user control over shower functions, often with programmable settings and diagnostic capabilities. Hospitality sector upgrades across Europe frequently adopt these controls to enhance guest experience and manage operational costs.
- Temperature Sensors:Components designed for real-time water temperature monitoring, ensuring user safety and comfort within smart shower systems.
- Water Use Monitors:Devices that track and display water consumption data, supporting conservation efforts and personalized usage patterns.
Digital Showers anchor the volume base while Smart Controls gain share at the steepest rate.
Installation Type:
Installation types vary significantly based on property design and renovation scope, ranging from simple component replacements to full system integrations. This impacts both installation complexity and the overall aesthetic appeal of the smart shower unit.
- Wall Mounted:These units are affixed to the shower wall, offering a common installation method for both new construction and renovation projects. High-end residential developments in Japan frequently opt for sleek wall-mounted designs.
- Integrated Systems:Comprehensive smart shower solutions are seamlessly built into the bathroom infrastructure, often hidden behind walls for a minimalist aesthetic. Luxury hotels in the United States prioritize integrated systems for a premium guest experience.
- Ceiling Mounted:Overhead showerheads and control panels offer a luxurious, rain-effect experience, popular in spa-like bathroom designs.
- Portable Units:Self-contained smart shower devices offer flexibility and temporary solutions, often found in outdoor or temporary living arrangements.
The preference for Wall Mounted units indicates widespread adoption, while Integrated Systems address the demand for advanced, concealed functionality.
End User:
End-user segments drive distinct demand patterns, with residential users seeking personalization and hospitality venues prioritizing operational efficiency and guest satisfaction. Each sector has specific requirements for durability, features, and system integration.
- Residential:Individual homeowners integrate smart showers for comfort, water conservation, and smart home ecosystem compatibility. Demand is strong in affluent households within the United States, driven by personalized wellness experiences.
- Hospitality:Hotels and resorts deploy smart showers to reduce water and energy costs while providing a modern, premium amenity. Major hotel chains in Europe are increasingly adopting these systems to attract and retain guests.
- Fitness Centers:These facilities utilize smart showers to enhance member experience with convenient, hygienic, and water-efficient bathing options.
- Healthcare Facilities:Hospitals and assisted living centers adopt smart showers for enhanced patient safety, including scald protection and precise temperature control.
While Residential represents the largest segment by volume, Hospitality offers higher average selling prices.
Technology:
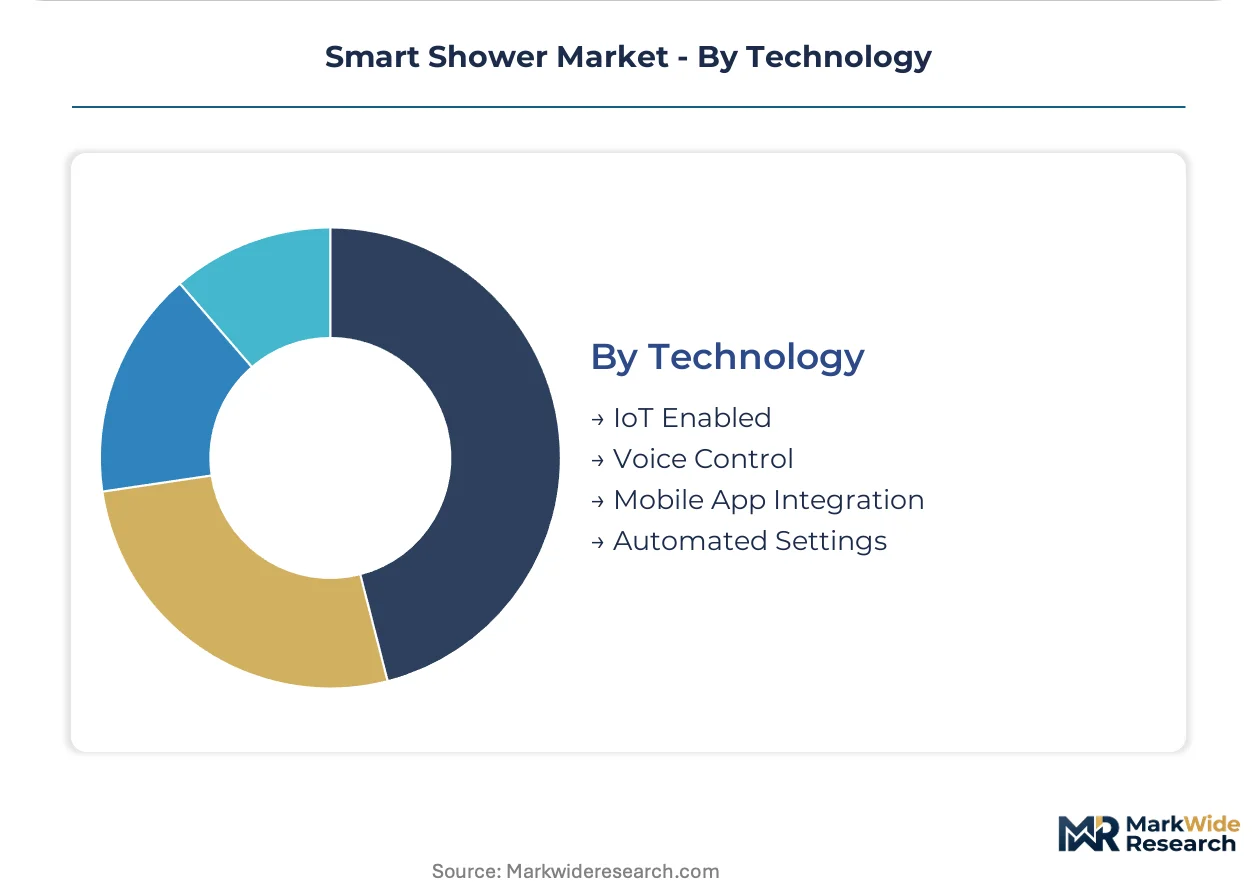
Technological advancements underpin the smart shower market's evolution, with innovation cycles driving new feature sets and user experiences. The convergence of digital controls and connectivity defines the leading-edge offerings in this category.
- IoT Enabled:These systems connect to the internet, allowing for remote control, data collection, and integration with broader smart home platforms. IoT-enabled systems represent the fastest-growing category in new high-end residential builds in Germany.
- Mobile App Integration:Dedicated smartphone applications provide intuitive interfaces for customizing shower settings, monitoring usage, and accessing diagnostic information. This integration enhances user convenience, especially for tech-savvy consumers in Japan.
- Voice Control:Integration with smart assistants allows users to operate shower functions through voice commands, adding a layer of hands-free convenience.
- Automated Settings:Pre-programmed or user-defined routines allow for consistent temperature, flow, and duration, optimizing comfort and resource use.
The future trajectory of the market is heavily influenced by advancements in IoT Enabled systems and the expanding capabilities of Mobile App Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Governmental programs encouraging water efficiency drive smart shower adoption across key global markets. The EPA's WaterSense program in the United States and CE marking in Europe compel manufacturers to meet stringent conservation standards. These regulatory frameworks significantly influence product design and market access, fostering innovation in water-saving technologies.
United States
Demand for personalized wellness experiences and water conservation mandates drive smart shower adoption. The EPA's WaterSense program incentivizes water-efficient fixtures, creating a strong regulatory tailwind for smart showers designed to optimize consumption. High-end residential projects in cities like New York and Los Angeles prioritize these advanced systems for luxury and sustainability. Integration with broader smart home ecosystems further boosts appeal.
Germany
High-end residential builders increasingly integrate IoT-enabled smart showers for advanced functionality and energy efficiency in new constructions. European CE marking is essential for all electronic components, ensuring compliance and market access for smart controls within the region. The Frankfurt Rhine-Main region sees significant adoption of these systems in new luxury developments, emphasizing connectivity. Manufacturers also focus on robust user data privacy protocols, aligning with GDPR principles.
Japan
Tech-savvy consumers and a focus on precision engineering fuel demand for smart showers with mobile app integration and automated settings. METI standards for energy efficiency and water conservation influence product design and market offerings, promoting resource optimization. High-end residential projects in Tokyo demonstrate a preference for sleek wall-mounted and integrated smart shower designs. User convenience and seamless integration into connected homes are paramount.
United Kingdom
The hospitality sector and residential renovations drive demand for digital shower innovations focusing on ease of installation and reliability. European regulatory frameworks, including CE marking, shape product development for connected devices and ensure safety standards. London's luxury hotel market and new residential builds frequently adopt smart shower systems to enhance guest experience and operational efficiency. Water usage monitors are particularly popular for conservation efforts.
Smart Shower Market Key Industry Players
On the supply side, the industry is moderately fragmented, with a mix of established plumbing fixture manufacturers and specialized smart technology providers. Strategic archetypes include premium brand innovators, digital shower specialists, and integrated smart home solution providers. Dominant competitive moves involve strategic partnerships to enhance IoT integration and portfolio diversification into higher-margin hospitality systems. Manufacturers also focus on geographic expansion into high-growth urban centers, particularly in Asia.
Premium brand innovators like Kohler Co. leverage extensive distribution networks and strong brand recognition in high-end residential markets, particularly in the United States. Aqualisa, a digital shower specialist, focuses on ease of installation and reliability for the European and United Kingdom markets, emphasizing innovative control systems. TOTO LTD., a Japanese manufacturer, exemplifies companies integrating smart shower technology within broader bathroom solution offerings for tech-savvy consumers in Asia. These companies collectively shape the market through continuous product innovation and strategic market segmentation across various end-user segments.
| Leading Market Players |
|---|
| TOTO LTD. |
| Aqualisa |
| Kohler Co. |
| ThermaSol |
| Dornbracht AG & Co. KG |
| Moen Incorporated |
| LIXIL Corporation |
| Grohe |
| Roca Sanitario S.A. |
| Others |
Cost & Logistics Intelligence
Component sourcing vulnerability, particularly for specialized electronic parts, determines both pricing tier spreads and the overall smart shower supply chain shape. This risk directly impacts the cost structure for manufacturers.
Pricing Analysis
IoT functionality creates the primary spread in smart shower pricing. The market utilizes a project-based pricing model for hospitality and large-scale residential developments, while individual residential sales are typically per-unit transactional. Brand premium and after-sales service, including installation and maintenance, further differentiate pricing. Pricing pressure stems from increased competition in entry-level digital shower systems. Hospitality buyers, focused on long-term operational savings, exhibit less price sensitivity compared to individual residential homeowners.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common in the smart shower market. Supply concentration for high-precision thermostatic mixing valves and IoT modules centers in Germany, Japan, and China. Raw material dependencies include specialized electronic components and advanced sensor technologies. Single-source vulnerability for these critical electronic parts represents a significant supply chain risk. Distribution runs through established plumbing distributors, direct-to-developer channels for major projects, and an expanding online retail presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires specific expertise in integrated platform development. Seamless interoperability across diverse smart home ecosystems remains a significant technical challenge, indicating a scarcity of relevant skills.
For Market Incumbents:
Pre-empt emerging tech-first entrants by investing heavily in secure, open-source IoT platforms. Acquire specialized software firms with proven data privacy and cybersecurity expertise to bolster internal capabilities. Reinforce channel control through long-term service agreements with property management firms and hospitality groups. Focus R&D on AI-driven predictive pre-heating and personalized water usage profiles.
For New Entrants and Emerging Players:
Establish a beachhead in niche segments like assisted living facilities, where enhanced safety features are paramount. Target eco-conscious residential developments with systems offering superior water efficiency and real-time consumption data. The most penetrable segment remains specialized applications requiring unique feature sets. Direct-to-consumer online sales, bundled with certified installation services, offers a viable go-to-market angle.
For Investors and Strategic Acquirers:
GDPR principles and EPA WaterSense program mandates reshape the acquisition landscape for smart shower technology. The market offers long-term viability as an integral component of connected home wellness and sustainability ecosystems. Target specialized IoT software developers or manufacturers with strong intellectual property in precision thermostatic control. Increased M&A activity involving smart home platform providers serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-driven predictive pre-heating systems | This initiative enhances user convenience and energy efficiency, appealing to premium residential and hospitality sectors. |
| Platform Integration: Deepen integration with major smart home ecosystems | Seamless connectivity expands market reach and simplifies user experience for tech-savvy consumers. |
| Strategic Partnership: Collaborate with property developers for large-scale projects | Securing long-term service agreements reconfigures procurement patterns and ensures volume adoption. |
| Acquisition of Specialist Firm: Acquire firms specializing in secure IoT data management | This move addresses growing data privacy concerns and strengthens compliance with regulatory frameworks like GDPR. |
| Geographic Expansion: Target high-growth urban centers in the Middle East | New luxury developments in these regions present significant opportunities for integrated smart shower systems. |
Research Approach
Initial hypotheses were tested against primary input from plumbing engineers, smart home integrators, hospitality procurement managers, and residential developers. This primary research was rigorously validated through comprehensive secondary data analysis. Secondary sources included EPA WaterSense program reports, European Commission directives, METI standards, and company annual reports. Both bottom-up and top-down triangulation methods ensured robust data integrity.
Demand-supply-balance modeling formed the core of the analytical framework across the projection horizon. The framework meticulously modeled segmentation dimensions including product type, installation type, end-user, technology, and regional regulatory compliance. Compound annual growth rates were derived from historical growth trends and projected adoption rates. Key forecast inputs included IoT module pricing trends and construction activity in high-end residential markets.
Sensitivities concentrate around shifts in water conservation mandates and cybersecurity incidents impacting IoT trust. Forecasts reflect assumptions documented through extensive research and expert consultations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
South Korea Cookware Market
Household Items
Knife Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Smart Drying Racks Market
Household Items
Air Humidifier Market
Household Items
Gel Warmers Market
Household Items
Residential Water Purifier Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Portable Humidifiers Market
Household Items
Smart Fork Market
Household Items
Cast Iron Cookware Market
Household Items
Remote Control Holder Market
Household Items
Saudi Arabia Cookware Market
Household Items
Hand Dryer Market
Household Items
Multi Pocket Holders Market
Household Items
Middle East and Africa Air Purifier Market