
 Forward Facing Type Child Safety Seats Market | 2026-2036
Forward Facing Type Child Safety Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Forward Facing Type Child Safety Seats Market Insights
Certified child passenger safety technician shortages across North America and Western Europe is unwinding installation confidence and dampening retail conversion rates. Graco leverages its broad retail footprint and parent education programs to sustain brand loyalty in mass-market channels. Britax anchors premium positioning through extended rear-facing-to-forward-facing engineering and rigorous crash-test protocols. Maxi-Cosi competes on European design heritage and integrated travel system compatibility.
Forward facing type child safety seats are automotive restraint devices engineered for children who have outgrown rear-facing limits, typically incorporating energy-absorbing foam, steel-reinforced frames, and harness systems rated to 65 pounds or more to mitigate frontal collision forces. These products serve the essential commercial purpose of reducing pediatric injury risk during vehicle travel while enabling caregiver visibility and child engagement. High-back booster configurations lead volume shipments due to prolonged regulatory mandates for head and torso support, while convertible seats capture margin concentration through dual-mode longevity that delays replacement purchases. Side impact protection technology represents the fastest-growing safety feature segment as regulatory test protocols expand beyond frontal assessments.
NHTSA's Federal Motor Vehicle Safety Standard 213 governs structural integrity and labeling requirements in the United States, while the EU's ECE R44/04 and successor i-Size regulations dictate dimensional compatibility and ISOFIX anchorage standards across European markets. China's GB 27887 standard, administered by SAMR, imposes mandatory CCC certification that filters non-compliant imports and elevates domestic manufacturing scale. Stakeholders must monitor regulatory harmonization pressures between i-Size and NHTSA protocols, as divergent test dummies and installation criteria threaten product platform standardization and inflate R&D duplication costs.
Market Dynamics
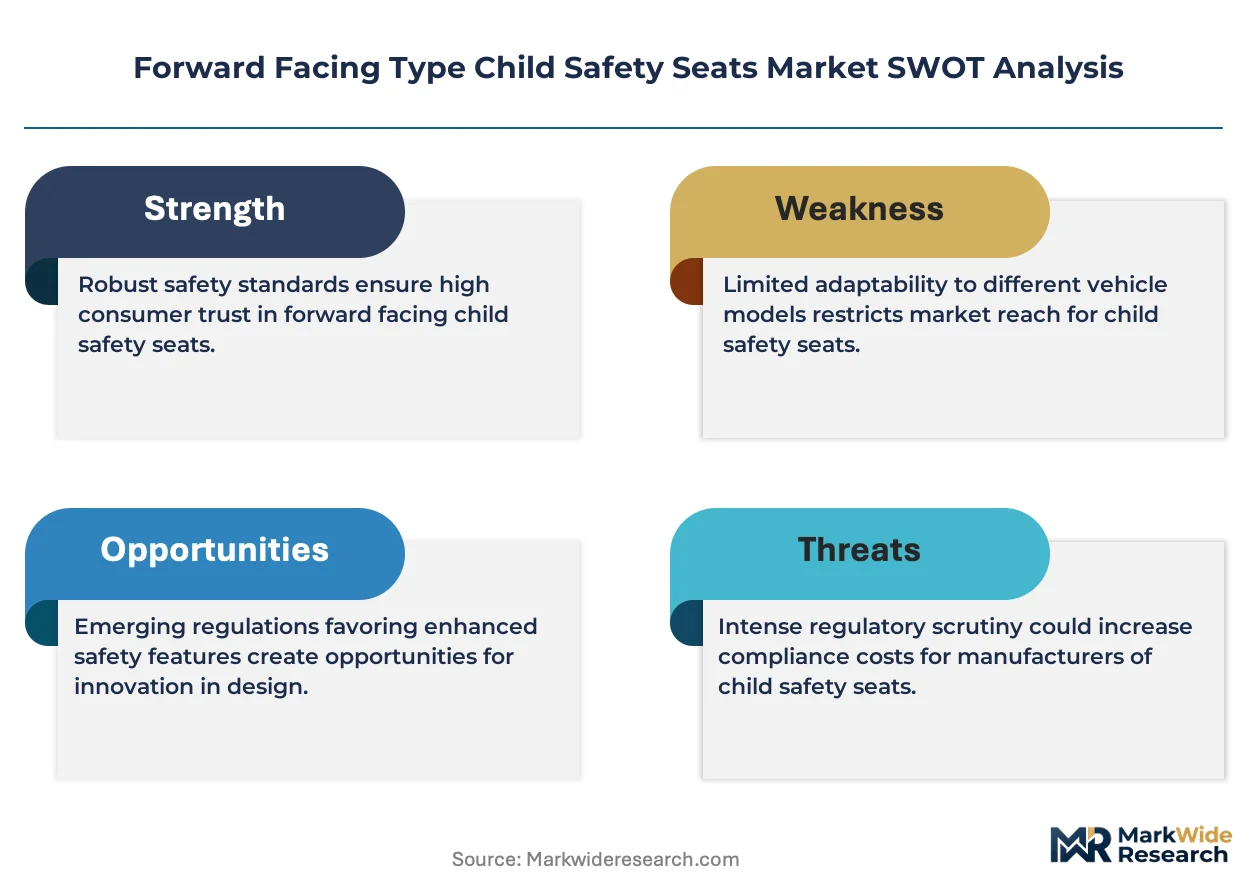
Regulatory divergence between NHTSA's FMVSS 213 and the EU's i-Size protocols is forcing manufacturers to maintain parallel engineering tracks, elevating R&D overhead and compressing margins across product lines.
Growth Catalysts
- Dual-income household expansion:Urban professional couples in the United States, Germany, and China are prioritizing certified safety equipment, expanding the addressable buyer base for premium configurations.
- FMVSS 213 upgrades:NHTSA's tightened structural integrity benchmarks are accelerating replacement cycles as older inventory fails to meet revised frontal crash-test thresholds.
- Side-impact technology diffusion:Energy-absorbing foam and reinforced frame architectures are becoming baseline expectations, pulling upgrade demand across all price tiers.
Market Restraints
- Polymer resin cost volatility:Petroleum-derived frame composites face input price swings that compress manufacturing margins without corresponding pricing power.
- ISOFIX anchor standard fragmentation:Incompatible latch geometries between NHTSA and ECE R44/04 jurisdictions force redundant tooling investments.
- Used-seat substitution:Secondary market circulation of certified pre-owned units captures price-sensitive demand that would otherwise flow to new product.
Strategic Opportunities
- India's BIS certification pathway:Mandatory AIS-072 compliance for child restraint systems creates first-mover advantage for brands establishing local assembly.
- Ride-share fleet mandates:Commercial vehicle operators in the United States face emerging liability exposure that demands dedicated forward-facing inventory.
- Sensor-integrated harness systems:Convergence of tension monitors with smartphone connectivity opens subscription-based safety alert revenue streams.
Industry Challenges
- Certified technician scarcity:NHTSA's standardized installation training programs graduate insufficient personnel to meet retail education demands.
- CCC timeline compression:China's SAMR approval cycles for GB 27887 compliance extend market entry by six to nine months versus domestic competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forward Facing Type Child Safety Seats Market |
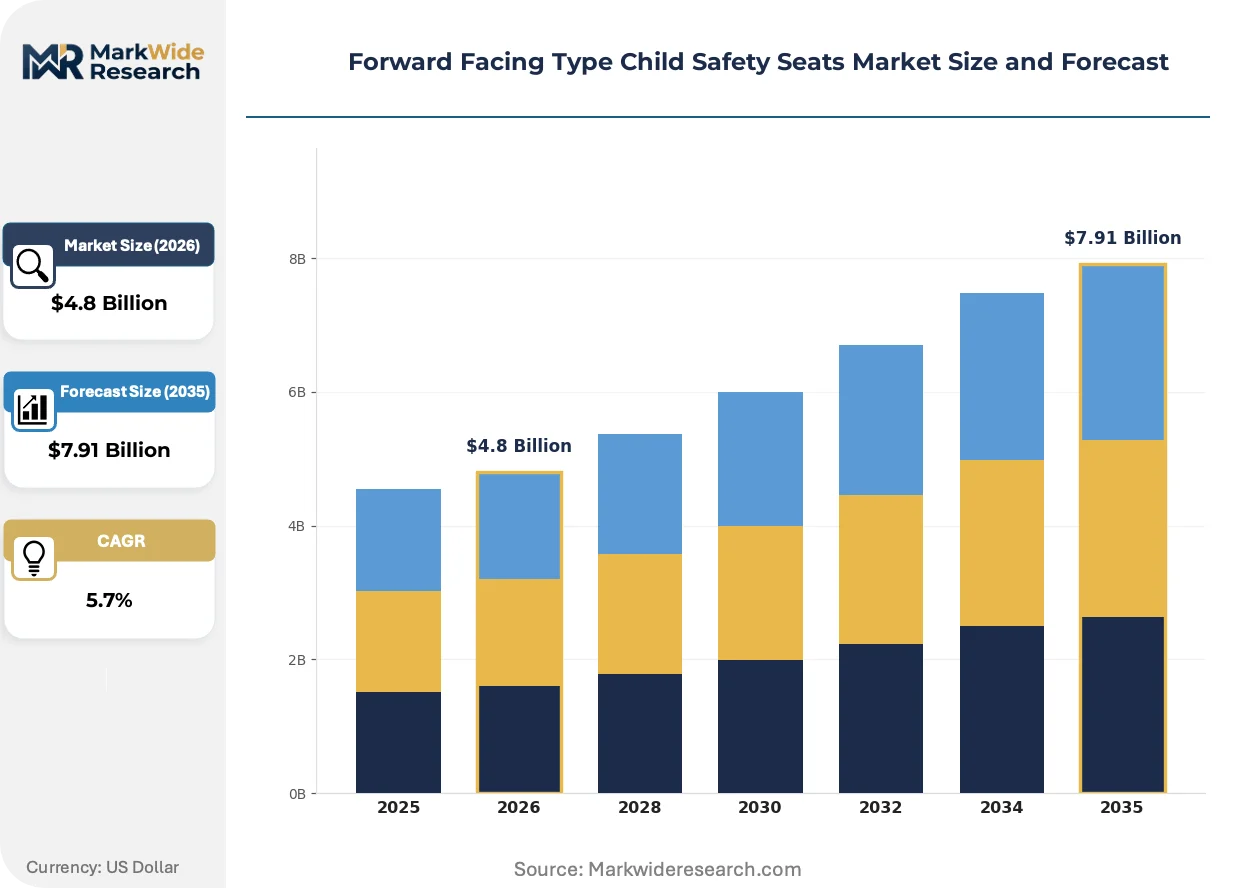
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Back Booster, Backless Booster, Convertible, Combination Seat Material: Plastic, Metal, Foam, Fabric Safety Feature: 5-Point Harness, Side Impact Protection, LATCH System, Anti-Rebound Bar Age Group: Infant, Toddler, Preschool, School Age |
| Companies Covered | Graco, Britax, Maxi-Cosi, Recaro, Chicco, Joyson Safety Systems, Combi, BeSafe, Concord, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forward Facing Type Child Safety Seats Market Trends and Innovations
Active safety integration and predictive monitoring capabilities are redefining product architecture, shifting competitive advantage from passive crash protection toward real-time risk mitigation and caregiver connectivity.
Sensor-embedded harness tension monitors are fragmenting the traditional hardware-centric value proposition. Dual-income households in Germany and the United States are specifying these systems at accelerating rates, treating connectivity as a non-negotiable feature. This capability diffusion is fragmenting price tiers as mid-market brands rush to match premium specifications without corresponding margin structures.
ECE R44/04's successor i-Size regulation is mandating extended rear-facing provisions that compress forward-facing entry timing. Manufacturers serving European markets must engineer convertible architectures that delay mode transitions without sacrificing installation confidence. High-back booster configurations face the most acute redesign pressure as dimensional compatibility requirements tighten.
Subscription-based safety monitoring services are displacing one-time hardware transactions. Direct-to-parent digital channels in China and the United States are capturing recurring revenue through app-integrated alert systems and usage analytics. This model shift concentrates value capture with brands that control software ecosystems rather than assembly operations.
Forward Facing Type Child Safety Seats Market Segmentation
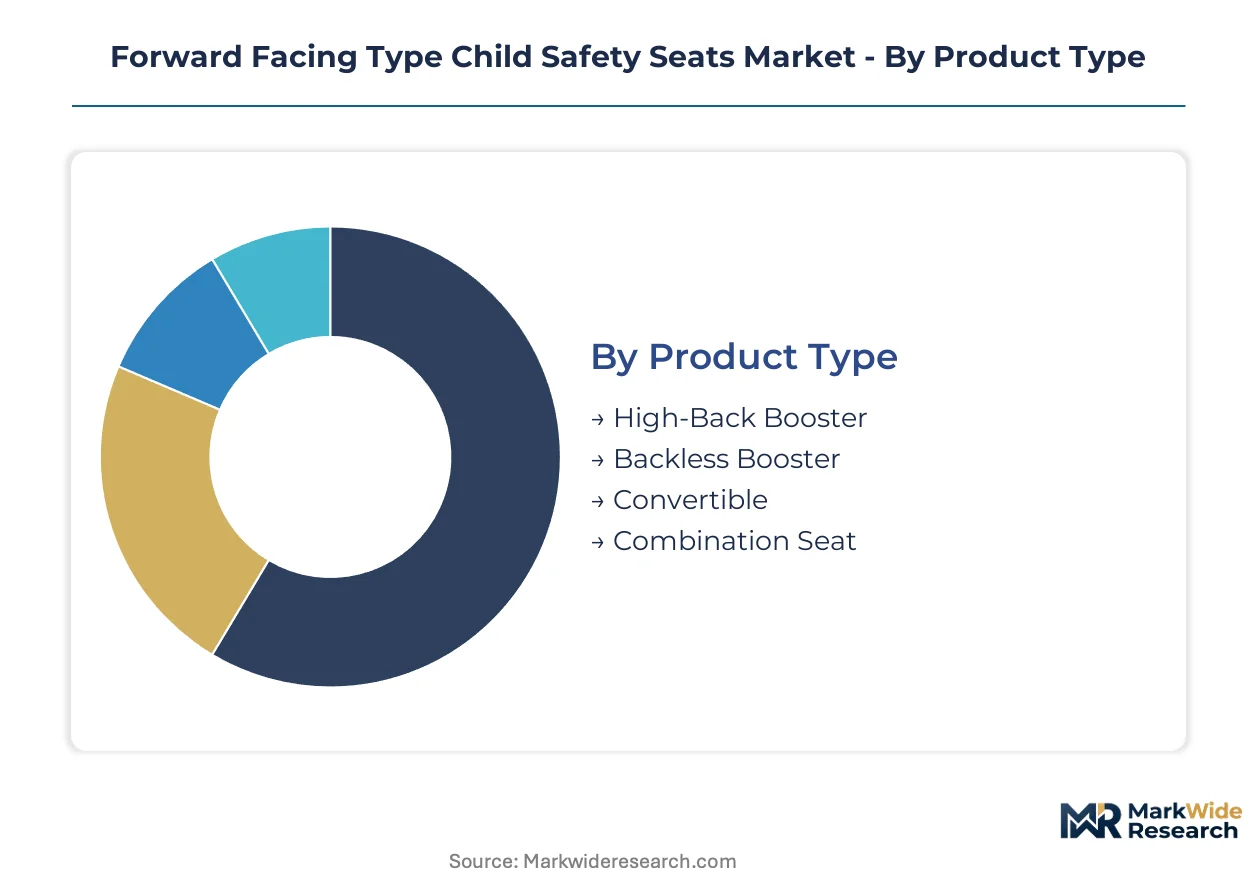
Forward facing type child safety seats fragment across four distinct dimensions that shape procurement priorities and margin structures. Product architecture, material composition, safety technology integration, and age-appropriate sizing each command separate engineering tracks and regulatory compliance pathways.
Product Type:
Geographic demand concentration varies sharply by configuration, with convertible seats dominating domestic replacement cycles in the United States while high-back boosters lead export volumes to European i-Size markets.
- High-Back Booster:These configurations integrate head and torso support with vehicle seat belt routing guides, typically rated for children above 40 pounds. Demand clusters in Germany and the United States where extended head support mandates persist through age requirements. NHTSA's evolving side-impact protocols are accelerating redesign cycles for energy-absorbing shell geometries.
- Convertible:Dual-mode architectures transition from rear-facing to forward-facing without replacement, capturing margin concentration through delayed purchase intervals. Urban dual-income households in China specify these units at premium price points, treating longevity as cost efficiency. SAMR's CCC certification timelines compress competitive windows for import brands.
- Backless Booster:Minimalist seat elevation devices for older children meeting belt-positioning requirements. Lightweight construction supports travel and secondary vehicle use cases.
- Combination Seat:Forward-facing harness systems that convert to belt-positioning boosters, bridging toddler through school-age requirements. Popular in multi-child households seeking stage-consolidation.
High-back booster configurations command the established base. The steepest expansion runs through convertible architectures.
Material:
Cost tier stratification separates premium steel-reinforced frames from economy polymer shells, with foam and fabric treatments creating mid-market differentiation.
- Plastic:Injection-molded polypropylene and ABS composites form the structural backbone of mass-market units, with petroleum-derived resin costs creating margin volatility. Manufacturers in China leverage domestic polymer supply chains to undercut import pricing.
- Metal:Steel-reinforced frames and aluminum structural members anchor premium crash-test performance, concentrated in Britax and Maxi-Cosi tier positioning. European i-Size dynamic testing protocols favor metal-intensive construction.
- Foam:Expanded polystyrene and polyurethane energy-absorbing layers manage impact deceleration. Thickness and density specifications vary by regulatory jurisdiction.
- Fabric:Upholstery materials span flame-retardant polyester blends to premium breathable meshes, with removable covers driving aftermarket replacement revenue.
Plastic structures anchor volume manufacturing. Metal reinforcement claims the steepest price escalation trajectory.
Safety Feature:
Technology integration intensity separates baseline compliance models from connected safety systems, with subscription-capable monitors creating new revenue architecture.
- Side Impact Protection:Reinforced wing structures and energy-absorbing foam pods extend protection beyond frontal test protocols. ECE R129 i-Size mandates are accelerating specification rates across European markets. This capability is expanding most quickly as regulatory test scopes widen.
- 5-Point Harness:Shoulder, hip, and crotch strap configurations with centralized tension adjustment remain the baseline restraint architecture. Graco's mass-market positioning depends on harness reliability at accessible price points.
- LATCH System:Lower anchors and tethers for children provide standardized vehicle attachment without seat belt routing. ISOFIX compatibility fragmentation between NHTSA and ECE geometries forces dual tooling investments.
- Anti-Rebound Bar:Stabilization devices that limit seat rotation during frontal impact, concentrated in rear-facing-to-forward-facing convertible designs.
5-point harness systems command the established base. Side impact protection features the steepest specification climb.
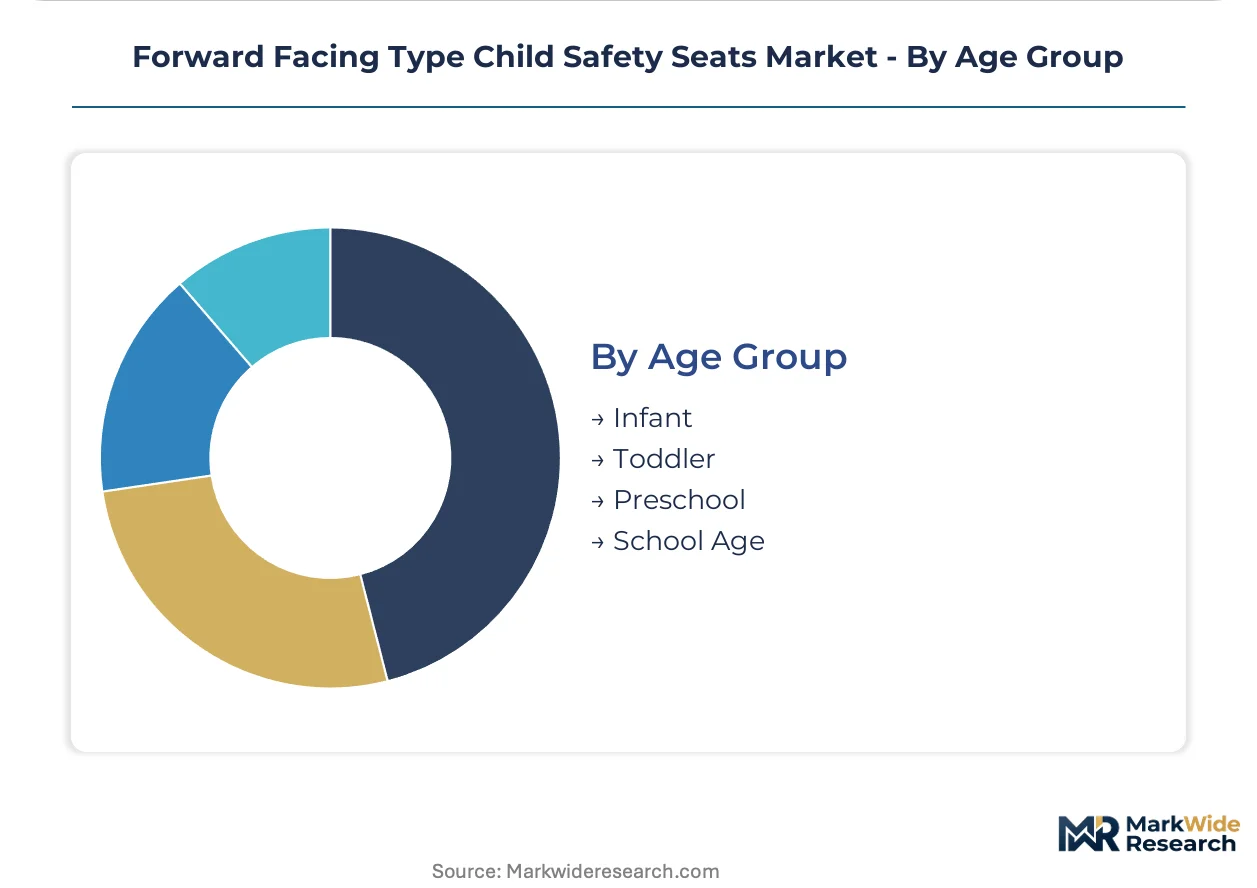
Age Group:
Customer lifecycle value concentrates in toddler and preschool segments where replacement frequency and safety sensitivity peak.
- Toddler:Children aged 1-3 years represent the primary forward-facing entry point, with outgrowing rear-facing limits triggering purchase decisions. United States households show highest conversion rates at this transition.
- Preschool:Ages 3-5 years drive high-back booster volume as harness systems accommodate growing torso dimensions. China's urban centers are prioritizing certified equipment at this stage.
- Infant:Below 12 months remains predominantly rear-facing, with forward-facing representing non-compliant misuse rather than intentional segmentation.
- School Age:5-12 years shifts toward belt-positioning boosters with declining parental safety equipment expenditure intensity.
Toddler specifications command the established base. Preschool configurations show the steepest volume acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets, with the United States prioritizing extended harness use while European households favor early booster transitions under i-Size protocols. China concentrates demand in convertible architectures that compress total ownership costs across multiple growth stages.
United States
Dual-income households in metropolitan corridors drive premium specification rates for side-impact protection and sensor-integrated systems. NHTSA's FMVSS 213 structural integrity mandates accelerate replacement cycles as older inventory fails revised frontal crash-test thresholds. Installation confidence gaps persist in suburban markets outside certified technician coverage zones.
Germany
European design heritage anchors consumer preference for metal-reinforced frames and extended rear-facing convertible engineering. ECE R129 i-Size regulations mandate dimensional compatibility standards that compress forward-facing entry timing and reshape product architecture requirements. Industrial concentration in Bavaria supports advanced crash-test facility access for domestic manufacturers.
China
Urban professional couples in Shanghai and Beijing specify certified equipment at accelerating rates, treating safety certification as non-negotiable procurement criteria. SAMR's GB 27887 standard imposes mandatory CCC certification that extends import approval timelines and elevates domestic manufacturing scale advantages. Yangtze River Delta assembly clusters capture volume production for Asia-Pacific distribution.
Japan
Compact vehicle fleet composition shapes demand for space-efficient convertible configurations with streamlined installation geometry. METI safety guidelines emphasize child restraint system penetration rates in private and commercial vehicle segments. Kanto region retail networks concentrate certified technician availability and parent education program delivery.
India
Emerging regulatory pressure through BIS AIS-072 compliance creates first-mover positioning for brands establishing local assembly operations. Maharashtra and Gujarat industrial corridors attract component sourcing investments that reduce landed cost structures for price-sensitive household segments. Ride-share fleet operators face emerging liability exposure that demands dedicated forward-facing inventory procurement.
Forward Facing Type Child Safety Seats Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated engineering capabilities and multi-channel distribution separating premium positioning from mass-market penetration. The competitive structure fragments across three strategic archetypes: full-spectrum portfolio operators, European design heritage specialists, and Asian manufacturing scale players. Dominant competitive moves include backward integration into polymer and metal component supply chains, plus geographic expansion through localized certification pathways in high-growth jurisdictions.
Among heritage European specialists, Maxi-Cosi and Recaro occupy positions emphasizing extended rear-facing engineering and rigorous dynamic testing protocols. Graco anchors the mass-market tier with broad retail footprint coverage and parent education program infrastructure. These three exemplify how competitive positioning fragments across premium design heritage, accessible volume distribution, and mid-market specification balancing.
| Leading Market Players |
|---|
| Graco |
| Britax |
| Maxi-Cosi |
| Recaro |
| Chicco |
| Joyson Safety Systems |
| Combi |
| BeSafe |
| Concord |
| Others |
Pricing and Supply Chain Analysis
NHTSA's FMVSS 213 certification gates both supply qualification and price differentiation simultaneously, filtering out uncertified manufacturers while enabling premium positioning for brands that exceed baseline structural integrity benchmarks. Dual-income households in the United States and Germany treat certification tier as a non-negotiable procurement filter, compressing price elasticity at the upper tier while expanding volume concentration in accessible mid-market configurations.
Pricing Analysis
Long-term offtake contracts with major retail chains anchor volume pricing for mass-market brands, while spot purchasing dominates premium direct-to-consumer channels where sensor-integrated systems command subscription attach rates. Three-tier pricing structure across premium, standard, and economy levels separates steel-reinforced metal frames with extended rear-facing engineering from polymer-shell units with basic harness systems. Cost compression in economy tiers is intensifying because petroleum-derived resin input volatility transfers margin pressure without corresponding pricing power. Fleet procurement teams at ride-share operators show highest price sensitivity, whereas urban professional couples in Shanghai and Beijing exhibit lowest elasticity for certified premium configurations.
Supply Chain Analysis
Inventory lead times stretch longest for metal-reinforced frame components sourced from European specialty suppliers, while polymer shell production cycles compress through Yangtze River Delta injection-molding clusters. Manufacturing gravity centers on China, Germany, and the United States, with domestic assembly in each market hedging tariff exposure and certification timeline risk. Steel-reinforced structural members, energy-absorbing foam layers, and ISOFIX anchor hardware constitute critical input dependencies. Single-source vulnerability concentrates in European dynamic-testing facility access for i-Size protocol validation. Distribution runs through mass-market retail chains, direct-to-parent digital channels, and commercial fleet procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based safety monitoring services are expanding faster than hardware transactions, converting one-time seat purchases into recurring revenue through app-integrated harness tension alerts and usage analytics.
For Market Incumbents: Consolidate certification infrastructure investments to defend against emerging domestic manufacturers in China and India that leverage compressed SAMR and BIS approval timelines. Deepen backward integration into polymer resin and steel component supply chains to buffer petroleum input volatility. Prioritize captive supply of energy-absorbing foam formulations that differentiate crash-test performance. For New Entrants and Emerging Players: Anchor in India's BIS AIS-072 compliance pathway before mandatory certification fully phases in, capturing first-mover positioning in Maharashtra and Gujarat industrial corridors. Target ride-share fleet operators facing emerging liability exposure that demands dedicated forward-facing inventory procurement. Pursue white-label manufacturing partnerships with established Yangtze River Delta assembly clusters to compress market entry timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sensor-integrated harness systems as smartphone connectivity modules commoditize, shifting value capture toward software ecosystem control. Long-term viability favors brands that own subscription alert platforms rather than assembly operations. Acquisition target archetype: mid-market manufacturers with dormant brand equity and underutilized certification infrastructure. Watch sensor-integrated specification rates in Germany and the United States as inflection indicator for recurring revenue model traction.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Safety Platform Launch | Converts hardware transactions into recurring revenue through app-integrated alert systems. |
| Backward Integration into Polymer Supply | Captures Yangtze River Delta resin cost advantages and buffers petroleum input volatility. |
| India BIS Certification Investment | Establishes first-mover positioning before AIS-072 mandates compress competitive windows. |
| Ride-Share Fleet Partnership | Addresses emerging commercial liability exposure with dedicated forward-facing inventory. |
| Extended Rear-Facing Engineering | Aligns product architecture with ECE R129 i-Size protocols compressing forward-facing entry timing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA FMVSS 213 filings, ECE R129 i-Size test protocols, SAMR CCC certification databases, and customs trade records across major import corridors. Primary interviews engaged product development engineers at Tier 1 child restraint manufacturers, certified child passenger safety technicians, retail category buyers at mass-market chains, and fleet procurement officers at ride-share operators. Bottom-up triangulation across unit shipment data and top-down validation against regulatory certification volumes ensures consistency.
Segmentation dimensions modeled include product architecture type, material composition tier, safety technology integration intensity, and age-appropriate sizing category across the projection horizon. CAGRs derive from regression analysis of historical certification volumes and replacement cycle dynamics. Forecast inputs incorporate dual-income household expansion rates in urban corridors and regulatory test protocol expansion timelines.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory tightening and petroleum input price stability; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Booster Car Seats Market