
 Smart Fork Market | 2026-2036
Smart Fork Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fork Market Insights
Embedded sensor miniaturization is tilting smart fork architectures toward low-power Bluetooth Low Energy and capacitive sensing arrays. OMRON Corporation leverages its industrial sensor heritage to anchor precision motion-detection capabilities. Pepperl+Fuchs specializes in ruggedized connectivity modules that sustain performance across temperature and humidity extremes. SICK AG competes on optical sensing integration for bite-detection accuracy.
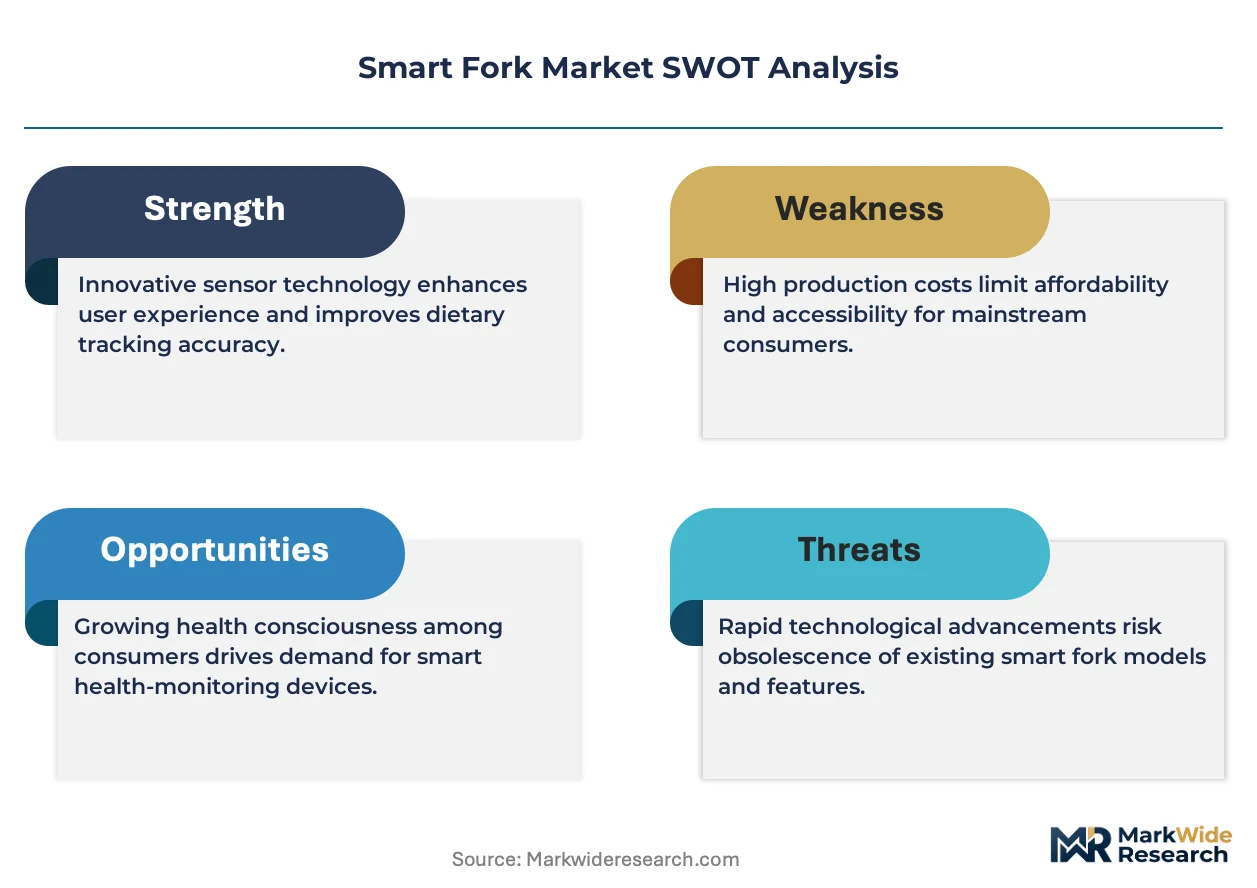
A smart fork is an instrumented eating utensil incorporating load cells, accelerometers, and microcontrollers to measure eating speed, bite frequency, and estimated caloric intake, transmitting data via Bluetooth or Wi-Fi to companion applications for dietary feedback. Bluetooth Fork variants dominate unit shipments due to universal smartphone compatibility and minimal power draw. Data Analytics applications represent the fastest-expanding technology segment as machine-learning models improve nutritional estimation accuracy. Restaurants occupy an emerging margin pool where enterprise fleet deployments enable behavioral-data monetization.
FDA digital health guidance governs wellness-claim substantiation for consumer-facing smart utensils, while FCC Part 15 regulates radio-frequency emissions from embedded connectivity modules. The EU Green Deal and REACH compliance constrain battery chemistry selections and end-of-life recyclability for European market access. Stakeholders must monitor evolving cybersecurity standards for connected dietary devices as data-privacy scrutiny intensifies across jurisdictions.
Market Dynamics
Embedded capacitive sensing arrays are compressing hardware footprints while FDA wellness-claim substantiation requirements are extending product development cycles for consumer-facing smart utensils.
Growth Catalysts
- FDA Digital Health Guidance:Clearer pathways for wellness-device classification in the United States are reducing regulatory uncertainty for smart utensil manufacturers seeking consumer market entry.
- Bluetooth Low Energy:Universal smartphone compatibility and minimal power draw are accelerating household adoption of connected dietary monitoring tools.
- Machine Learning:Nutritional estimation algorithms trained on expanded dietary databases are improving bite-detection accuracy and user retention rates.
Market Restraints
- Lithium-Ion Chemistry Constraints:EU REACH and Green Deal battery regulations are limiting cell supplier options and complicating European market access for disposable-powered designs.
- Precision Manufacturing Concentration:Load cell and accelerometer fabrication capacity clusters in East Asian contract manufacturers create single-source vulnerability.
- Manual Food Logging:Free smartphone applications remain adequate substitutes for price-sensitive consumers, capping willingness-to-pay for hardware solutions.
Strategic Opportunities
- Enterprise Restaurant Fleets:Behavioral data monetization through anonymized eating-pattern analytics offers recurring revenue streams beyond hardware sales.
- FCC Part 15 Certification:Pre-certified radio module availability is shortening time-to-market for new entrants in the United States.
- Capacitive-Optical Fusion:Combined sensing modalities are enabling contactless bite detection that expands addressable use cases to liquid and semi-solid foods.
Industry Challenges
- Embedded Firmware Talent:Scarce developers with combined Bluetooth stack and low-power microcontroller expertise are extending engineering timelines.
- Cybersecurity Compliance:Evolving data-privacy scrutiny across multiple jurisdictions is forcing redundant security architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fork Market |
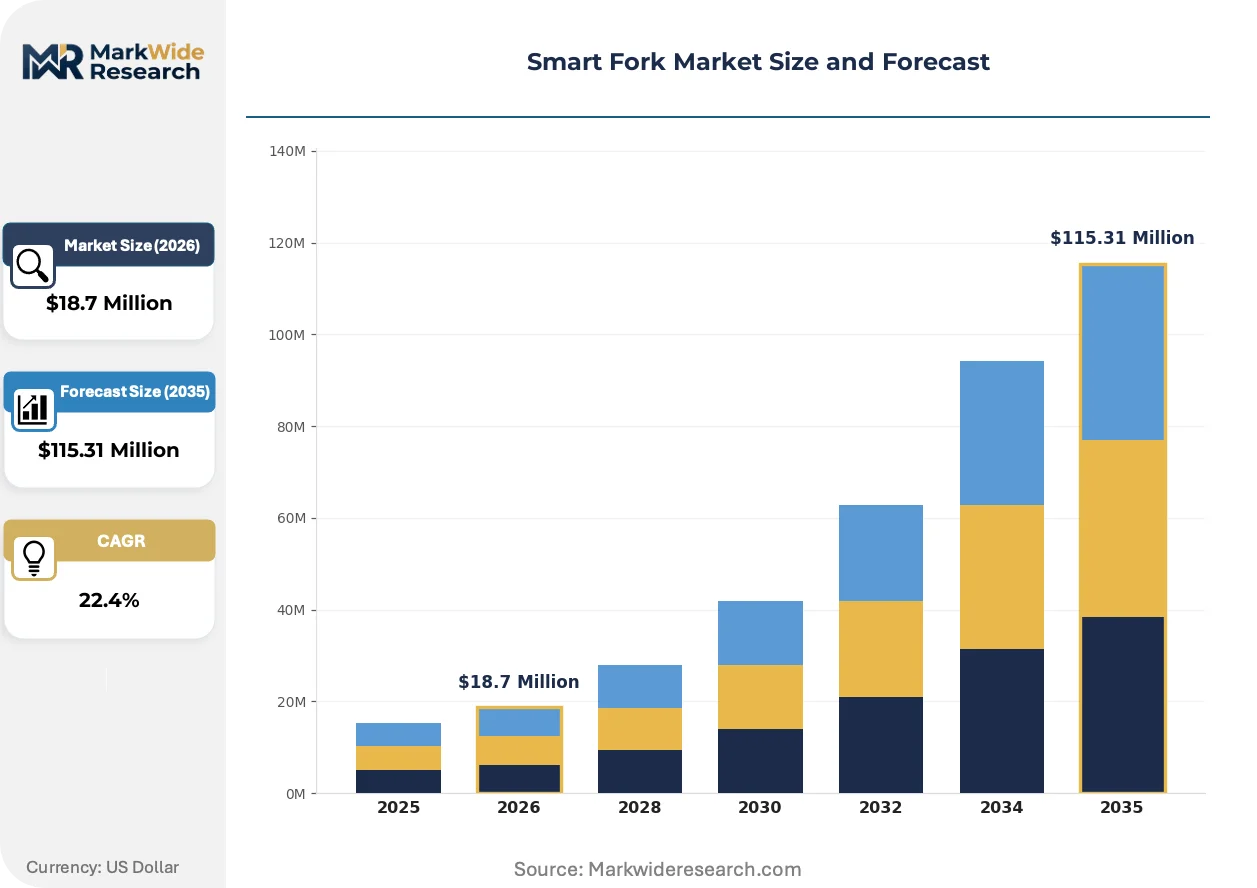
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $115.31 Million |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Fork, Wi-Fi Fork, USB Fork, NFC Fork End User: Consumers, Restaurants, Healthcare Facilities, Fitness Centers Technology: Smart Sensors, Data Analytics, Connectivity Modules, Battery Management Application: Caloric Tracking, Nutritional Monitoring, Dietary Assistance, Interactive Eating |
| Companies Covered | OMRON Corporation, SICK AG, Pepperl+Fuchs, Leuze Electronic, Datalogic, Baumer, SensoPart Industriesensorik GmbH, Banner Engineering Corp, ROHM Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fork Market Trends and Innovations
Sensor fusion architectures and regulatory clarity are converging to reshape competitive positioning in connected dietary hardware, with differentiation shifting from raw measurement precision to predictive behavioral feedback.
Multi-modal sensing is digitizing nutritional estimation by combining accelerometer motion signatures with capacitive load detection. Weight-management clinics and corporate wellness programs are piloting these instrumented utensils for patient adherence monitoring. The technology is digitizing how dietary feedback loops close, compressing the delay between consumption and actionable insight.
EU Green Deal battery sustainability mandates are forcing industrial design revisions toward user-replaceable cells and recyclable material selections. Manufacturers serving European markets must now document end-of-life processing pathways before CE marking approval. Premium product tiers are responding with modular architectures that separate sensor cores from disposable power components.
Subscription-based companion applications are displacing one-time hardware purchases as the primary revenue anchor. Direct-to-consumer channels are capturing share from specialty retail as buyers prioritize seamless onboarding over physical inspection. This shift is most visible in United States urban wellness markets where telehealth integration drives bundled device-and-coaching offerings.
Smart Fork Market Segmentation
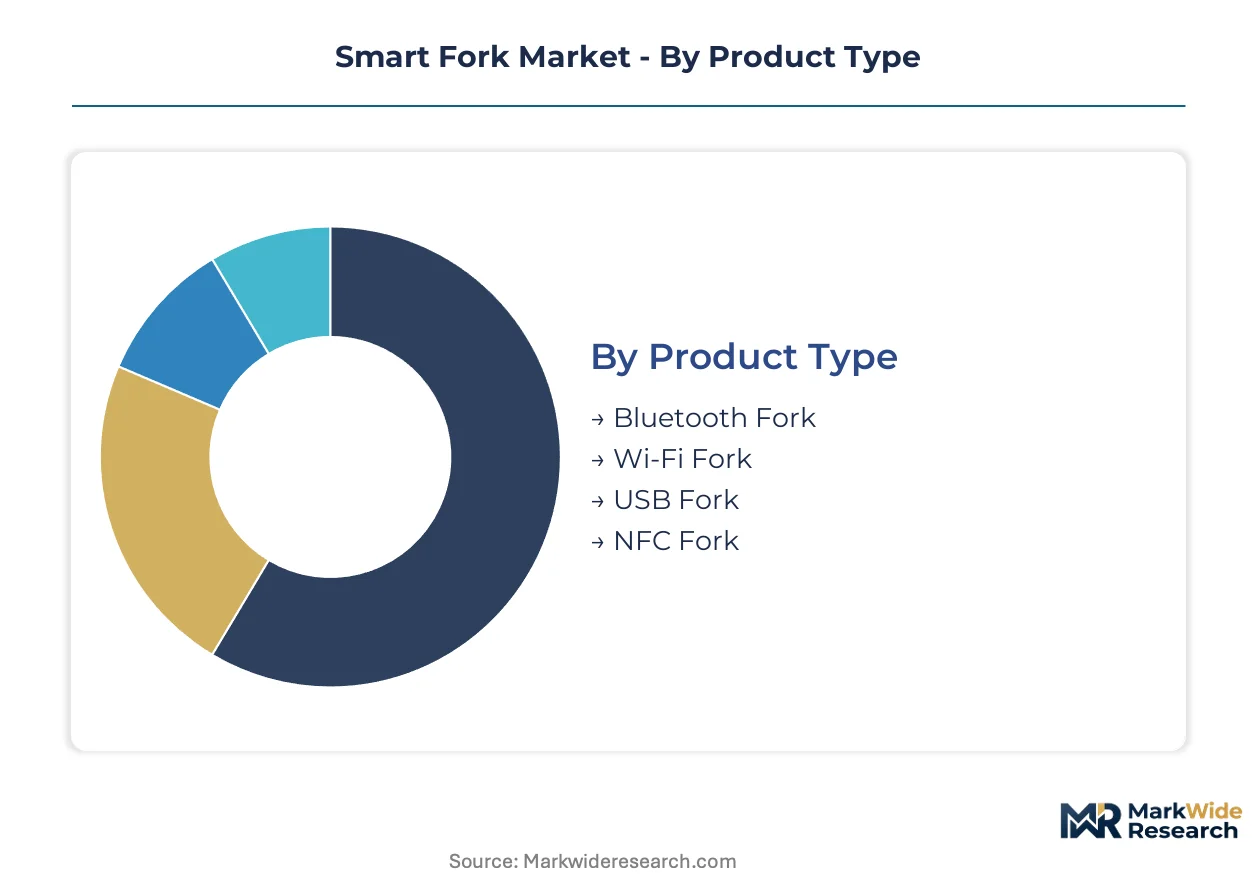
Smart fork segmentation reveals how hardware specifications, deployment environments, and data-processing capabilities partition addressable demand. Distinct buyer requirements across home, clinical, and commercial settings force specialized product configurations.
Product Type:
Connectivity protocols define power budgets, range, and smartphone interoperability across residential and enterprise deployments.
- Bluetooth Fork:Bluetooth Low Energy radios enable sub-10mA standby consumption and universal iOS/Android pairing without gateway infrastructure. Household wellness adopters in the United States favor this variant for seamless caloric logging with minimal charging overhead.
- Wi-Fi Fork:Direct cloud connectivity bypasses smartphone tethering for real-time data streaming to nutritionist dashboards and enterprise analytics platforms. Hospital weight-management clinics and corporate cafeteria fleets specify Wi-Fi architectures for centralized patient monitoring without BYOD dependencies.
- USB Fork:Tethered designs eliminate wireless certification complexity and battery maintenance for fixed-station dietary research applications.
- NFC Fork:Near-field tap-to-pair operation serves hospitality environments requiring instant guest onboarding without app store friction.
The dominant share belongs to Bluetooth Fork, while Wi-Fi Fork is closing the gap fastest.
End User:
Procurement authority and data-privacy requirements split the market across individual purchasers and institutional buyers with compliance obligations.
- Consumers:Direct-to-consumer channels capture individuals pursuing weight management through quantified eating feedback. FDA wellness-claim substantiation shapes marketing language for this price-sensitive segment.
- Restaurants:Enterprise fleet deployments enable anonymized behavioral-data monetization through pattern analytics sold to food manufacturers and health insurers.
- Healthcare Facilities:Bariatric surgery centers and diabetes clinics prescribe instrumented utensils for post-operative adherence monitoring, requiring HIPAA-aligned data architectures.
- Fitness Centers:Premium gym chains bundle smart forks with nutrition coaching subscriptions to differentiate membership tiers and reduce churn.
Consumer volume leads unit shipments, though restaurant enterprise contracts are climbing the fastest as data monetization models mature.
Technology:
Component-level capabilities determine measurement precision, connectivity reliability, and operational lifespan across use cases.
- Smart Sensors:Capacitive load cells and MEMS accelerometers detect bite timing, chewing cadence, and food mass with milligram resolution. Fitness center deployments demand this tier for competitive benchmarking features that drive member retention.
- Data Analytics:Cloud-based machine-learning pipelines convert raw sensor streams into personalized dietary recommendations and adherence scoring. Healthcare facilities prioritize this layer for insurance reimbursement documentation and remote patient monitoring integration.
- Connectivity Modules:Pre-certified radio subsystems from FCC Part 15 approved vendors compress certification timelines for new market entrants.
- Battery Management:EU REACH-compliant cell chemistries and user-replaceable architectures satisfy Green Deal sustainability mandates for European market access.
Smart Sensors anchor hardware bill-of-materials, while Data Analytics is expanding most quickly as recurring subscription revenue displaces one-time device sales.
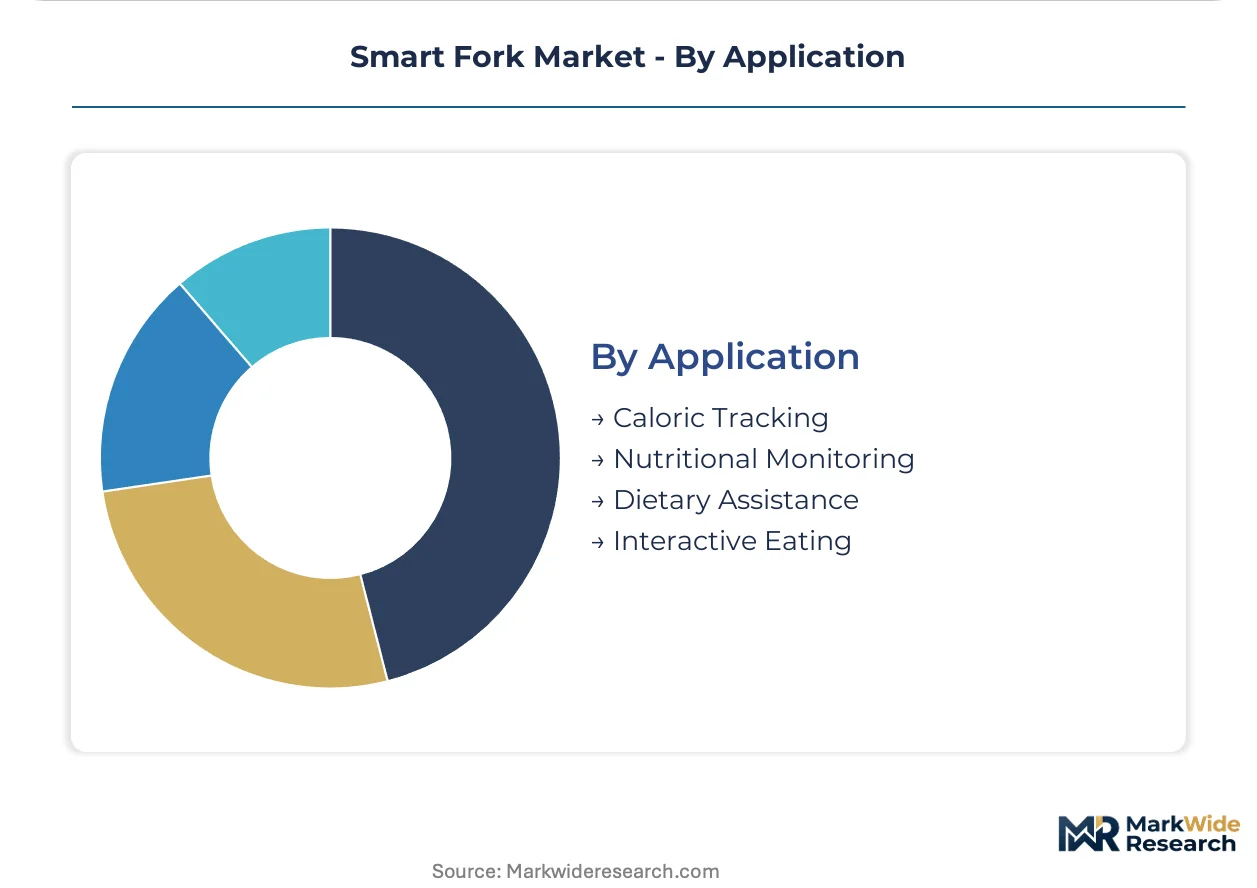
Application:
Functional use cases span passive measurement through active behavioral intervention, with reimbursement eligibility varying by clinical claim intensity.
- Caloric Tracking:Automated energy-intake estimation eliminates manual food-logging friction for weight-management consumers. Bluetooth Fork hardware dominates this application due to minimal power draw during intermittent use.
- Nutritional Monitoring:Macro-nutrient breakdowns and micronutrient flagging serve clinical populations with diabetes, renal disease, or eating disorders. Healthcare facilities mandate this application tier for FDA-cleared wellness device procurement.
- Dietary Assistance:Real-time eating-speed feedback and portion pacing support post-surgical bariatric patients with strict consumption protocols.
- Interactive Eating:Gamified meal experiences and social sharing features target fitness center demographics seeking engagement-driven habit formation.
Caloric Tracking commands installed base leadership, though Nutritional Monitoring is gaining share fastest as telehealth reimbursement expands diagnostic device prescribing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean component manufacturers export Bluetooth Low Energy modules to United States wellness hardware brands, establishing a primary trade corridor that supplies capacitive sensing arrays for caloric-tracking utensils.
United States
FDA digital health guidance and telehealth reimbursement expansion drive demand for wellness-device certification in urban wellness markets. HIPAA-aligned data architectures govern healthcare facility procurement of instrumented utensils for bariatric patient monitoring. Silicon Valley hardware startups and Boston-area digital health clusters concentrate firmware development talent for Bluetooth stack integration.
Germany
Industrial sensor heritage from precision manufacturing bases sustains demand for optical sensing integration in dietary research applications. EU Green Deal battery sustainability mandates and REACH compliance constrain cell chemistry selections for European market access. Munich and Stuttgart engineering clusters specialize in ruggedized connectivity modules for temperature-extreme environments.
Japan
Aging demographics and metabolic disease management protocols expand clinical prescribing of eating-speed feedback devices. METI standards for connected health devices shape domestic certification requirements for cloud-linked utensils. Tokyo-Osaka corridor electronics manufacturers supply MEMS accelerometer components to fork OEMs.
South Korea
Corporate wellness program adoption and fitness center chain expansion drive fleet procurement of nutritional monitoring hardware. MFDS medical device classification guidance influences wellness-claim substantiation for consumer-facing products. Seoul Capital Area semiconductor foundries fabricate low-power microcontroller units for Bluetooth Fork architectures.
China
Domestic weight-management app ecosystems and cross-border e-commerce channels accelerate consumer adoption of caloric-tracking hardware. NMPA digital health oversight and GB standards for wireless devices regulate radio-frequency emissions from embedded modules. Shenzhen and Dongguan manufacturing clusters concentrate load cell and capacitive sensor assembly capacity.
Smart Fork Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressure concentrates around pre-certified radio module availability and FDA wellness-claim substantiation capabilities. Three archetypes dominate: industrial sensor heritage firms, connectivity module specialists, and optical sensing integrators. Strategic moves center on capacitive-optical fusion R&D partnerships and enterprise restaurant fleet data monetization licensing.
Within the industrial sensor heritage tier, OMRON Corporation and SICK AG represent precision motion-detection capabilities derived from factory automation applications. Pepperl+Fuchs occupies a position among ruggedized connectivity specialists serving temperature-extreme deployment environments. These three firms exemplify how established industrial sensing competencies transfer into consumer wellness hardware through miniaturized form factors and Bluetooth Low Energy integration.
| Leading Market Players |
|---|
| OMRON Corporation |
| SICK AG |
| Pepperl+Fuchs |
| Leuze Electronic |
| Datalogic |
| Baumer |
| SensoPart Industriesensorik GmbH |
| Banner Engineering Corp |
| ROHM Semiconductor |
| Others |
Pricing and Supply Chain Analysis
Seoul-to-Los Angeles air freight corridors carry MEMS accelerometer and capacitive sensor shipments from South Korean foundries to United States wellness hardware assemblers, with per-kilogram rates compressing margins on Bluetooth Fork tiers while amplifying price spreads between FDA-cleared clinical variants and consumer-grade alternatives.
Pricing Analysis
Next-generation capacitive-optical fusion architectures command 40-60% premiums over prior-generation Bluetooth-only designs, while legacy USB-tethered forks face price erosion from smartphone-app substitutes. Pricing stratifies across premium, standard, and economy tiers based on FDA wellness-claim substantiation status and telehealth integration depth. Cost compression in the consumer Bluetooth segment is intensifying because free manual-logging applications cap willingness-to-pay. Healthcare facilities demonstrate the lowest price sensitivity due to insurance reimbursement eligibility, while individual wellness adopters exhibit acute sensitivity to hardware-plus-subscription bundles.
Supply Chain Analysis
Extended payment terms from South Korean semiconductor foundries to fork OEMs are stabilizing working capital for Bluetooth Low Energy module procurement, though supplier-financing facilities remain concentrated among tier-one industrial sensor heritage firms. Component fabrication clusters in China, South Korea, and Japan supply MEMS accelerometers, capacitive load cells, and low-power microcontrollers. Raw material dependencies span lithium-ion battery chemistry, rare-earth magnet materials for haptic feedback motors, and medical-grade stainless steel for food-contact surfaces. Single-source vulnerability concentrates in East Asian contract manufacturers for precision load cell calibration. Distribution runs through direct-to-consumer channels capturing share from specialty retail, with enterprise restaurant fleets procuring through dedicated B2B sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent combining Bluetooth stack expertise with low-power microcontroller optimization is the binding constraint compressing product development timelines and amplifying acquisition premiums for teams with shipped connected-device experience.
For Market Incumbents: Insulate margin position by deepening backward integration into capacitive sensor calibration and securing exclusive foundry capacity for Bluetooth Low Energy module variants. OMRON Corporation and SICK AG should accelerate FDA wellness-claim substantiation investments to create regulatory moats against smartphone-app substitutes. Priority capacity addition in South Korean semiconductor clusters reduces exposure to East Asian contract manufacturer concentration. For New Entrants and Emerging Players: Pursue white-space opportunities in Wi-Fi Fork architectures for healthcare facility deployments, where HIPAA-aligned data architectures and telehealth reimbursement expansion create procurement windows. The restaurant enterprise fleet segment offers the most penetrable entry point through behavioral-data monetization licensing rather than hardware margin capture. Go-to-market execution should anchor on pre-certified FCC Part 15 radio module integration to compress certification timelines. For Investors and Strategic Acquirers: Industrial sensor heritage firms with miniaturized form-factor capabilities and existing FDA digital health guidance navigation experience represent the highest-conviction acquisition archetype. Long-term viability hinges on recurring subscription revenue displacement of one-time hardware sales across the projection horizon. The signal to monitor is telehealth reimbursement expansion enabling diagnostic device prescribing authority for instrumented utensils.| Strategic Initiative | Industry Significance |
|---|---|
| Capacitive-Optical Fusion R&D Partnership | Combined sensing modalities expand addressable use cases to liquid and semi-solid foods beyond solid-bite detection. |
| FDA Wellness-Claim Substantiation Investment | Clearer regulatory pathways reduce market entry uncertainty for consumer-facing smart utensil manufacturers. |
| Enterprise Restaurant Fleet Data Licensing | Anonymized eating-pattern analytics generate recurring revenue streams beyond hardware sales cycles. |
| EU REACH-Compliant Battery Architecture Redesign | User-replaceable cell designs satisfy Green Deal sustainability mandates for European CE marking approval. |
| Telehealth Platform Integration Development | Bundled device-and-coaching offerings capture United States urban wellness market share from standalone hardware. |
Research Methodology
A spread of perspectives from smart fork product managers, FDA regulatory affairs consultants, hospital biomedical engineering directors, and restaurant technology procurement leads converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from FCC Part 15 equipment authorization databases, FDA digital health guidance documents, EU REACH substance restriction lists, and South Korean customs export records. Bottom-up shipment estimates triangulated against top-down addressable market calculations across connectivity protocol, end-user segment, and application tier dimensions.
Demand-supply-balance framing anchored the forecast framework, with consumption projections derived from healthcare facility procurement cycles, fitness center membership tier bundling strategies, and enterprise restaurant fleet refresh timelines across the analysis window. Segmentation modeling incorporated product type, end user, technology layer, and application intensity dimensions. CAGRs were computed from annual growth rate progression analysis. Industry-specific forecast inputs included Bluetooth Low Energy module cost curves, machine-learning nutritional estimation accuracy improvements, and telehealth reimbursement policy evolution trajectories.
Sensitivities concentrate around FDA digital health guidance revisions, EU battery chemistry mandate enforcement intensity, and cybersecurity standard evolution for connected dietary devices. Forecasts reflect documented assumptions on sensor fusion adoption curves and subscription pricing elasticity. Macroeconomic contraction reducing discretionary wellness hardware expenditure, regulatory restriction on cross-border data flows, or breakthrough smartphone-app accuracy matching instrumented utensil precision would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Dosage Spoon Market
Household Items
Remote Control Holder Market
Household Items
Range Hood Cleaning Service Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Commercial Locker Market
Household Items
India POU Water Purifiers Market
Household Items
Hands-Free Faucet Market
Household Items
Shoe Shine Machine Market
Household Items
Microwave Safe Utensils Market
Household Items
Portable Humidifiers Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Gas Hobs Market
Household Items
Middle East and Africa Air Purifier Market
Household Items
Beach Towel Market
Household Items
Kitchen Towel Market
Household Items
Smart Drying Racks Market