
 Knife Market | 2026-2036
Knife Market Size, Share, and Industry Trends Forecast 2026-2036
Knife Market Analysis
Asset-light leasing models for commercial kitchen equipment are reshaping how restaurants and hospitality groups access premium cutlery. Benchmade leverages vertical integration over its Oregon manufacturing base to sustain quality control across tactical and outdoor lines. Spyderco anchors its position through distinctive blade geometries and ergonomic handle designs that differentiate the brand in specialty retail channels.
A knife is a cutting tool consisting of a blade with one or more sharpened edges attached to a handle, typically forged from alloyed steel with Rockwell hardness ratings between 54 and 62 HRC for edge retention and durability. Its primary commercial purpose spans food preparation, industrial processing, outdoor recreation, and tactical applications where precision cutting reliability determines operational efficiency. Chef's Knife and Utility Knife categories dominate volume in commercial channels where durability under continuous use commands premium positioning, while Damascus Steel and Ceramic materials capture margin pools among enthusiast and professional chef segments seeking performance differentiation. Folding Blade configurations lead outdoor and everyday carry demand, whereas Fixed Blade designs sustain higher average selling prices in tactical and hunting applications.
EU REACH regulations govern chemical composition in steel alloys and handle materials, while FDA guidelines in the United States specify surface finishes and corrosion resistance for food-contact blades. CE marking requirements under the EU Machinery Directive shape product access for electric and automated cutting systems in European commercial kitchens. Stakeholders must monitor evolving material compliance standards and energy efficiency benchmarks for powered blade equipment as regulatory scope expands across both manual and automated cutlery categories.
Market Dynamics
The Knife Market is experiencing structural pressure from the EU Green Deal's material sourcing mandates, which are forcing manufacturers to requalify supply chains and absorb certification costs while commercial kitchens accelerate replacement cycles for professional-grade cutlery.
Growth Catalysts
- EU Green Deal compliance requirements:The EU Green Deal is tightening traceability standards for metal goods sold in Europe, creating procurement urgency among distributors to secure compliant inventory before enforcement deadlines tighten.
- Hospitality sector expansion:Commercial kitchens in the hospitality sector are expanding procurement of professional-grade cutlery as hotel and restaurant construction rebounds in Germany and France.
- Precision manufacturing clusters:Demand is concentrating in Germany, where Solingen's precision manufacturing clusters support premium blade production and attract specialized tooling investments from adjacent industries.
Market Restraints
- Alloy steel price volatility:High-grade chromium and vanadium alloy inputs face price swings tied to energy-intensive smelting operations in Eastern European supplier networks.
- REACH chemical compliance friction:ECHA's REACH regulations govern chemical composition in steel alloys and handle materials, extending product development timelines by 8-14 months for new formulations.
- Ceramic blade substitution in consumer segments:Ceramic knives capture margin pools among enthusiast segments seeking performance differentiation without metal sourcing complexity.
Strategic Opportunities
- Asset-light leasing models:Leasing models for commercial kitchen equipment are reshaping how restaurants and hospitality groups access premium cutlery, reducing upfront capital barriers.
- CE marking expansion for powered systems:CE marking requirements under the EU Machinery Directive shape product access for electric and automated cutting systems, favoring early movers with certified equipment portfolios.
- Damascus steel artisan positioning:Damascus Steel materials capture margin pools among professional chef segments seeking performance differentiation through distinctive metallurgical aesthetics.
Industry Challenges
- Master bladesmith skill scarcity:Traditional forging expertise concentrates in aging practitioner pools across Solingen and Seki, constraining premium production scale-up.
- Multi-jurisdiction certification complexity:FDA guidelines in the United States specify surface finishes and corrosion resistance for food-contact blades, forcing dual-track testing for manufacturers serving both EU and US markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knife Market |
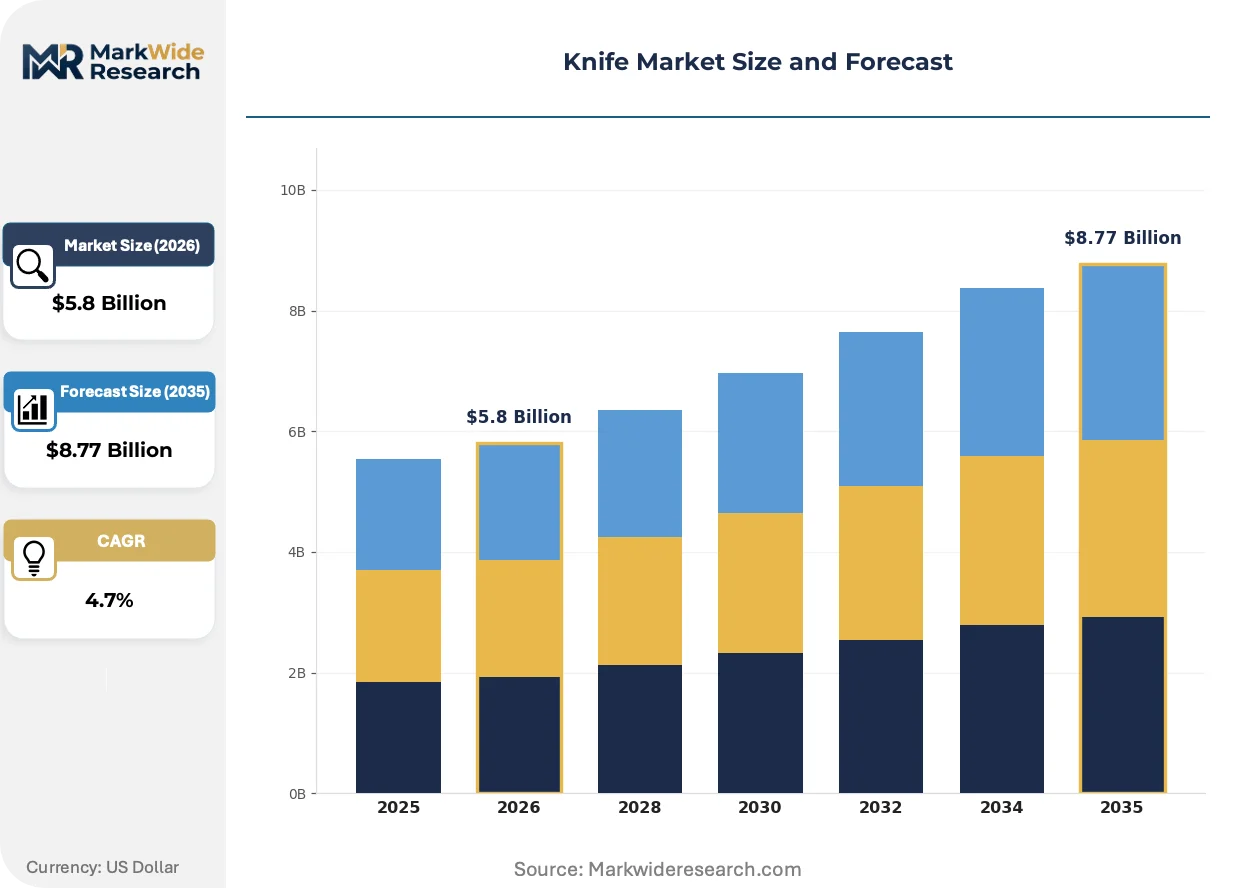
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chef's Knife, Paring Knife, Serrated Knife, Utility Knife Material: Stainless Steel, Carbon Steel, Ceramic, Damascus Steel Blade Type: Fixed Blade, Folding Blade, Electric Blade, Tactical Blade End User: Household, Commercial Kitchen, Outdoor, Professional Chef |
| Companies Covered | Spyderco, SOG Specialty Knives, Benchmade, Case, Kershaw, Buck Knives, Columbia River Knife & Tool, Microtech, Cold Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knife Market Emerging Trajectories
Active reshaping in the Knife Market centers on digital integration of production workflows, regulatory tightening of material provenance standards, and the unbundling of traditional distribution relationships between manufacturers and end-users.
Laser-guided grinding and robotic heat-treatment systems are digitizing quality control in blade manufacturing. Mid-tier producers in Taiwan and Japan are adopting these systems fastest, compressing variance in Rockwell hardness ratings and reducing manual inspection labor. This digitizing of production protocols is enabling smaller batches with consistent specifications, eroding the scale advantages previously held by volume-focused competitors.
EU REACH regulations are extending disclosure requirements to cover cobalt and nickel content in high-performance alloys. Manufacturers must now document smelting origins and chemical compositions through tier-two suppliers. European commercial kitchen equipment importers face the steepest compliance burden, with several reallocating procurement toward domestic European steel sources to reduce documentation risk.
Direct-to-chef subscription services are fragmenting the traditional distributor-wholesaler channel structure. Independent culinary professionals in urban centers now bypass restaurant supply houses, sourcing blades through specialized e-commerce platforms that offer sharpening credits and replacement warranties. This channel disintermediation is most visible in France and the Netherlands, where chef-owned independent restaurants concentrate in dense metropolitan corridors.
Knife Market Segmentation
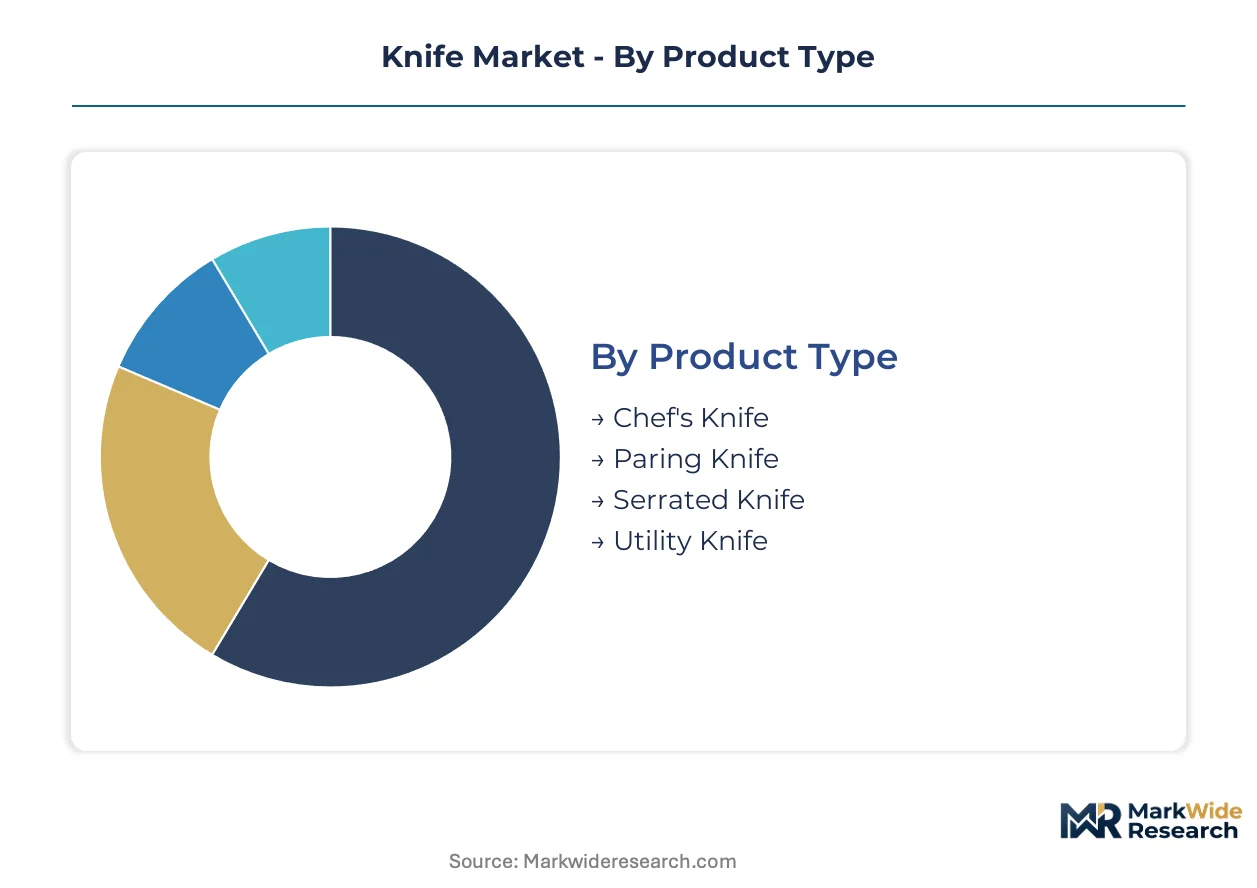
Knife market segmentation reveals distinct replacement cadences across product categories, with commercial kitchen equipment cycling faster than household inventory. Material selection and blade configuration further stratify procurement patterns between institutional buyers and enthusiast consumers.
Product Type:
Chef's Knives turn over fastest in professional settings where edge degradation triggers immediate replacement, while Paring Knives sustain longer utility cycles in residential applications.
- Chef's Knife:Broad 8-12 inch blades with Rockwell hardness ratings between 56-62 HRC deliver the primary cutting workhorse for protein and vegetable processing. Demand concentrates in Germany's hospitality construction pipeline where hotel kitchen fit-outs specify premium German or Japanese forged models to meet durability requirements under continuous use.
- Utility Knife:Mid-size 4-7 inch blades bridge precision tasks and general prep with versatile edge geometries. Commercial kitchens in France accelerate procurement of high-carbon utility variants as independent restaurants bypass traditional supply houses through direct-to-chef subscription platforms.
- Paring Knife:Compact 2-4 inch blades execute detailed peeling and coring work in residential and light commercial settings.
- Serrated Knife:Scalloped edges maintain cutting effectiveness on crusty breads and delicate skins without frequent sharpening.
Chef's Knife anchors the volume base while Utility Knife gains share at the steepest rate.
Material:
Cost tier stratification separates commodity stainless procurement from premium artisan materials, with certification burden heaviest on alloy traceability.
- Stainless Steel:Chromium-alloyed formulations between 12-18% content deliver corrosion resistance for food-contact applications under FDA guidelines. EU commercial kitchen importers face REACH documentation requirements for nickel and cobalt content, pushing procurement toward domestic European smelters to reduce tier-two supplier risk.
- Damascus Steel:Layered metallurgical construction produces distinctive wave patterns through repeated folding and forge-welding of contrasting carbon alloys. Professional chef segments in urban France and Netherlands concentrate demand through specialized e-commerce channels seeking performance differentiation through aesthetic distinction.
- Carbon Steel:Higher carbon content enables sharper edges with easier honing, though oxidation requires active maintenance.
- Ceramic:Zirconium dioxide compositions offer extreme edge retention without metal sourcing complexity.
Stainless Steel retains the dominant cost tier position while Damascus Steel commands the steepest premium expansion.
Blade Type:
Application context determines mechanical configuration, with powered systems facing distinct regulatory pathways from manual implements.
- Fixed Blade:Full-tang construction extends blade steel through the handle for maximum torque transmission and durability. Hunting and tactical applications in North American markets sustain higher average selling prices, while Solingen manufacturers supply professional butcher operations requiring impact-resistant designs.
- Folding Blade:Pivot mechanisms with locking systems enable safe pocket carry for everyday and outdoor utility. Spyderco's distinctive compression locks and Benchmade's axis mechanisms differentiate specialty retail positioning through ergonomic innovation.
- Electric Blade:Motorized cutting systems require CE marking under EU Machinery Directive for commercial kitchen access.
- Tactical Blade:Specialized geometries prioritize rapid deployment and grip security for security and emergency applications.
Fixed Blade sustains premium positioning while Folding Blade expands volume through everyday carry adoption.
End User:
Customer type segmentation aligns procurement authority with performance specifications, separating institutional specification from individual preference.
- Commercial Kitchen:Hospitality sector buyers specify NSF-certified blades with documented corrosion resistance and dishwasher compatibility. Asset-light leasing models reshape access patterns as restaurant groups reduce upfront capital barriers through equipment-as-a-service arrangements.
- Professional Chef:Independent culinary professionals source through disintermediated channels, prioritizing edge geometry and handle ergonomics over brand recognition. Sharpening credits and replacement warranties from specialized platforms capture loyalty in dense metropolitan corridors.
- Household:Residential consumers balance initial cost against perceived durability in retail environments.
- Outdoor:Camping and hunting enthusiasts prioritize corrosion resistance and multi-function versatility in field conditions.
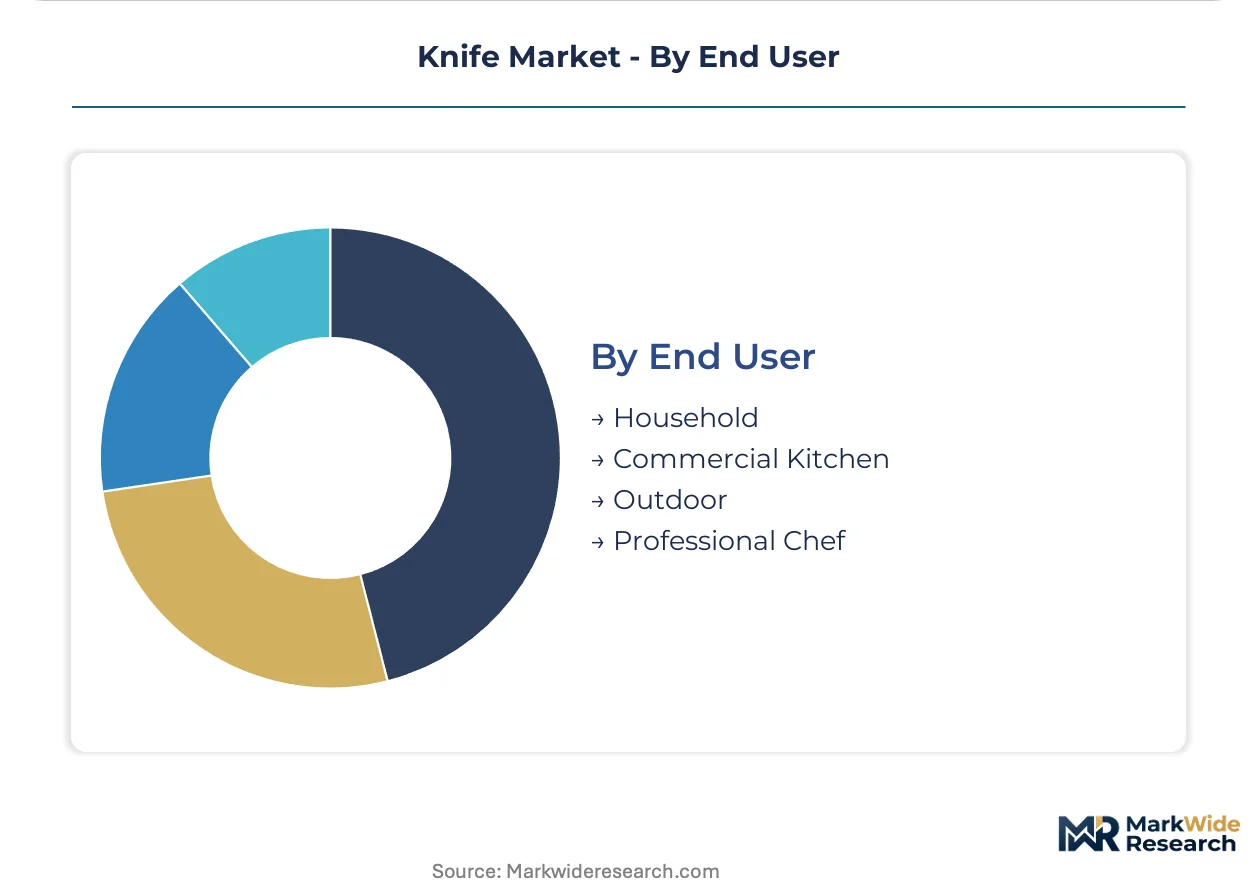
Commercial Kitchen anchors institutional volume while Professional Chef segments expand most quickly through channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a knife trade surplus driven by Solingen's precision manufacturing exports, while the United States and Japan balance specialized imports against domestic premium production. France and the Netherlands exhibit rising direct-to-chef procurement that bypasses traditional import channels.
Germany
Hotel and restaurant construction in Berlin and Munich accelerates commercial kitchen fit-outs specifying forged chef's knives with 56-62 HRC ratings. EU Green Deal material sourcing mandates force requalification of chromium and vanadium supply chains through documented smelting origins. Solingen's precision manufacturing clusters attract specialized tooling investments from adjacent metalworking industries seeking blade-making expertise.
United States
Outdoor recreation and tactical applications sustain higher average selling prices for fixed-blade designs in North American markets. FDA surface finish and corrosion resistance guidelines govern food-contact blade specifications, forcing dual-track testing for exporters serving European markets. Oregon-based manufacturers leverage in-house production over captive supply networks to sustain quality control across specialty lines.
Japan
Traditional forging expertise concentrates in Seki City's aging practitioner pools, constraining premium production scale-up for global export demand. METI industrial standards shape domestic quality benchmarks that influence international perception of Japanese blade craftsmanship. Mid-tier producers in Gifu Prefecture adopt laser-guided grinding systems fastest, compressing variance in Rockwell hardness ratings.
France
Independent restaurants in Paris and Lyon concentrate demand for high-carbon utility variants sourced through disintermediated subscription platforms. ECHA REACH chemical composition disclosure requirements extend to cobalt and nickel content in high-performance alloys imported from Asian suppliers. Dense metropolitan corridors enable chef-owned independents to bypass traditional restaurant supply houses entirely.
Netherlands
Amsterdam and Rotterdam hospitality groups pilot asset-light leasing models for commercial kitchen equipment, reducing upfront capital barriers for premium cutlery access. CE marking requirements under the EU Machinery Directive shape procurement criteria for electric and automated cutting systems in institutional kitchens. Specialized e-commerce platforms offering sharpening credits capture loyalty among urban culinary professionals.
Knife Market Vendor Landscape
On the supply side, the industry is bifurcated between heritage manufacturers with generational forging expertise and digitally native specialists leveraging direct distribution channels. Consolidation pressure concentrates among mid-tier producers facing compliance cost absorption from EU material traceability mandates. Three archetypes dominate: Solingen-based precision forgers, Oregon-centered vertically integrated producers, and Taiwan-Japan mid-tier adopters of robotic quality control. M&A activity targets specialized heat-treatment capabilities, while strategic partnerships secure certified European steel sources ahead of enforcement deadlines.
Within the heritage-forging tier, Benchmade and Spyderco exemplify distinct positioning strategies. Benchmade anchors Oregon-based manufacturing with in-house production control over tactical and outdoor lines. Spyderco occupies a position defined by ergonomic innovation and distinctive blade geometries that differentiate specialty retail presence. Cold Steel represents the scale-driven archetype with broad portfolio diversification across price tiers. These three fabricators illustrate how geographic concentration, design specialization, and volume scale create defensible market positions against regulatory and competitive pressure.
| Leading Market Players |
|---|
| Spyderco |
| SOG Specialty Knives |
| Benchmade |
| Case |
| Kershaw |
| Buck Knives |
| Columbia River Knife & Tool |
| Microtech |
| Cold Steel |
| Others |
Supply Flow & Price Mechanics
Rhine-Alpine corridor freight costs from Solingen to Rotterdam terminals compress margin pools for mid-tier forged blades while amplifying price spreads between artisan Damascus outputs and commodity stainless imports. EU Green Deal documentation requirements for chromium traceability force distributors to absorb certification overhead or pass through tiered premiums to hospitality procurement teams.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in commercial kitchen equipment. Price differentiation rests on Rockwell hardness certification tiers and NSF compliance documentation, with Solingen-origin brands commanding 40-60% premiums over Taiwanese robotic-ground alternatives. Cost compression in standard-grade stainless is intensifying because REACH nickel disclosure extends development timelines. Quick-service restaurant chains exhibit highest price sensitivity, while independent chef-owned establishments in Paris and Lyon prioritize edge geometry over unit cost.
Supply Chain Analysis
Solingen-based master forges and Seki City specialty houses concentrate premium blade capacity, while Gifu Prefecture mid-tier producers and Taiwanese robotic-grinding facilities supply volume tiers. Raw material flows draw from German chromium stockholders, Swedish powder metallurgy inputs, and Japanese high-carbon steel sources. Single-source vulnerability concentrates in aging Seki bladesmith pools, where generational expertise constrains artisan production scale-up. Distribution runs through traditional restaurant supply houses, though direct-to-chef subscription platforms in France and the Netherlands fragment channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Knife market fragmentation creates opportunity niches as direct-to-chef procurement disintermediates legacy distributor relationships. Channel control splinters across specialized e-commerce platforms, asset-light leasing operators, and heritage forge direct sales.
For Market Incumbents: Pre-empt ceramic blade substitution in enthusiast segments by accelerating Damascus steel artisan certification programs. Secure captive supply of documented European chromium sources before REACH enforcement deadlines tighten. Vertical integration into in-house heat-treatment capabilities defends margin position against mid-tier robotic-grinding competitors from Taiwan.
For New Entrants and Emerging Players: Establish a beachhead in asset-light leasing models for independent restaurant groups in Amsterdam and Rotterdam corridors. Target professional chef segments through sharpening-credit subscription platforms, bypassing traditional supply house relationships entirely. Go-to-market leverage centers on replacement warranty bundling with specialized e-commerce fulfillment.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-held commercial kitchen equipment divisions lacking blade-specific certification expertise. Long-term viability favors specialized heat-treatment capabilities and documented European steel sourcing relationships. Monitor ECHA REACH enforcement cadence as inflection signal for compliance-cost absorption capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Steel Sourcing | EU Green Deal traceability mandates favor early movers with documented smelting origins from German and Swedish suppliers. |
| Direct-to-Chef Subscription Platform Launch | Channel disintermediation in Paris and Lyon metropolitan corridors captures loyalty through sharpening credits and replacement warranties. |
| Robotic Grinding System Adoption | Taiwanese and Japanese mid-tier producers compress Rockwell hardness variance, eroding scale advantages of volume-focused competitors. |
| Damascus Steel Artisan Certification Program | Professional chef segments in urban France and Netherlands pay premiums for aesthetic distinction through layered metallurgical construction. |
| Asset-Light Leasing Model Expansion | Amsterdam and Rotterdam hospitality groups reduce upfront capital barriers while locking in long-term blade replacement revenue streams. |
Methodological Framework
Operator-level perspectives from executive chefs, commercial kitchen procurement directors, restaurant supply house category managers, and master bladesmiths anchored the qualitative base. Secondary validation drew from ECHA REACH substance databases, EU customs trade flows for cutlery classifications, FDA food-contact surface guidelines, and hospitality construction permits in Berlin, Munich, Paris, and Lyon. Bottom-up segment sizing triangulated against top-down market value estimates across product type, material grade, and end-user category dimensions.
Scenario-bracketing framed projections across the analysis window, modeling low-case ceramic substitution acceleration against high-case artisan premium expansion. Segmentation dimensions spanned blade configuration, Rockwell hardness tier, NSF certification status, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis in commercial kitchen settings and adoption curve modeling for direct-to-chef channels. Forecast inputs incorporated EU Green Deal enforcement phasing and REACH disclosure timeline extensions.
Stress conditions across alloy price volatility, master bladesmith attrition rates, and channel disintermediation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement cadence and hospitality construction pipelines. Quarterly review of ECHA substance restriction proposals and chef-owned independent restaurant openings in dense metropolitan corridors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Insulated Water Bottles Market
Household Items
Memory Foam Market
Household Items
South Korea Cookware Market
Household Items
Facial Tissue Paper Market
Household Items
Thermos Bottle Market
Household Items
India Digital Showers Market
Household Items
Qatar Gas Hobs Market
Household Items
Mexico Cookware Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Laundry Detergent Sheets Market
Household Items
Smart Toilet Market
Household Items
Smart Memory Foam Market
Household Items
Air Mattress Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Liquid Hand Soap Market
Household Items
Floor-Standing Integrated Smart Toilet Market