
 Smartphone Console Market | 2026-2036
Smartphone Console Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Console Market Insights
EU RoHS and REACH compliance requirements for electronics is expanding the addressable market for certified peripheral manufacturers. GameSir leverages in-house controller calibration to meet these standards across European distribution channels. Razer anchors its position through premium materials sourcing that satisfies ECHA substance restrictions. Flydigi competes on price-performance ratios while navigating the same regulatory thresholds.
Smartphone consoles are dedicated gaming peripherals that pair with mobile devices via Bluetooth, USB-C, or proprietary low-latency protocols to deliver tactile input for cloud-streamed and locally rendered titles. These devices typically incorporate hall-effect joysticks, programmable rear paddles, and passthrough charging to sustain extended gameplay sessions without thermal throttling the host phone. Handheld consoles within the product type category capture the highest margin pools due to integrated compute and display components. Cross-platform compatibility is accelerating fastest as consumers reject ecosystem-locked accessories. Cloud gaming as a segment is maturing rapidly with infrastructure investments from hyperscalers.
FCC equipment authorization governs radio frequency emissions for smartphone consoles sold in the United States, while CE marking and the EU's Radio Equipment Directive shape market access across European member states. China's MIIT enforces GB standards for wireless transmission power that directly affect controller range and battery life specifications. Stakeholders must monitor evolving right-to-repair legislation across multiple jurisdictions, as repairability mandates threaten to reshape hardware architectures and aftermarket service economics.
Market Dynamics
Cloud gaming infrastructure from hyperscalers is compressing hardware requirements while simultaneously expanding the addressable base for tactile peripherals, forcing smartphone console makers to optimize for latency rather than compute.
Growth Catalysts
- EU AI Act compliance:Hardware-software integration mandates under this framework are accelerating certified controller development cycles for European distribution.
- Hall-effect sensor adoption:Drift-resistant magnetic sensing technology is eliminating mechanical wear failure modes in premium controller tiers.
- Shenzhen manufacturing clusters:Concentrated PCB assembly and joystick module production in China's Pearl River Delta compress component lead times.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings for hall-effect joysticks create margin pressure on mid-range hardware.
- FCC equipment authorization timelines:Radio frequency testing queues for Bluetooth 5.3 controllers delay US market entry by 8-14 weeks.
- Touchscreen substitution:Haptic feedback improvements in flagship smartphones reduce perceived value-add of external controllers for casual sessions.
Strategic Opportunities
- Right-to-repair mandates:Emerging EU and US state-level repairability requirements favor modular controller architectures with swappable thumbstick modules.
- Passthrough charging standardization:USB-C PD integration at 45W+ enables docked-console use cases previously reserved for dedicated handhelds.
- Cross-platform protocol unification:DirectInput and HID++ convergence allows single-controller deployment across cloud streaming services and native mobile titles.
Industry Challenges
- Firmware security certification:GB standards from China's MIIT mandate encrypted wireless stacks that extend development cycles.
- Controller-to-cloud latency budgeting:Engineering teams must reconcile local input polling with variable network round-trip times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Console Market |
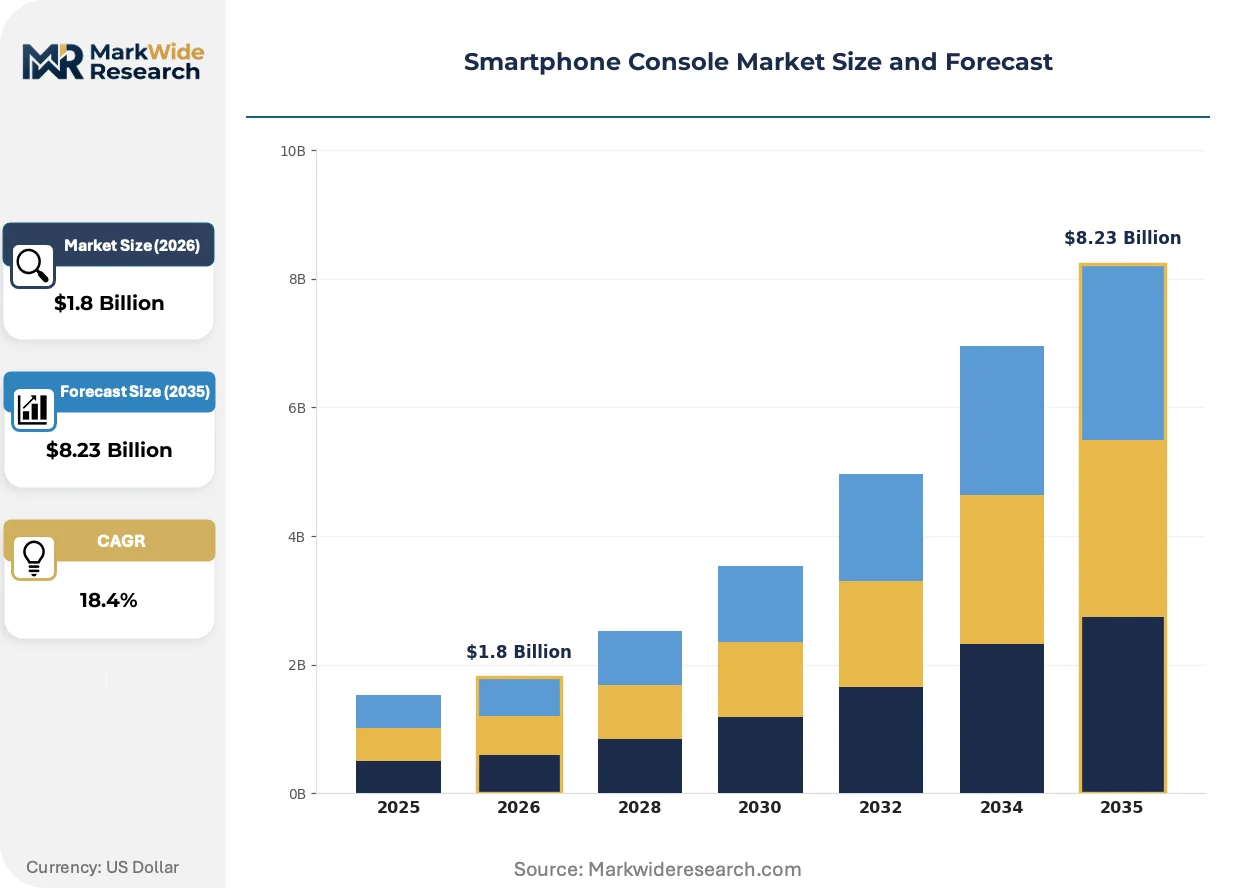
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Gaming, Handheld Consoles, Mobile Accessories, Game Streaming Services Compatibility: iOS, Android, Cross-Platform, Gaming PC Distribution Channel: Online Retail, Brick & Mortar Stores, Direct Sales, Digital Downloads Customer Type: Casual Gamers, Professional Gamers, Families, Tech Enthusiasts |
| Companies Covered | GameSir, Flydigi, Razer, SteelSeries, 8BitDo, Betop, Gamevice, Beboncool, IPEGA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Console Market Trends and Innovations
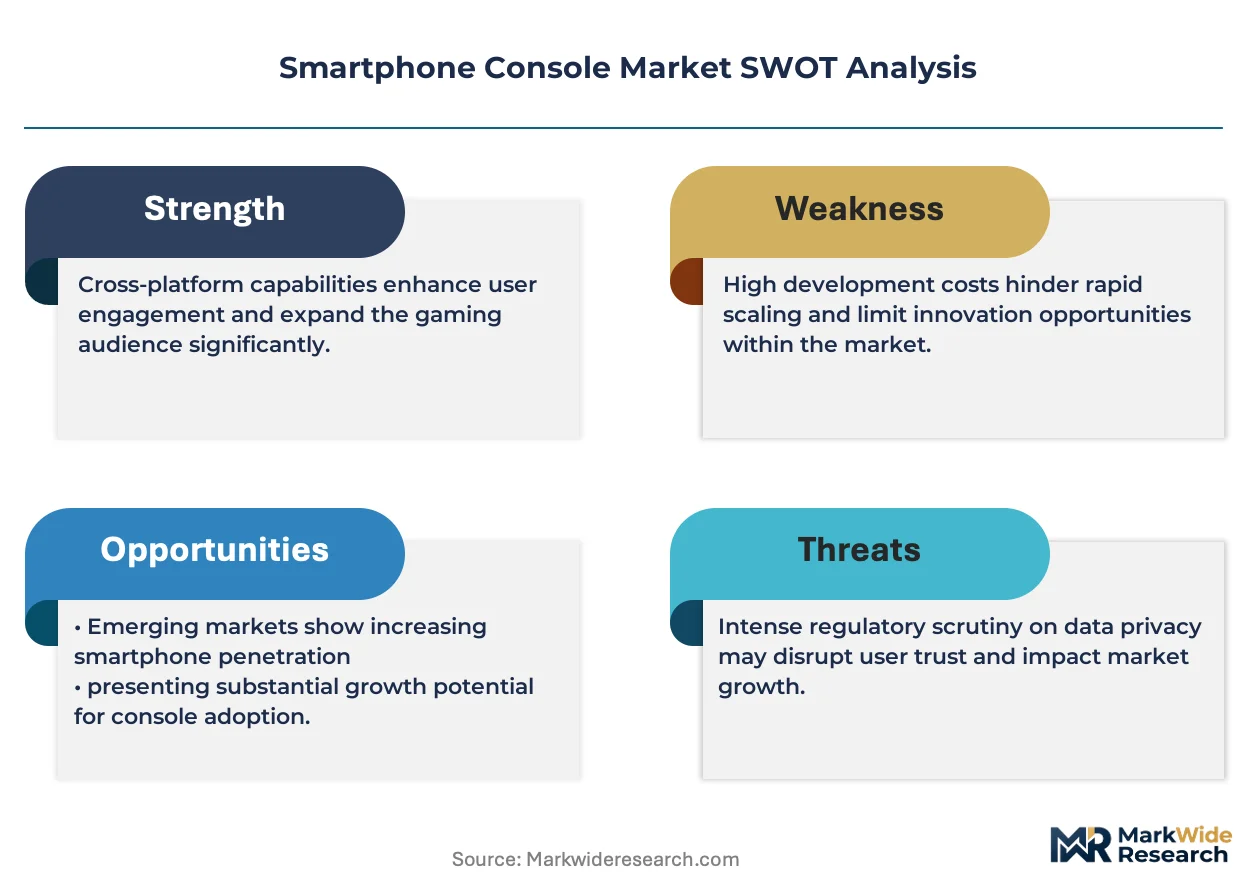
Latency optimization and regulatory compliance are converging to reshape hardware architectures, with manufacturers racing to embed adaptive protocols while navigating fragmented certification requirements across major economies.
Hall-effect magnetic sensing is integrating drift-free position tracking into mainstream controller tiers. Cloud gaming subscribers adopting premium subscription tiers are demanding this reliability feature at mid-range price points. The technology is integrating previously separate calibration and durability value propositions into single SKUs.
REACH substance restrictions from ECHA are forcing reformulation of elastomer grip compounds and PCB flame retardants. Manufacturers serving European channels must resubmit material safety datasheets biannually. Handheld console variants with integrated batteries face the steepest compliance burden due to cell chemistry disclosure requirements.
Direct-to-gamer subscription bundling is displacing retail channel dependence for controller distribution. Cloud gaming platform operators are white-labeling peripherals as onboarding incentives. This pattern is most visible in China, where domestic streaming services leverage manufacturing proximity to customize hardware at volume.
Smartphone Console Market Segmentation
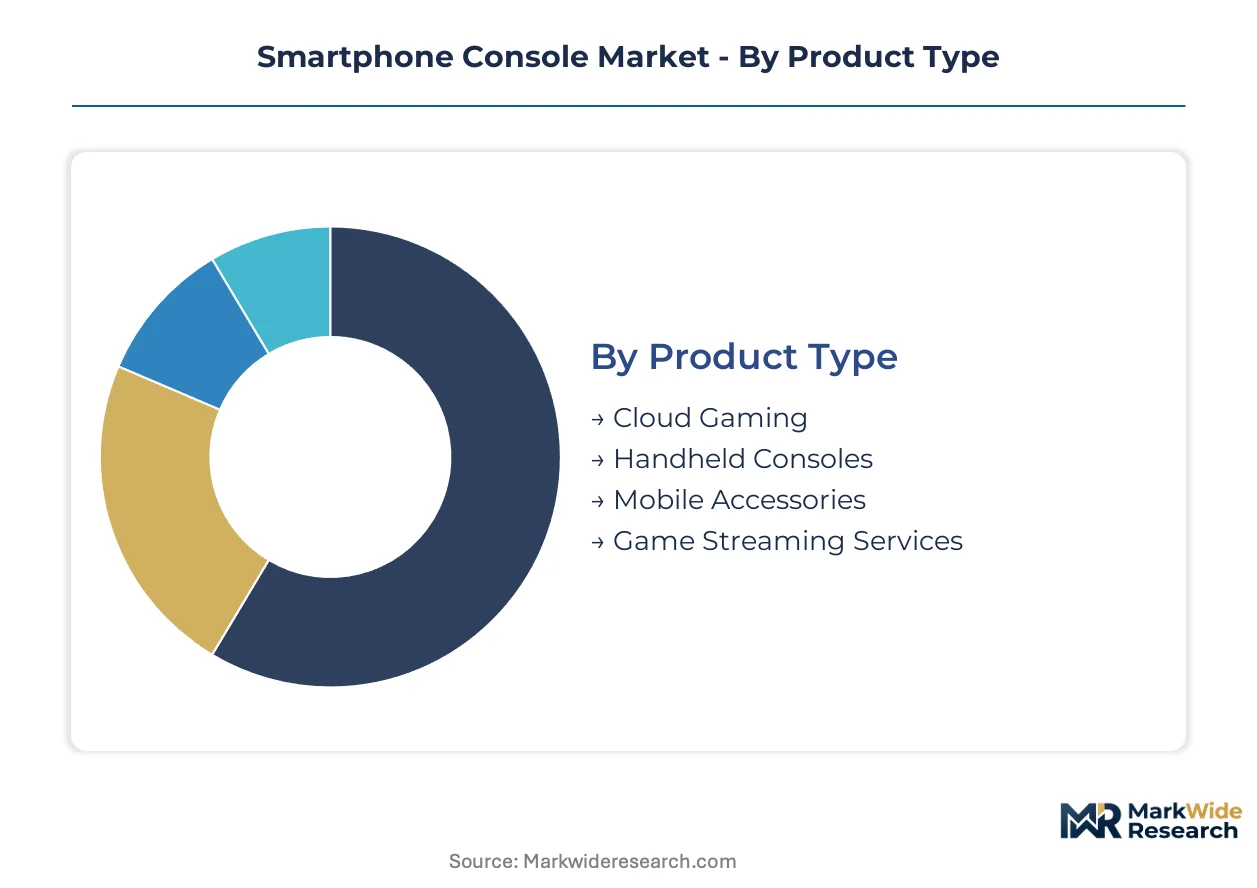
Segmentation in the smartphone console market reveals how certification requirements, latency specifications, and distribution economics fragment addressable demand. Each dimension carries distinct regulatory loads and margin structures that shape vendor prioritization.
Product Type:
CE marking under the EU's Radio Equipment Directive and FCC equipment authorization in the United States impose tiered compliance burdens across hardware categories. Handheld consoles face the steepest battery chemistry disclosure requirements under ECHA REACH, while cloud gaming peripherals prioritize radio frequency stability over integrated compute.
- Cloud Gaming:Peripherals optimized for hyperscaler streaming infrastructure emphasize sub-20ms input latency and adaptive bitrate synchronization. Demand concentrates among casual gamers in China leveraging domestic cloud infrastructure from Tencent and Alibaba.
- Handheld Consoles:Integrated compute-and-display units incorporate ARM-based SoCs, hall-effect joysticks, and passthrough charging at 45W+. European distribution requires full ECHA substance documentation for elastomer grips and lithium cell chemistries.
- Mobile Accessories:Bluetooth 5.3 controllers and clip-on cooling fans serve the broadest price-performance spectrum.
- Game Streaming Services:Platform-agnostic subscription bundles increasingly white-label hardware as onboarding incentives.
Handheld Consoles sits at the top of the volume ranking, with Cloud Gaming climbing the fastest.
Compatibility:
Protocol fragmentation across mobile ecosystems drives SKU proliferation and firmware branching costs. iOS mandates MFi certification for low-latency controller protocols, while Android's HID++ openness enables faster hardware iteration cycles.
- iOS:Apple's MFi program enforces encrypted authentication chips and fixed button mapping schemas that extend development timelines. Demand clusters in North American and Japanese premium tiers where iPhone penetration peaks.
- Android:Open HID++ implementation allows direct firmware updates and custom key remapping without platform gatekeeping. Chinese OEMs leverage this flexibility for rapid feature deployment.
- Cross-Platform:Single-controller deployment across mobile, PC, and console ecosystems is gaining share fastest as consumers reject ecosystem lock-in.
- Gaming PC:XInput and DirectInput backward compatibility targets Steam Link and Moonlight streaming users.
Android leads absolute shipment volume, with Cross-Platform expanding most quickly.
Distribution Channel:
Channel economics diverge sharply on return rates, warranty exposure, and firmware update reach. Direct sales capture the highest margin pools but demand captive logistics infrastructure.
- Online Retail:Amazon and domestic Chinese platforms dominate volume, with review velocity driving algorithmic visibility. Return rates run higher due to fit uncertainty with specific phone models.
- Brick & Mortar Stores:Physical touchpoints allow haptic evaluation of grip ergonomics and joystick resistance. European electronics chains increasingly demand RoHS documentation at point of stocking.
- Direct Sales:Manufacturer-owned storefronts and subscription bundling bypass platform fees and enable firmware update push notifications.
- Digital Downloads:Software-only controller configuration apps and cloud gaming subscriptions without hardware attachment.
Online Retail holds the volume crown, with Direct Sales gaining share fastest.
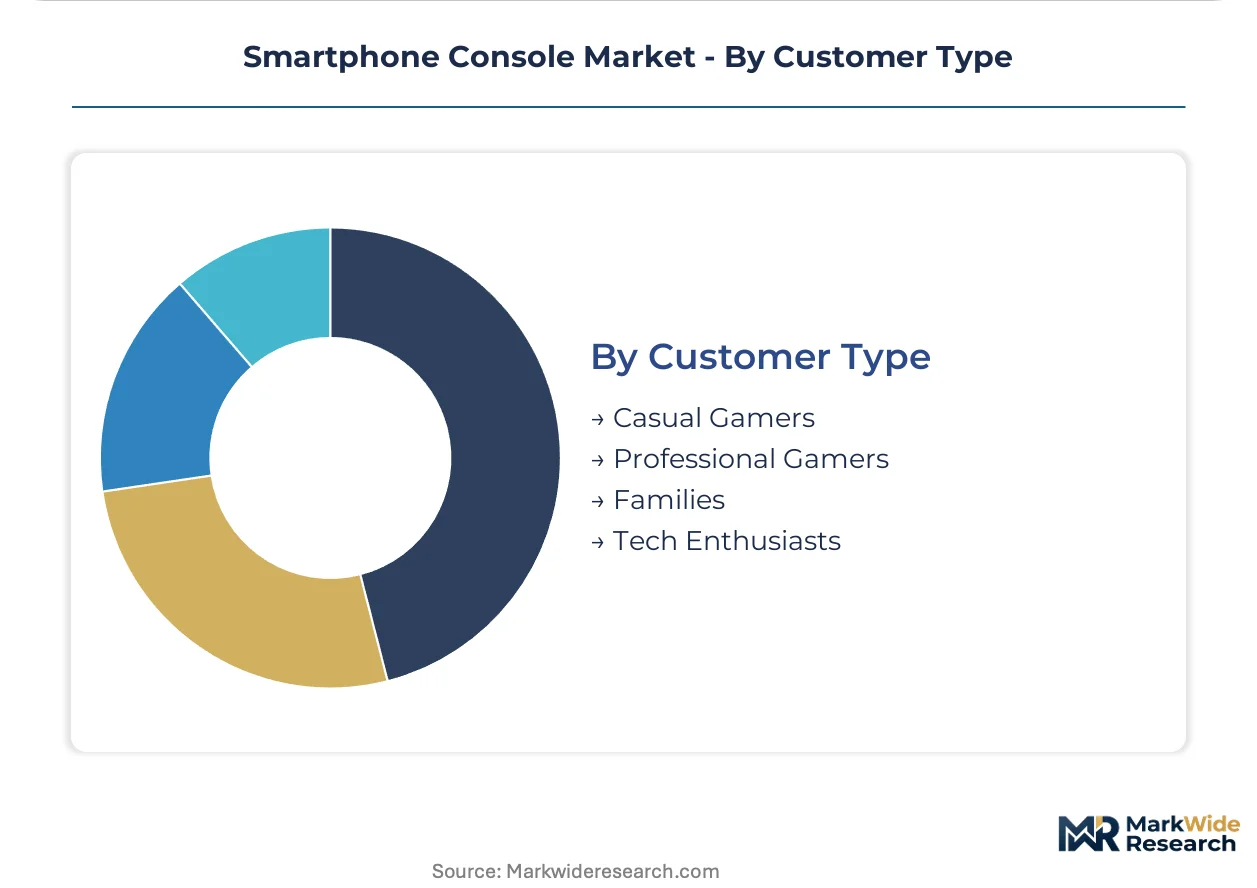
Customer Type:
Purchasing behavior splits on price sensitivity, feature depth tolerance, and ecosystem commitment length. Professional gamers demand replaceable components and tournament-grade latency guarantees unavailable to casual tiers.
- Casual Gamers:Price-elastic buyers prioritizing plug-and-play simplicity over calibration depth. This segment is expanding most quickly as cloud gaming lowers entry barriers across emerging markets.
- Professional Gamers:Esports competitors requiring sub-10ms polling rates, swappable thumbstick modules, and firmware audit trails for tournament compliance. Concentrated in South Korea, Japan, and Nordic training facilities.
- Families:Multi-user households favoring durable construction and parental control integration over performance specifications.
- Tech Enthusiasts:Early adopters of hall-effect sensors, rear paddle configurations, and open-source firmware platforms.
Casual Gamers dominates absolute addressable base, with Professional Gamers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's manufacturing ecosystem birthed the smartphone console industry during the mid-2010s mobile gaming boom, with Pearl River Delta factories now supplying hardware to streaming platforms worldwide.
China
Domestic cloud gaming subscribers from Tencent and Alibaba drive peripheral demand across tier-one cities. MIIT enforces GB standards for wireless transmission power that constrain controller range specifications. Shenzhen manufacturing clusters compress PCB assembly lead times while serving both domestic platforms and export markets.
United States
iPhone penetration in coastal metropolitan areas sustains premium controller demand for Apple Arcade and Xbox Cloud Gaming. FCC equipment authorization timelines for Bluetooth 5.3 controllers delay market entry by 8-14 weeks. Austin and Seattle tech corridors host hyperscaler engineering teams optimizing latency budgets for mobile streaming.
Germany
Steam Deck adoption in Berlin and Munich creates adjacent demand for smartphone-compatible peripherals. ECHA REACH mandates biannual resubmission of material safety datasheets for elastomer grip compounds. Bavaria's electronics distribution hubs enforce RoHS documentation at point of stocking for retail channel access.
Japan
Professional esports training facilities in Tokyo and Osaka require sub-10ms polling rates for tournament-grade hardware. METI oversees consumer electronics safety standards affecting battery chemistry disclosures. Kansai manufacturing subcontractors supply precision joystick modules to domestic and international brands.
South Korea
5G infrastructure density in Seoul enables low-latency cloud gaming adoption among mobile-first consumers. MFDS regulates lithium cell safety for handheld console variants with integrated batteries. Pangyo Techno Valley hosts R&D centers developing adaptive bitrate synchronization protocols for streaming peripherals.
Smartphone Console Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and sensor technology tiers. The vendor base stratifies into three density layers: Shenzhen-based OEMs serving white-label contracts, mid-tier specialists balancing price-performance ratios, and premium brands commanding materials sourcing premiums. Two strategic archetypes dominate: hall-effect sensor integrators targeting drift-resistant reliability, and protocol-agnostic platform builders optimizing for cross-compatibility. Competitive moves concentrate on M&A for joystick module capabilities and strategic partnerships with cloud gaming operators for subscription bundling.
Among the named specialists, GameSir occupies a position within the calibration-centric tier, Flydigi exemplifies price-performance optimization for emerging market penetration, and Razer anchors the premium materials sourcing segment. These three represent distinct competitive vectors rather than overlapping positioning, with each archetype commanding different margin structures and certification investment profiles.
| Leading Market Players |
|---|
| GameSir |
| Flydigi |
| Razer |
| SteelSeries |
| 8BitDo |
| Betop |
| Gamevice |
| Beboncool |
| IPEGA |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between premium hall-effect tiers and commodity potentiometer alternatives splits both margin structures and sourcing strategies across the smartphone console industry. Premium controllers command materials sourcing premiums for neodymium magnets and ECHA-compliant elastomers while Shenzhen-based OEMs optimize for Pearl River Delta assembly economies at volume.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by sensor technology and regulatory compliance depth. Premium tiers absorb hall-effect module costs and FCC/CE certification investments, while economy SKUs compete on Shenzhen manufacturing scale. Cost compression in mid-range tiers intensifies because touchscreen haptics reduce perceived controller value-add. Casual gamers exhibit highest price sensitivity, demanding sub-$30 entry points, whereas professional esports facilities accept $150+ tournament-grade hardware with swappable modules and firmware audit trails.
Supply Chain Analysis
Freight cost volatility from Pearl River Delta export hubs to European and North American distribution centers compresses margin buffers on low-density controller shipments. Component sourcing concentrates in China for PCB assembly and joystick module production, Japan for precision sensor subassemblies, and South Korea for lithium cell integration. Neodymium magnet supply draws from Chinese rare earth processing facilities, creating tariff exposure under evolving trade frameworks. Distribution runs through Amazon and domestic Chinese platforms for volume, with direct-to-gamer subscription bundling capturing highest-margin white-label contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartphone console market functions as a stable compounder anchored by cloud gaming infrastructure expansion from Tencent, Microsoft, and Amazon. Hyperscaler streaming investments sustain peripheral demand through hardware-software bundling economics.
For Market Incumbents: Deploy hall-effect sensor integration as a defensive moat against touchscreen substitution threats. Prioritize M&A for joystick module capabilities to secure captive supply of drift-resistant magnetic sensing components. Deepen backward integration into Shenzhen PCB assembly to compress lead times against emerging OEM competitors.
For New Entrants and Emerging Players: Capture white-space in right-to-repair compliant modular controllers for EU distribution. Target professional esports training facilities in South Korea and Japan with sub-10ms polling rate guarantees. Pursue direct-to-gamer subscription bundling partnerships with domestic Chinese cloud gaming platforms as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where joystick module specialization overlaps with firmware security certification capabilities for MIIT GB standards compliance. The five-to-ten year viability window favors acquisition targets with established ECHA REACH documentation workflows and European retail channel relationships. Monitor passthrough charging standardization at 45W+ as the inflection signal for docked-console use case expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hall-Effect Sensor Integration | Eliminates drift failure modes for cloud gaming subscribers demanding reliability at mid-range price points. |
| Right-to-Repair Modular Design | Aligns hardware architectures with emerging EU and US state-level repairability mandates for retail access. |
| Subscription Bundling Partnerships | Displaces retail channel dependence through white-label controller distribution with Tencent and Alibaba platforms. |
| Cross-Platform Protocol Unification | Enables single-controller deployment across iOS MFi, Android HID++, and PC DirectInput ecosystems. |
| Passthrough Charging Standardization | Unlocks docked-console use cases at 45W+ USB-C PD previously reserved for dedicated handhelds. |
Research Methodology
Bottom-up cloud gaming subscriber modeling reconciled against top-down Shenzhen manufacturing output tracking forms the analytical core of this study. Primary interviews with hardware product managers at peripheral OEMs, regulatory compliance officers at ECHA-notified bodies, procurement leads at cloud gaming platforms, and distribution channel partners at European electronics chains informed demand-side assumptions. Secondary validation drew from FCC equipment authorization databases, MIIT GB standard filings, SEC 10-K disclosures from listed gaming hardware firms, and hyperscaler capex announcements for streaming infrastructure.
Input-output matrices map controller shipment volumes against cloud gaming subscription growth, segmentation by sensor technology tier, compatibility protocol, and regional regulatory cluster. CAGRs were derived from regression analysis of historical peripheral adoption rates against streaming platform user expansion. Forecast inputs include neodymium price indices for hall-effect joystick cost modeling and FCC authorization queue lengths for US market entry timing.
Rare earth magnet volatility, right-to-repair legislative acceleration, and touchscreen haptic advancement are the dominant revision risks across the projection horizon. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Tablet Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
United States Stylus Pen Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Nanopresso Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Earphones Market