
 Dry Vacuum Cleaner Market | 2026-2036
Dry Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Vacuum Cleaner Market Foresight
The EU Ecodesign Directive is pivoting the cost-of-entry calculus for motor efficiency compliance across the European supply base. Dyson leverages proprietary digital motor technology to sustain premium positioning against regulatory thresholds. SharkNinja competes through agile product cycles that navigate evolving energy-label requirements without heavy R&D infrastructure.
Dry vacuum cleaners are suction-based cleaning appliances engineered to remove particulate matter from surfaces without liquid recovery, typically employing airflow rates between 30 and 150 cubic feet per minute depending on duty class. Their primary commercial purpose spans debris extraction in residential, commercial, and industrial environments where moisture-sensitive substrates prohibit wet-system deployment. Robotic units within the product type dimension are capturing disproportionate investment as autonomous navigation and LiDAR mapping mature, while canister formats retain margin concentration in European commercial channels where maneuverability commands price premiums. The application dimension shows industrial segments anchoring replacement demand in Germany and Japan, whereas residential robotic adoption accelerates fastest among cleaning services in US metropolitan corridors.
EPA Energy Star certification in the US, EU Ecodesign Directive compliance, and China's GB standards for electromagnetic compatibility collectively shape product architecture, testing protocols, and market access timelines across the three largest manufacturing basins. These frameworks force component-level redesigns of motors, filters, and control boards before products qualify for retail placement or institutional procurement. Stakeholders must monitor divergence between regional efficiency metrics and electromagnetic thresholds to avoid stranded inventory in cross-border fulfillment channels.
Market Dynamics
The EU Ecodesign Directive's motor efficiency mandates are compressing legacy brushed-motor supply chains while accelerating brushless DC platform transitions across European manufacturing bases. Factory automation in Germany's industrial corridor is simultaneously pulling heavy-duty extraction systems into sustained replacement cycles.
Growth Catalysts
- EU Ecodesign Directive:Tightening motor efficiency thresholds force component-level redesigns that favor brushless DC architectures, expanding addressable market for compliant OEMs.
- Commercial cleaning services:Robotic unit procurement accelerates across US metropolitan corridors as autonomous navigation and LiDAR mapping mature.
- Germany's factory automation:Industrial segments anchor replacement demand for heavy-duty dry extraction systems in moisture-sensitive manufacturing environments.
Market Restraints
- Rare-earth magnet supply:Brushless DC motor production depends on neodymium-dysprosium supply chains concentrated in China's processing corridor, exposing manufacturers to input cost volatility.
- REACH compliance:European chemical registration requirements create regulatory friction for filter material innovations and polymer formulations.
- Wet-dry hybrids:Multi-surface cleaning appliances threaten substitution in residential segments where moisture tolerance is less constrained.
Strategic Opportunities
- India's BIS certification:Electromagnetic compatibility standardization creates first-mover advantage for OEMs establishing local testing infrastructure ahead of mandatory implementation.
- LiDAR-IMU convergence:Sensor fusion advances enable robotic navigation in unstructured industrial environments previously requiring human operation.
- Equipment-as-service models:Cleaning service procurement is shifting from capital purchase to subscription-based fleet management, opening recurring revenue streams.
Industry Challenges
- Embedded firmware talent:Robotic control systems require scarce expertise in simultaneous localization and mapping algorithms, constraining product development velocity.
- Cross-border certification timelines:Divergence between EPA Energy Star, EU Ecodesign, and China's GB standards forces redundant testing protocols that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Vacuum Cleaner Market |
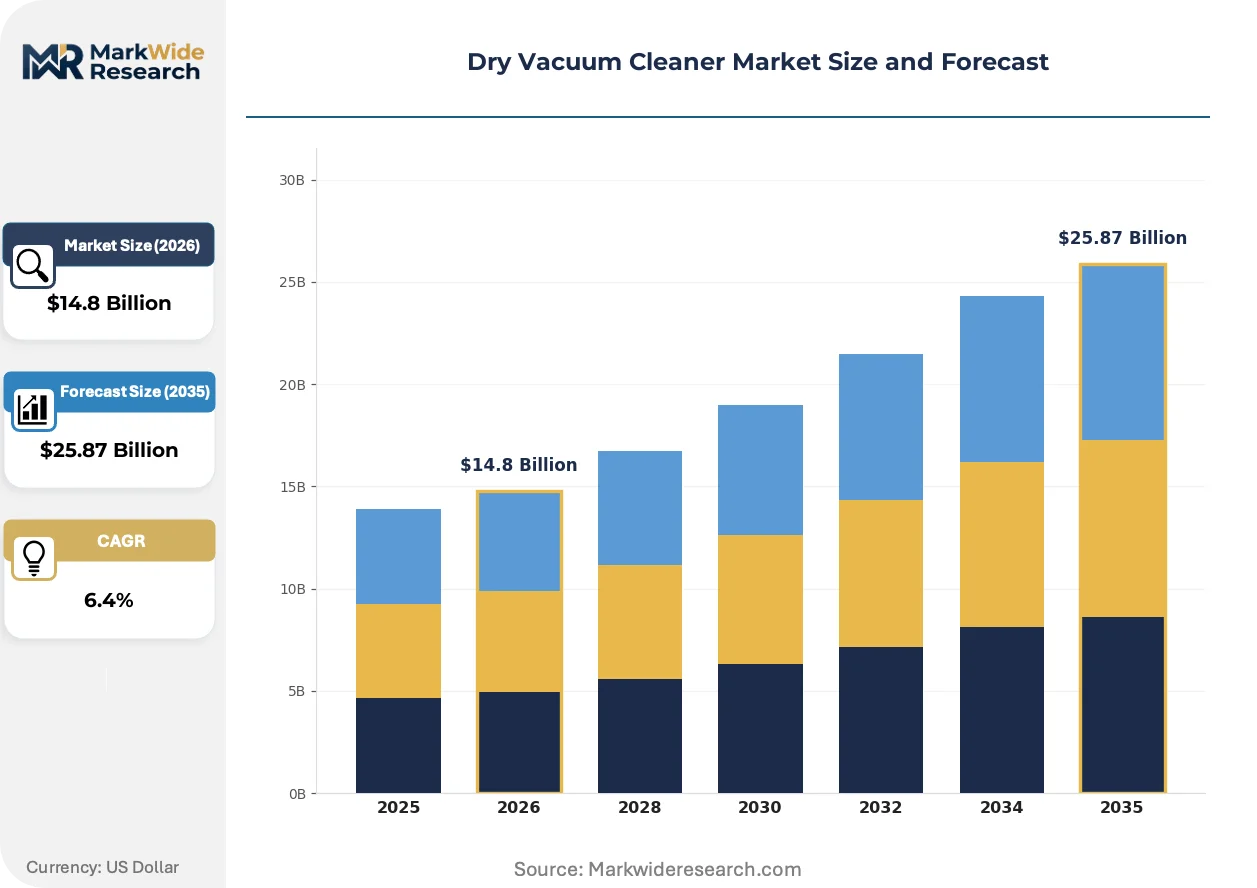
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Handheld Application: Residential, Commercial, Industrial, Automotive Technology: Cyclonic, Bagged, Bagless, Wet/Dry Customer Type: Homeowners, Cleaning Services, Retailers, Contractors |
| Companies Covered | Dyson, SharkNinja, Bissell Homecare, iRobot, Electrolux, Alfred Karcher SE & Co. KG, Nilfisk A/S, Tennant Company, Stanley Black & Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Vacuum Cleaner Market Shifts & Advancements
Brushless DC motor platforms are displacing legacy universal motors across efficiency-sensitive segments while robotic navigation systems penetrate industrial environments previously resistant to automation. Regulatory frameworks in Europe and North America are tightening concurrently, forcing synchronized product architecture redesigns.
Brushless DC motor technology delivers airflow rates between 30 and 150 cubic feet per minute with substantially higher efficiency than brushed alternatives. Industrial cleaning contractors and facility managers are adopting these platforms for sustained-duty applications. The technology is expanding into heavy-duty canister formats previously dominated by universal-motor designs, compressing margin structures for non-compliant suppliers.
REACH regulations in Europe are restricting hazardous substance use in polymer components and filter media. Manufacturers must reformulate housing materials and HEPA filter binders to maintain market access. German and French commercial channels face the steepest compliance costs due to early enforcement and premium positioning requirements.
Cleaning service procurement patterns are fragmenting as regional operators consolidate into multi-city networks with centralized fleet management. Traditional distributor relationships face disintermediation from direct OEM partnerships. This shift concentrates most visibly in US metropolitan corridors where venture-backed cleaning platforms scale rapidly through technology-enabled operations.
Dry Vacuum Cleaner Market Segmentation
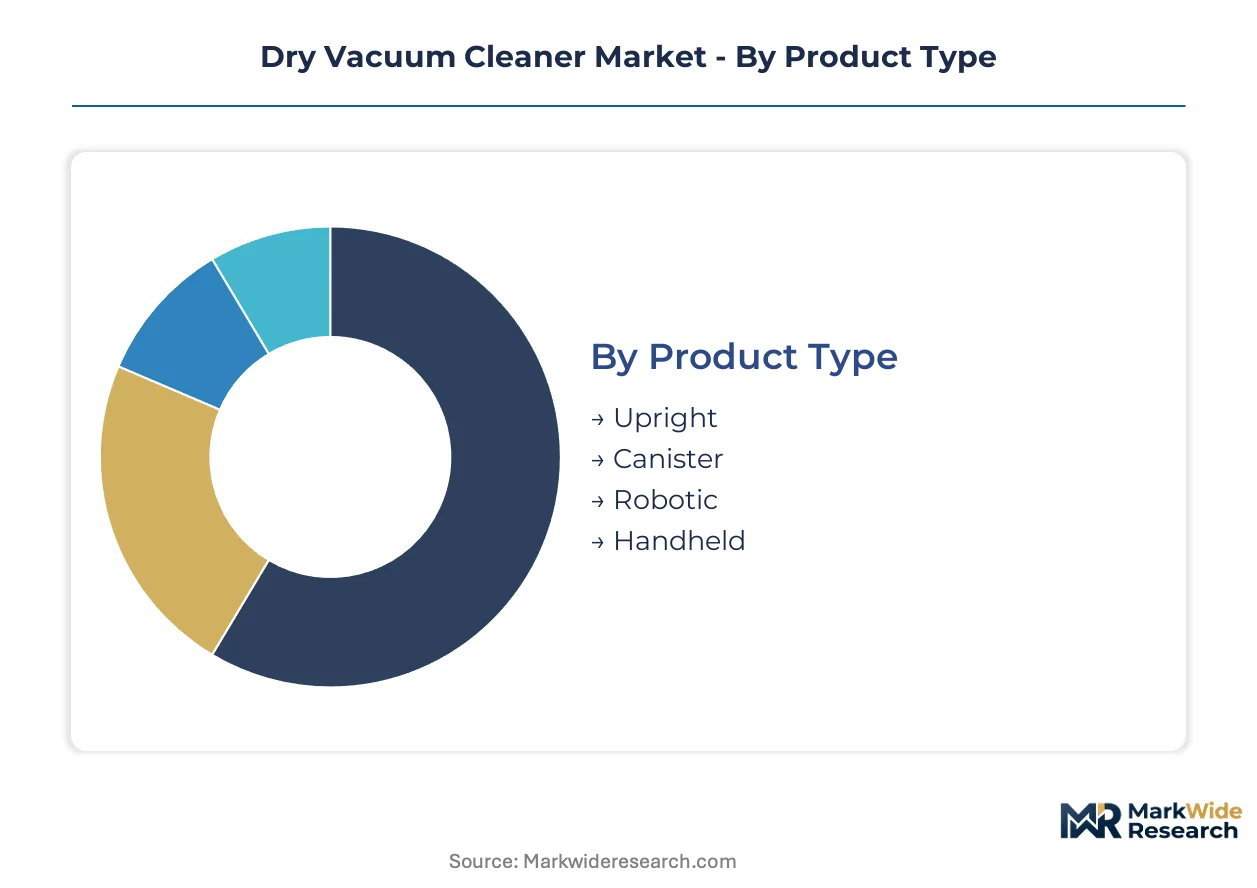
Dry vacuum cleaner segmentation reveals divergent margin structures across product architectures and procurement channels. Understanding where volume concentrates versus where premium pricing holds determines resource allocation for component sourcing and certification investment.
Product Type:
Volume concentrates in formats optimized for residential floor plans, while premium positioning clusters around autonomous navigation and specialized extraction capabilities.
- Upright:These units integrate motor, dust collection, and handle into a single vertical chassis, typically delivering airflow rates between 80 and 150 cubic feet per minute for broad surface coverage. Demand concentrates in US suburban households where carpeted flooring dominates, constrained by maneuverability limitations in compact European dwellings.
- Robotic:Autonomous units deploy LiDAR mapping and simultaneous localization algorithms to navigate without human guidance. US metropolitan cleaning services are scaling fleet deployments fastest as labor costs rise and navigation reliability improves.
- Canister:Separated motor and suction head designs optimize for maneuverability in multi-surface environments. European commercial channels command price premiums for this format.
- Handheld:Compact battery-powered units target spot cleaning and vehicle interiors. Portability drives adoption in automotive aftermarket channels.
Today's leader: Upright. Tomorrow's challenger: Robotic.
Application:
End-use differentiation separates scheduled maintenance contracts from discretionary household purchase cycles.
- Commercial:Cleaning services and facility managers operate equipment across extended duty cycles, prioritizing durability metrics and service network density. Procurement concentrates in US metropolitan corridors where venture-backed platforms consolidate multi-city operations.
- Industrial:Heavy-duty extraction systems remove particulate matter from manufacturing floors where moisture-sensitive substrates prohibit wet-system deployment. Germany's industrial corridor anchors replacement demand as factory automation expands.
- Residential:Homeowners purchase through retail channels with replacement cycles tied to warranty expiration and aesthetic obsolescence. Energy-label visibility shapes purchase decisions in regulated markets.
- Automotive:Detailing shops and service centers require compact, high-suction units for interior debris extraction. Specialist distributors dominate this channel.
Commercial channels scale fastest. Industrial segments retain margin concentration.
Technology:
Filtration architecture determines consumable revenue streams and regulatory compliance pathways.
- Cyclonic:Centrifugal separation eliminates bag replacement, reducing lifetime operating costs. Bagless positioning dominates residential segments in North America.
- Bagged:Sealed containment systems satisfy hygiene requirements in healthcare and hospitality settings. European commercial specifications favor this architecture.
- Wet/Dry:Multi-surface capability threatens pure dry-system substitution where moisture tolerance permits. Construction contractors drive adoption.
- Bagless:Transparent dust chambers provide visual feedback on extraction performance. Consumer preference varies by regional cleaning habits.
Cyclonic captures volume leadership. Bagged defends premium niches.
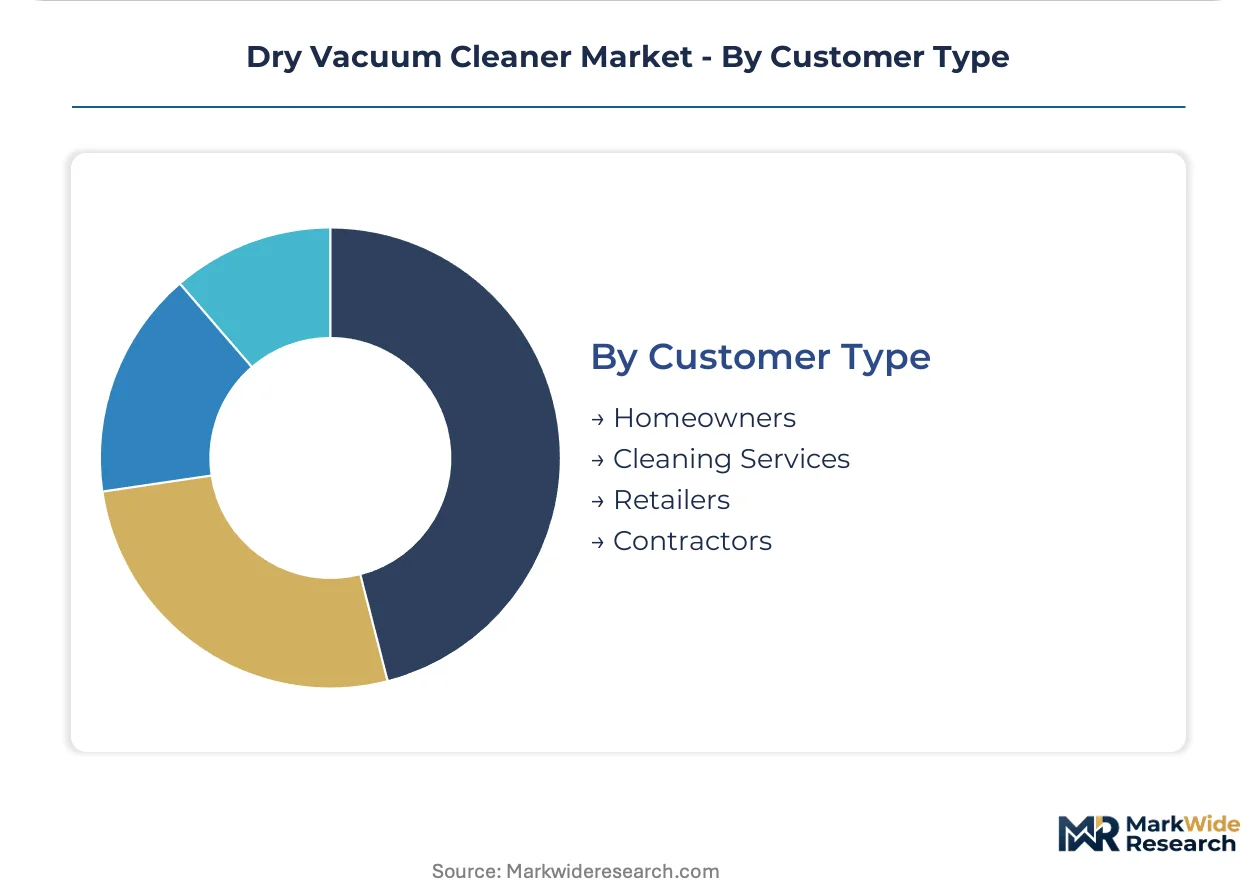
Customer Type:
Procurement authority separates capital-budget purchasers from operational expenditure decision-makers.
- Cleaning Services:Fleet operators negotiate direct OEM partnerships, bypassing traditional distribution. Subscription-based equipment-as-service models are displacing capital purchases in scaled operations.
- Contractors:Construction and industrial cleaning specialists prioritize suction power and debris capacity over energy efficiency. Rental channels supplement ownership in project-based work.
- Homeowners:Retail-driven purchase decisions respond to energy-label visibility and warranty terms. Online reviews increasingly influence selection.
- Retailers:Merchandising buyers control shelf placement and promotional pricing, extracting slotting fees and marketing contributions from manufacturers.
Cleaning Services drive structural change. Contractors anchor replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled robotics engineers in Boston and Shenzhen anchor development pipelines for autonomous navigation systems. Manufacturing technicians across Germany's industrial belt sustain heavy-duty extraction system production. Supply chain coordinators in Shanghai manage rare-earth magnet procurement for brushless DC motor platforms.
United States
Commercial cleaning services in New York and Chicago deploy robotic fleet expansions as labor costs climb. EPA Energy Star certification mandates shape product architecture for retail placement. Venture-backed platforms in Los Angeles and Miami consolidate multi-city operations through centralized procurement.
Germany
Factory automation in Bavaria and Baden-Württemberg drives replacement cycles for industrial extraction systems. EU Ecodesign Directive motor efficiency thresholds compress legacy brushed-motor supply chains. Stuttgart's manufacturing corridor concentrates brushless DC platform transitions.
China
GB standards for electromagnetic compatibility govern domestic market access and export qualification. Rare-earth processing clusters in Jiangxi and Inner Mongolia supply neodymium-dysprosium for brushless DC production. Shenzhen's electronics ecosystem anchors robotic navigation component sourcing.
Japan
METI efficiency guidelines and JIS standards shape product development timelines for domestic and export markets. Industrial segments in Nagoya and Osaka anchor sustained replacement demand. Kanto region robotics specialists advance LiDAR-IMU sensor fusion for unstructured environments.
India
BIS certification for electromagnetic compatibility creates compliance barriers for imported equipment. Cleaning service networks in Mumbai and Bengaluru scale through technology-enabled operations. Tamil Nadu's manufacturing corridor attracts local testing infrastructure investment ahead of mandatory implementation.
Dry Vacuum Cleaner Market Competitive Landscape
The competitive structure tilts toward diversified appliance conglomerates with cross-category manufacturing scale. Tiered specialization separates premium motor technology developers from volume-oriented agile cyclers. Strategic moves concentrate on direct-to-service fleet partnerships and component-level efficiency certification rather than retail shelf expansion.
Among UK-based technology developers, Dyson occupies a position exemplifying proprietary digital motor architecture. SharkNinja represents the agile product cycling archetype navigating regulatory thresholds without heavy fixed R&D infrastructure. Alfred Karcher SE & Co. KG anchors the industrial-specialist tier with German GmbH structure and commercial channel concentration.
| Leading Market Players |
|---|
| Dyson |
| SharkNinja |
| Bissell Homecare |
| iRobot |
| Electrolux |
| Alfred Karcher SE & Co. KG |
| Nilfisk A/S |
| Tennant Company |
| Stanley Black & Decker |
| Others |
Supply & Pricing Matrix
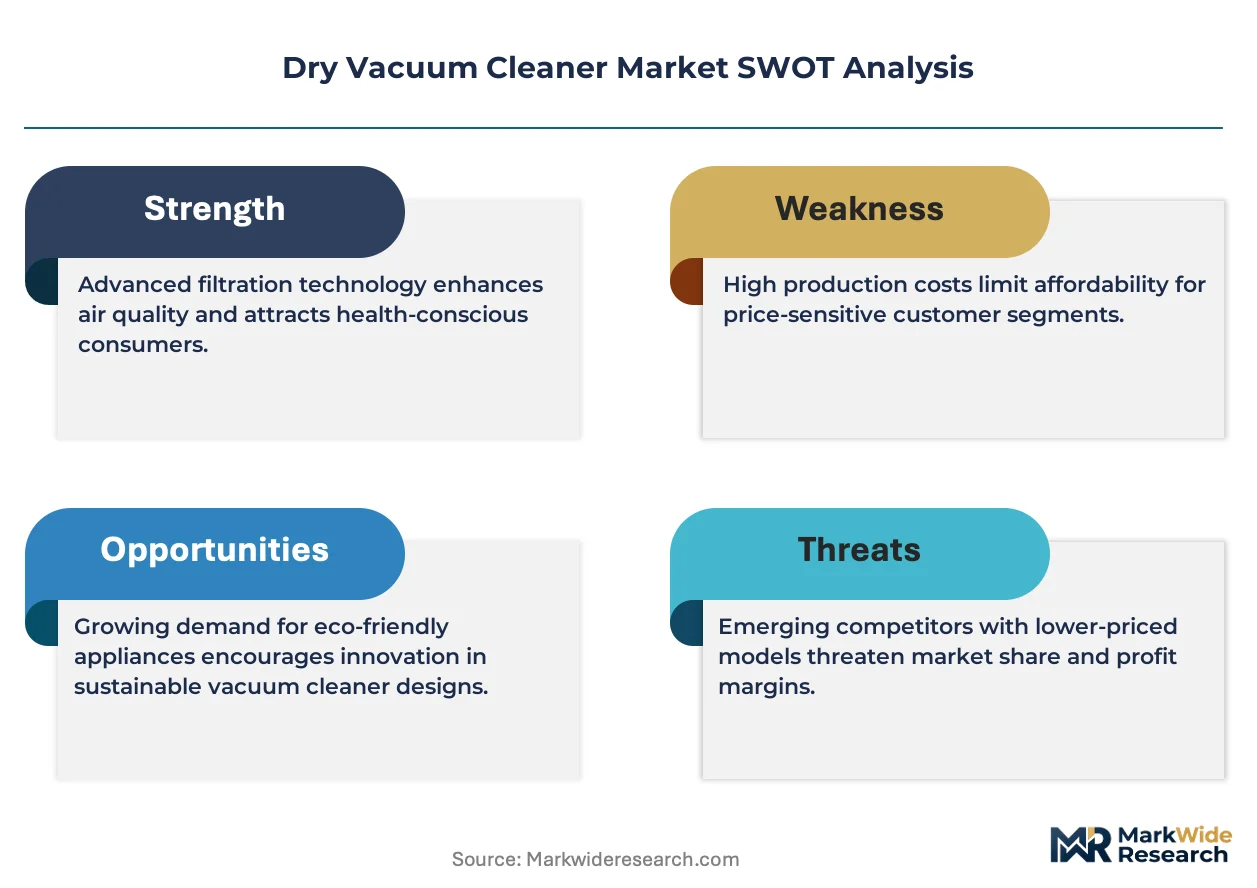
EU Ecodesign Directive motor efficiency mandates are forcing component-level redesigns toward brushless DC architectures, compressing margin structures for suppliers locked into legacy brushed-motor platforms while expanding pricing power for compliant OEMs with certified digital motor technology.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-purchase transactions from subscription-based equipment-as-service models. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor efficiency certification and autonomous navigation capability. Cost compression in economy tiers is intensifying because wet-dry hybrid substitution threatens pure dry-system volume. Cleaning services demonstrate lowest price sensitivity due to fleet-scale procurement leverage, while residential retail buyers exhibit highest elasticity to energy-label visibility.
Supply Chain Analysis
Certification and qualification gating through EPA Energy Star, EU Ecodesign, and China's GB standards forces redundant testing protocols that extend lead times and concentrate supplier relationships with accredited laboratories. Brushless DC motor production draws from rare-earth processing clusters in China, motor winding facilities in Germany, and electronics assembly in Vietnam. Single-source vulnerability in neodymium-dysprosium supply chains concentrated in Jiangxi and Inner Mongolia exposes manufacturers to input cost volatility. Distribution runs through direct OEM partnerships with scaled cleaning service networks, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential as brushless DC platform transitions unlock premium tier positioning while factory automation in Germany sustains industrial replacement cycles at higher price points.
For Market Incumbents: Lock in supply chain control over rare-earth magnet procurement through long-term offtake agreements with Chinese processors. Deepen backward integration into brushless DC motor manufacturing to defend against emerging agile cyclers. Prioritize certification investment in India's BIS electromagnetic compatibility standards ahead of mandatory implementation to secure first-mover positioning.
For New Entrants and Emerging Players: The price-point gap between premium robotic units and economy upright formats creates white-space opportunity in mid-tier canister segments for European commercial channels. India's cleaning service networks in Mumbai and Bengaluru represent the most penetrable geography due to technology-enabled operational scaling. Pursue direct fleet partnerships with venture-backed multi-city platforms rather than retail shelf placement.
For Investors and Strategic Acquirers: Asymmetric upside sits with component suppliers possessing accredited testing infrastructure across multiple regulatory jurisdictions. Long-term viability favors specialists in LiDAR-IMU sensor fusion for unstructured industrial navigation. Watch for inflection signals in cleaning service procurement shifts from capital purchase to subscription-based equipment-as-service models.
| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Platform Transition | EU Ecodesign compliance unlocks premium positioning in efficiency-sensitive German industrial channels. |
| Direct Fleet Partnership Formation | Bypassing wholesale distribution captures margin from consolidating US metropolitan cleaning services. |
| LiDAR-IMU Sensor Fusion Investment | Enables robotic penetration of unstructured factory environments previously requiring human operation. |
| India BIS Certification Pre-positioning | Local testing infrastructure investment secures market access ahead of mandatory electromagnetic standards. |
| Equipment-as-Service Model Launch | Subscription revenue streams align with cleaning service shift from capital purchase to operational expenditure. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with cleaning service fleet managers, OEM procurement directors, motor component suppliers, and aftermarket service heads alongside secondary validation through EPA Energy Star certification databases, EU Ecodesign regulatory filings, China's GB standards documentation, and customs trade records. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application, technology architecture, and customer procurement authority. CAGRs derive from fitted growth curves applied to replacement cycle analysis and regulatory compliance timelines. Industry-specific forecast inputs incorporate factory automation expansion rates in Germany's industrial corridor and LiDAR cost decline trajectories for robotic navigation.
Caveats apply where rare-earth supply disruptions or regulatory threshold acceleration could materially shift the outlook. Forecasts reflect assumptions about motor efficiency adoption curves and cleaning service consolidation velocity. A model refresh is warranted upon material change in EU Ecodesign implementation timelines or China's export restriction policies on processed rare-earth elements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Acrylic Aquarium Market
Household Items
Cast Iron Cookware Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
North America Water Purifier Market
Household Items
United States Smart Shower Market
Household Items
Insulated Tumblers Market
Household Items
Robot Mops Market
Household Items
Smart Fridge Market
Household Items
Oman Gas Hobs Market
Household Items
Smart Pool Skimmer Market
Household Items
Mosquito Trap Market
Household Items
Shoe Shine Machine Market
Household Items
Gel Warmers Market
Household Items
Japan Faucets Market
Household Items
Turkey Cookware Market