
 Global Smart Watch Market | 2026-2036
Global Smart Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Watch Market Outlook
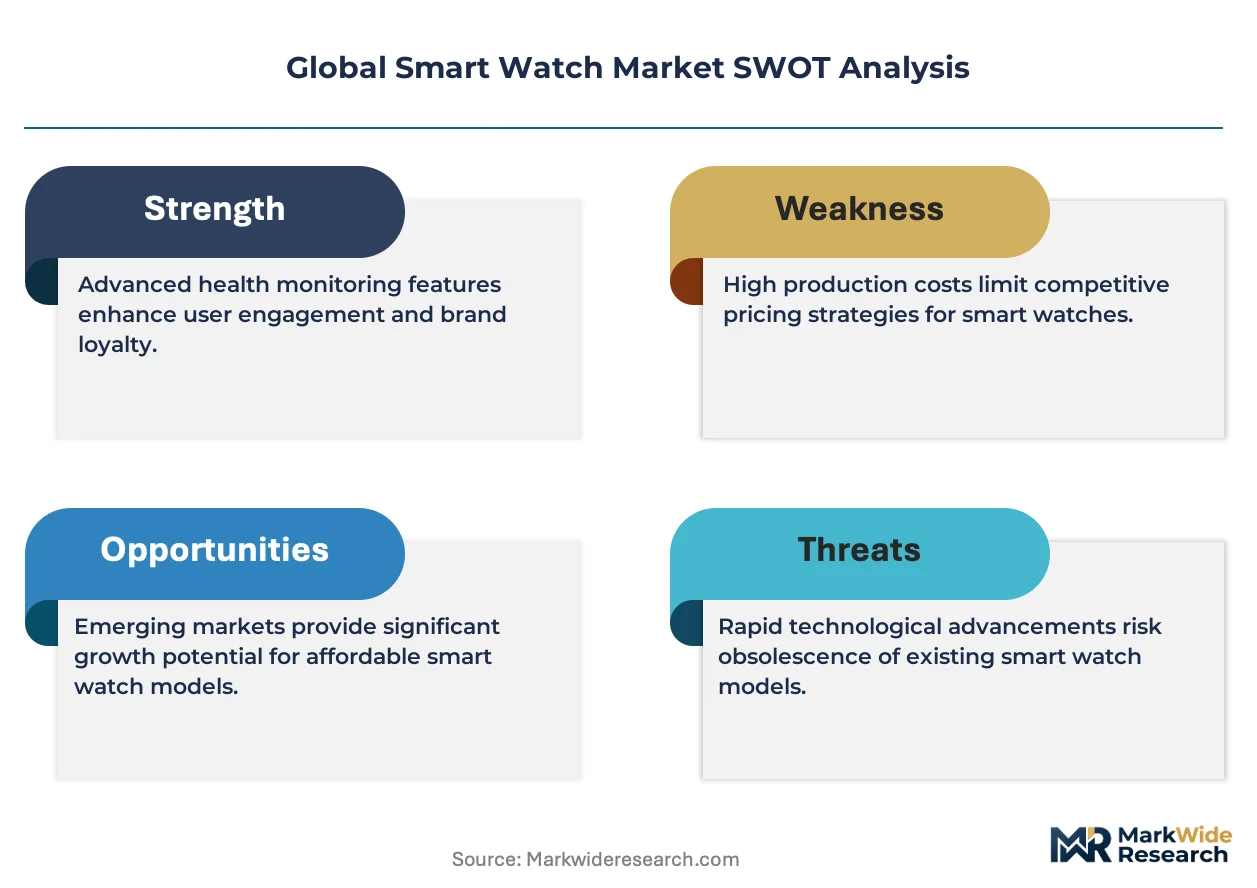
FCC equipment authorization and CE marking compliance is bifurcating the vendor landscape between ecosystem-integrated giants and component-dependent challengers. Apple Inc. leverages its vertical silicon design to sustain margin pools that competitors cannot match. Samsung Electronics anchors its position through Galaxy ecosystem lock-in across North America and Europe. Garmin Ltd. specializes in ruggedized outdoor GPS functionality that dominates the athletic professional niche.
A smart watch is a wrist-worn computing device incorporating biometric sensors, low-power microprocessors, and wireless transceivers to deliver health monitoring, notification relay, and application execution. Manufacturing emphasizes hermetic sealing for water resistance ratings and flexible OLED lamination for curved display durability. Classic smartwatch units lead volume shipments due to balanced feature-to-price positioning, while luxury smartwatch configurations capture disproportionate margin through precious material casings and concierge service bundling. Cellular-enabled technology variants represent the fastest-growing connectivity tier as eSIM provisioning eliminates smartphone tethering dependency.
FDA digital health pre-certification and EU MDR Class IIa requirements are elevating clinical-validation burdens for heart-rate and blood-oxygen algorithms, forcing R&D budget reallocation toward regulatory affairs teams. China's NMPA and GB standards mandate SAR testing and battery-safety documentation that delay product launches for non-domestic entrants. Stakeholders must monitor whether emerging glucose-noninvasive sensing platforms trigger medical-device reclassification that would reshape competitive moats and partnership structures.
Market Dynamics
Clinical-grade algorithm validation is forcing R&D budget reallocation toward regulatory affairs teams, compressing margins for challengers while ecosystem giants absorb compliance costs through captive silicon design.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic explainability requirements for biometric diagnostics are accelerating FDA digital health pre-certification adoption among vendors seeking dual-market entry.
- Health enthusiast cohort expansion:Cardiovascular awareness campaigns in India and China are shortening replacement cycles for aging wearable devices.
- eSIM provisioning:Cellular-enabled variants eliminate smartphone tethering dependency, unlocking standalone emergency response and mobile payment use cases.
Market Restraints
- GB standards battery documentation:China's NMPA mandates SAR testing and safety certification that delay product launches for non-domestic entrants by six to nine months.
- OLED display supply concentration:Flexible lamination capacity clusters in South Korea and Taiwan, exposing vendors to single-source disruption risk.
- Noninvasive glucose sensing uncertainty:Medical-device reclassification triggers for optical metabolite detection remain unresolved, freezing platform development roadmaps.
Strategic Opportunities
- India BIS certification pathway:Local manufacturing incentives under PLI schemes reduce import duty burdens for domestic assembly operations.
- Concierge service bundling:Luxury configurations pair precious material casings with personalized health coaching subscriptions.
- Galaxy ecosystem lock-in extension:Samsung leverages cross-device continuity to capture enterprise wellness program procurement.
Industry Challenges
- EU MDR Class IIa clinical-validation burden:Heart-rate and blood-oxygen algorithm verification requires prospective studies that strain mid-cap R&D budgets.
- Hermetic sealing yield rates:Water resistance rating consistency demands capital-intensive cleanroom expansion for adhesive dispensing automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Watch Market |
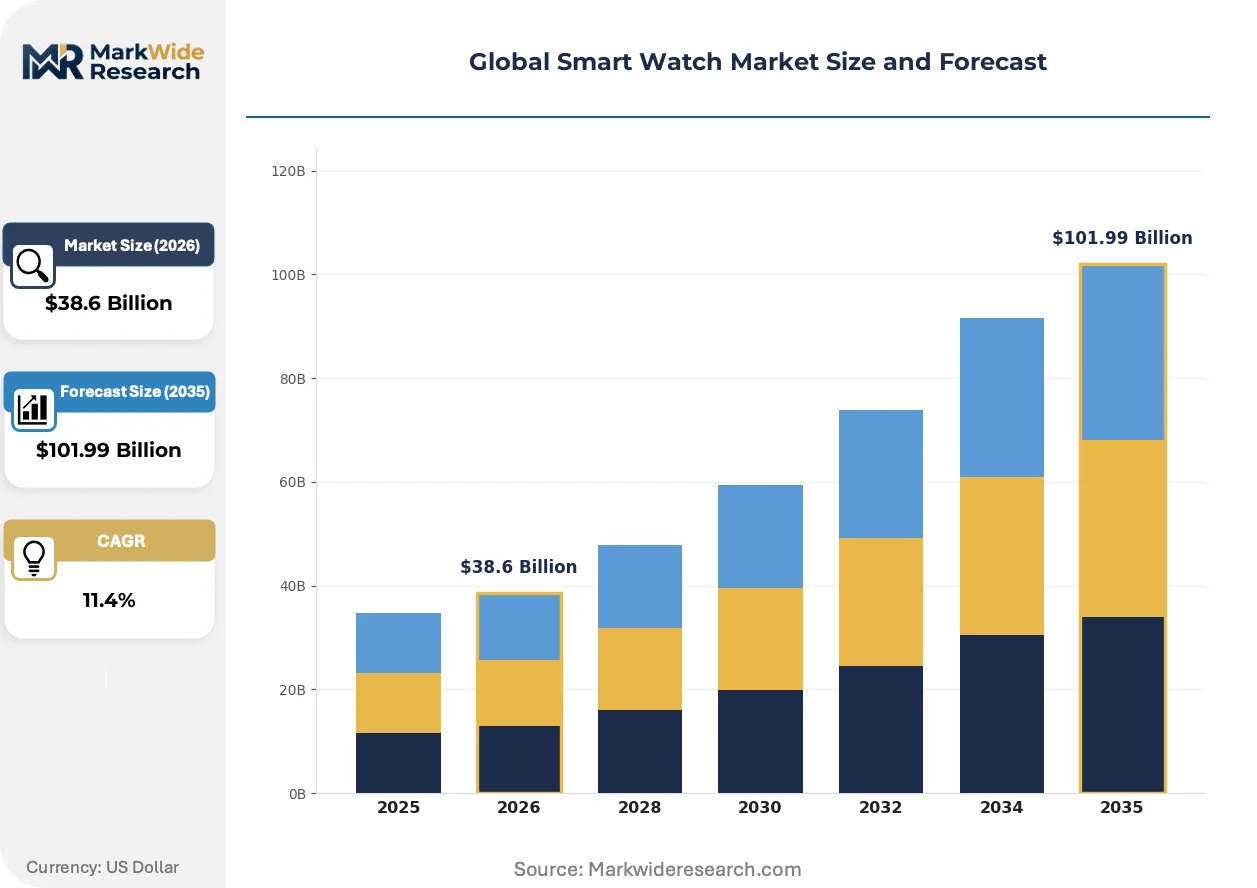
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Tracker, Hybrid Smartwatch, Classic Smartwatch, Luxury Smartwatch Technology: Bluetooth, Wi-Fi, NFC, Cellular End User: Health Enthusiasts, Tech Savvy Users, Professionals, Casual Users Distribution Channel: Online Retail, Electronics Stores, Brand Outlets, Supermarkets |
| Companies Covered | Apple Inc., Samsung Electronics, Huawei Technologies Co., Ltd., Garmin Ltd., Fitbit, Xiaomi Corporation, Fossil Group, Amazfit, Withings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Watch Market Strategic Shifts
Three concurrent shifts are compressing development timelines while elevating compliance burdens across the value chain.
Photoplethysmography signal processing is bifurcating the vendor landscape. Advanced noise-filtering firmware enables clinical-grade arrhythmia detection in consumer-priced hardware. Athletic professional segments in the United States and Germany adopt these capabilities fastest, forcing component-dependent challengers into price wars against vertically integrated ecosystem giants.
REACH substance restrictions on nickel and cobalt in wearable casings are tightening material sourcing requirements. EU MDR biocompatibility documentation now extends to wrist-contact surfaces previously exempt from medical-device scrutiny. Premium-tier manufacturers in Switzerland and Japan accelerate ceramic and titanium alloy substitution to preempt regulatory friction.
Enterprise wellness programs are consolidating procurement around platform-agnostic data aggregation. Human resources departments in the United States demand API interoperability with existing health benefit administration systems. This specification shift disadvantages closed-ecosystem vendors while elevating middleware providers offering HIPAA-compliant data normalization layers.
Global Smart Watch Market Segmentation
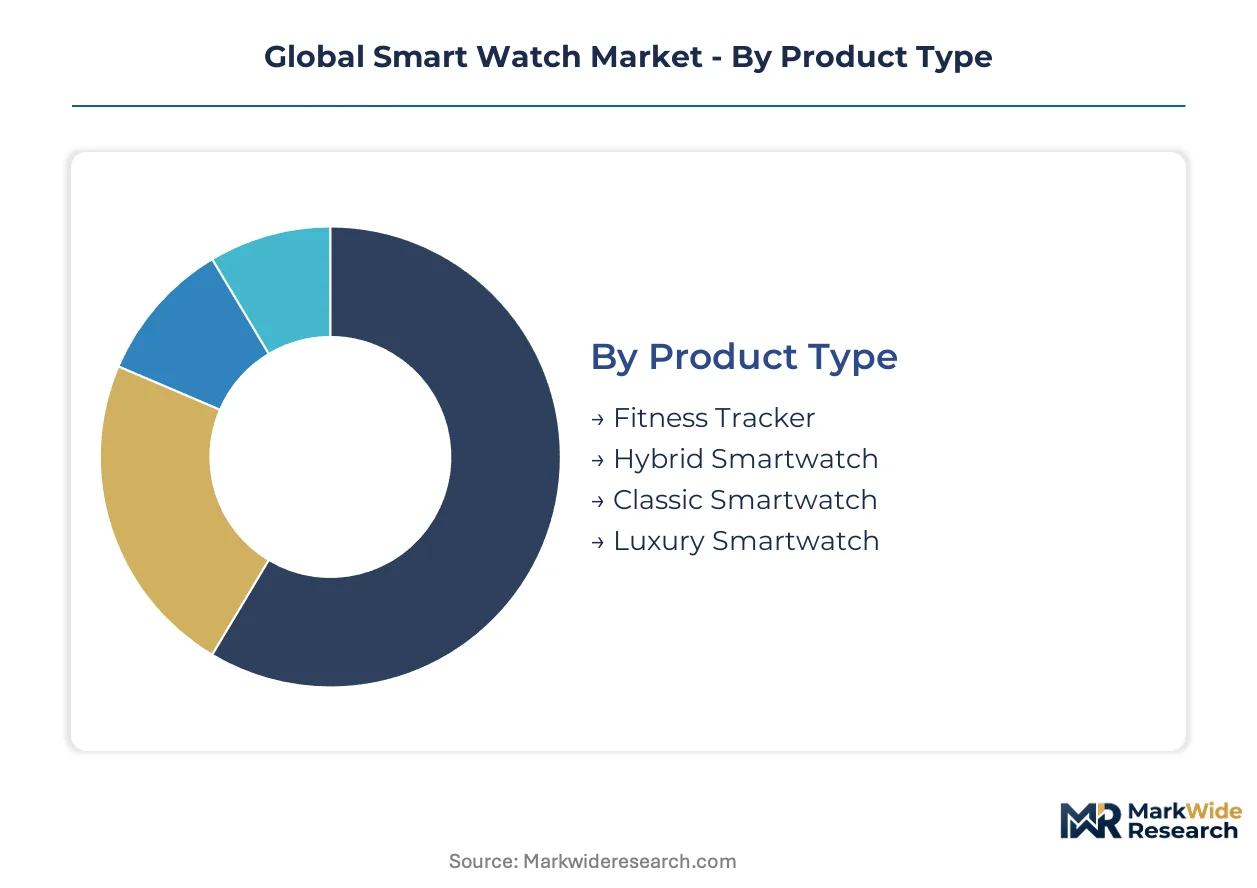
Segmentation in the smart watch market determines which feature bundles justify premium positioning versus mass-market penetration. Vendors calibrate sensor arrays, connectivity tiers, and casing materials to match distinct willingness-to-pay thresholds across user cohorts.
Product Type:
Fitness trackers face the most intense substitution pressure from smartphone health apps and dedicated sports watches, forcing vendors to differentiate through clinical-grade algorithm integration.
- Classic Smartwatch:Balanced feature-to-price positioning with biometric sensors, notification relay, and third-party app support. Demand concentrates in the United States and China where smartphone ecosystem penetration drives replacement cycles among health-conscious consumers seeking FDA-cleared heart-rate monitoring without luxury premiums.
- Luxury Smartwatch:Precious material casings paired with concierge service bundling and limited production runs. Switzerland and Japan anchor demand as premium-tier manufacturers accelerate ceramic and titanium alloy substitution to preempt EU REACH substance restrictions on nickel and cobalt.
- Fitness Tracker:Stripped-down biometric monitoring with extended battery life for single-purpose health tracking.
- Hybrid Smartwatch:Analog watch aesthetics with embedded step counting and basic notification alerts.
Classic smartwatch configurations anchor the volume base while luxury smartwatch variants gain share at the steepest rate through material differentiation and service bundling.
Technology:
Connectivity cost tiers separate standalone utility from smartphone-dependent models, with cellular provisioning requiring carrier partnerships that only ecosystem giants can negotiate at scale.
- Cellular:eSIM provisioning eliminates smartphone tethering dependency, enabling standalone emergency response and mobile payment use cases. The United States and Germany lead adoption as athletic professional segments demand untethered GPS tracking and real-time health data transmission during training sessions.
- Bluetooth:Low-energy pairing with smartphones for notification relay and sensor data offload. India and China concentrate volume as price-sensitive consumers prioritize basic connectivity over standalone functionality.
- Wi-Fi:Direct cloud synchronization for music streaming and software updates without phone proximity.
- NFC:Contactless payment and transit authentication through tokenized credential storage.
Bluetooth-enabled units dominate shipment volumes while cellular-equipped variants expand most quickly as eSIM provisioning matures across carrier networks.
End User:
Application intensity varies dramatically, with clinical-grade biometric demands forcing hardware specifications that casual notification-checking users will not subsidize.
- Health Enthusiasts:Cardiovascular awareness campaigns in India and China shorten replacement cycles for aging wearable devices. This cohort demands photoplethysmography-based arrhythmia detection and blood-oxygen monitoring that meets FDA digital health pre-certification thresholds.
- Professionals:Enterprise wellness program procurement with API interoperability requirements for health benefit administration systems. United States human resources departments drive platform-agnostic data aggregation specifications that disadvantage closed-ecosystem vendors.
- Tech Savvy Users:Early adoption of beta firmware features and third-party application sideloading.
- Casual Users:Notification relay and basic step counting with minimal sensor engagement.
Health enthusiasts generate the highest revenue per unit while professionals represent the fastest-expanding corporate procurement segment.
Distribution Channel:
Channel control determines margin capture, with direct-to-consumer platforms preserving pricing power that third-party retail partnerships erode through promotional discounting.
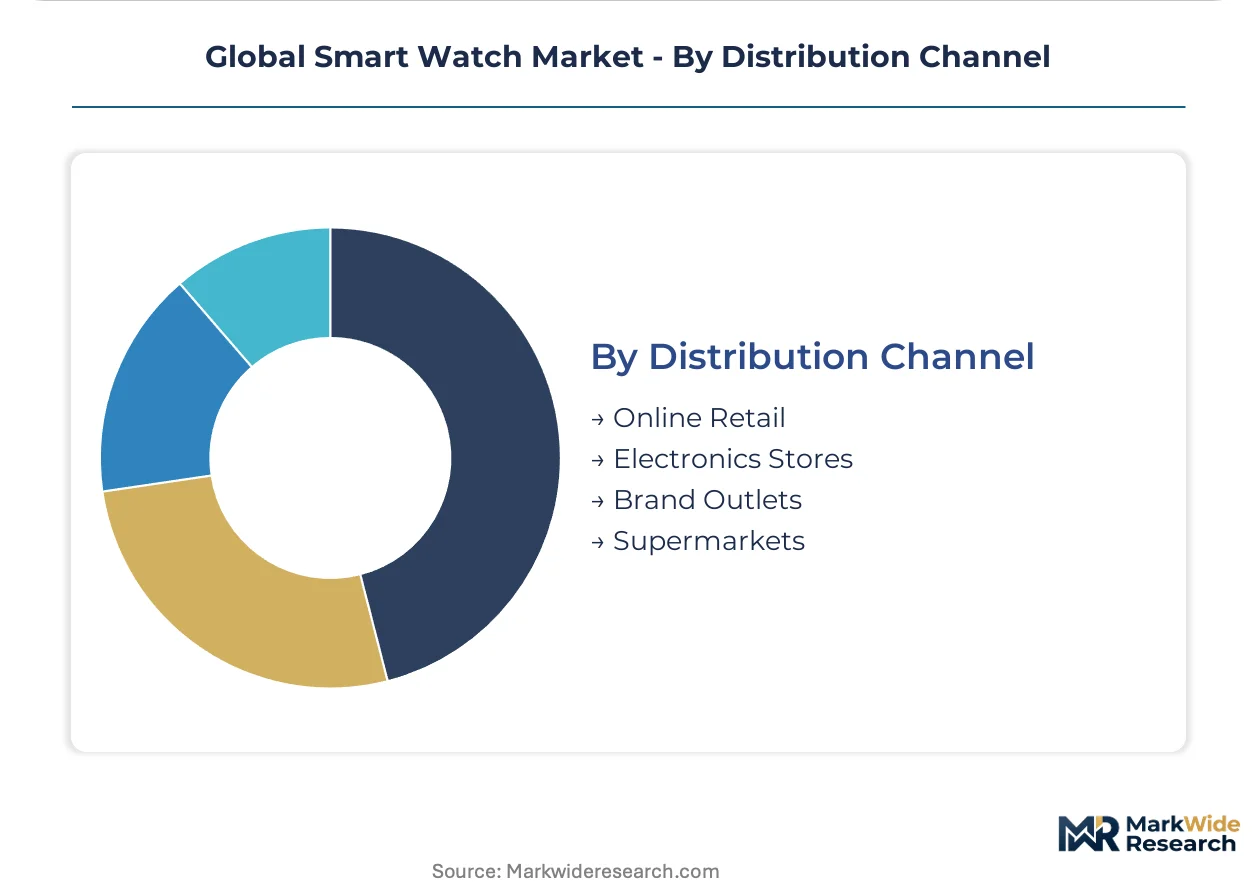
- Online Retail:E-commerce platforms aggregate comparison shopping and subscription bundling opportunities. China and India concentrate volume as domestic assembly operations under PLI schemes reduce import duty burdens for local fulfillment.
- Brand Outlets:Controlled environment for ecosystem demonstration and personalized configuration services. Switzerland and Japan anchor premium-tier positioning through in-store concierge onboarding and extended warranty programs.
- Electronics Stores:Multi-brand comparison shopping with promotional pricing during holiday periods.
- Supermarkets:Impulse purchase placement for entry-level fitness trackers and gift-oriented SKUs.
Online retail channels command the dominant volume share while brand outlets capture margin expansion through service attachment and ecosystem lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI schemes in India and FDA digital health pre-certification in the United States are redirecting manufacturing footprints and clinical-validation investments across the value chain. Regulatory divergence between EU MDR Class IIa requirements and China's NMPA battery-safety mandates forces vendors to maintain parallel compliance tracks. Demand concentrates where smartphone ecosystem penetration intersects with cardiovascular awareness campaigns.
United States
Enterprise wellness program procurement drives corporate volume as human resources departments mandate API interoperability with health benefit administration systems. FDA digital health pre-certification elevates clinical-validation burdens for heart-rate and blood-oxygen algorithms. Austin and San Francisco anchor development clusters where photoplethysmography firmware teams compete for talent.
China
Domestic assembly operations under PLI-equivalent incentives capture cost advantages for regional fulfillment. NMPA mandates SAR testing and GB standards battery-safety documentation that delay product launches for non-domestic entrants. Shenzhen and Dongguan concentrate flexible OLED lamination capacity, exposing vendors to single-source disruption risk.
India
Cardiovascular awareness campaigns shorten replacement cycles for aging wearable devices among health enthusiasts. BIS certification pathways and PLI scheme local manufacturing incentives reduce import duty burdens for domestic assembly operations. Bengaluru and Noida emerge as fulfillment hubs for online retail channels serving price-sensitive consumers.
Germany
Athletic professional segments adopt cellular-enabled variants for untethered GPS tracking during training sessions. EU AI Act transparency mandates and EU MDR Class IIa requirements accelerate algorithmic explainability investments. Munich and Stuttgart host automotive-to-wearable talent pipelines leveraging sensor fusion expertise.
Japan
Premium-tier manufacturers accelerate ceramic and titanium alloy substitution to preempt EU REACH substance restrictions on nickel and cobalt. METI standards and PMDA guidance shape biocompatibility documentation for wrist-contact surfaces. Tokyo and Osaka anchor luxury smartwatch positioning through in-store concierge onboarding and extended warranty programs.
Global Smart Watch Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance capabilities, creating a tiered structure where ecosystem giants absorb FDA and EU MDR costs through captive silicon design. Private specialists concentrate in ruggedized outdoor GPS functionality and hybrid analog-digital aesthetics. Three archetypes dominate: vertically integrated ecosystem giants with semiconductor design capabilities, component-dependent challengers reliant on third-party sensor modules, and premium-tier specialists in precious material casings. Competitive moves center on eSIM carrier partnership negotiations and clinical-validation study sponsorships.
Within the ecosystem-integrated tier, Apple Inc. and Samsung Electronics exemplify archetypes that leverage vertical silicon design and cross-device continuity to sustain margin pools. Garmin Ltd. occupies a position among ruggedized outdoor specialists where hermetic sealing expertise and GPS firmware differentiation create defensible niches. These three anchors span Cupertino-based semiconductor design, Suwon-centered ecosystem lock-in, and Olathe-rooted athletic professional segmentation.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Huawei Technologies Co., Ltd. |
| Garmin Ltd. |
| Fitbit |
| Xiaomi Corporation |
| Fossil Group |
| Amazfit |
| Withings |
| Others |
Value Chain & Pricing Dynamics
Flexible OLED lamination capacity utilization above 85 percent in South Korea and Taiwan compresses margin pools for component-dependent vendors while elevating price floors for clinical-grade sensor arrays. Scale concentration in display fabrication and semiconductor packaging forces challengers to absorb premium input costs or surrender tier-one positioning.
Pricing Analysis
Certification level creates the primary spread between economy and premium tiers, with FDA digital health pre-certification and EU MDR Class IIa compliance adding substantial validation overhead that vertically integrated giants absorb through captive silicon design. Three-tier pricing structure across premium, standard, and economy levels reflects algorithm transparency grade, hermetic sealing IP rating, and after-sales concierge bundling. Cost compression in the standard tier intensifies as Chinese vendors leverage domestic assembly under NMPA pathways to undercut import-dependent rivals. Health enthusiasts in Germany and the United States exhibit lowest price sensitivity for clinical-grade arrhythmia detection, while casual users in India prioritize basic Bluetooth connectivity at entry price points.
Supply Chain Analysis
South Korea and Taiwan anchor flexible OLED lamination and advanced semiconductor packaging, while China concentrates PCB fabrication and final assembly operations. The supply chain draws from cobalt and nickel for battery cathodes, sapphire crystal for display covers, and rare-earth elements for sensor magnetics. Single-source vulnerability in OLED substrate production exposes vendors to disruption risk from Taiwan Strait logistics constraints. Distribution runs through direct-to-consumer brand outlets for premium tiers and online retail platforms for volume shipments in India and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EU MDR, and NMPA compliance tracks fragments procurement specifications, creating white-space opportunities for middleware specialists and regional assemblers who navigate certification complexity faster than ecosystem giants.
For Market Incumbents: Compound ecosystem lock-in through cross-device continuity APIs that enterprise wellness programs mandate for health benefit administration integration. Deepen captive silicon design to absorb EU AI Act algorithmic transparency costs that strain component-dependent challengers. Prioritize hermetic sealing yield rate investments to defend athletic professional positioning against ruggedized outdoor specialists. For New Entrants and Emerging Players: Anchor in India's PLI scheme domestic assembly corridors to capture BIS certification advantages and reduced import duty structures for online retail fulfillment. Target hybrid smartwatch analog aesthetics for Japan's premium-tier consumers seeking ceramic and titanium alloy alternatives to REACH-restricted nickel casings. Pursue carrier partnership negotiations for eSIM provisioning in Germany's athletic professional segment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors middleware providers offering HIPAA-compliant data normalization layers as enterprise wellness procurement consolidates around platform-agnostic aggregation. Long-term viability rests on regulatory navigation capabilities rather than hardware differentiation alone. Watch for noninvasive glucose sensing medical-device reclassification as the inflection signal that would reshape competitive moats and partnership structures.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical-Grade Algorithm Certification | FDA digital health pre-certification unlocks enterprise wellness procurement in the United States. |
| eSIM Carrier Partnership Negotiation | Cellular provisioning agreements with Deutsche Telekom and Verizon enable standalone emergency response use cases. |
| Ceramic and Titanium Alloy Substitution | Preemptive material pivot avoids EU REACH substance restrictions on nickel and cobalt wrist-contact surfaces. |
| PLI Scheme Domestic Assembly | India's local manufacturing incentives reduce import duty burdens for BIS-certified fulfillment operations. |
| API Interoperability Development | HIPAA-compliant data normalization layers capture enterprise wellness program consolidation in the United States. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wearable device product managers, regulatory affairs directors at FDA submission-stage firms, carrier partnership executives, and flexible OLED procurement leads at tier-one assemblers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and SEC semiconductor capex disclosures. Bottom-up shipment estimates triangulated against top-down ecosystem revenue allocations across the analysis window.
Across the projection horizon, the analytical framework modeled product type segmentation by feature tier, technology differentiation by connectivity architecture, end-user intensity by clinical-grade biometric demand, and distribution channel control by margin capture structure. CAGRs were derived from replacement cycle compression rates in India and China, algorithm validation timeline assumptions, and eSIM carrier provisioning expansion curves. Forecast inputs included OLED lamination capacity utilization trajectories and EU AI Act implementation phase-in schedules.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory divergence between FDA and EU MDR tracks; material harmonization or reclassification of optical metabolite sensing would warrant model refresh. Specific risks that could revise trajectories include Taiwan Strait logistics disruption to display substrate supply and NMPA battery-safety documentation delays for non-domestic entrants. Recalibration cycles align with material shifts in glucose-noninvasive sensing regulatory classification and PLI scheme incentive modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Asia Pacific Smartwatch Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Kids Watch Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Children Digital Watch Market
Wearable Technology
Smart Bra Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Europe Watch Market
Wearable Technology
Global Wearable Materials Market