
 Sanitary Napkin Receptacles Market | 2026-2036
Sanitary Napkin Receptacles Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Napkin Receptacles Market Insights
China is fragmenting its sanitary napkin receptacle manufacturing base across Guangdong and Zhejiang provinces as domestic hygiene infrastructure spending accelerates. Kimberly-Clark Corporation anchors North American distribution through institutional supply contracts with healthcare networks. Essity Aktiebolag leverages its European manufacturing footprint to sustain margin pools in the stainless steel segment. Hengan International Group Company Limited dominates cost-optimized plastic variants across Asia-Pacific markets.
Sanitary napkin receptacles are enclosed disposal units engineered from stainless steel, antimicrobial plastic, or aluminum, typically incorporating foot-pedal or sensor-activated mechanisms to enable touch-free waste deposit and odor containment. Wall-mounted configurations lead volume in healthcare settings where floor space optimization governs procurement, while automatic designs are capturing fastest growth in premium commercial spaces seeking touchless hygiene protocols. The plastic material segment occupies the broadest installed base across public restrooms, though stainless steel concentrates margin pools in hospital-grade specifications where durability and sanitization standards escalate replacement cycles.
FDA guidelines on medical facility sanitation shape hospital procurement standards for receptacle antimicrobial properties and sealed containment design. EPA regulations on restroom hygiene and waste stream management influence specifications in educational institutions and public facilities across the United States. OSHA workplace sanitation standards further constrain product selection in commercial environments. Stakeholders must monitor evolving touchless technology integration requirements and regional compliance divergence as hygiene infrastructure investment priorities shift across institutional buyer segments.
Market Dynamics
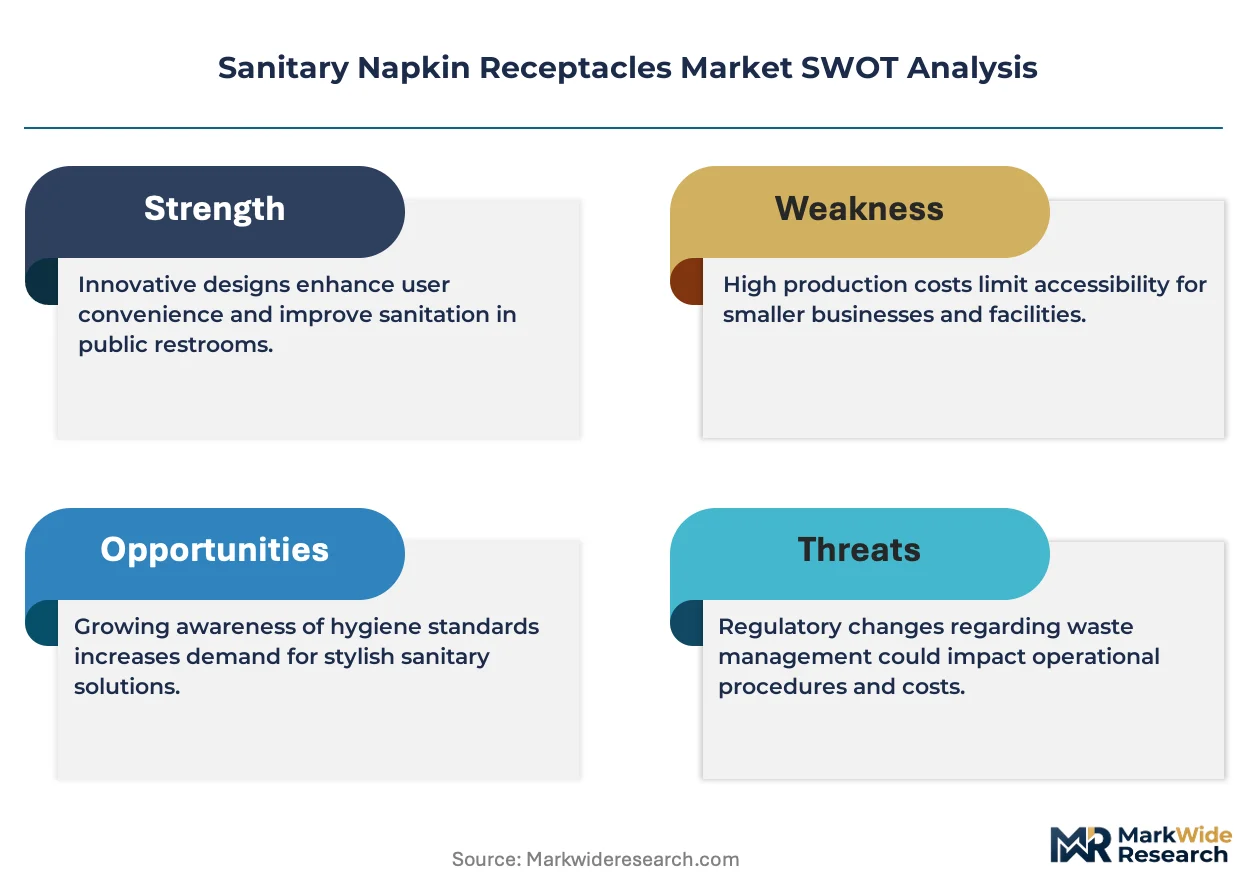
Touch-free sensor activation is compressing replacement cycles across institutional procurement, forcing manufacturers to reengineer mechanical pedal systems or exit mid-tier healthcare contracts entirely.
Growth Catalysts
- EPA restroom hygiene mandates:Federal waste segregation protocols in United States educational facilities are specifying sealed antimicrobial containment, accelerating specification upgrades in California and New York school districts.
- Stainless steel durability premiums:Hospital-grade specifications are extending replacement intervals while commanding margin pools in acute care settings where sanitization standards govern capital planning.
- Guangdong manufacturing scale:China's domestic hygiene infrastructure investment is fragmenting production across specialized provincial clusters, reducing unit costs for plastic-variant export supply.
Market Restraints
- Aluminum input volatility:Raw material price swings constrain margin stability for mid-tier producers dependent on non-ferrous metal formulations.
- Sensor component concentration:Touchless mechanism supply concentrates among a narrow base of electromechanical specialists, creating single-source vulnerability for automatic unit assemblers.
- Plastic substitution ceiling:Healthcare procurement officers resist polymer variants in operating theater adjacencies despite cost advantages, limiting addressable market expansion.
Strategic Opportunities
- India institutional sanitation:Swachh Bharat Mission infrastructure rollout is creating first-mover advantage for receptacle suppliers securing municipal tender relationships.
- IoT-enabled fill monitoring:Convergence of wireless telemetry with waste management logistics is opening service-contract revenue streams in facility management outsourcing.
- OSHA workplace mandates:Updated sanitation standards for commercial environments are mandating enclosed containment in manufacturing floor restrooms previously served by open bins.
Industry Challenges
- Electromechanical integration complexity:Legacy maintenance staff in aging school facilities lack training to service sensor-activated units, forcing supplier investment in technician certification programs.
- Antimicrobial certification timelines:EPA registration for novel surface treatments extends product launch windows, compressing competitive response time to specification shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Napkin Receptacles Market |
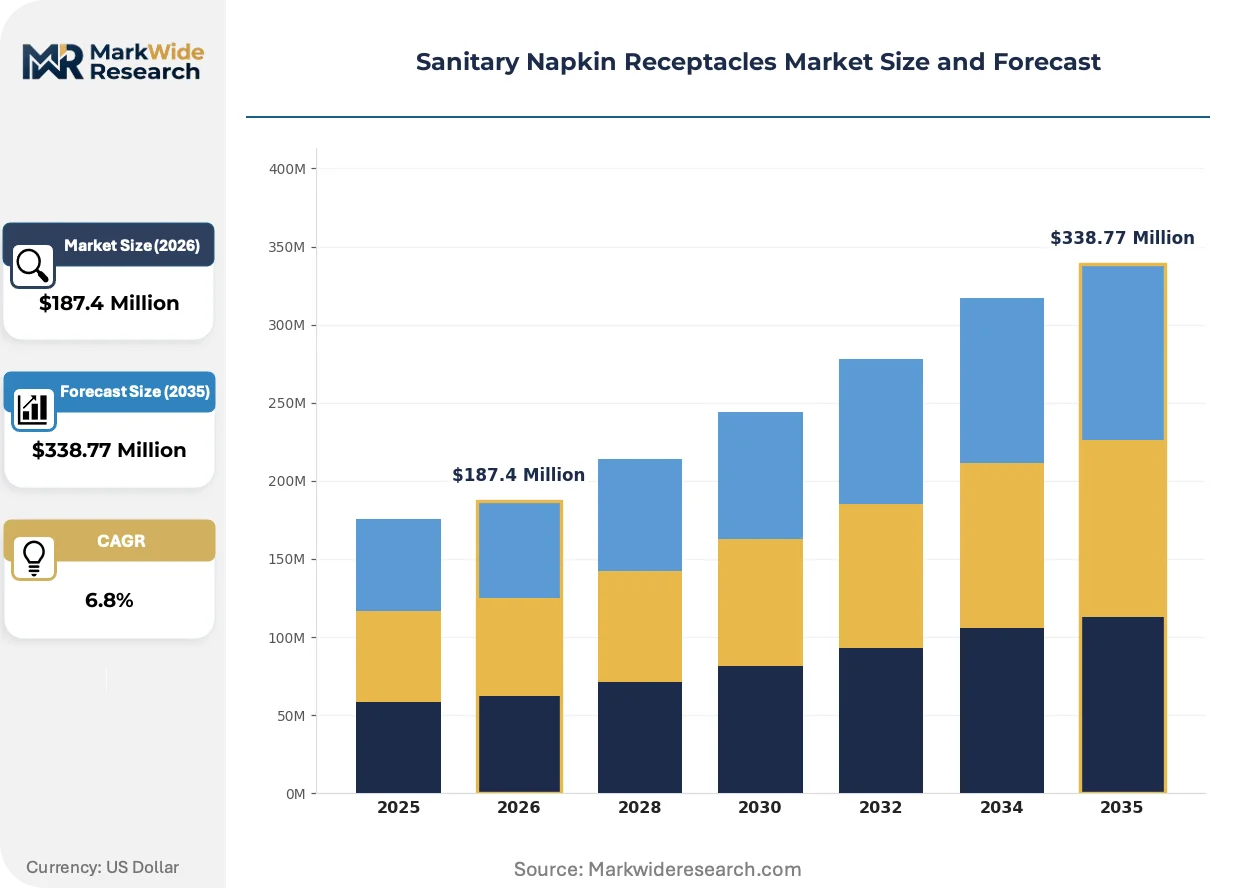
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Portable, Automatic Material: Plastic, Stainless Steel, Aluminum, Fiberglass End User: Hospitals, Educational Institutions, Public Restrooms, Commercial Spaces Design: Modern, Traditional, Eco-Friendly, Customizable |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Hengan International Group Company Limited, Kao Corporation, Essity Aktiebolag, Unicharm Corporation, Ontex Group NV, Edgewell Personal Care Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Napkin Receptacles Market Trends and Innovations
Active coating technologies and connected infrastructure are redefining product specifications, while procurement authority migrates from facilities managers to infection control committees with distinct performance metrics.
Antimicrobial surface treatments are migrating from supplemental spray applications to factory-integrated ionic silver or copper alloy substrates. Hospital procurement committees are specifying these permanent protections in new construction tenders. This migration from aftermarket to embedded protection is compressing margins for regional fabricators lacking vacuum deposition or powder-coating capabilities.
REACH chemical safety protocols in the European Union are restricting certain plasticizers in polymer receptacle formulations. Manufacturers serving EU institutional buyers are reformulating ABS and polypropylene compounds to maintain CE marking compliance. Stainless steel variants are capturing displaced volume in German and French healthcare networks where polymer requalification timelines extend procurement cycles.
Specification authority is migrating from general facilities management to dedicated infection control officers with clinical backgrounds. These stakeholders prioritize touchless activation and sealed containment over unit cost in United States acute care networks. Distributor relationships are restructuring around clinical education capabilities rather than traditional logistics coverage.
Sanitary Napkin Receptacles Market Segmentation
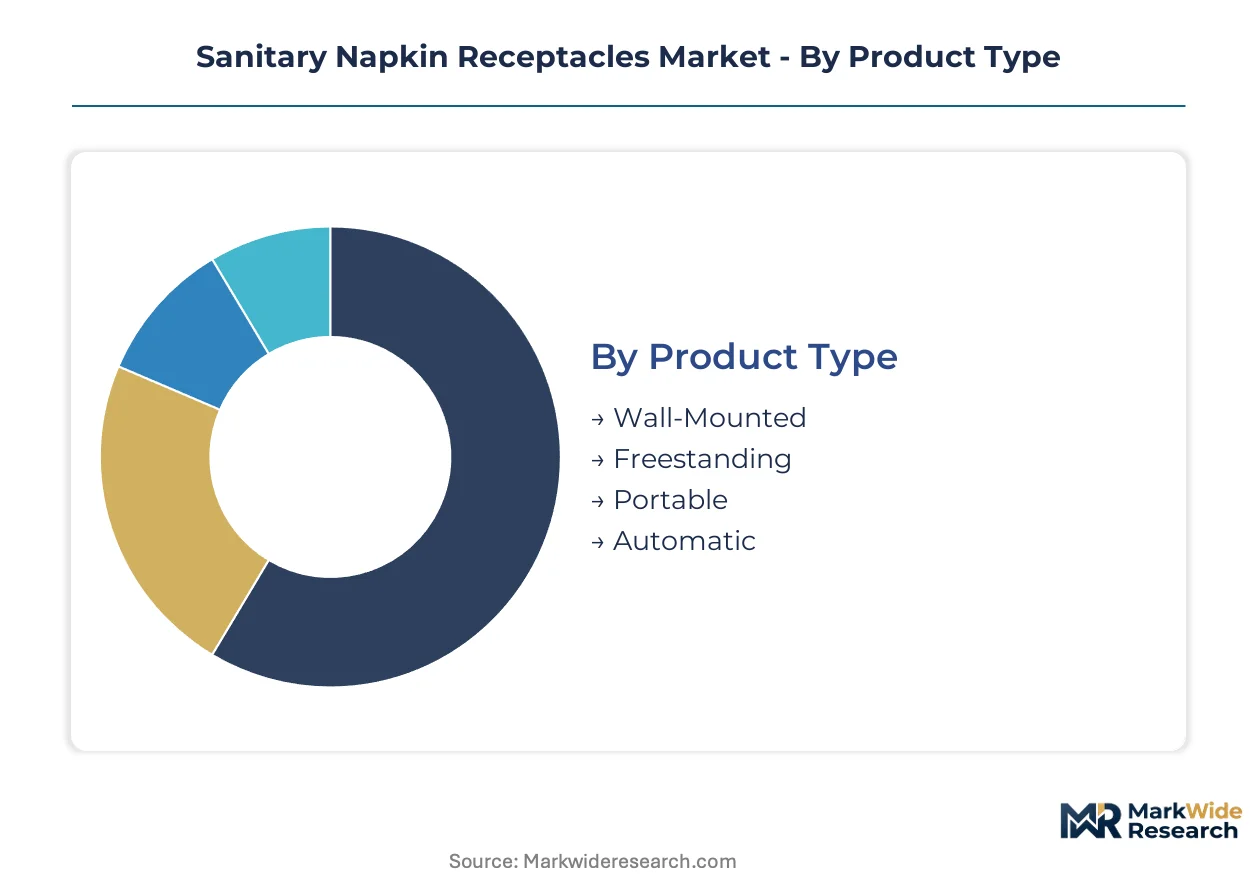
Segmentation in sanitary napkin receptacles determines procurement pathways across institutional buyers with divergent capital cycles and compliance obligations. Specification authority varies dramatically by end-use, with hospital infection control committees demanding stainless steel durability while school districts prioritize cost-optimized plastic variants under EPA procurement guidelines.
Product Type:
Wall-mounted units turn over slowest in healthcare capital planning, while automatic sensor-activated designs compress replacement cycles as touchless protocols spread across institutional facilities.
- Wall-Mounted:These units attach directly to restroom partitions or vertical surfaces, optimizing floor space in high-traffic medical corridors and school facilities. Demand concentrates in California and New York school districts where EPA waste segregation mandates specify sealed containment with minimal footprint intrusion.
- Automatic:Sensor-activated mechanisms enable touch-free waste deposit through infrared or capacitive detection systems. Procurement is accelerating in United States acute care networks where infection control officers prioritize touchless protocols over unit cost in capital planning decisions.
- Freestanding:Floor-supported configurations serve retrofit installations where wall structural integrity limits mounting options.
- Portable:Mobile units with casters address temporary facility deployments and event sanitation infrastructure.
Wall-mounted configurations dominate installed base across healthcare and educational facilities. Automatic designs are where expansion concentrates as touchless hygiene protocols displace mechanical pedal systems.
Material:
Cost tiers stratify sharply between commodity polymer formulations and hospital-grade metallurgy, with procurement officers trading acquisition expense against replacement interval and sanitization compliance.
- Plastic:ABS and polypropylene variants deliver lowest unit cost for high-volume institutional procurement. Demand concentrates in United States public school districts and municipal restroom networks where capital budgets constrain specification upgrades, though REACH chemical safety protocols in Europe are forcing compound reformulation for CE marking retention.
- Stainless Steel:Austenitic grades with antimicrobial surface treatments command durability premiums in hospital-grade specifications. Procurement concentrates in United States acute care settings where FDA sanitation guidelines govern sealed containment design and extended replacement intervals justify higher capital outlay.
- Aluminum:Lightweight non-ferrous formulations serve mid-tier commercial applications where corrosion resistance and moderate cost intersect.
- Fiberglass:Reinforced polymer composites address niche applications requiring chemical resistance and impact durability in industrial environments.
Plastic occupies broadest installed base across public restroom infrastructure. Stainless steel is where margin pools concentrate as hospital procurement specifications escalate sanitization standards.
End User:
Customer type determines specification authority structure, with clinical stakeholders overriding facilities managers in acute care while procurement departments retain control in educational and commercial settings.
- Hospitals:Acute care networks specify stainless steel construction with antimicrobial surface treatments and sealed containment design. Procurement authority has migrated to infection control committees with clinical backgrounds who prioritize touchless activation and EPA-compliant waste segregation over unit cost in United States healthcare systems.
- Educational Institutions:School districts across California and New York are expanding procurement of touch-free disposal units under tightening EPA restroom hygiene guidelines. Capital planning cycles extend replacement intervals, though sensor-activated designs are compressing upgrade timelines as federal waste segregation protocols specify sealed antimicrobial containment.
- Public Restrooms:Municipal and transportation facility procurement prioritizes durability and vandal resistance in high-traffic environments.
- Commercial Spaces:Office and retail facility managers balance aesthetic integration with maintenance efficiency in restroom design specifications.
Hospitals command premium pricing tiers through clinical specification authority. Educational institutions are where volume expansion concentrates as federal hygiene mandates accelerate procurement across United States school districts.
Design:
Aesthetic positioning stratifies across architectural integration requirements, with modern minimalism commanding premium positioning in commercial spaces while traditional configurations retain share in heritage facility retrofits.
- Modern:Clean-line geometries with concealed hardware and neutral finishes dominate new commercial construction and healthcare facility renovations. Demand concentrates in premium office and hospitality segments where restroom design signals facility quality to occupants.
- Eco-Friendly:Recycled content formulations and biodegradable liner compatibility address corporate sustainability procurement criteria. Specification is gaining traction in United States commercial spaces with published ESG commitments and LEED certification targets.
- Traditional:Ornate detailing and heritage-appropriate proportions serve historic building preservation requirements and conservative institutional aesthetics.
- Customizable:Configurable finishes, branding integration, and dimensional adaptation address flagship corporate facilities and hospitality venues with distinctive design standards.
Modern design dominates new construction specifications across commercial and healthcare segments. Eco-friendly configurations are where specification growth concentrates as corporate sustainability procurement criteria harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA restroom hygiene mandates are accelerating specification upgrades across United States school districts, while China's provincial manufacturing clusters and India's sanitation infrastructure programs reshape supply and demand geography.
United States
California and New York school districts are expanding procurement of touch-free disposal units under tightening federal waste segregation protocols. FDA guidelines on medical facility sanitation govern hospital-grade antimicrobial specifications. Manufacturing and distribution concentrate in Midwest industrial corridors serving institutional supply chains.
China
Domestic hygiene infrastructure spending is fragmenting production across Guangdong and Zhejiang provincial clusters. GB standards on public restroom equipment are tightening quality specifications for institutional procurement. Shenzhen and Hangzhou manufacturing hubs are scaling cost-optimized plastic variant output for regional supply.
Germany
REACH chemical safety protocols are restricting plasticizers in polymer receptacle formulations, displacing volume toward stainless steel variants. CE marking compliance requirements extend requalification timelines for compound reformulation. Bavarian and North Rhine-Westphalian healthcare networks are specifying permanent antimicrobial surface treatments in new construction tenders.
India
Swachh Bharat Mission infrastructure rollout is creating first-mover advantage for suppliers securing municipal tender relationships. Central government sanitation targets are mandating enclosed containment in public educational facilities. Maharashtra and Gujarat state procurement offices are consolidating vendor relationships for high-volume institutional deployment.
Japan
Metropolitan facility managers are integrating touchless activation systems in premium commercial restroom renovations. JIS standards on public hygiene equipment are specifying sensor-activated mechanisms for high-traffic transportation hubs. Kanto and Kansai regional healthcare networks are prioritizing sealed containment design in acute care capital planning.
Sanitary Napkin Receptacles Market Competitive Landscape
Multinational hygiene conglomerates and regional manufacturing specialists split the market between premium institutional specifications and cost-optimized volume production. Consolidation pressure concentrates around electromechanical component supply and antimicrobial surface treatment capabilities. Three archetypes dominate: integrated hygiene corporations with institutional supply contracts, regional fabricators with provincial manufacturing scale, and component specialists with sensor mechanism expertise. Competitive moves center on strategic partnerships for touchless technology licensing and backward integration into antimicrobial material supply.
Among integrated hygiene corporations, Kimberly-Clark Corporation and Essity Aktiebolag exemplify divergent geographic anchoring strategies. Hengan International Group Company Limited occupies a position within the Asia-Pacific cost-optimized manufacturing tier. These three entities represent the spectrum from North American institutional distribution dominance to European stainless steel margin concentration to Chinese provincial scale production.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Hengan International Group Company Limited |
| Kao Corporation |
| Essity Aktiebolag |
| Unicharm Corporation |
| Ontex Group NV |
| Edgewell Personal Care Company |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Los Angeles container freight corridors transmit cost volatility from Guangdong manufacturing clusters into North American distributor margins, amplifying price spreads between stainless steel hospital-grade units and plastic variants procured by budget-constrained school districts.
Pricing Analysis
Price differentiation between California hospital networks and Midwest school districts exceeds forty percent for equivalent capacity units. Three-tier pricing structure across premium antimicrobial steel, standard aluminum, and economy ABS plastic segments governs institutional procurement. Cost compression in the plastic tier is intensifying because Zhejiang provincial scale expansion floods export channels with undifferentiated volume. Educational procurement officers exhibit highest price sensitivity, while infection control committees in acute care settings prioritize sealed containment performance over unit cost.
Supply Chain Analysis
Stainless steel feedstock sourcing centers on Indonesian nickel smelters and Chinese ferrochrome producers before fabrication in Guangdong and Zhejiang provincial clusters. Electromechanical sensor components draw from South Korean and Japanese specialist manufacturers, creating single-source vulnerability for automatic unit assemblers. Tariff exposure on aluminum sheet imports constrains margin stability for mid-tier producers serving commercial building retrofits. Distribution runs through institutional supply contractors and healthcare GPO networks rather than direct manufacturer-to-facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority fragmentation across infection control committees, educational procurement officers, and facilities managers creates defendable niche positions for differentiated product architectures.
For Market Incumbents: Build certification moats around EPA-registered antimicrobial surface treatments and touchless mechanism IP. Kimberly-Clark and Essity should deepen backward integration into ionic silver coating supply to offset electromechanical component cost inflation. Securing exclusive sensor technology licensing from Japanese or South Korean specialists limits entrant replication of automatic unit specifications. For New Entrants and Emerging Players: Maharashtra and Gujarat state procurement offices under India's Swachh Bharat Mission represent the most penetrable institutional demand cluster. Municipal tender relationships in secondary Indian cities lack entrenched supplier relationships. Positioning as low-cost stainless steel fabricators with rapid CE marking compliance for eventual European export offers a viable go-to-market angle. For Investors and Strategic Acquirers: Regional fabricators with vacuum deposition capabilities for permanent antimicrobial coatings represent the priority acquisition archetype. Long-term viability hinges on embedded surface treatment technology displacing aftermarket spray applications. Monitor EPA registration timelines for novel copper alloy substrates as the inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Backward Integration | Captive ionic silver supply secures margin pools against raw material volatility. |
| Sensor Technology Licensing Agreement | Japanese electromechanical partnerships differentiate automatic units in hospital procurement. |
| India Municipal Tender Partnership | Swachh Bharat Mission relationships establish first-mover positioning in high-volume institutional deployment. |
| CE Marking Fast-Track Investment | REACH-compliant compound reformulation opens displaced polymer volume in German healthcare networks. |
| IoT Fill Monitoring Platform Launch | Wireless telemetry integration creates service-contract revenue streams in facility management outsourcing. |
Research Methodology
A spread of perspectives from hospital infection control officers, educational procurement directors, facilities management executives, and antimicrobial coating specialists converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against EPA registration databases, FDA medical device filings, and institutional supply contract disclosures. Customs records from Guangdong and Zhejiang export corridors, REACH chemical safety protocol amendments, and Swachh Bharat Mission tender announcements furnished additional triangulation anchors. Bottom-up unit demand estimates from end-use segments were cross-checked against top-down manufacturing capacity assessments.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by mounting configuration and activation mechanism, material tier stratification by metallurgical grade and polymer compound, and end-user differentiation between clinical specification authority and budget-constrained procurement. CAGRs were derived from replacement cycle compression rates for sensor-activated units and capital planning interval extensions for stainless steel hospital-grade specifications. Analysis window inputs included EPA restroom hygiene mandate implementation timelines and provincial manufacturing cluster expansion trajectories.
Practitioners should monitor EPA antimicrobial registration delays, aluminum price volatility transmitted through LME futures curves, and sensor component supply concentration among Japanese and South Korean electromechanical specialists for early signals of forecast revision. Cross-checking against institutional supply distributor inventory turnover data and healthcare GPO contract renewal patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Knife Set Market
Household Items
Cast Iron Cookware Market
Household Items
Luxury Massage Chair Market
Household Items
Netherlands Cookware Market
Household Items
Compressed Tablet Towel Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Wipes Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Coffin and Cremation Urn Market
Household Items
Washing Machine Cleaner Market
Household Items
Electric Shoe Polisher Market
Household Items
Air Mattress Market
Household Items
Electric Tealight Candles Market
Household Items
Washing Capsules Market
Household Items
Kitchen Towel Market