
 South Korea Cookware Market | 2026-2036
South Korea Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Cookware Market Insights
Smart kitchen subscription services and software-enabled cooking assistance is restructuring how South Korean consumers acquire cookware value. Coway leverages its home appliance ecosystem to bundle connected cookware with air and water purification units. Samsung Electronics anchors premium positioning through induction-integrated cooktop ecosystems that require matched vessel specifications. Lock & Lock competes aggressively in the mass-market storage-to-cookware extension with borosilicate and ceramic-coated lines.
Cookware comprises vessels and containers designed for food preparation, heating, and serving, typically fabricated from metals such as aluminum alloy or multi-ply stainless steel with thermal conductivity ratings exceeding 200 W/m·K, or from ceramic composites fired above 1,200°C for chemical stability. Stainless steel product types dominate commercial kitchens in Seoul and Busan due to durability under MFDS-mandated sanitation cycles. Non-stick aluminum lines show the fastest expansion in online retail channels where coating technology claims drive conversion. Cast iron occupies a niche premium tier among home enthusiasts seeking thermal mass for Korean barbecue-style table cooking.
MFDS food-contact notifications and KTL electromagnetic compatibility standards shape product entry requirements for both domestic manufacturers and importers. The Korea Consumer Agency's safety monitoring program periodically recalls cookware with excessive heavy metal migration, pressuring supply chain documentation. Stakeholders must monitor how upcoming revisions to electrical appliance safety rules affect induction-compatible cookware certification scope and testing costs.
Market Dynamics
Induction-compatible vessel specifications are compressing replacement cycles as Seoul apartment complexes retrofit kitchen infrastructure, forcing cookware portfolios to align with electromagnetic heating standards rather than legacy gas compatibility.
Growth Catalysts
- MFDS food-contact material notifications:Stricter heavy metal migration limits are accelerating certified product turnover in retail channels, creating pull-through demand for compliant inventory.
- Busan food service corridor expansion:Restaurant-grade stainless steel procurement is concentrating in this southeastern cluster as hospitality infrastructure scales.
- Multi-ply thermal conductivity engineering:Aluminum-stainless laminates exceeding 200 W/m·K ratings are displacing single-material vessels in premium home segments.
Market Restraints
- Specialty steel input volatility:Nickel and chromium price swings compress margin stability for domestic stainless steel fabricators.
- Coating technology import dependence:Ceramic and sol-gel formulations concentrate among German and Japanese chemical suppliers, creating supply vulnerability.
- KTL electromagnetic compatibility testing backlog:Certification queue delays extend product launch timelines by four to eight weeks for induction-compatible lines.
Strategic Opportunities
- Gwangju-Jeonnam manufacturing belt:Underdeveloped cookware production capacity in southwestern provinces offers greenfield facility potential with lower labor costs than Seoul metro.
- Smart kitchen ecosystem convergence:Bluetooth-enabled temperature monitoring vessels paired with recipe applications are opening subscription revenue streams beyond hardware sales.
- Jeju Island tourism hospitality procurement:Resort and boutique hotel kitchen outfitting cycles create concentrated demand spikes for premium ceramic-coated lines.
Industry Challenges
- Coating chemistry technical talent scarcity:Formulation specialists with fluoropolymer and ceramic sol-gel expertise command premium wages, constraining R&D team scaling.
- Legacy gas-cookware inventory obsolescence:Distributors face write-down pressure as induction penetration renders flat-bottom aluminum lines uncompetitive.
- MFDS-KTL dual certification synchronization:Misaligned testing schedules between food-contact and electromagnetic agencies create launch coordination friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Cookware Market |
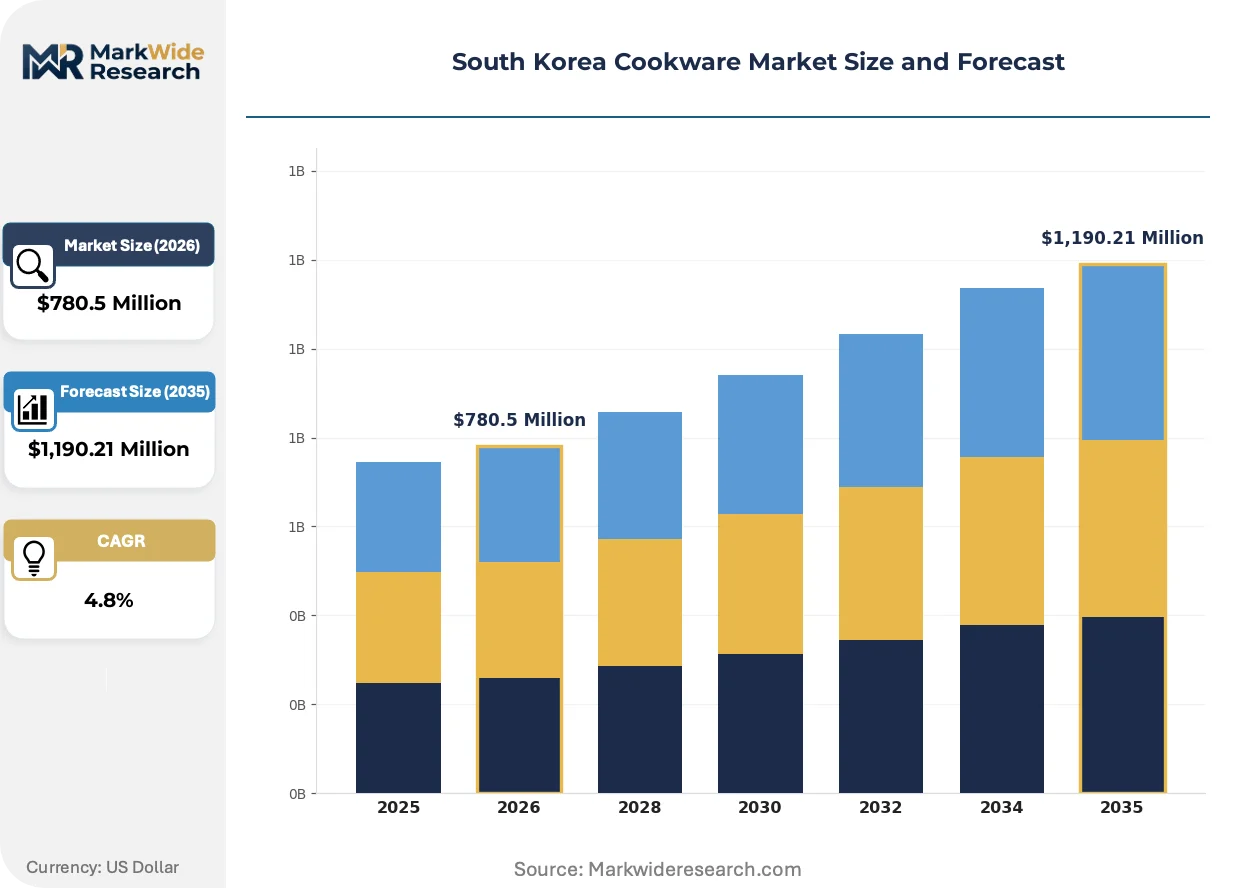
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,190.21 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-stick, Stainless Steel, Cast Iron, Copper Material: Aluminum, Ceramic, Glass, Enamel End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Samsung Electronics, Coway, Lock & Lock, SCANPAN, KitchenAid, Cuckoo Electronics, Winia Electronics, Fissler, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Cookware Market Trends and Innovations
Connected cooking infrastructure and material science advances are restructuring how South Korean households and commercial kitchens evaluate vessel performance, shifting purchasing criteria from durability alone to thermal precision and ecosystem compatibility.
Multi-ply bonded construction with copper or aluminum cores is expanding into mid-market retail segments as domestic manufacturers master roll-bonding automation. Younger Seoul households are adopting these vessels at twice the rate of single-ply alternatives. This thermal performance democratization is compressing the premium tier's historical price premium by fifteen to twenty percent.
KTL electromagnetic compatibility standards revision is tightening field emission limits for induction-compatible cookware, forcing redesigns of ferritic stainless steel formulations. Domestic testing laboratories are expanding capacity to handle the certification surge. Small and mid-size importers face the steepest compliance cost escalation as in-house testing becomes uneconomical.
Subscription-based cookware refresh programs are displacing traditional ownership models in Seoul's dense apartment districts. Young professionals and newly formed households are piloting these services through home appliance ecosystem bundling. Daegu and Daejeon secondary cities show the fastest adoption velocity as the model proves operational viability beyond the capital region.
South Korea Cookware Market Segmentation
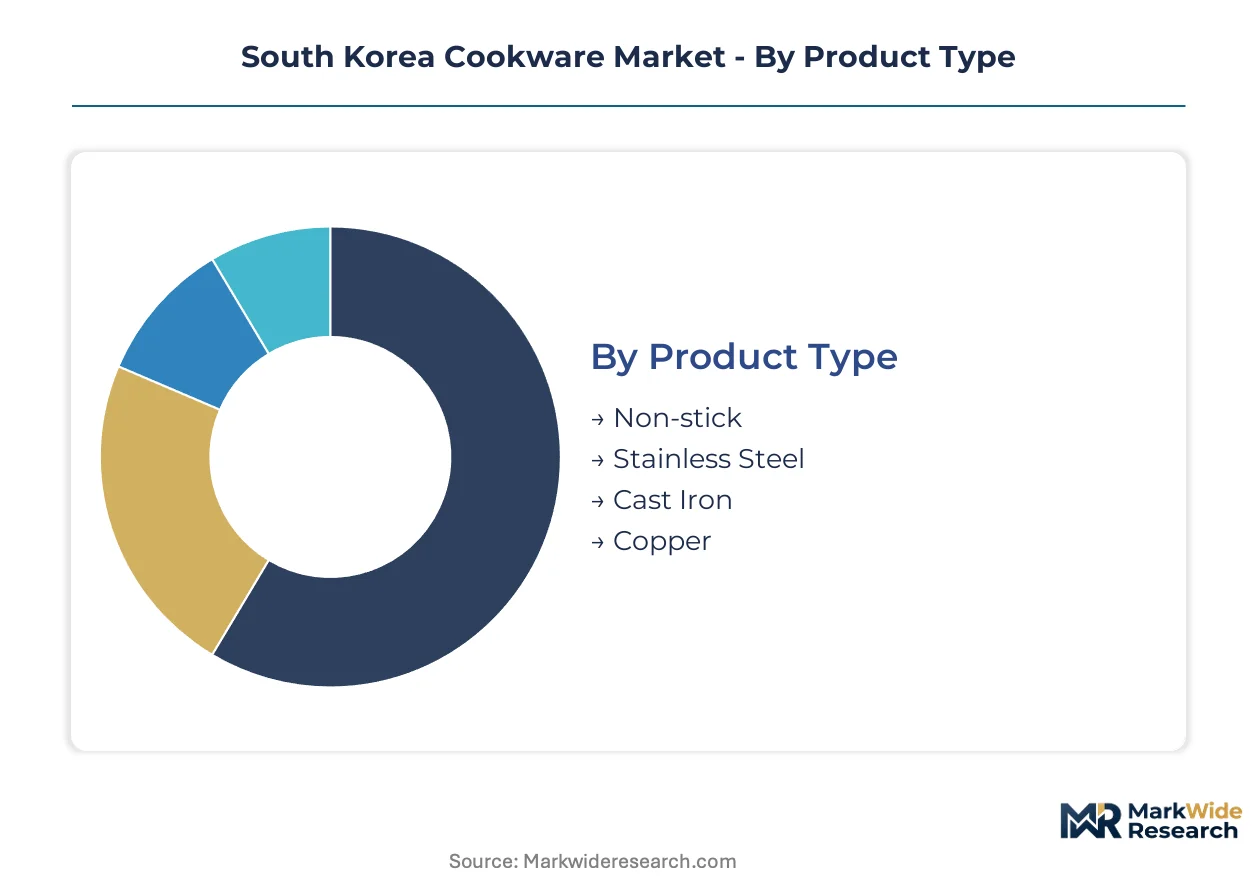
Segmentation in South Korea's cookware market tracks how Seoul apartment infrastructure retrofits and MFDS compliance requirements reshape procurement patterns across household and commercial buyers. Material specifications and distribution access determine competitive positioning more than brand heritage alone.
Product Type:
Purchase decisions pivot on induction compatibility and thermal conductivity specifications as Seoul's residential stock converts from gas infrastructure.
- Stainless Steel:Multi-ply laminates with aluminum or copper cores exceeding 200 W/m·K ratings dominate Busan restaurant procurement and Seoul commercial kitchen upgrades. MFDS-mandated sanitation durability drives replacement cycles in food service corridors where dishwashing protocols stress single-material alternatives.
- Non-stick:Ceramic and sol-gel coated aluminum lines are expanding most quickly through online retail channels where coating technology claims drive conversion among younger Seoul households. Import dependence on German and Japanese chemical suppliers creates supply vulnerability during certification surges.
- Cast Iron:Thermal mass properties serve Korean barbecue-style table cooking enthusiasts in premium home segments. Enamel-coated variants from domestic foundries command price premiums over uncoated imports.
- Copper:Professional-grade solid and tin-lined vessels concentrate in Seoul's high-end restaurant tier where thermal precision justifies maintenance-intensive ownership.
Volume sits with stainless steel; growth tilts toward non-stick lines as coating chemistry advances and induction compatibility standardizes.
Material:
Cost tier stratification separates commodity inputs from certified food-contact formulations that satisfy KTL and MFDS dual requirements.
- Aluminum:Roll-bonded and anodized grades form the substrate backbone for mid-market non-stick production. Price volatility in alumina refining compresses margin stability for domestic fabricators serving mass retail channels.
- Ceramic:Sol-gel and glass-ceramic coatings fired above 1,200°C are displacing legacy fluoropolymer formulations in Seoul premium segments. Coating chemistry technical talent scarcity constrains R&D team scaling for domestic manufacturers.
- Glass:Borosilicate lines from Lock & Lock's storage-to-cookware extension compete in visual-presentation cookware for social media-driven purchase decisions.
- Enamel:Vitreous coatings on cast iron and steel substrates serve heritage-brand positioning and color-differentiated retail placement in specialty store channels.
Aluminum captures shipment volume; ceramic formulations gain share fastest as heavy metal migration limits tighten.
End User:
Application intensity and replacement frequency create divergent specification requirements across consumption settings.
- Households:Seoul apartment dwellers drive induction-compatible vessel turnover as kitchen infrastructure retrofits accelerate. Smart kitchen ecosystem bundling from home appliance manufacturers is restructuring acquisition patterns toward subscription refresh models.
- Restaurants:Busan's expanding food service corridor concentrates procurement of MFDS-certified stainless steel for high-cycle sanitation compliance. Multi-ply thermal conductivity engineering displaces single-material vessels in premium kitchen fit-outs.
- Catering Services:Volume procurement emphasizes durability under transport stress and standardized portion control across institutional settings.
- Food Trucks:Mobile operations prioritize lightweight aluminum and compact storage configurations for constrained workspace environments.
Restaurant procurement anchors revenue; household replacement cycles show the steepest expansion trajectory as smart kitchen convergence accelerates.
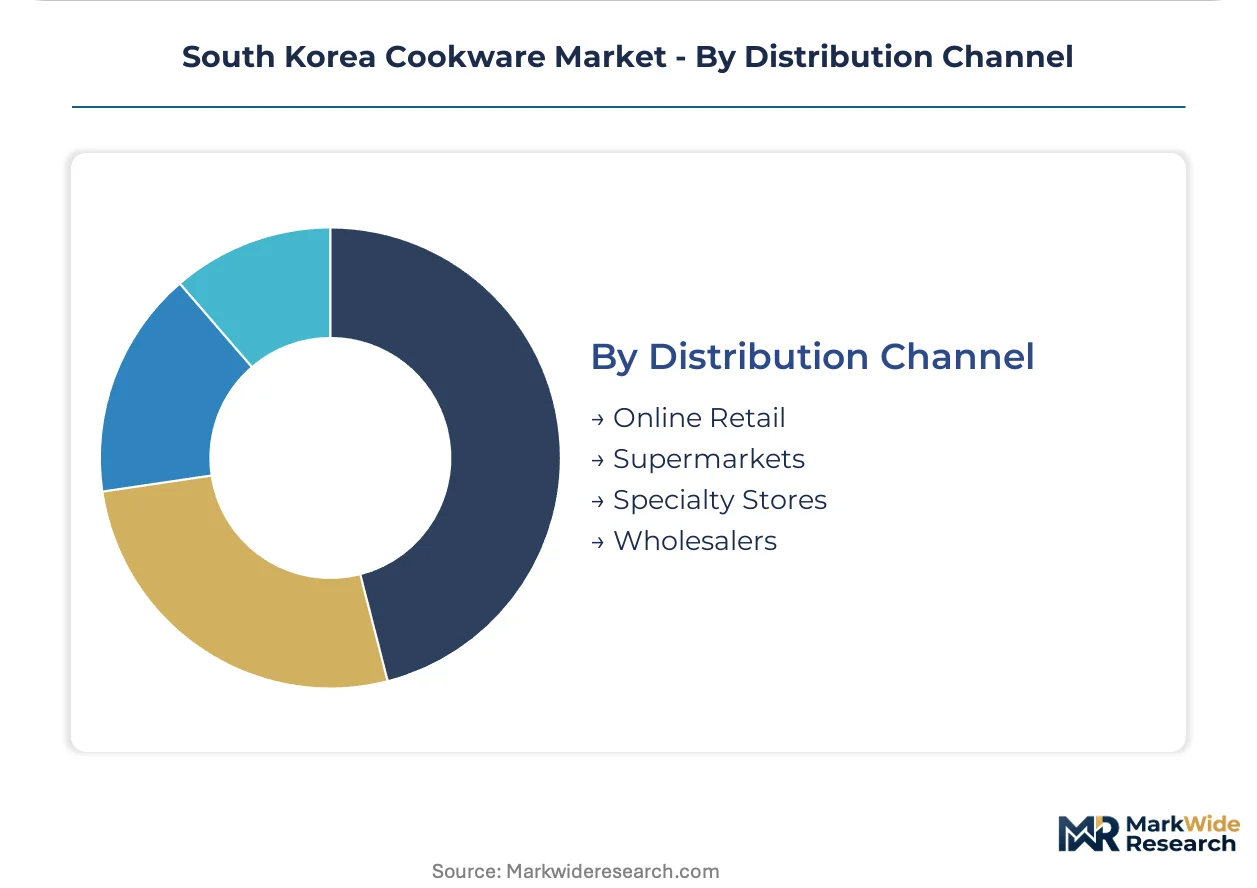
Distribution Channel:
Customer type and purchase urgency determine channel preference between immediate physical inspection and digital convenience.
- Online Retail:Non-stick aluminum lines with coating technology claims convert efficiently through detailed specification disclosure and review aggregation. Daegu and Daejeon secondary cities show fastest adoption velocity for subscription-based refresh programs.
- Supermarkets:Mass-market stainless steel and basic non-stick lines serve emergency replacement and gift purchase occasions with limited deliberation time.
- Specialty Stores:Premium multi-ply and copper vessels require tactile evaluation and staff consultation for thermal performance justification.
- Wholesalers:Restaurant-grade procurement concentrates through Busan corridor distributors with MFDS documentation and volume pricing structures.
Supermarket volume remains largest; online retail climbs fastest as connected cooking infrastructure drives digital-native purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area dominates South Korean cookware procurement through apartment kitchen retrofits and smart home ecosystem bundling. The region concentrates MFDS certification activity and KTL electromagnetic testing capacity. Busan-Ulsan anchors restaurant-grade stainless steel demand through food service corridor expansion.
Seoul Capital Area
Apartment dwellers drive induction-compatible vessel turnover as residential complexes retrofit from gas infrastructure. MFDS food-contact material notifications enforce stricter heavy metal migration limits across retail channels. Gwangjin and Songpa districts concentrate smart kitchen subscription pilots linking connected cookware to home appliance ecosystems.
Busan-Ulsan
Restaurant-grade stainless steel procurement concentrates in this southeastern corridor as hospitality infrastructure scales. KTL electromagnetic compatibility standards shape product entry requirements for imported metal lines. Haeundae and Seomyeon clusters anchor commercial kitchen fit-outs demanding MFDS-mandated sanitation durability.
Daegu-Gyeongbuk
Secondary city households show fastest adoption velocity for subscription-based cookware refresh programs beyond the capital region. The Korea Consumer Agency's safety monitoring program periodically recalls non-compliant inventory, pressuring distributor documentation. Gyeongsan manufacturing zones supply mid-market aluminum substrates to national retail networks.
Daejeon-Sejong
Government complex relocation has stimulated residential construction and associated kitchen outfitting cycles. KTL testing laboratory expansion here addresses certification queue delays that extend product launch timelines. Sejong's planned city design incorporates induction-ready infrastructure from inception, bypassing retrofit friction.
Gwangju-Honam
Southwestern provinces offer greenfield facility potential with lower labor costs than Seoul metro for domestic fabricators. Underdeveloped cookware production capacity creates opportunity for multi-ply thermal conductivity engineering investment. Jeju Island tourism hospitality procurement generates concentrated demand spikes for premium ceramic-coated lines accessible through Honam distribution channels.
South Korea Cookware Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Korea's cookware market. Domestic foundries and metal fabricators maintain in-house forging and roll-bonding capacity, while brand marketers outsource vessel production to specialized third-party manufacturers. Three strategic archetypes dominate: home appliance ecosystem bundlers leveraging connected device platforms, mass-market storage-to-cookware extenders exploiting retail distribution scale, and imported premium specialists commanding specialty store placement. Competitive moves center on smart kitchen convergence partnerships and MFDS-KTL dual certification synchronization to accelerate compliant product launches.
Among domestic ecosystem bundlers, Samsung Electronics and Coway exemplify the home appliance convergence archetype, anchoring premium positioning through induction-integrated platform strategies. Lock & Lock represents the mass-market extension model, leveraging storage container distribution networks into cookware line expansion. These three Korean companies illustrate how domestic players compete against SCANPAN, KitchenAid, and Fissler imports through differentiated channel access rather than direct product parity.
| Leading Market Players |
|---|
| Samsung Electronics |
| Coway |
| Lock & Lock |
| SCANPAN |
| KitchenAid |
| Cuckoo Electronics |
| Winia Electronics |
| Fissler |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Nickel and chromium alloy inputs cascade through South Korea's stainless steel cookware tiers, compressing margins for domestic fabricators while elevating price premiums for multi-ply thermal conductivity engineering that exceeds MFDS food-contact certification thresholds.
Pricing Analysis
Throughput-based thermal performance anchors value-based pricing for induction-compatible vessels, with certified multi-ply laminates commanding premiums over single-material alternatives. Price differentiation rests on MFDS compliance grade and KTL electromagnetic compatibility tier, with restaurant procurement in Busan showing lowest price sensitivity due to mandated sanitation durability requirements. Cost compression in mass-market aluminum lines is intensifying because coating chemistry import dependence exposes fabricators to German and Japanese supplier pricing power. Younger Seoul households in online retail channels exhibit highest price sensitivity, while commercial kitchen operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for ceramic and sol-gel coating formulations force Korean manufacturers to qualify both German and Japanese chemical suppliers, extending procurement cycles. Geographic supply concentration draws from China for aluminum substrate, Germany and Japan for coating chemistry, and domestic Gwangju-Jeonnam belt for final assembly. Raw material dependencies center on nickel-chromium specialty steel, alumina refining output, and imported sol-gel precursors. Single-source vulnerability in coating technology creates supply disruption exposure during MFDS certification surges. Distribution runs through Busan corridor wholesalers for restaurant-grade procurement and Seoul-centric online retail for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as MFDS-KTL dual certification synchronization costs force smaller importers and fabricators toward exit or acquisition.
For Market Incumbents: Hedge against coating chemistry import dependence by securing captive supply agreements with German sol-gel specialists or accelerating domestic R&D hiring despite formulation talent scarcity. Defensive positioning requires vertical integration into Gwangju-Jeonnam manufacturing capacity to capture labor cost advantages over Seoul metro operations. Channel control through smart kitchen ecosystem bundling with home appliance platforms protects against pure-play cookware entrants. For New Entrants and Emerging Players: Food truck operators represent an underserved buyer archetype with concentrated procurement needs for lightweight aluminum configurations and compact storage designs that incumbent portfolios neglect. Secondary city subscription-based refresh programs in Daegu and Daejeon offer the most penetrable geography, with lower competitive intensity than Seoul's saturated smart kitchen ecosystem. A direct-to-chef go-to-market angle through Busan food service corridor relationships bypasses wholesale distributor gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier domestic fabricators with existing MFDS certification infrastructure but constrained working capital in Gwangju-Honam provinces. Long-term viability across a five-to-ten-year window hinges on induction compatibility standardization completing and smart kitchen convergence maturing beyond early-adopter segments. The signal to watch is KTL testing laboratory capacity expansion resolving certification queue delays and restoring normalized product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | Reduces German and Japanese supplier dependence for sol-gel formulation inputs. |
| Smart Kitchen Ecosystem Partnership | Links Bluetooth-enabled vessels to Samsung and Coway home appliance platforms. |
| Gwangju-Jeonnam Manufacturing Footprint | Captures labor cost advantages versus Seoul metro for multi-ply production. |
| MFDS-KTL Dual Certification Investment | Accelerates compliant product launches amid testing backlog congestion. |
| Subscription Refresh Program Expansion | Displaces ownership models in Daegu and Daejeon secondary city households. |
Research Methodology
MFDS food-contact notification databases, KTL electromagnetic compatibility certification records, and Korea Consumer Agency safety monitoring reports formed the secondary backbone, supplemented by customs trade data on aluminum and specialty steel imports. Primary interviews with cookware brand managers, restaurant procurement officers in Busan's Haeundae corridor, Gwangju manufacturing plant directors, and online retail category buyers validated demand assumptions. Bottom-up shipment estimates by product type and material tier were triangulated against top-down market sizing from household formation rates and commercial kitchen fit-out cycles.
Bottom-up modeling tracked vessel unit economics across stainless steel, non-stick aluminum, cast iron, and copper categories, while top-down analysis anchored on Seoul apartment retrofit penetration and Busan food service corridor expansion. Segmentation dimensions included product type, material formulation, end-user application intensity, and distribution channel access, with regional clusters modeled separately for certification compliance cost variations. CAGRs were derived from induction infrastructure conversion curves and smart kitchen ecosystem adoption velocity, incorporating nickel-chromium price volatility and coating chemistry supply constraints as sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MFDS standards revision timing and KTL electromagnetic compatibility testing capacity expansion. Projections reflect assumptions about induction penetration rates, subscription model operational viability beyond Seoul, and sustained German-Japanese coating chemistry supply stability. A model refresh is warranted upon material change in MFDS heavy metal migration limits or KTL field emission standards revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Asia-Pacific Air Purifier Market
Household Items
Can Opener Market
Household Items
Smart Fork Market
Household Items
Germany Digital Showers Market
Household Items
Folded Tissues Market
Household Items
Thermos Bottle Market
Household Items
Mosquito Lamps Market
Household Items
Chest Freezers Market
Household Items
Compressed Tablet Towel Market
Household Items
Saudi Arabia Cookware Market
Household Items
Global Sports Bottle Market
Household Items
Cutlery Market
Household Items
Disposable Napkins Market
Household Items
Smart Fridge Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Japan Faucets Market