
 Air Humidifier Market | 2026-2036
Air Humidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Air Humidifier Market Analysis
Multi-source component procurement is restructuring supply economics for humidifier manufacturers. Honeywell International Inc. leverages its building automation heritage to dominate commercial and industrial channels. Xiaomi Inc. anchors its position through aggressive cost engineering and ecosystem integration across Asia. Dyson Appliances Ltd. differentiates via air-multiplier engineering and premium design positioning in developed markets.
An air humidifier is an electromechanical device that adds water vapor to ambient air to maintain relative humidity within specified ranges, typically 30-60 percent for human comfort or precise thresholds for industrial processes; units employ ultrasonic piezoelectric transducers, evaporative wick media, or thermal steam generation to achieve controlled moisture output. Ultrasonic models lead residential volume due to silent operation and compact form factors, while evaporative systems sustain industrial preference where mineral-free output prevents equipment corrosion. Smart controls represent the fastest-growing feature category as IoT-enabled humidity sensing and automated climate integration command premium positioning.
The U.S. EPA sets voluntary indoor air quality guidelines that shape consumer expectations for humidifier performance and safety, while FDA oversight classifies clinical-grade units as medical devices with stringent validation requirements. China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility that govern manufacturing compliance for export-oriented producers. Stakeholders must monitor evolving energy efficiency mandates and antimicrobial material regulations as jurisdictions tighten performance benchmarks without harmonization.
Market Dynamics
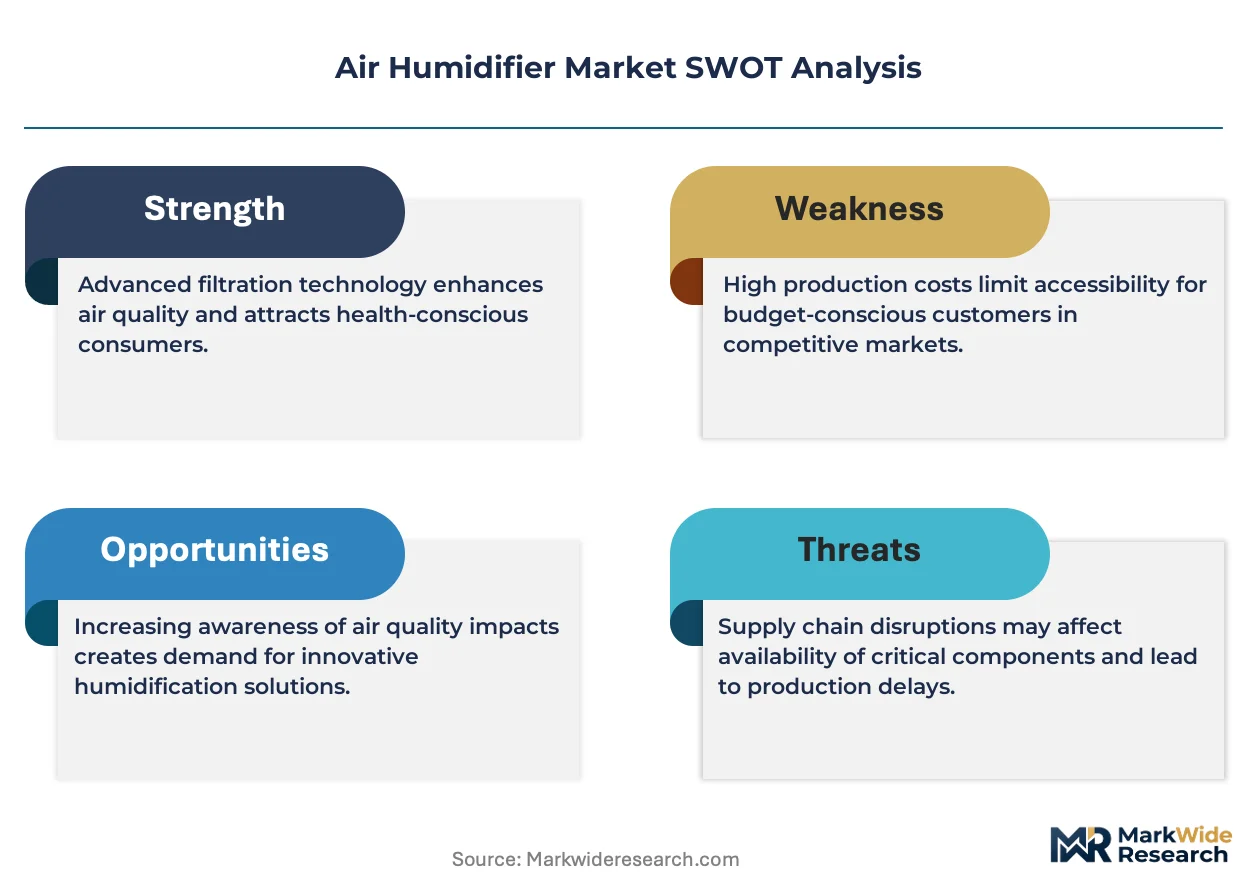
The air humidifier market faces structural pressure from antimicrobial material mandates and energy efficiency tightening across multiple jurisdictions, forcing manufacturers to redesign core components while maintaining cost discipline.
Growth Catalysts
- Healthcare facility expansion:Hospitals and long-term care centers in Germany, Japan, and the United States are installing clinical-grade humidification to protect immunocompromised patients from airborne pathogens.
- Smart home ecosystem integration:IoT-enabled humidity sensors now synchronize with building management systems, creating automated climate control that commands premium positioning in residential retrofits.
- GB standards compliance:China's SAMR enforcement of updated electrical safety and electromagnetic compatibility regulations has consolidated manufacturing quality, enabling export-oriented producers to access developed markets with reduced certification friction.
Market Restraints
- Piezoelectric transducer supply concentration:Ceramic oscillator production clusters in specific East Asian manufacturing zones create single-source vulnerability for ultrasonic humidifier assembly.
- Mineral deposit technical limitation:Evaporative wick systems require continuous water quality management to prevent scale accumulation that degrades output consistency and voids warranty coverage.
- FDA medical device classification friction:Clinical-grade units face extended validation timelines and documentation burdens that delay commercialization for therapeutic applications in respiratory care settings.
Strategic Opportunities
- Underpenetrated residential base in India:Rising middle-class housing stock in Mumbai, Delhi, and Bangalore lacks climate control infrastructure, creating first-mover positioning for compact ultrasonic units with localized voltage compatibility.
- Agricultural greenhouse application emergence:Controlled environment agriculture operators in the Netherlands and Spain are adopting precision humidification to optimize crop yield and reduce water stress in vertical farming installations.
- EU F-Gas Regulation tailwind:Phasedown of fluorinated greenhouse gases is accelerating demand for water-based climate control alternatives that avoid refrigerant-dependent dehumidification-humidification cycling.
Industry Challenges
- Embedded systems firmware certification:Smart humidifier platforms require cybersecurity validation under evolving IEC 62443 standards, extending development cycles for connectivity-enabled product lines.
- Antimicrobial additive regulatory fragmentation:Inconsistent biocide approval frameworks between EPA, ECHA, and national regulators force parallel compliance pathways that inflate formulation testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Humidifier Market |
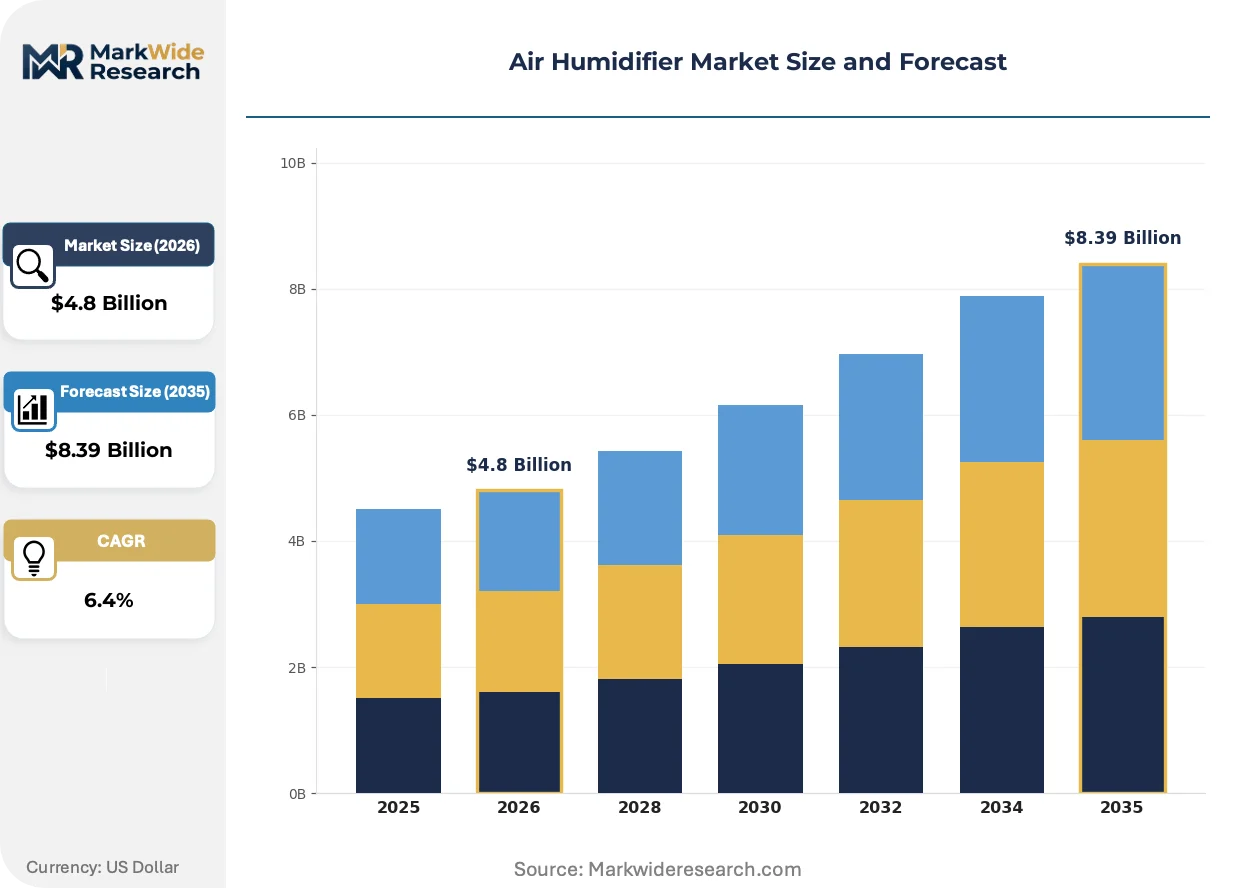
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporative, Ultrasonic, Steam Vaporizers, Impellers End User: Residential, Commercial, Industrial, Healthcare Distribution Channel: Online Retail, Offline Retail, Distributors, Wholesalers Feature: Smart Controls, Filtered, Portable, Decorative |
| Companies Covered | Condair Group, Honeywell International Inc., Armstrong International Inc., Levoit, Dyson Appliances Ltd., Boneco AG, Coway Co. Ltd., Xiaomi Inc., Carel Industries S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Humidifier Market Emerging Trajectories
Humidifier engineering is pivoting toward adaptive moisture delivery and predictive maintenance architectures, with component-level innovation outpacing finished-product differentiation.
Ultrasonic transducer arrays with independent zone control are modularizing humidity management in commercial buildings. Facility managers in Singapore and Dubai are deploying these systems to address microclimate variations across open-plan offices. The technology is modularizing how mechanical contractors specify climate infrastructure, enabling phased installation that reduces upfront capital commitment.
The EPA's updated voluntary indoor air quality guidelines are tightening consumer performance expectations for residential units. Manufacturers serving the United States market must now validate output consistency across variable water hardness conditions. Ultrasonic product categories face the steepest compliance adjustment as mineral dispersion claims undergo enhanced scrutiny.
Direct-to-installer channel bypass is compressing traditional distribution margins for evaporative industrial systems. Mechanical contractors in Germany and France now source wick media and reservoir assemblies separately from control electronics, unbundling what were previously integrated supplier relationships. This pattern is most visible in commercial retrofit projects where specification authority has shifted from facilities departments to HVAC subcontractors.
Air Humidifier Market Segmentation
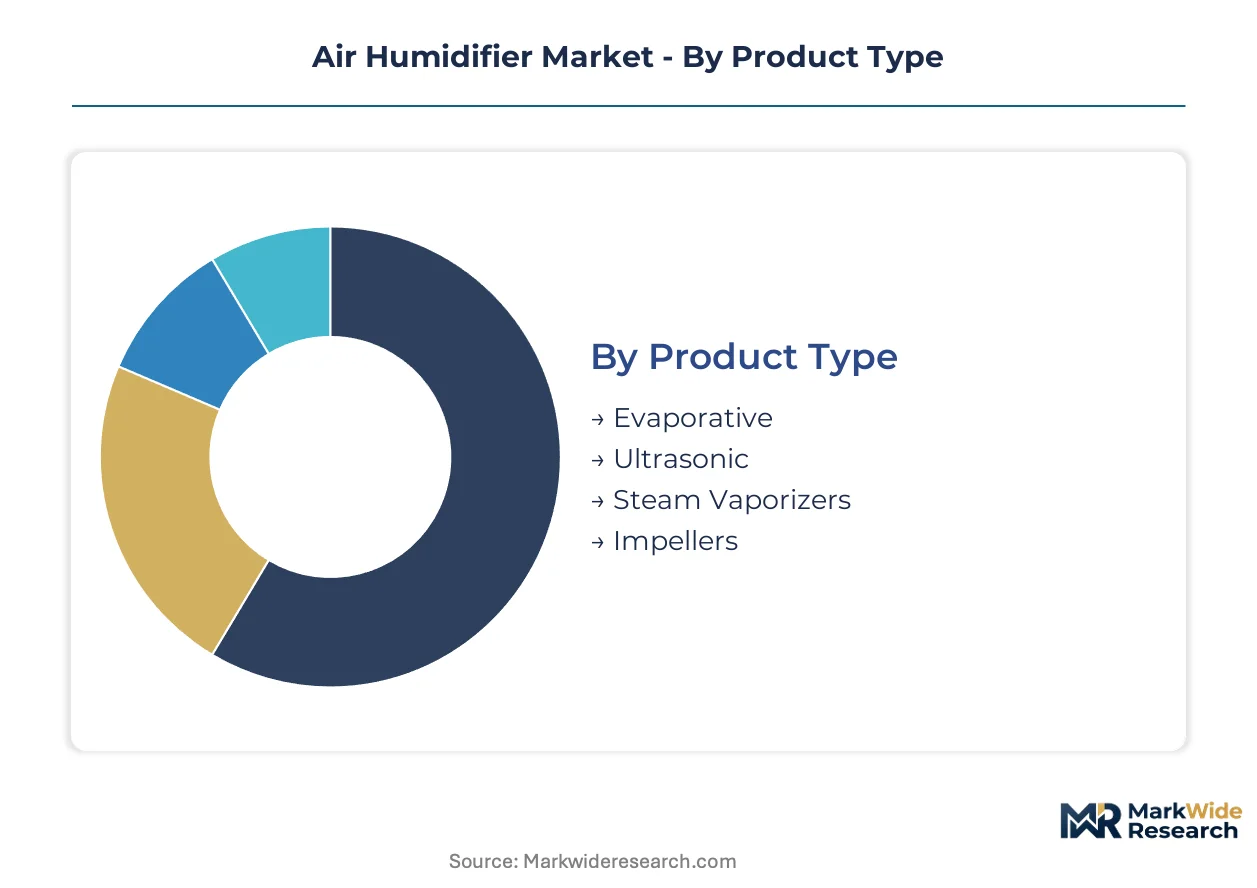
Humidifier purchasing decisions fragment across technical specifications, end-use environments, and channel accessibility. Manufacturers must align product architecture with distinct performance thresholds and procurement workflows.
Product Type:
Standardized ultrasonic platforms dominate residential volume, while evaporative and steam systems command premium positioning through customization for water chemistry and output precision.
- Evaporative:Wick-based systems draw air through moistened media to release humidity without mineral dispersion. Industrial facilities in Germany specify these units to protect corrosion-sensitive electronics from white dust contamination.
- Ultrasonic:Piezoelectric transducers vibrate at megahertz frequencies to atomize water into micro-droplets. Silent operation drives residential preference in Japan and South Korea where compact living demands noise suppression below 30 decibels.
- Steam Vaporizers:Thermal boiling eliminates microbial concerns through heat sterilization. Pediatric clinics specify these for respiratory therapy applications where FDA medical device classification applies.
- Impellers:Rotating disks fling water against diffusers to create cool mist without heating elements. Budget residential segments in India favor these for energy efficiency in voltage-variable grid conditions.
Most installed capacity flows through Ultrasonic. Expansion is steepest in Steam Vaporizers.
End User:
Volume concentrates in price-sensitive residential replacement cycles, while margin accretion shifts toward healthcare and industrial applications with certification barriers.
- Residential:Individual households purchase compact units for seasonal comfort modulation. North American consumers prioritize smart controls that integrate with Alexa and Google Home ecosystems.
- Commercial:Office buildings and retail spaces deploy centralized systems through HVAC contractors. Facility managers in Singapore specify zone-controlled arrays to address microclimate variations across open floor plans.
- Industrial:Manufacturing plants require precise humidity maintenance for process integrity. Textile mills in Bangladesh and printing facilities in Italy invest in heavy-duty evaporative infrastructure to prevent material deformation.
- Healthcare:Hospitals and long-term care centers install clinical-grade units under FDA or EMA oversight. Immunocompromised patient protection drives specification of steam vaporizers with validated microbial elimination.
Residential captures the largest unit volume. Healthcare climbs the fastest on regulatory tailwinds.
Distribution Channel:
Channel selection reflects customer technical sophistication and installation complexity, with direct procurement gaining share in commercial segments.
- Online Retail:E-commerce platforms enable specification comparison and price transparency. Amazon and JD.com dominate residential ultrasonic sales through algorithmic recommendation engines.
- Offline Retail:Big-box stores and appliance specialists provide immediate fulfillment for replacement purchases. Home Depot and Lowe's anchor North American seasonal demand spikes.
- Distributors:HVAC wholesalers carry commercial-grade inventory for contractor specification. Watsco and Ferguson Enterprises control North American commercial evaporative system flow.
- Wholesalers:Bulk procurement serves industrial and healthcare institutional buyers. Group purchasing organizations negotiate multi-site humidification contracts for hospital networks.
Distributors handle the heaviest commercial throughput. Online Retail gains share fastest in residential replacement cycles.
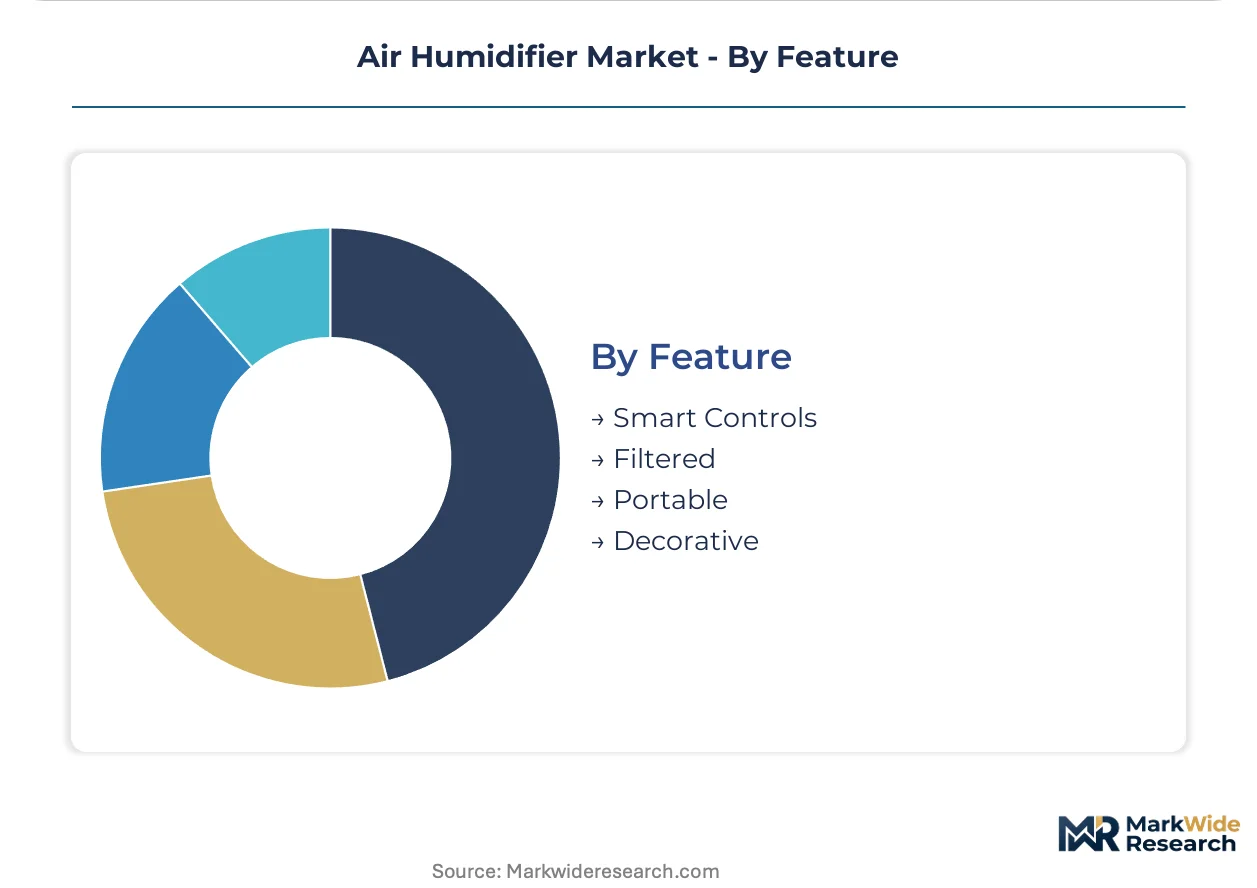
Feature:
Feature bundling separates premium positioning from commodity competition, with connectivity and filtration commanding price premiums.
- Smart Controls:IoT-enabled humidity sensors synchronize with building management systems and voice assistants. Honeywell and Xiaomi compete on ecosystem integration depth.
- Filtered:Activated carbon and HEPA pre-filtration addresses consumer air quality concerns. EPA guideline tightening validates premium positioning for validated filtration claims.
- Portable:Lightweight designs with handle integration serve seasonal and travel applications. Japanese consumers favor these for tatami room flexibility.
- Decorative:Aesthetic casing materials and ambient lighting target design-conscious residential buyers. Dyson commands this segment through sculptural industrial design.
Filtered features anchor the largest installed base. Smart Controls expand most quickly on connected home adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting humidifier production toward jurisdictions with streamlined certification pathways and consolidated component ecosystems. Manufacturers now site final assembly in zones where GB standards, CE marking, or FDA clearance create distinct market-access advantages.
United States
Healthcare facility retrofits and smart home adoption drive specification of clinical-grade and IoT-enabled units. The EPA's updated voluntary indoor air quality guidelines tighten validation requirements for mineral dispersion claims. Dallas and Phoenix emerge as distribution hubs for contractor-channel evaporative systems serving the Southwest's dry climate zones.
Germany
Industrial corrosion protection and precision manufacturing sustain demand for wick-based evaporative infrastructure. ECHA oversight of antimicrobial additive formulations shapes material selection for commercial-grade reservoir assemblies. The Ruhr Valley mechanical engineering cluster houses specification engineers who unbundle integrated systems into component procurement for facility retrofits.
China
Residential middle-class upgrades and export-oriented manufacturing concentrate demand and supply in parallel. SAMR enforcement of updated GB standards for electrical safety and electromagnetic compatibility consolidates quality tiers for global market access. Shenzhen and Dongguan anchor piezoelectric transducer production, creating single-source vulnerability for ultrasonic humidifier assembly chains.
Japan
Compact living constraints and tatami-room flexibility preferences elevate silent ultrasonic models with sub-30-decibel operation. METI energy efficiency benchmarks and PMDA medical device pathways for respiratory therapy units create dual certification tracks. Osaka-based HVAC subcontractors specify zone-controlled arrays for commercial microclimate management.
India
First-time climate control infrastructure in rising middle-class housing stock opens residential penetration for compact ultrasonic units. BIS electrical safety certification and voltage compatibility standards govern localized product variants. Mumbai, Delhi, and Bangalore concentrate demand as housing completions outpace installed humidification capacity.
Air Humidifier Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue ecosystem integration and premium design positioning. The vendor base spans diversified conglomerates with building automation heritage, cost-engineering specialists with platform scale, and industrial design houses commanding margin through aesthetic differentiation. Three archetypes dominate: automation-heritage systems integrators, ecosystem-platform consumer electronics firms, and sculptural-design premium brands. Competitive moves center on M&A for climate-control portfolio expansion and strategic partnerships for IoT ecosystem access.
Among automation-heritage conglomerates, Honeywell International Inc. exemplifies the systems-integration archetype through its building management lineage. Xiaomi Inc. anchors the ecosystem-platform tier with cost-engineered consumer electronics scale. Dyson Appliances Ltd. occupies the design-premium position through sculptural industrial differentiation. Carel Industries S.p.A. and Condair Group represent specialized climate-control engineering firms with commercial and industrial channel focus. Boneco AG and Coway Co. Ltd. sit within the regional-specialist tier, while Levoit exemplifies direct-to-consumer platform brands. Armstrong International Inc. anchors industrial steam-generation applications.
| Leading Market Players |
|---|
| Condair Group |
| Honeywell International Inc. |
| Armstrong International Inc. |
| Levoit |
| Dyson Appliances Ltd. |
| Boneco AG |
| Coway Co. Ltd. |
| Xiaomi Inc. |
| Carel Industries S.p.A. |
| Others |
Supply Flow & Price Mechanics
Piezoelectric ceramic costs cascade through ultrasonic humidifier tiers from Shenzhen assembly floors to North American retail shelves, with transducer pricing volatility compressing margins at the standard tier while premium brands absorb fluctuations through design differentiation.
Pricing Analysis
Input-cost pass-through from ceramic oscillator suppliers tightens standard-tier margins disproportionately. Three-tier pricing structure across premium, standard, and economy levels separates Dyson-level design premiums from Xiaomi-scale volume plays. Price differentiation hinges on certification grade and smart control integration. Pricing pressure stems from antimicrobial additive compliance costs. Residential buyers in India exhibit highest price sensitivity; healthcare procurement committees in Germany show lowest.
Supply Chain Analysis
Freight cost spikes from East Asian ports to European distribution centers amplify landed costs for evaporative wick media assemblies. Component manufacturing clusters in China, South Korea, and Vietnam feed global assembly. Supply chains draw from piezoelectric ceramics, activated carbon filtration media, and ABS polymer casings. Single-source vulnerability concentrates in Shenzhen-Dongguan transducer production zones. Distribution runs through HVAC wholesalers for commercial segments and direct-to-installer channels for industrial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air humidifier market functions as a regulatory compounder where EPA indoor air quality guideline tightening and FDA medical device pathway expansion continuously reshape demand architecture.
For Market Incumbents: Lock in ceramic oscillator supply through backward integration into transducer production or long-term offtake agreements with Ruizhou manufacturers. Defend against Xiaomi-scale ecosystem entrants by deepening smart home platform certification investment. Prioritize antimicrobial formulation pipelines ahead of ECHA biocide registration deadlines.
For New Entrants and Emerging Players: Sensor fusion algorithms for predictive humidity management offer a technology-first wedge into premium residential retrofit segments. Target first-time buyers in Mumbai and Delhi with voltage-resilient ultrasonic units. Pursue direct-to-installer channel partnerships bypassing traditional HVAC wholesale markup structures.
For Investors and Strategic Acquirers: Consolidation pressure builds where component sourcing scale advantages exceed brand equity value in standard-tier manufacturing. Five-to-ten year viability favors climate-control engineering specialists with FDA 510(k) clearance capabilities over consumer electronics assemblers lacking clinical validation infrastructure. Monitor ECHA antimicrobial additive registration rejections as inflection signal for formulation-dependent incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Formulation Pre-Registration | ECHA biocide compliance ahead of 2025 regulatory deadlines protects European market access. |
| Piezoelectric Transducer Backward Integration | Captive ceramic oscillator supply insulates margin from East Asian component price volatility. |
| FDA 510(k) Clinical-Grade Pathway Investment | Respiratory therapy device classification opens hospital procurement channels with reimbursement tailwinds. |
| Smart Home Ecosystem Certification | Matter protocol integration with Alexa and Google Home platforms commands residential premium positioning. |
| Direct-to-Installer Channel Development | Bypassing Watsco-Ferguson wholesale layers captures margin in commercial retrofit specification flows. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HVAC contractors, hospital biomedical engineers, appliance retail category managers, and humidifier OEM procurement leads with secondary validation against EPA guidance documents, FDA 510(k) clearance databases, SAMR GB standard filings, and customs trade flow records. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-weighting approaches distributed value across product type, end user, distribution channel, and feature dimensions throughout the forecast period. CAGRs derived from fitted growth curves against historical shipment trajectories and regulatory milestone timing. Industry-specific inputs included ECHA biocide registration timelines and METI energy efficiency benchmark adoption curves.
The model holds under stable regulatory enforcement trajectories; deviation in antimicrobial additive approval rejections or ceramic supply disruptions would shift volume and value outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Sanitary Metal Ware Market
Household Items
Air Care Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Infrared Sauna Heaters Market
Household Items
North America Liquid Hand Soap Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Thermos Bottle Market
Household Items
Global Laptop Tables Market
Household Items
US Digital Showers Market
Household Items
Hydralight Lanterns Market
Household Items
India Cookware Market
Household Items
Bladeless Neck Fan Market
Household Items
Luxury Massage Chair Market
Household Items
France Digital Showers Market
Household Items
Microwave Safe Utensils Market
Household Items
Wax Removal Aids Market