
 Europe Digital Showers Market | 2026-2036
Europe Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Showers Market Analytics
Hospitality developers are reorganizing specification priorities for digital shower systems across European hotel renovation pipelines. Aqualisa Products Limited anchors the United Kingdom market through installer-trained channel programs and direct trade relationships. Grohe AG leverages its German manufacturing base to control premium distribution across Northern Europe. Hansgrohe SE competes on thermostatic precision engineering and sustainability-certified product lines.
Europe digital showers integrate electronically controlled thermostatic mixing valves with digital interfaces for temperature, flow rate, and preset programming, typically operating within 38°C to 50°C safety ranges with ±0.3°C accuracy to prevent scalding and optimize water consumption. Wall-mounted systems dominate current specification volumes in residential new-build across Germany and France, while app-controlled technology represents the fastest-expanding configuration as hospitality operators seek centralized facility management integration. Sensor-based installations remain niche but command premium margins in healthcare and accessible design segments where touchless hygiene protocols apply.
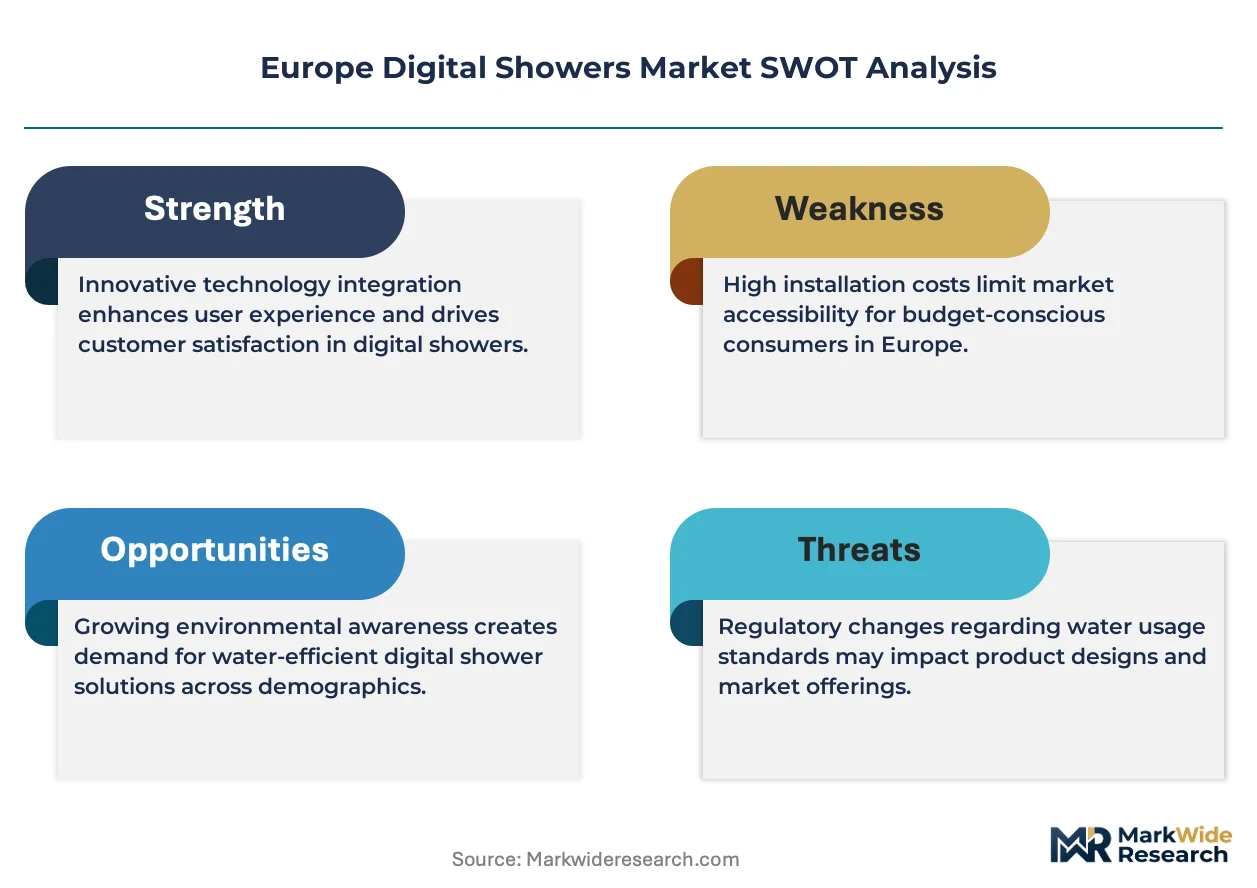
The EU Ecodesign Directive and national transpositions in Germany, France, and Italy mandate maximum flow rates and efficiency labeling that directly shape product development cycles and market access conditions. CE marking under the Construction Products Regulation and country-specific plumbing certifications from KBA-aligned German institutes and French CSTB create layered compliance requirements for cross-border suppliers. Stakeholders must monitor pending revisions to the Drinking Water Directive and national transpositions that could impose new material restrictions on valve components and electronic housing materials.
Market Dynamics
EU Ecodesign Directive flow-rate mandates and the EU Green Deal's building renovation targets are compressing product development cycles and forcing rapid thermostatic valve redesigns across European manufacturers.
Growth Catalysts
- EU Green Deal renovation wave:Building efficiency mandates across Germany, France, and Italy are accelerating bathroom fixture replacement cycles in residential and hospitality sectors.
- CE marking harmonization:Unified Construction Products Regulation compliance is reducing cross-border certification friction for thermostatic mixing valve suppliers.
- Sensor-based hygiene protocols:Touchless digital interfaces are gaining specification in healthcare and accessible design segments where contamination control is paramount.
Market Restraints
- Brass and electronic component cost volatility:Copper alloy input prices and semiconductor shortages are compressing margin structures for mid-tier valve assemblers.
- German manufacturing concentration:Premium thermostatic engineering capacity clusters in Baden-Württemberg and North Rhine-Westphalia, creating geographic supply vulnerability.
- REACH substance restrictions:Pending revisions to SVHC candidate lists threaten lead-free alloy formulations and electronic housing plastics.
Strategic Opportunities
- Eastern European retrofit penetration:Poland, Czech Republic, and Romania present underdeveloped digital shower specification in aging residential building stock.
- App-integrated facility management:Hospitality operators in the United Kingdom and Spain are centralizing water temperature and flow monitoring across multi-property portfolios.
- Drinking Water Directive alignment:Anticipated material purity standards will create first-mover advantage for suppliers with pre-certified valve architectures.
Industry Challenges
- Plumber installer skill gaps:Digital commissioning and app-pairing protocols require training investments that traditional trade channels resist absorbing.
- Multi-layer certification timelines:KBA-aligned German institute testing followed by French CSTB validation extends product launch cycles.
- Legacy mixing valve interoperability:Retrofit installations demand backward-compatible electronic interfaces that increase firmware complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Showers Market |
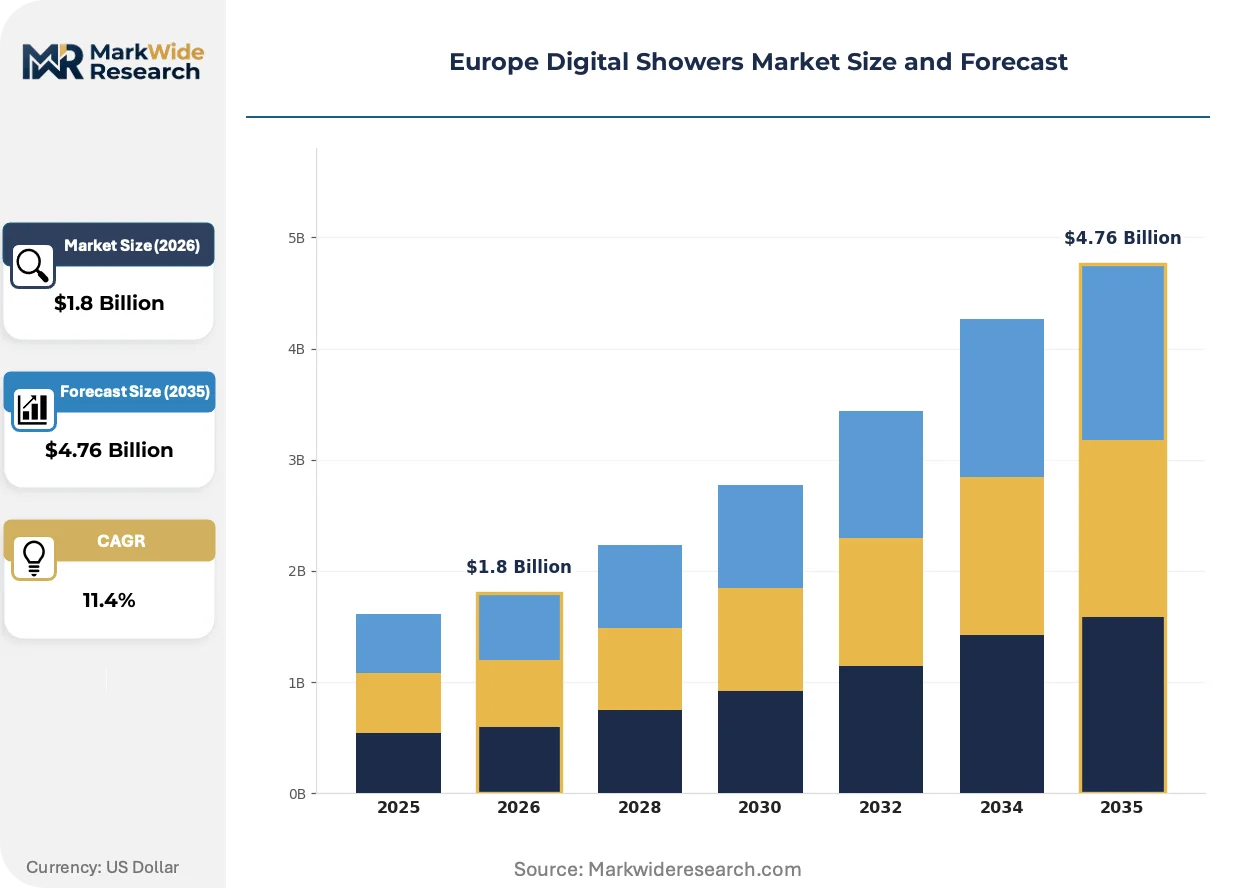
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Ceiling-Mounted, Handheld, Smart Showerheads Technology: Bluetooth, Wi-Fi, App-Controlled, Sensor-Based End User: Residential, Commercial, Hospitality, Healthcare Installation Type: New Installation, Retrofit, Custom Installation, Pre-Configured Systems |
| Companies Covered | Toto Ltd., Aqualisa Products Limited, Kohler Co., Moen Incorporated, Dornbracht Deutschland GmbH & Co. KG, Grohe AG, Lixil Corporation, Roca Sanitario, SA, Hansgrohe SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Showers Market Evolving Landscape
Connected water management systems are fragmenting traditional fixture specification. Thermostatic precision, regulatory compliance, and centralized control capabilities now determine competitive positioning.
Modular digital valve architectures are decomposing integrated thermostatic systems into separable sensor, processor, and actuator components. Hospitality facility managers in Spain and Portugal are piloting these configurations for centralized maintenance scheduling. Component standardization is decomposing proprietary supplier lock-in and enabling third-party firmware integration.
EU Ecodesign Directive water efficiency labeling is tightening maximum flow thresholds for shower outlets sold in Germany, France, and Italy. Manufacturers must redesign nozzle geometries and pressure-compensating inserts to maintain user experience at reduced volumes. Premium product lines are absorbing compliance costs through thermostatic precision positioning.
Installer-trained specification channels are consolidating influence over residential renovation decisions. United Kingdom plumbing merchants and German SHK trade counters now control digital shower selection through exclusive distribution agreements and certified training programs. Direct-to-consumer online channels are losing ground in premium bathroom renovation projects.
Europe Digital Showers Market Segmentation
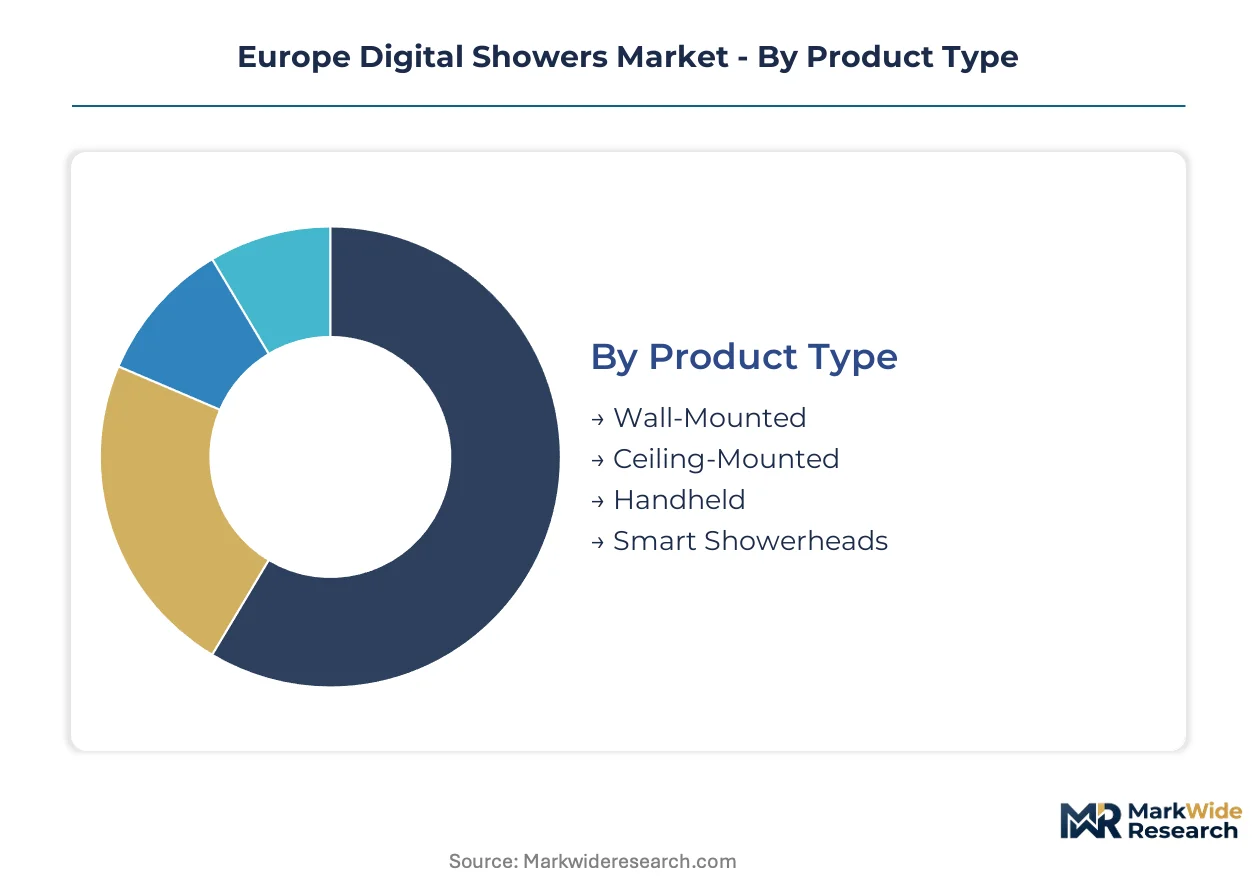
Digital shower specification diverges sharply across European construction channels. Procurement priorities in hospitality retrofit projects differ fundamentally from residential new-build decisions, forcing suppliers to maintain parallel product architectures and certification pathways.
Product Type:
Margin pools concentrate in integrated thermostatic systems that bundle valve hardware with digital control interfaces. Premium positioning depends on precision engineering and installer certification programs rather than commodity nozzle design.
- Wall-Mounted:These systems integrate the thermostatic mixing valve directly into the wall cavity with a digital control panel at shower height. Specification concentrates in German and French residential new-build where concealed plumbing is standard practice. CE marking under the Construction Products Regulation and KBA-aligned German institute testing create compliance barriers that favor established suppliers with certification infrastructure.
- Ceiling-Mounted:Overhead rain shower configurations with integrated digital temperature control. Hospitality operators in Spain and Portugal specify these for luxury suite renovations where architectural minimalism drives design decisions. The installation complexity and specialized waterproofing requirements command premium margins and limit price competition.
- Handheld:Portable digital units with docked charging bases and wireless temperature control.
- Smart Showerheads:Self-contained units embedding thermostatic sensors and microprocessors within the showerhead housing.
Wall-Mounted holds installed capacity. Ceiling-Mounted is rotating up the share rankings.
Technology:
Application context determines connectivity protocol selection. Residential buyers prioritize standalone reliability while hospitality procurement demands centralized fleet management capabilities.
- Bluetooth:Short-range wireless pairing between shower control and personal devices for preset programming. Residential renovation in the United Kingdom favors this protocol for its simplicity and absence of home network dependencies. Installer training requirements remain minimal compared to Wi-Fi configurations.
- Wi-Fi:Cloud-connected systems enabling remote monitoring and firmware updates. Hospitality chains with multi-property portfolios in France and Italy are standardizing on this architecture for centralized facility management integration. Cybersecurity compliance with EU data protection frameworks adds implementation complexity.
- App-Controlled:Smartphone-dependent interfaces replacing physical control panels.
- Sensor-Based:Touchless activation systems using proximity detection for water flow initiation.
Bluetooth dominates unit volumes. Wi-Fi is climbing the fastest as hospitality procurement scales.
End User:
Customer type segmentation reveals diverging specification authority structures. Residential decisions flow through installer-trained merchants while commercial procurement centralizes through facilities management hierarchies.
- Residential:Individual homeowners and private landlords specifying digital showers through renovation projects. German SHK trade counters and United Kingdom plumbing merchants control selection through exclusive distribution agreements and certified training programs that steer buyers toward pre-approved product lines.
- Hospitality:Hotel and serviced apartment operators with standardized room fit-out requirements. Premium bathroom renovation cycles across Spain, Portugal, and Italy are accelerating specification of app-controlled systems with centralized monitoring for water temperature compliance and maintenance scheduling.
- Commercial:Office buildings, retail spaces, and institutional facilities with public washroom installations.
- Healthcare:Hospitals, care homes, and accessible housing where thermostatic precision prevents scalding injuries.
Residential absorbs the highest unit volumes. Hospitality is gaining share fastest on retrofit pipeline expansion.
Installation Type:
Project phase determines compatibility requirements and margin structure. New installations allow optimized system design while retrofits demand backward-compatible interfaces that increase engineering complexity.
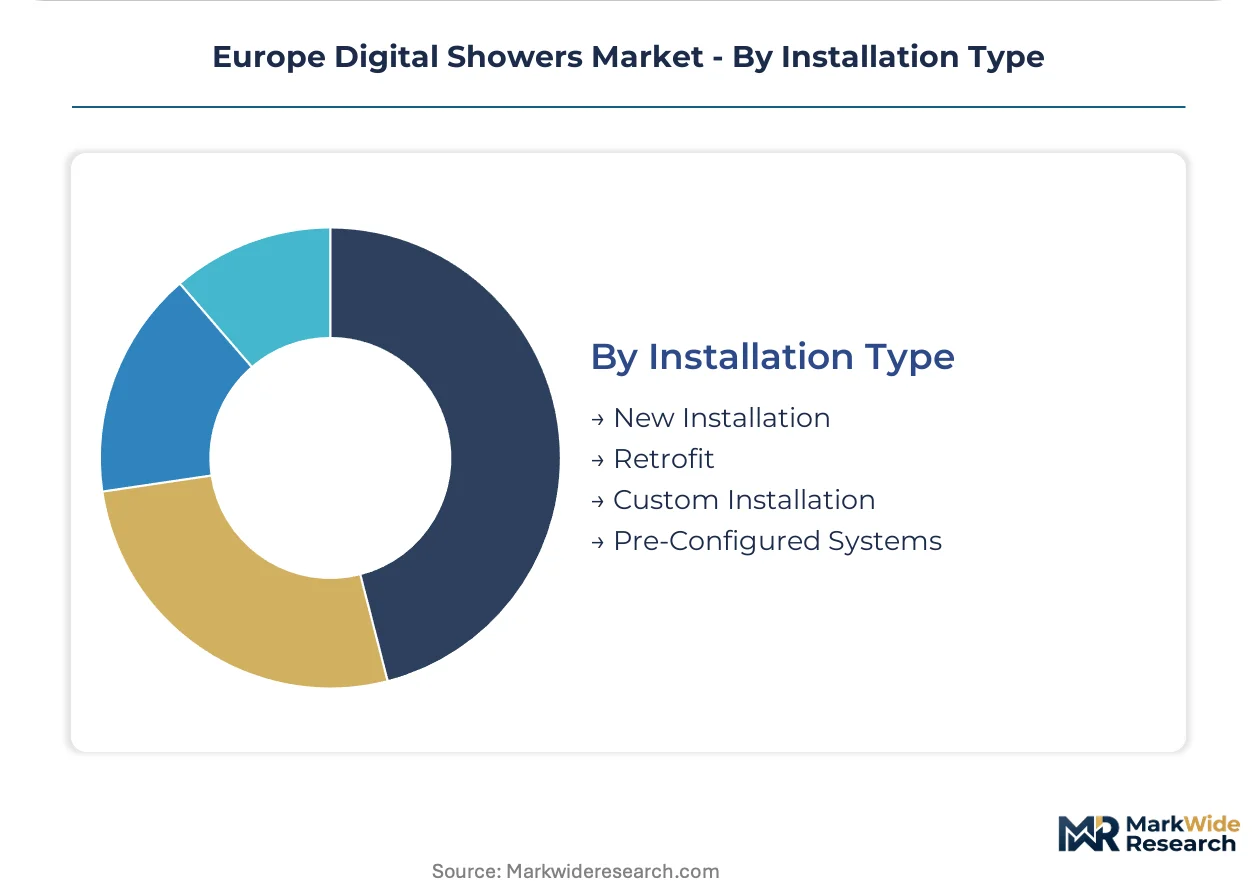
- New Installation:Integrated digital systems specified during construction phase with concealed plumbing and dedicated electrical supply. French and German residential development permits full thermostatic valve optimization without legacy infrastructure constraints.
- Retrofit:Replacement installations demanding compatibility with existing pipework and pressure conditions. United Kingdom bathroom renovation cycles are expanding this segment as aging housing stock undergoes efficiency upgrades. Firmware complexity increases to accommodate variable supply conditions.
- Custom Installation:Bespoke configurations for architectural specifications or accessibility requirements.
- Pre-Configured Systems:Factory-assembled packages with standardized component bundles for rapid deployment.
New Installation holds current capacity. Retrofit is expanding most quickly on renovation wave momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered thermostatic valve assemblies to hospitality renovation projects across Spain and Portugal. Cross-border trade flows concentrate through distributor networks serving premium bathroom specification channels.
Germany
Baden-Württemberg and North Rhine-Westphalia house concentrated thermostatic engineering capacity serving pan-European distribution. KBA-aligned German institutes enforce plumbing certification standards that shape product development cycles. Stuttgart-based manufacturing clusters specialize in concealed wall-mounted systems for residential new-build specifications.
United Kingdom
Bathroom renovation cycles in aging housing stock are expanding retrofit installation volumes. Installer-trained plumbing merchants control specification through exclusive distribution agreements and certified training programs. London and Southeast England concentrate hospitality retrofit demand from hotel operators centralizing facility management.
France
Residential new-build permits in Île-de-France and Auvergne-Rhône-Alpes specify concealed digital systems with dedicated electrical supply. CSTB certification requirements create compliance barriers favoring established suppliers. Paris-based hospitality operators are piloting app-controlled centralized monitoring across multi-property portfolios.
Spain
Luxury suite renovations in Madrid and Barcelona drive ceiling-mounted rain shower specifications for architectural minimalism. Portuguese and Spanish hospitality operators are standardizing on Wi-Fi-connected systems for fleet-wide temperature compliance. Andalusia and Valencia present underdeveloped retrofit penetration in aging residential stock.
Italy
Northern Italian manufacturing districts supply thermostatic components to German and French assemblers. National transpositions of the EU Ecodesign Directive mandate maximum flow rates that compress nozzle geometry redesign cycles. Lombardy-based distributors are expanding into Eastern European markets with pre-certified valve architectures.
Europe Digital Showers Market Competitive Landscape
Player mix skews toward precision-engineering specialists with captive thermostatic valve production and trade-trained distribution networks. Market structure concentrates around German and UK-based suppliers with established certification infrastructure. Two strategic archetypes dominate: vertically integrated valve manufacturers controlling premium specification channels, and modular component suppliers enabling third-party firmware integration. Competitive moves center on installer certification program expansion and hospitality fleet management partnership formation.
Within the precision-engineering tier, Grohe AG and Hansgrohe SE exemplify German manufacturing-based competitive positioning, while Aqualisa Products Limited anchors UK market access through trade-trained channel relationships. These three entities represent distinct geographic anchoring strategies—Baden-Württemberg engineering concentration, Black Forest thermostatic specialization, and British installer network control—each occupying positions that compliance complexity and certification timelines reinforce.
| Leading Market Players |
|---|
| Toto Ltd. |
| Aqualisa Products Limited |
| Kohler Co. |
| Moen Incorporated |
| Dornbracht Deutschland GmbH & Co. KG |
| Grohe AG |
| Lixil Corporation |
| Roca Sanitario, SA |
| Hansgrohe SE |
| Others |
Value Network & Pricing Analysis
Lead-free brass alloy substitution for traditional copper-zinc formulations simultaneously concentrates thermostatic valve sourcing in Baden-Württemberg foundries and compresses margin structures for mid-tier assemblers unable to absorb REACH compliance premiums. This materials transition rewards German manufacturers with captive metallurgy capabilities while forcing price repositioning across import-dependent suppliers.
Pricing Analysis
Next-generation app-controlled systems command 40-60% premiums over Bluetooth-enabled current-generation units, while prior-generation manual thermostatic valves face accelerating price erosion in retrofit channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and installer training depth. Pricing pressure stems from semiconductor input volatility and copper alloy cost swings. Residential renovation buyers exhibit highest price sensitivity; hospitality procurement prioritizes fleet-management integration over unit economics.
Supply Chain Analysis
Strait of Malacca transit risk for semiconductor shipments from Taiwan and South Korea to German assembly plants concentrates supply vulnerability in premium digital controller sourcing. Thermostatic valve production clusters in Germany, Italy, and Czech Republic. Raw material dependencies span lead-free brass billets, ceramic disc cartridges, and microprocessor units. Single-source vulnerability sits with Taiwanese foundry capacity for precision sensor components. Distribution runs through installer-trained plumbing merchants and SHK trade counters controlling specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European bathroom renovation cycles are entering a recovery phase as EU Green Deal building efficiency mandates accelerate fixture replacement timelines across residential and hospitality sectors.
For Market Incumbents: Secure certification infrastructure investments ahead of pending Drinking Water Directive revisions that will impose new material purity standards on valve architectures. Deepen backward integration into lead-free brass metallurgy to defend margin position against REACH-driven input cost volatility. Expand installer training program coverage in United Kingdom plumbing merchant channels to maintain specification lock-in against modular component suppliers.
For New Entrants and Emerging Players: Anchor in Eastern European retrofit penetration opportunities across Poland, Czech Republic, and Romania where aging residential stock lacks digital shower specification. Target hospitality facility management partnerships in Spain and Portugal seeking centralized water monitoring capabilities. Pursue white-label modular valve architectures that enable third-party firmware integration without proprietary thermostatic engineering investments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with UK-based trade-trained distribution specialists holding exclusive plumbing merchant relationships. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor pending EU Ecodesign Directive flow-rate threshold revisions as the critical signal for product development cycle compression and consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Installer Certification Program Expansion | United Kingdom plumbing merchants and German SHK counters control specification through exclusive training relationships. |
| Hospitality Fleet Management Partnership | Spanish and Portuguese hotel operators centralize water temperature compliance across multi-property portfolios. |
| Lead-Free Alloy Metallurgy Investment | REACH SVHC candidate list revisions threaten traditional brass formulations and reward pre-compliant suppliers. |
| Eastern European Distribution Buildout | Poland, Czech Republic, and Romania present underdeveloped digital shower penetration in aging residential stock. |
| Modular Valve Architecture Development | Component standardization decomposes proprietary lock-in and enables third-party firmware integration. |
Research Methodology
A spread of perspectives from thermostatic valve engineering directors, plumbing merchant category managers, hospitality facilities executives, and KBA-aligned certification specialists converged on the working assumptions underlying demand segmentation. Primary fieldwork combined structured interviews with secondary validation against CE marking databases, CSTB approval registries, EU Ecodesign Directive implementation documents, and construction permit filings across Germany, France, and the United Kingdom. Bottom-up installation volume estimates triangulated against top-down bathroom renovation spending projections.
Segmentation dimensions modeled span product mounting configuration, connectivity protocol, end-user vertical, and installation phase across the projection horizon. Analytical framework derived CAGRs through regression against construction permit volumes, hospitality pipeline data, and regulatory implementation timelines. Industry-specific forecast inputs incorporated EU Green Deal renovation wave targets and national building efficiency code adoption curves.
Material uncertainties — copper alloy price volatility, semiconductor availability, and REACH substance restriction revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and construction sector labor availability. Practitioners should keep alternative scenarios live as EU Drinking Water Directive alignment negotiations and national transposition schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Bathroom Market
Household Items
US Air Fresheners Market
Household Items
Global Rimless Toilets Market
Household Items
Shower Heads Market
Household Items
US Hand Dryers Market
Household Items
Dryer Sheets Market
Household Items
Nebulizing Diffuser Market
Household Items
Mexico Cookware Market
Household Items
Crash Mat Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Global Ceramic Tableware Market
Household Items
Air Freshener Market
Household Items
Aquarium Hydrometers Market
Household Items
Portable Steamers Market
Household Items
Beach Towel Market
Household Items
Pet Stain Remover and Odour Control Market