
 Cast Iron Cookware Market | 2026-2036
Cast Iron Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Iron Cookware Market Intelligence
The consumer movement toward durable, 'buy-it-for-life' goods as a counter to disposable culture is consolidating demand for long-lasting cookware materials. Lodge Manufacturing Company leverages its long-standing American heritage and pre-seasoned product lines to capture a significant portion of this market. Le Creuset differentiates with its premium enameled cast iron, commanding higher price points through strong brand equity and aesthetic appeal. Staub competes in the premium segment, specializing in cocottes and Dutch ovens with unique interior textures.
Cast iron cookware refers to pots, pans, and vessels made from an iron-carbon alloy, typically produced through a sand casting process. Its high thermal mass provides superior heat retention and even distribution, making it ideal for searing, braising, and slow-cooking applications. Within product types, skillets and Dutch ovens represent the largest share, serving as foundational items for many consumers. Enameled cooking surfaces are gaining share over traditional pre-seasoned options, particularly in the household end-user segment, due to easier maintenance.
Market access is governed by food contact material safety standards, including regulations set by the US FDA and the EU's REACH framework. In China, compliance with GB standards for metal articles intended for food contact is mandatory for all manufacturers. Future competitive advantage will hinge on developing lighter-weight alloys and more durable enamel coatings without compromising thermal performance.
Market Dynamics
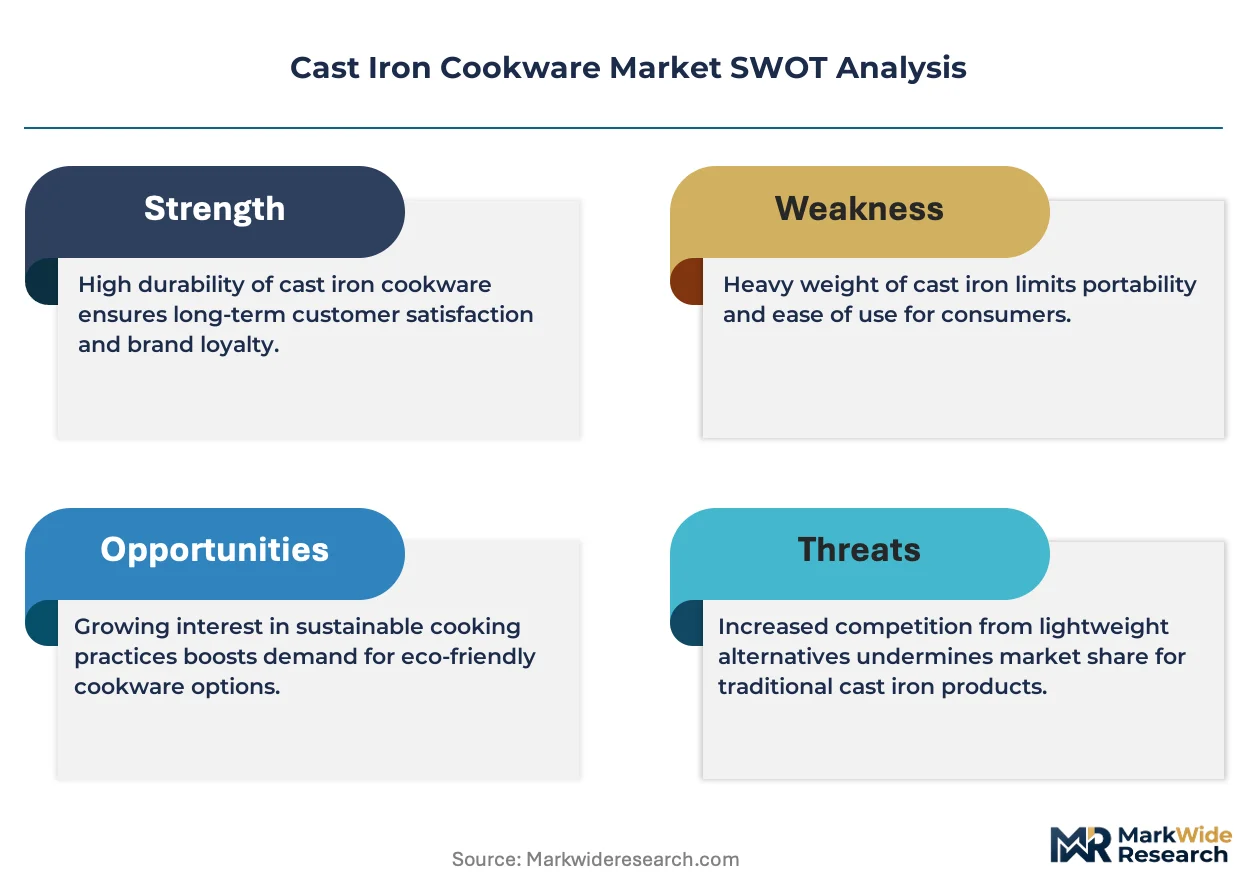
The market's central dynamic involves a tension between the legacy of durable, heavy-duty cookware valued by professional kitchens and the modern consumer demand for lighter, easier-to-maintain products, pushing innovation in materials science and surface treatments.
Growth Catalysts
- Food Service Demand:The commercial food sector, including restaurants and catering services, prioritizes the superior heat retention and durability of cast iron for high-volume cooking, ensuring consistent demand for skillets and Dutch ovens.
- EU Food Contact Regulations:Stricter rules like Regulation (EC) No 1935/2004 on materials contacting food favor inert cookware, positioning cast iron as a safe alternative to plastics or coated pans with potential chemical leaching concerns.
- Consumer Anti-Disposable Culture:A growing consumer movement favoring long-lasting, repairable goods over throwaway items creates a strong pull for cast iron, often marketed as a 'buy-it-for-life' or heirloom product.
Market Restraints
- Product Weight:The inherent density and weight of cast iron can be a significant deterrent for some consumers, especially those with physical limitations or a preference for lightweight, easy-to-handle cookware like aluminum.
- Maintenance Requirements:Traditional, un-enameled cast iron requires specific seasoning and cleaning protocols to prevent rust and maintain its non-stick surface, a process that can be perceived as inconvenient compared to modern alternatives.
- Substitution from Non-Stick Pans:The prevalence of low-cost, convenient non-stick aluminum and ceramic-coated pans presents a constant substitution threat, particularly for entry-level consumers focused on ease of use over longevity.
Strategic Opportunities
- Lightweight Alloy Development:Formulating new iron-based alloys that reduce weight without compromising thermal performance represents a significant opportunity to broaden market appeal to consumers deterred by the material's traditional heft.
- Advanced Enamel Coatings:There is market space for developing more durable, chip-resistant, and stain-proof enamel coatings that extend product lifespan and enhance aesthetic appeal, justifying premium price points.
- Emerging Market Penetration:Targeting the growing middle class in markets across Asia-Pacific and Latin America, where home cooking trends are evolving, offers a substantial avenue for geographic expansion.
Industry Challenges
- Energy-Intensive Production:The sand casting manufacturing process is highly energy-intensive, exposing producers to volatile energy costs and increasing pressure to invest in more efficient furnace and molding technologies.
- Skilled Labor Dependency:Achieving consistent quality in casting and finishing requires a skilled workforce, creating potential production bottlenecks and challenges in regions where such specialized manufacturing talent is scarce.
- Global Regulatory Compliance:Manufacturers must navigate and comply with a patchwork of food contact material standards, including US FDA guidelines, EU's REACH, and China's GB standards, adding complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Iron Cookware Market |
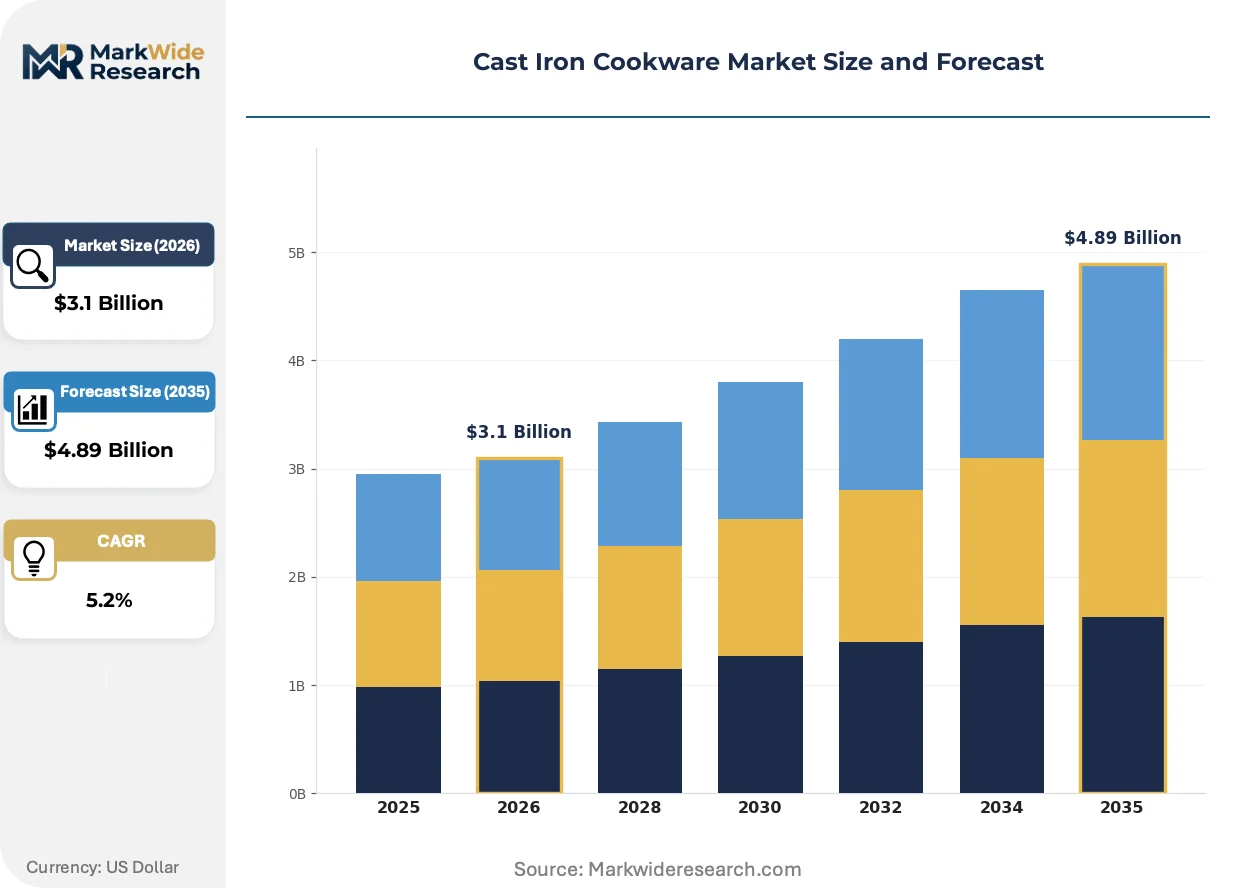
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skillets, Dutch Ovens, Griddles, Grill Pans, Cauldrons Cooking Surface: Pre-Seasoned, Enameled, Polished, Textured, Polished Matte End User: Households, Food Service Providers, Culinary Schools, Outdoor Enthusiasts Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Wholesale Suppliers |
| Companies Covered | Meyer Corporation, Cuisinart, Lodge Manufacturing Company, Tramontina, Williams-Sonoma Inc., Le Creuset, Camp Chef, Victoria Cookware, Staub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Iron Cookware Market Strategic Shifts & Innovations
Innovations in material science are transforming cast iron from a purely utilitarian tool into a high-performance, aesthetically versatile product. This evolution reflects a market balancing heritage appeal with modern demands for convenience and design.
Advanced hybrid enamel surfaces combine the non-stick properties of modern coatings with the durability of traditional enamel. Household consumers are the primary adopters, seeking easier maintenance without sacrificing the searing capability of iron. This development is decentralizing the focus from pure heat retention to a more holistic user experience, attracting buyers previously loyal to non-stick aluminum pans.
Europe's enhanced enforcement of Regulation (EC) No 1935/2004 on food contact materials is increasing scrutiny on heavy metals like cadmium and lead in enamel glazes. This forces manufacturers to invest in cleaner production processes and rigorous third-party testing. The enameled cookware segment is most affected, with compliance becoming a key differentiator for premium brands.
A consumer shift toward "kitchen-to-table" dining, amplified by social media, is elevating the importance of cookware aesthetics. This disrupts traditional retail channels that prioritize function over form, creating an opening for direct-to-consumer brands that excel in visual marketing and storytelling. This behavioral change is most pronounced among millennial and Gen Z home cooks in North America and Western Europe.
Cast Iron Cookware Market Segmentation
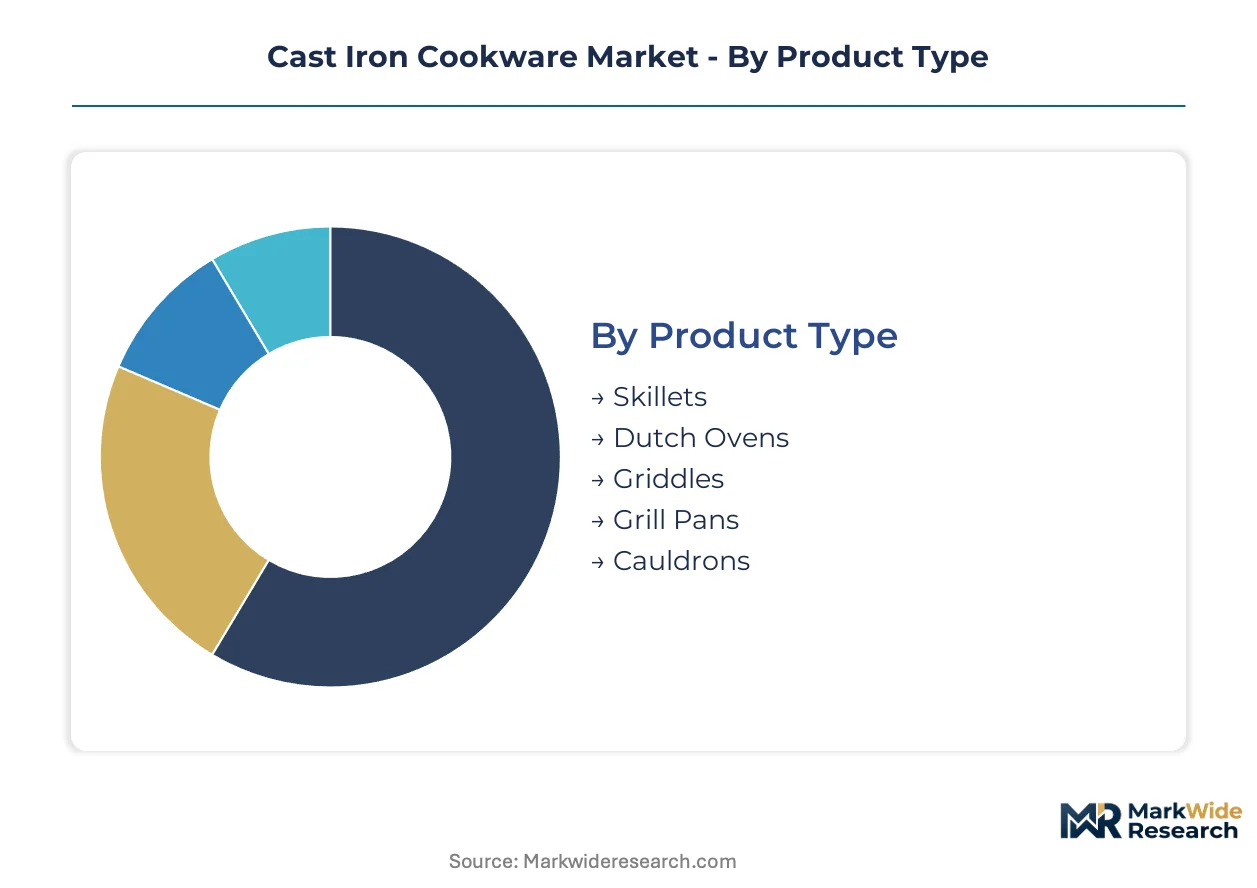
Analyzing the cast iron cookware market through detailed segmentation provides critical insights into consumer behavior, product preferences, and competitive landscapes. This granular view helps manufacturers tailor product development and marketing strategies to specific end-user needs and distribution channels. Understanding segment dynamics also reveals opportunities for innovation and market expansion across different product types and cooking surfaces.
Product Type:
The product type segmentation highlights the balance between high-volume, utilitarian items and more specialized, premium offerings.
- Skillets:These flat-bottomed, shallow pans are foundational cast iron products, valued for their searing capabilities and even heat distribution across home kitchens and professional settings. Demand for skillets is consistently high among both new and experienced cooks in Germany who appreciate their versatility.
- Dutch Ovens:Heavy, lidded pots designed for slow cooking, braising, and baking, Dutch ovens offer superior moisture retention and thermal mass for complex culinary tasks. Their versatility and aesthetic appeal drive significant demand among household consumers in North America seeking multi-purpose kitchen tools.
- Griddles:Flat, often round or rectangular pans, griddles are used for cooking pancakes, bacon, and grilled sandwiches.
- Grill Pans:Featuring raised ridges, grill pans mimic outdoor grilling indoors, ideal for searing meats and vegetables.
- Cauldrons:Large, deep pots, cauldrons are less common in modern kitchens but retain niche appeal for traditional cooking methods.
Today's leader: Skillets. Tomorrow's challenger: Dutch Ovens.
Cooking Surface:
The cooking surface segmentation reflects evolving consumer preferences for maintenance, aesthetics, and performance characteristics.
- Enameled:Featuring a vitreous enamel coating, these surfaces offer easier cleaning, rust resistance, and a wide range of colors, appealing to modern consumers prioritizing convenience and design. Demand for enameled cast iron is particularly strong among household users in Western Europe due to their low maintenance.
- Pre-Seasoned:These traditional surfaces undergo a factory-applied oil treatment, providing immediate non-stick properties and rust protection, improving user experience from the first use. Food service providers in the US favor pre-seasoned options for their durability and consistent performance in high-volume environments.
- Polished:Smooth, highly finished cast iron surfaces offer a refined aesthetic and can be seasoned by the user over time.
- Textured:Surfaces with a deliberate pattern or texture enhance food release and can contribute to unique cooking results.
- Polished Matte:Combining a polished finish with a subdued, non-reflective appearance, offering a contemporary visual appeal.
Enameled surfaces are expanding most quickly, driven by household demand for convenience.
End User:
This segment delineates demand based on the primary user group, highlighting distinct purchasing drivers and product requirements.
- Households:Individual consumers and families represent the largest segment, driven by home cooking trends, the desire for durable goods, and aesthetic considerations for kitchen-to-table presentation. The anti-disposable culture movement significantly influences household purchasing decisions across North America.
- Food Service Providers:Commercial kitchens, restaurants, and catering services prioritize cast iron for its superior heat retention, durability, and ability to withstand rigorous daily use. Professional chefs in France consistently demand high-performance cast iron for searing and braising tasks.
- Culinary Schools:Educational institutions utilize cast iron to teach fundamental cooking techniques and equipment handling.
- Outdoor Enthusiasts:Campers and outdoor cooks value cast iron for its robustness and versatility over open flames.
The household segment remains the largest volume contributor, while food service providers offer consistent, high-value demand.
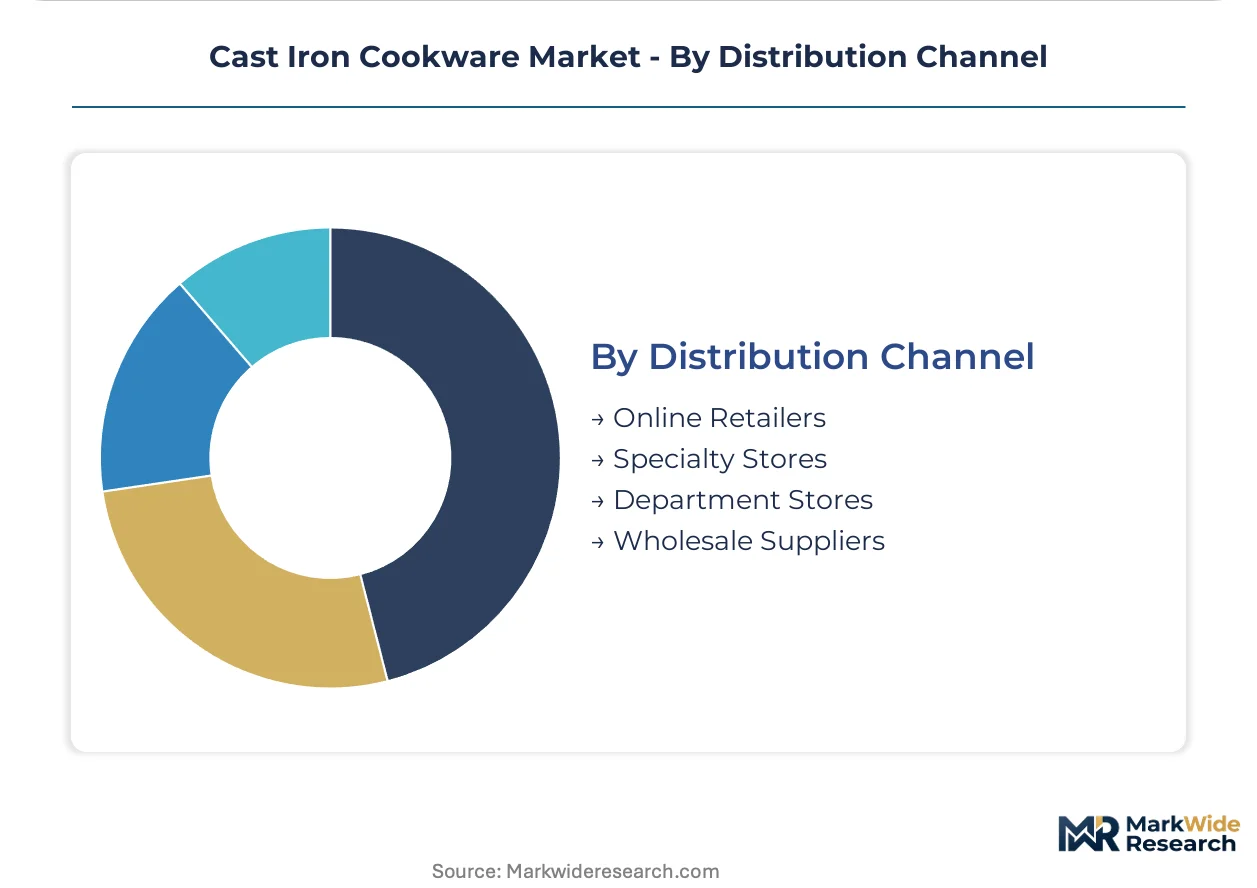
Distribution Channel:
The distribution channel segment illustrates how cast iron cookware reaches its diverse customer base, from mass markets to specialized buyers.
- Online Retailers:E-commerce platforms offer extensive product selections, competitive pricing, and convenience, making them a primary channel for reaching a broad consumer base globally. Online retailers are particularly effective for reaching millennial and Gen Z consumers in North America.
- Specialty Stores:These outlets provide curated selections, expert advice, and a hands-on shopping experience, catering to discerning customers seeking premium brands and specialized products. Specialty kitchen stores in Germany maintain strong sales for high-end cast iron brands like Le Creuset.
- Department Stores:Larger retail establishments offer a range of cookware brands, often including premium cast iron lines, appealing to a diverse customer demographic.
- Wholesale Suppliers:These channels serve commercial clients, including restaurants, hotels, and institutional buyers, providing bulk purchasing options.
Online channels are expanding their market penetration, while specialty stores sustain premium brand visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cast iron cookware market traces its origins to early metallurgy, with significant scaling of production and adoption occurring across Europe and North America. Today, diverse regional preferences and regulatory frameworks shape demand for these durable kitchen tools. Each distinct geography contributes to the product's evolving performance and aesthetic.
Germany
Germany exhibits strong demand for high-performance cast iron cookware, driven by both professional chefs and discerning home cooks. EU regulations, such as Regulation (EC) No 1935/2004, mandate strict food contact material safety standards, favoring inert options like cast iron. Specialty kitchen stores in cities like Munich and Berlin maintain robust sales for premium cast iron brands, reflecting a cultural appreciation for quality.
United States
United States households drive substantial demand for cast iron cookware, influenced by the anti-disposable culture and a preference for heirloom products. Manufacturers comply with US FDA guidelines for food contact materials, ensuring product safety. The manufacturing heartland in states like Tennessee, home to Lodge Manufacturing, continues to innovate in pre-seasoned product lines, serving a broad consumer base.
France
French professional chefs consistently demand high-performance cast iron for searing and braising tasks, valuing its superior heat retention. Strict EU food safety standards, including REACH, govern material composition and production processes for cookware sold in France. Culinary schools in Paris and Lyon integrate cast iron into their curricula, reinforcing its traditional culinary importance.
China
China presents a growing market for cast iron cookware, propelled by an expanding middle class and evolving home cooking trends. Compliance with GB standards for metal articles intended for food contact is mandatory for all manufacturers operating within China. Industrial clusters in provinces like Zhejiang and Guangdong are developing new production capabilities to meet both domestic and export demand.
India
India's market for cast iron cookware is expanding as urban consumers increasingly adopt modern kitchen appliances and durable goods. The Bureau of Indian Standards (BIS) sets quality benchmarks for metal products, including cookware, ensuring consumer safety. Major metropolitan areas like Mumbai and Bangalore are witnessing a surge in specialty kitchenware retailers, catering to this rising interest.
Cast Iron Cookware Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the cast iron cookware market, creating a varied competitive structure. The market exhibits a moderate level of fragmentation, with several established players alongside numerous niche manufacturers. Strategic archetypes include heritage brands focusing on traditional craftsmanship, premium brands emphasizing design and innovation, and value-oriented producers. Companies pursue competitive advantage through advanced material development and strategic geographic expansion.
Lodge Manufacturing Company, a US-based entity, represents the heritage and durability archetype, focusing on traditional pre-seasoned cast iron. Le Creuset, a French company, exemplifies the premium segment, commanding higher price points through strong brand equity and enameled aesthetics. Staub, another French brand, occupies a specialized position within the premium segment, known for its unique cocottes and Dutch ovens.
| Leading Market Players |
|---|
| Meyer Corporation |
| Cuisinart |
| Lodge Manufacturing Company |
| Tramontina |
| Williams-Sonoma Inc. |
| Le Creuset |
| Camp Chef |
| Victoria Cookware |
| Staub |
| Others |
Cost & Logistics Intelligence
Food service providers' consistent demand for durable cookware directly influences the pricing structure for high-volume cast iron products. This concentration of commercial buyers often leads to contract-based pricing models for bulk orders.
Pricing Analysis
Premium-mid-economy pricing differentiation characterizes the cast iron cookware market. Brand equity and advanced enamel quality serve as primary price differentiation drivers. Pricing pressure stems from the energy-intensive production process, exposing manufacturers to volatile energy costs. The entry-level household segment exhibits the highest price sensitivity, often opting for more affordable, pre-seasoned options.
Supply Chain Analysis
Online retailers and specialty stores form the primary distribution channels for cast iron cookware, reaching diverse customer bases. Supply concentration draws from manufacturing hubs in China, the United States, and France. Raw material dependencies include iron ore, carbon, and specialized enamel glazes. Global regulatory compliance across various food contact material standards represents a structural supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a geographic-arbitrage play, leveraging lower production costs in certain regions against premium pricing opportunities driven by stringent EU regulations and brand heritage in Western markets.
For Market Incumbents: Cement market leadership through continuous investment in lightweight alloy development and chip-resistant enamel coatings. This counteracts the threat from convenient non-stick alternatives and addresses consumer preferences for easier maintenance. Vertical integration into specialized material sourcing provides a lever against volatile input costs.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce platforms offer a viable entry point for brands emphasizing aesthetic appeal and unique product features. Target millennial and Gen Z home cooks in North America and Western Europe who prioritize design and kitchen-to-table presentation. A strong go-to-market angle focuses on visual storytelling and community building around sustainable home cooking.
For Investors and Strategic Acquirers: Consumer goods companies seeking durable brands are the most active acquirers in this space, valuing established heritage and premium positioning. The long-term viability of cast iron is secure, supported by anti-disposable culture trends and professional demand. A signal to watch is the commercialization of significantly lighter, high-performance cast iron alloys.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Enamel R&D | Developing more durable enamel coatings extends product lifespan and justifies premium pricing for household consumers. |
| Lightweight Alloy Innovation | Formulating new iron-based alloys broadens market appeal by addressing traditional product weight concerns. |
| Direct-to-Consumer Expansion | Building strong online channels allows brands to capture millennial and Gen Z home cooks directly in North America. |
| Emerging Market Localization | Tailoring product lines to specific cooking styles and preferences in Asia-Pacific expands geographic reach. |
| Sustainable Production Investment | Adopting energy-efficient casting technologies mitigates exposure to volatile energy costs for manufacturers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the cast iron cookware market. Primary insights stemmed from discussions with professional chefs, kitchenware retailers, material scientists, and manufacturing engineers. Secondary validation drew from EU Regulation (EC) No 1935/2004, US FDA guidelines, China's GB standards, and company annual reports, ensuring robust bottom-up and top-down triangulation.
The forecast framework anchored the projection horizon to historical performance across the analysis window, integrating future demand drivers and technological advancements. Segmentation dimensions modeled included product type, cooking surface, end user, distribution channel, and regional preferences. Compound annual growth rates derived from a detailed analysis of market dynamics, with raw material price forecasts and energy cost projections serving as key industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for non-stick material development would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer preference evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Pool Skimmer Market
Household Items
Oman Gas Hobs Market
Household Items
Bladeless Neck Fan Market
Household Items
Window Rain Guards Market
Household Items
Collapsible Water Bottle Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Moving Supplies Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Gas Hobs Market
Household Items
US Hand Dryers Market
Household Items
Neck Pillows Market
Household Items
Snow Blower Market
Household Items
India Cookware Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Brazil Cookware Market
Household Items
North America Robotic Pool Cleaner Market