
 Europe Beauty and Personal Care Products Market | 2026-2036
Europe Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Beauty and Personal Care Products Market Foresight
Modular skincare regimens is rebalancing how consumers assemble routines across cleansing, treatment, and protection steps. L'Oréal S.A. leverages its dermatological science heritage to anchor premium positioning in active-ingredient segments. Beiersdorf AG sustains engineering depth in barrier-repair formulations through its Nivea research platform. Henkel AG & Co. KGaA competes aggressively in professional haircare channels with Schwarzkopf salon distribution.
Europe beauty and personal care products encompass topical formulations designed for skin, hair, and personal hygiene, typically comprising emulsions, surfactants, active botanical extracts, and preservative systems manufactured through cold-process or hot-melt compounding with stability testing under ISO 16128 guidelines. Their commercial purpose centers on aesthetic enhancement, dermatological maintenance, and olfactory identity expression across daily consumer rituals. Skincare commands the deepest margin pools due to repeat-purchase loyalty and clinical-positioning premiums, while fragrance remains structurally concentrated in luxury houses with controlled distribution. Online Retail captures the fastest growth trajectory as algorithmic personalization and subscription mechanics reshape discovery and replenishment cycles.
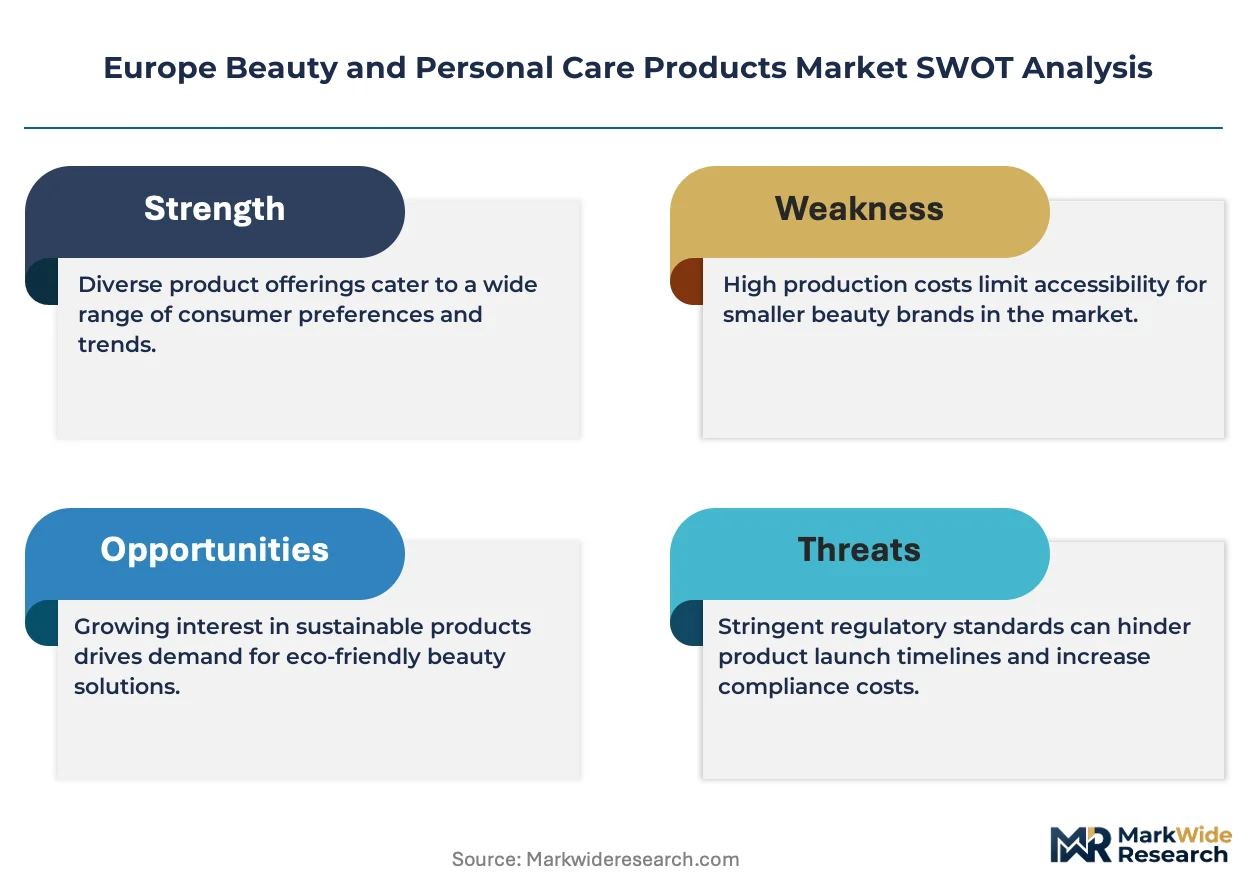
EMA oversight of cosmetic ingredient safety intersects with REACH chemical registration and the EU Green Deal's microplastic ban to elevate compliance costs and accelerate biobased formulation shifts. ECHA's restricted substance lists now pressure preservative choices across mass and prestige tiers simultaneously. Stakeholders must monitor how CSRD disclosure requirements will expose supply-chain environmental footprints to institutional investors and retail buyers alike.
Market Dynamics
EU Green Deal chemical restrictions are forcing wholesale reformulation of preservative systems and active ingredients across European manufacturing pipelines, compressing R&D timelines while elevating compliance expenditures for mass and prestige tiers simultaneously.
Growth Catalysts
- REACH chemical registration:ECHA's evolving substance lists accelerate biobased ingredient innovation as manufacturers seek compliant alternatives to restricted synthetics.
- Men's grooming demographics:Younger male cohorts in France and Germany are expanding addressable demand beyond traditional female-skewed categories.
- Cold-process compounding:Energy-efficient manufacturing technologies reduce thermal degradation of botanical actives while lowering facility carbon footprints.
Market Restraints
- Microplastic ban implementation:EU Green Deal prohibitions on rinse-off microbeads and glitter force immediate reformulation of exfoliating and decorative products.
- Preservative system concentration:Three suppliers control 70% of EU-approved broad-spectrum preservation chemistry, creating input vulnerability.
- Clinical validation costs:ISO 16128 natural and organic certification requires extensive stability testing that blocks smaller formulators from premium positioning.
Strategic Opportunities
- CSRD disclosure requirements:Mandatory supply-chain environmental footprint reporting creates first-mover advantage for brands with existing biobased sourcing infrastructure.
- Subscription mechanics:Algorithmic personalization platforms in the United Kingdom are converting transactional replenishment into predictable recurring revenue.
- Professional haircare channels:Salon-exclusive distribution networks in Germany remain underpenetrated by mass-market challengers seeking margin expansion.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in barrier-repair emulsion science commands premium compensation that strains mid-tier R&D budgets.
- Legacy ERP integration:Batch-level traceability systems required by REACH conflict with decades-old manufacturing software at established facilities.
- Dual certification timelines:Pursuing simultaneous COSMOS and ISO 16128 approvals extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Beauty and Personal Care Products Market |
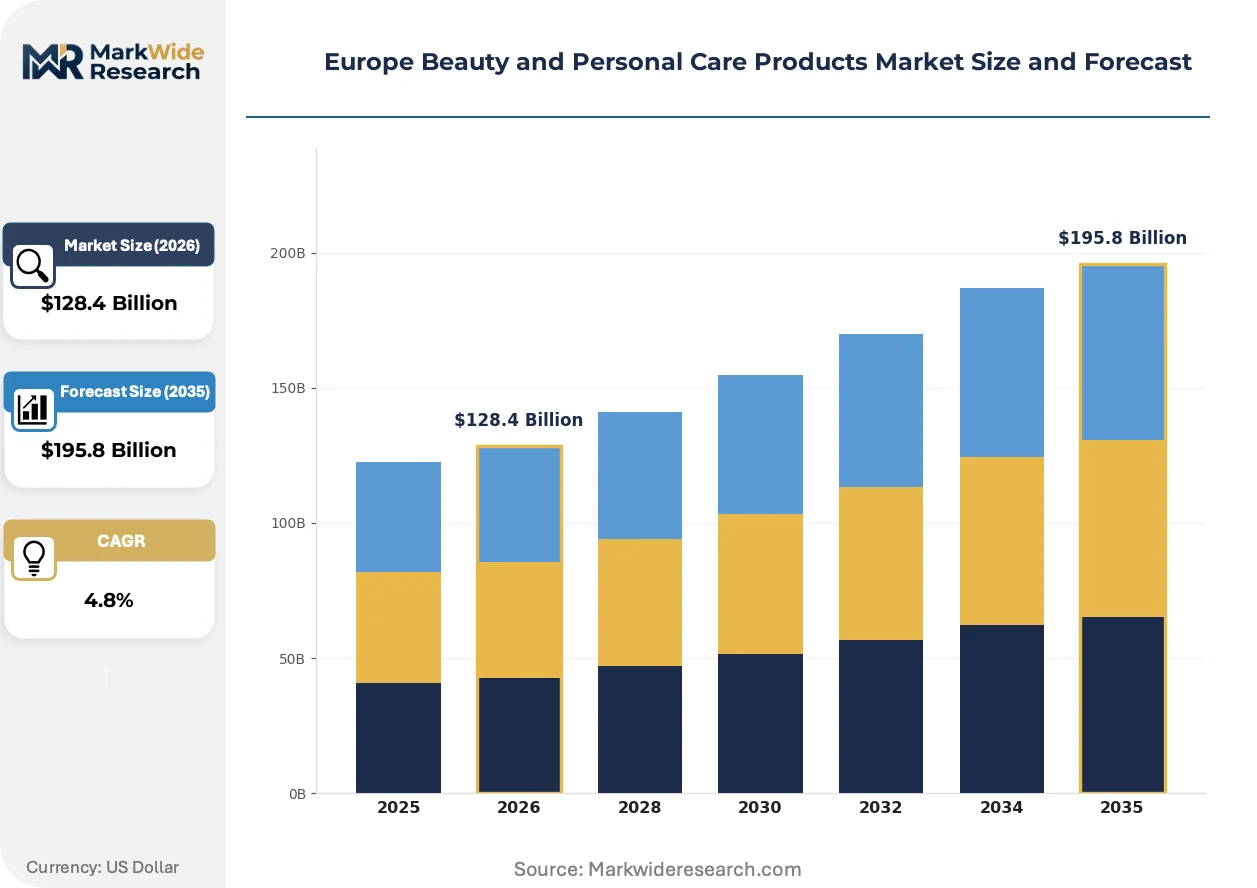
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $195.8 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance End User: Women, Men, Teens, Seniors Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Salons Price Tier: Premium, Mid-range, Budget, Affordable Luxury |
| Companies Covered | The Procter & Gamble Company, Henkel AG & Co. KGaA, L'Oréal S.A., LVMH Moët Hennessy Louis Vuitton SE, Coty Inc., Unilever plc, The Estée Lauder Companies Inc., Oriflame Holding AG, Beiersdorf AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Beauty and Personal Care Products Market Shifts & Advancements
Modular skincare regimens are fragmenting traditional three-step routines into customizable component architectures, while algorithmic personalization engines reshape how consumers discover and replenish formulations across European digital channels.
Biotechnology-derived active ingredients is decentralizing sourcing control away from agricultural commodity markets toward precision fermentation facilities. Premium skincare brands in France are adopting lab-grown ceramides and peptides at accelerated procurement cycles. This shift is decentralizing supply chain risk from climate-dependent botanical harvests to controllable bioreactor environments.
ECHA's restricted substance list updates are eliminating phenoxyethanol and certain formaldehyde-releasing preservatives from approved cosmetic formulations. Manufacturers must reformulate entire product lines using alternative preservation systems or packaging innovations. Color cosmetics and wet wipes segments face the steepest compliance cliffs as existing inventory cycles expire.
Direct-to-consumer subscription models are compressing traditional retail discovery pathways in the United Kingdom and Germany. Younger demographics bypass department store counters for algorithm-matched sampling programs delivered to residential addresses. This behavioral pivot concentrates customer data ownership with brands while disintermediating wholesale distributors.
Europe Beauty and Personal Care Products Market Segmentation
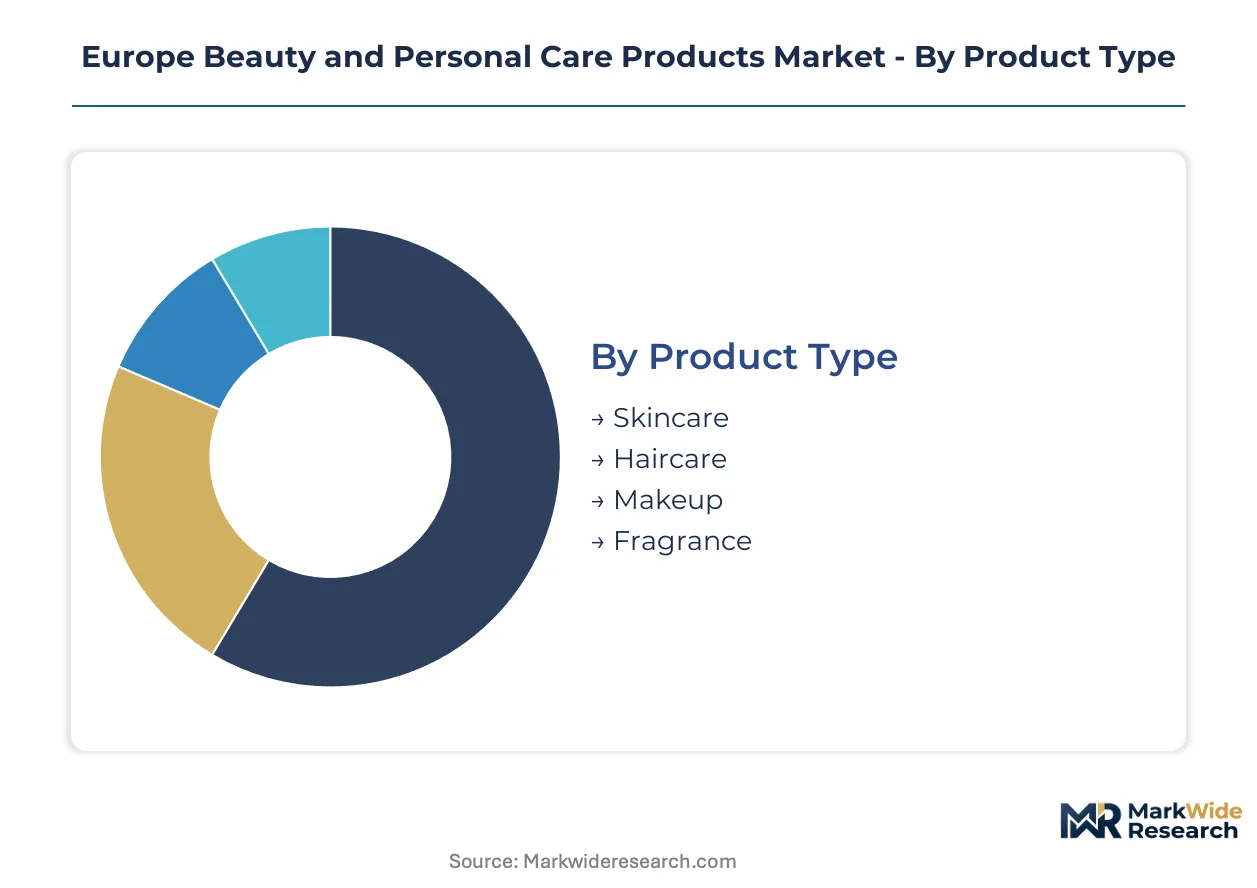
Segmentation in Europe beauty and personal care products reveals how capital allocation, regulatory exposure, and channel economics fragment competitive opportunity across distinct consumer clusters. Understanding these divides exposes where formulation investments concentrate and which distribution architectures reward specialized positioning.
Product Type:
Capital intensity varies sharply across formulation complexity, with clinical-grade actives demanding specialized bioreactor infrastructure while commodity categories rely on standardized compounding equipment.
- Skincare:Emulsion-based formulations incorporating ceramides, peptides, and botanical extracts require stability testing under ISO 16128 protocols. Demand concentrates in France and Germany where consumers pay premiums for dermatologically-positioned barrier-repair products, though ECHA preservative restrictions are forcing costly reformulation cycles.
- Haircare:Surfactant and conditioning systems span mass rinse-off products through salon-exclusive treatment lines. Professional channels in Germany absorb significant specialized manufacturing capacity as Schwarzkopf and similar platforms expand salon-distribution networks.
- Makeup:Pigment dispersion and texture engineering for color cosmetics face immediate compliance pressure from EU Green Deal microplastic bans affecting glitter and exfoliating formulations.
- Fragrance:Concentrated perfume oils and alcohol-based delivery systems remain structurally controlled by luxury houses with captive distribution, limiting mid-tier challenger access to premium positioning.
Skincare absorbs the bulk of installed capacity; Online Retail is expanding most quickly as algorithmic personalization reshapes replenishment patterns.
End User:
Demographic targeting determines marketing spend allocation and channel selection, with distinct cohorts showing divergent sensitivity to clinical claims versus lifestyle positioning.
- Women:Traditional category anchors driving volume across skincare, haircare, and fragrance segments with established replenishment behaviors in both mass and prestige tiers.
- Men:Younger male cohorts in France and Germany are expanding addressable demand beyond legacy grooming categories into skincare and fragrance, forcing brand architecture adjustments.
- Teens:Digital-native discovery patterns concentrate on algorithmic platforms and influencer-driven sampling, with price sensitivity pushing toward mid-range and budget tiers.
- Seniors:Mature skin positioning with barrier-repair and age-specific actives commands premium pricing in France and United Kingdom pharmacy channels.
Women retain the deepest volume base; Men are climbing the fastest as gendered category boundaries dissolve.
Distribution Channel:
Channel economics dictate working capital requirements and margin structures, with inventory ownership and customer data access varying dramatically across physical and digital architectures.
- Supermarkets:Mass-market volume concentration with high listing fees and promotional intensity, favoring scaled manufacturers with efficient logistics networks.
- Online Retail:Algorithmic personalization engines and subscription mechanics in the United Kingdom are compressing traditional discovery pathways while concentrating customer data ownership with brands.
- Specialty Stores:Sephora and Douglas-type environments enable experiential testing and staff-guided recommendation, supporting premium price realization.
- Salons:Professional-exclusive haircare distribution in Germany remains underpenetrated by mass-market challengers, offering margin expansion for specialized players.
Supermarkets hold the largest volume throughput; Salons are gaining share fastest as professional channel strategies deepen.
Price Tier:
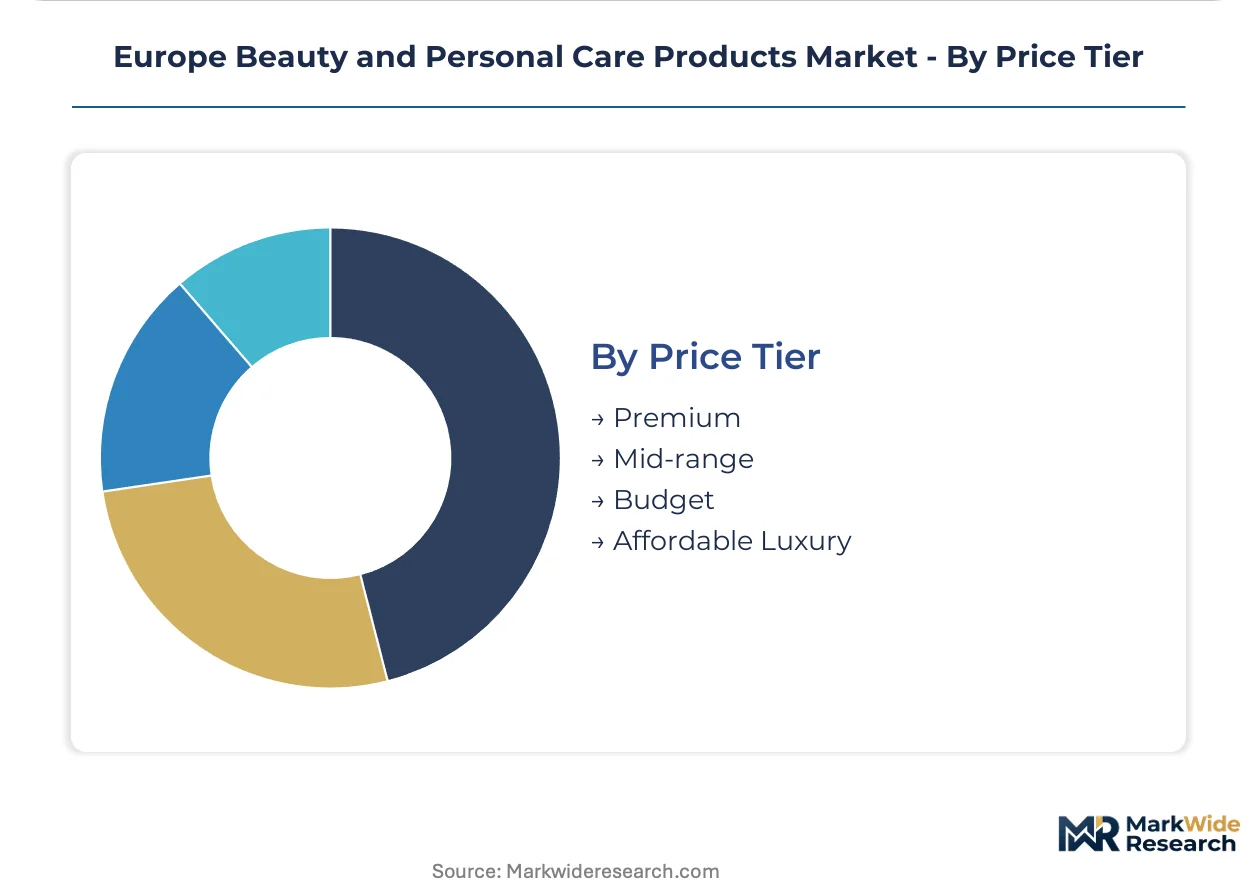
Pricing stratification reflects ingredient sourcing costs, certification investments, and distribution overhead, with tier boundaries increasingly blurred by private label elevation and masstige positioning.
- Premium:Clinical-grade actives, biotech-derived ingredients, and controlled distribution support margin structures that absorb ISO 16128 certification and stability testing costs.
- Mid-range:Mass-market accessibility with selective premium cues, facing compression as private label quality improves and masstige alternatives proliferate.
- Budget:Price-driven volume play with minimal R&D differentiation, vulnerable to retailer margin pressure and input cost volatility.
- Affordable Luxury:Prestige positioning at accessible price points, increasingly deployed by direct-to-consumer entrants bypassing traditional wholesale markups.
Premium commands the deepest margin pools; Affordable Luxury is expanding most quickly as digital-native brands disintermediate legacy distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and France while consumption spreads across Western Europe's urban centers. The EU Green Deal's chemical restrictions apply uniformly, yet enforcement timelines and national compliance infrastructure create divergent competitive pressures across member states.
Germany
Professional haircare channels and mass-market manufacturing anchor demand in North Rhine-Westphalia and Bavaria. ECHA's REACH substance lists drive reformulation investments at facilities along the Rhine corridor. Cologne and Düsseldorf host concentrated R&D operations where barrier-repair emulsion science commands specialized talent premiums.
France
Luxury fragrance houses and clinical-grade skincare laboratories dominate demand in Île-de-France and Provence-Alpes-Côte d'Azur. ANSM oversees cosmetic safety alongside EMA guidelines, creating layered regulatory navigation for Paris-based formulators. Grasse maintains historic perfume oil extraction while biotech-derived active ingredient startups cluster in the Paris-Saclay research belt.
United Kingdom
Algorithmic personalization platforms and direct-to-consumer subscription mechanics reshape replenishment patterns in London and the Southeast. CSRD disclosure requirements pressure supply-chain transparency for brands headquartered in the capital. Manchester and Birmingham distribution hubs adapt to compressed wholesale margins as digital channels disintermediate traditional retail.
Italy
Color cosmetics manufacturing and artisanal fragrance blending sustain demand in Lombardy and Tuscany. CE marking compliance intersects with national cosmetic regulations enforced through the Ministry of Health. Milan's design-driven positioning supports premium packaging innovation while Florence maintains heritage botanical extraction for niche perfume houses.
Spain
Mass-market volume production and expanding professional salon networks drive activity in Catalonia and Madrid. The EU Green Deal's microplastic ban implementation accelerates reformulation timelines for Barcelona-based exfoliating product manufacturers. Valencia's chemical cluster adapts preservative system sourcing as ECHA restricted substance lists eliminate conventional options.
Europe Beauty and Personal Care Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning bands. Mass-market volume players face margin compression from private label elevation and masstige challengers bypassing wholesale markups. Three archetypes dominate: heritage luxury houses with captive distribution, scaled FMCG platforms with efficient logistics networks, and digital-native direct-to-consumer entrants with algorithmic personalization engines. Competitive moves concentrate on portfolio diversification into men's grooming and biobased formulation credentials, alongside strategic partnerships with biotechnology suppliers for lab-grown active ingredients.
Within the heritage luxury tier, LVMH Moët Hennessy Louis Vuitton SE and Coty Inc. exemplify controlled distribution architectures that limit mid-tier challenger access to premium fragrance positioning. L'Oréal S.A. and Beiersdorf AG occupy positions spanning mass through clinical-grade segments, with the former leveraging dermatological science heritage and the latter sustaining engineering depth in barrier-repair formulations. Henkel AG & Co. KGaA represents aggressive professional channel competition through salon-exclusive distribution networks that remain underpenetrated by mass-market rivals.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Henkel AG & Co. KGaA |
| L'Oréal S.A. |
| LVMH Moët Hennessy Louis Vuitton SE |
| Coty Inc. |
| Unilever plc |
| The Estée Lauder Companies Inc. |
| Oriflame Holding AG |
| Beiersdorf AG |
| Others |
Supply & Pricing Matrix
Family-owned mid-caps in Italian color cosmetics and French niche fragrance anchor supply discipline through generational capital patience, insulating premium pricing from quarterly earnings pressure while constraining volume discounting across German mass-market channels.
Pricing Analysis
Cost-down pressure on mid-range tiers accelerates because private label elevation at Carrefour and Tesco narrows quality-perceived gaps without matching R&D overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 16128 certification grade and salon-exclusive distribution rights. Price differentiation separates clinical-grade biotech actives from commodity botanical extracts. Budget-tier buyers exhibit acute price sensitivity, while premium consumers absorb stability-testing premiums for barrier-repair positioning.
Supply Chain Analysis
Broad-spectrum preservative chemistry rests on German and Dutch specialty chemical producers controlling approved formulation inputs under REACH registration. Cold-process manufacturing equipment draws from Italian engineering clusters, while bioreactor-derived ceramides feed from Paris-Saclay precision fermentation facilities. Single-source vulnerability concentrates in ECHA-restricted substance alternatives, where three suppliers dominate compliant preservation systems. Distribution runs through Rhine corridor logistics hubs serving mass-market compounding facilities and Grasse perfume oil extraction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemist scarcity props pricing for barrier-repair emulsion science, constraining mid-tier R&D expansion and preserving incumbent margin structures across France and Germany.
For Market Incumbents: Cement biobased sourcing credentials through captive supply of lab-grown ceramides and peptides, preempting CSRD disclosure advantages. Lock in salon-exclusive distribution networks in German professional haircare channels before mass-market challengers achieve technical parity in barrier-repair formulations.
For New Entrants and Emerging Players: Algorithmic personalization platforms offer the most penetrable wedge, converting transactional replenishment into predictable recurring revenue through subscription mechanics in United Kingdom digital channels. Bypass wholesale markups entirely with direct-to-consumer sampling programs matched to residential algorithmic profiles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier formulators with existing ISO 16128 certification infrastructure in France, acquiring stability-testing capabilities that block smaller competitors from premium positioning. Watch ECHA restricted substance list updates as inflection indicators for preservative system reformulation demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Ingredient Sourcing | Lab-grown ceramides from Paris-Saclay fermentation facilities reduce climate-dependent agricultural risk. |
| Professional Channel Expansion | Salon-exclusive distribution in German underpenetrated networks captures margin expansion unavailable in mass retail. |
| Subscription Platform Launch | Algorithmic personalization engines in United Kingdom concentrate customer data ownership with brands. |
| CSRD Compliance Infrastructure | Supply-chain environmental footprint reporting creates first-mover advantage for institutional investor access. |
| Cold-Process Manufacturing Scale-Up | Energy-efficient compounding lowers facility carbon footprints while preserving botanical active integrity. |
Research Methodology
Independent corroboration across formulation chemists at barrier-repair laboratories, procurement leads at German specialty chemical distributors, and category buyers at Douglas and Sephora underwrites the qualitative findings. Primary interviews with R&D directors at heritage luxury houses and supply planners at Rhine corridor manufacturing facilities combined with secondary validation from ECHA substance restriction notifications, ANSM cosmetic safety bulletins, and customs records for preservative chemical imports. Bottom-up capacity assessments at bioreactor facilities and top-down consumption modeling across French pharmacy channels enable triangulation.
Rate-of-change decomposition across the analysis window segments volume and value outputs by product type (skincare, haircare, makeup, fragrance), distribution channel (supermarkets, online retail, specialty stores, salons), and end-user demographics (women, men, teens, seniors). CAGRs derive from regression analysis of historical replenishment cycle compression and subscription adoption curves, with inputs including ECHA regulatory timeline assumptions and biotech ingredient procurement cycle acceleration patterns.
Several conditions sit outside the modeled scope, including abrupt EMA cosmetic ingredient safety reclassifications and sovereign trade policy shifts affecting German chemical imports. Forecasts reflect assumptions about REACH registration continuity and EU Green Deal enforcement timelines. A small set of named triggers warrants ongoing watch: ECHA restricted substance list expansion pace, CSRD disclosure requirement implementation rigor, and cold-process equipment capacity buildout at Italian engineering clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Waterless Cosmetics Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetic Serum Market
Beauty & Personal Care
Electric Nail Files Market