
 Multi Pocket Holders Market | 2026-2036
Multi Pocket Holders Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Pocket Holders Market Foresight
The gap between premium branded multi pocket holders and commodity-grade alternatives is realigning as material certification and durability claims separate price tiers. Smurfit Kappa Group leverages its corrugated board expertise to dominate sustainable paper-based holder segments in Europe. WestRock Company anchors North American supply through integrated pulp-to-converting operations. Graphic Packaging International competes via food-contact compliant coatings that extend holder utility into retail display applications.
Multi pocket holders are rigid or semi-rigid containers featuring two or more partitioned compartments, typically manufactured through thermoforming, injection molding, die-cutting, or sewing processes depending on substrate, designed to organize, display, or transport multiple items in fixed positions. Fabric holders lead residential and student segments where washability and portability outweigh unit cost, while plastic holders sustain the fastest trajectory in professional and office settings due to moisture resistance and stackability. Metal holders occupy premium positioning in architectural and healthcare environments where sterilization compatibility and longevity justify higher price points.
REACH in Europe and FDA food-contact regulations in the United States constrain plasticizer and adhesive selection, pushing converters toward validated substrate declarations. India's BIS certification for plastic articles and the country's PLI scheme for technical textiles indirectly shape competitive cost structures for fabric and synthetic holders. Stakeholders must monitor evolving extended producer responsibility frameworks and material traceability requirements as these will determine which substrate categories retain cost advantages across key demand clusters.
Market Dynamics
REACH compliance in Europe is compressing plasticizer options for converters while India's PLI scheme for technical textiles redirects fabric holder investment toward domestic synthetic fiber capacity.
Growth Catalysts
- Hybrid work normalization:Office workers across North America and Western Europe are outfitting home workstations with stackable plastic organizers, sustaining replacement cycles for damaged residential units.
- REACH substance restrictions:ECHA's tightening limits on phthalates and heavy metals in plastic articles are accelerating validated substrate declarations among European converters seeking premium positioning.
- Technical textile incentives:India's PLI scheme is expanding domestic spunbond and needlepunch capacity, lowering input costs for fabric holder manufacturers serving student and residential segments.
Market Restraints
- Petrochemical volatility:Polypropylene and ABS resin prices fluctuate with naphtha cracking margins, compressing margin predictability for injection-molded plastic holder producers.
- Concentrated corrugated supply:European sustainable paper-based holder output depends on Smurfit Kappa and a handful of integrated board suppliers, creating bottleneck risk during pulp price spikes.
- Metal sterilization complexity:Autoclave-compatible stainless steel holders require precision welding and passivation, limiting viable fabricators to certified medical device subcontractors.
Strategic Opportunities
- Food-contact retail displays:Graphic Packaging International's barrier-coated board technology opens multi pocket holder applications for chilled ready-meal merchandising in US grocery chains.
- Healthcare sterilization workflows:Surgical kit organizers with color-coded compartments are penetrating ambulatory surgery centers in Germany and Switzerland where METI-equivalent quality protocols apply.
- Extended producer responsibility frameworks:France's AGEC law and similar mandates across EU member states are creating first-mover advantage for holders designed with mono-material construction and QR-coded disassembly instructions.
Industry Challenges
- Thermoforming die lead times:Custom aluminum tooling for deep-draw plastic holders requires 12-16 week procurement cycles, constraining rapid response to seasonal demand surges in back-to-school and tax-season office supply peaks.
- Fabric holder wash durability certification:Validating colorfastness and seam integrity across 50+ industrial laundry cycles for healthcare textile holders delays product launches by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Pocket Holders Market |
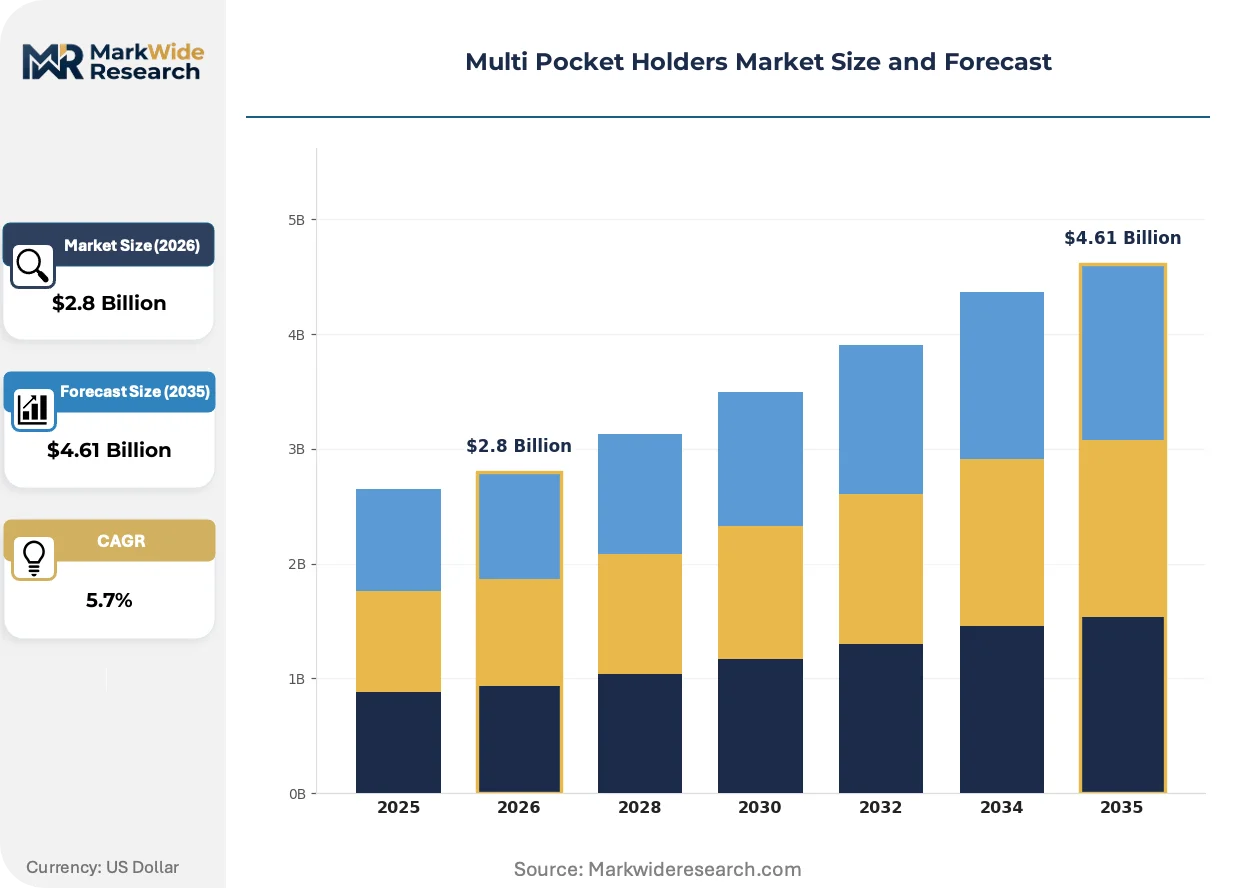
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric Holders, Plastic Holders, Metal Holders, Wood Holders End User: Residential Users, Office Workers, Students, Professionals Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Adflair India, Plastic Design & Manufacturing, Packzen, G.D. Enterprises, Smurfit Kappa Group, WestRock Company, Graphic Packaging International, Fishbone Packaging, Grip-Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Pocket Holders Market Shifts & Advancements
Material substitution and regulatory compliance are converging to reshape competitive positioning across substrate categories, with sustainability credentials increasingly separating price tiers.
Recycled-content polypropylene compounds with near-virgin mechanical properties are overtaking conventional resins in office-grade plastic holders. Corporate procurement teams in Germany and the Netherlands are mandating minimum 30% post-consumer content for supply contracts. This resin transition is compressing price premiums for sustainable variants while exposing smaller converters without validated recycling partnerships.
EU Green Deal implementation through the CSRD and packaging waste directives is forcing substrate disclosure down to the polymer batch level. Holders sold into French and Belgian retail channels now require traceability documentation for adhesives and coatings. Food-contact compliant variants with EFSA-validated barrier layers are capturing shelf-space in supermarket produce and deli departments.
Direct-to-facility procurement through specialized workplace supply platforms is fragmenting traditional distributor relationships. Facilities managers in US healthcare systems and UK universities are consolidating holder purchases with ergonomic furniture and storage contracts. This channel compression is most visible in the Nordics where municipal procurement cooperatives aggregate demand across hospitals and school districts.
Multi Pocket Holders Market Segmentation
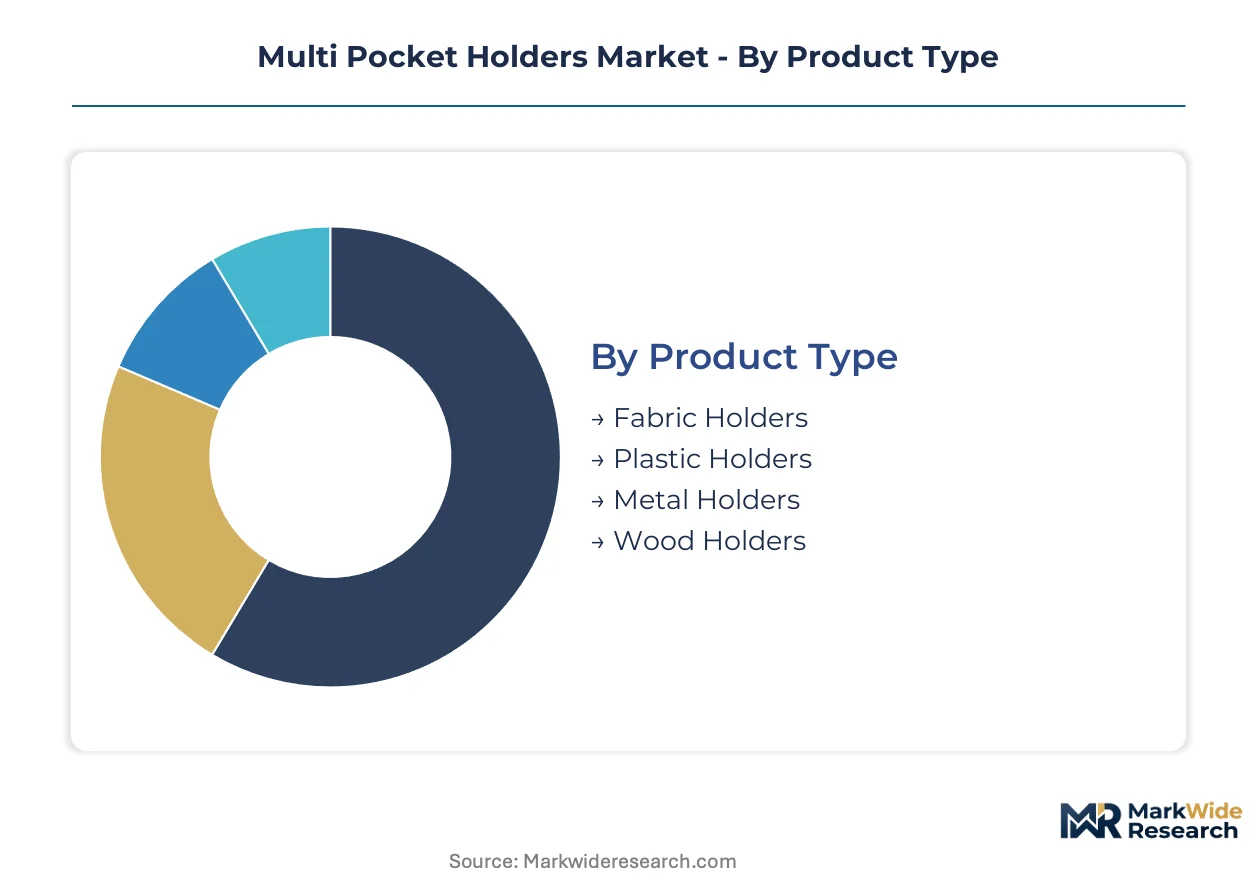
Multi pocket holders serve distinct use cases across material durability, workspace configuration, and procurement channel preferences. Understanding how upgrade cycles and replacement triggers vary by segment enables targeted positioning against specific functional requirements and compliance thresholds.
Product Type:
Replacement cycles diverge sharply by substrate durability, with premium metal holders measured in decades and commodity fabric variants in single-year refresh patterns.
- Fabric Holders:Woven or non-woven textile constructions featuring stitched compartments and reinforced seams. Students in India and residential users in Western Europe drive volume through portability requirements and washability expectations that trigger annual replacement purchases.
- Plastic Holders:Injection-molded polypropylene or ABS thermoformed shells with integrated dividers. Office workers across Germany and the United States sustain demand through stackability and moisture resistance that supports hybrid work normalization and document protection needs.
- Metal Holders:Stainless steel or powder-coated aluminum frameworks with welded compartment grids. Surgical kit organizers in Swiss ambulatory centers and architectural specification projects justify premium positioning through autoclave compatibility and multi-decade service life.
- Wood Holders:CNC-milled or joined hardwood constructions with routed slot dividers. Boutique retail displays and premium residential desk accessories in Scandinavian markets emphasize aesthetic warmth over functional durability.
Plastic holders sit at the top of the volume ranking, with metal holders climbing the fastest on healthcare sterilization workflow penetration.
End User:
Cost tier stratification separates budget-conscious student procurement from enterprise-scale office supply contracts with negotiated service agreements.
- Residential Users:Home organization applications spanning kitchen utensil storage to craft supply sorting. REACH-compliant plastic variants face substitution pressure from fabric alternatives in French and Belgian households responding to extended producer responsibility mandates.
- Office Workers:Hybrid work infrastructure investments including document organizers and cable management systems. Corporate procurement teams in the Netherlands specify minimum recycled content thresholds that reshape supplier qualification requirements.
- Students:Backpack-integrated and dorm-room storage solutions prioritizing lightweight construction and price accessibility. India's technical textile PLI scheme expands domestic spunbond capacity serving this price-sensitive volume segment.
- Professionals:Healthcare, legal, and architectural practitioners requiring certified material traceability and customized compartment configurations. FDA food-contact compliance opens adjacent retail display applications for barrier-coated variants in US grocery chains.
Office workers command the highest per-unit spend bracket, with professionals expanding most quickly on compliance-driven specification upgrades.
Size:
Application geometry and storage footprint requirements determine dimensional clustering across portable, desktop, and fixed-installation use cases.
- Small:Pocket-sized organizers for travel accessories, medication, and electronic cables. Airline carry-on compliance and TSA checkpoint convenience sustain replacement demand in US and UK frequent traveler segments.
- Medium:Desktop document trays and drawer inserts dominating standard office cubicle configurations. German workplace ergonomics regulations indirectly shape dimensional standards through filing system compatibility requirements.
- Large:Countertop appliance organizers and retail display fixtures. Supermarket produce departments in France specify food-contact barrier coatings that extend holder utility into chilled merchandising applications.
- Extra Large:Floor-standing or wall-mounted systems for warehouse picking stations and healthcare supply rooms. Custom aluminum thermoforming dies for deep-draw plastic variants constrain rapid response to seasonal demand surges in this dimensional class.
Medium dimensions anchor volume production runs, with large formats gaining share fastest on retail display diversification.
Distribution Channel:
Customer type and purchase urgency dictate channel selection, with direct procurement consolidating among institutional buyers and fragmented retail serving discretionary replacement.
- Online Retailers:E-commerce platforms capturing student and residential segments through price transparency and bulk purchase incentives. Amazon and specialized workplace supply platforms fragment traditional distributor relationships in Nordic municipal procurement cooperatives.
- Specialty Stores:Office furniture dealers and healthcare supply distributors offering specification support and ergonomic consultation. Facilities managers in UK universities consolidate holder purchases with storage system contracts through this channel.
- Supermarkets:Mass-market placement for commodity-grade plastic and fabric variants targeting impulse replacement purchases. Food-contact compliant coatings enable shelf-space expansion into deli and produce departments.
- Direct Sales:Manufacturer-to-institution contracts for customized healthcare and corporate rollout programs. Smurfit Kappa's corrugated board expertise leverages this channel for sustainable paper-based holder deployment across European retail chains.
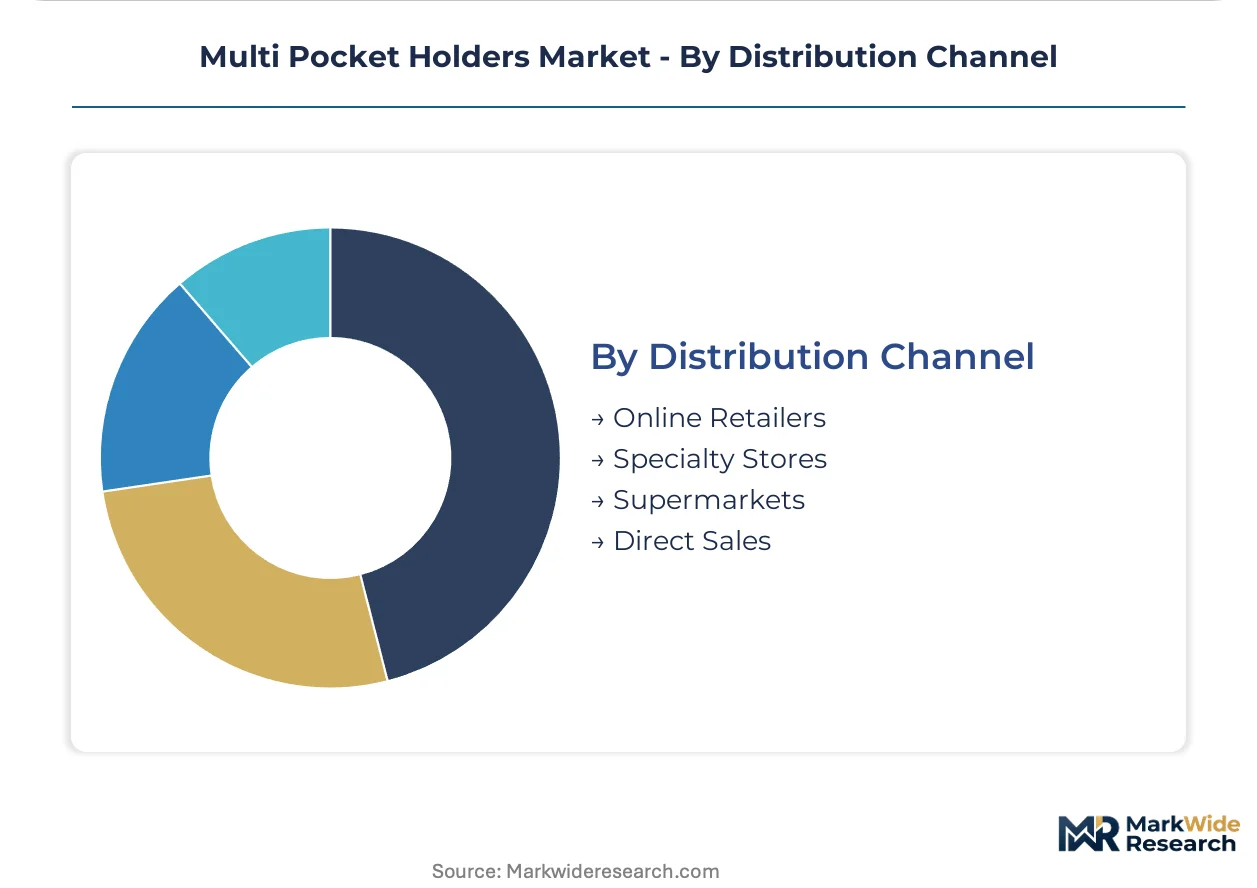
Online retailers process the highest transaction volume, with direct sales expanding most quickly on institutional procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Office workers in Germany and the United States anchor professional-grade demand through hybrid work infrastructure investments. India's student population and technical textile workforce drive volume production of fabric variants. Swiss healthcare procurement teams specify sterilization-compatible metal organizers for surgical workflows.
United States
Corporate procurement teams in the Netherlands specify minimum recycled content thresholds that reshape supplier qualification requirements. FDA food-contact regulations constrain plasticizer selection for retail display applications. Dallas-Fort Worth logistics corridors concentrate injection-molded plastic holder distribution for back-to-school and tax-season demand surges.
Germany
Workplace ergonomics regulations indirectly shape dimensional standards through filing system compatibility requirements. ECHA's tightening REACH limits on phthalates accelerate validated substrate declarations among converters. Stuttgart industrial clusters host precision thermoforming operations serving automotive document management systems.
India
Students in Maharashtra and Gujarat drive annual replacement purchases of lightweight fabric organizers. BIS certification for plastic articles and the PLI scheme for technical textiles expand domestic spunbond capacity. Tiruppur textile belt converters leverage needlepunch infrastructure for washable holder exports to European residential segments.
Switzerland
Ambulatory surgery centers in Zurich and Geneva specify METI-equivalent quality protocols for surgical kit organizers. Swissmedic oversight of medical device subcontractors constrains autoclave-compatible stainless steel fabrication to certified precision welders. Basel pharmaceutical procurement cooperatives consolidate holder purchases with laboratory supply contracts.
France
Supermarket produce departments in Paris and Lyon specify food-contact barrier coatings extending holder utility into chilled merchandising. AGEC law mandates mono-material construction with QR-coded disassembly instructions for extended producer responsibility compliance. Lille packaging innovation clusters develop validated recycling partnerships for post-consumer polypropylene compounds.
Multi Pocket Holders Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across substrate categories in a moderately fragmented structure. Integrated pulp-to-converting operations anchor supply security for paper-based variants while specialized thermoformers and textile converters populate commodity tiers. Three archetypes dominate: corrugated board specialists with backward integration into sustainable forestry, injection molders with captive resin compounding capabilities, and technical textile houses with industrial laundry certification partnerships. Capacity expansion and validated recycling partnerships constitute the dominant competitive moves as procurement teams mandate batch-level traceability documentation.
Among India-based fabricators, Adflair India exemplifies the technical textile tier leveraging PLI scheme incentives for spunbond capacity expansion. Smurfit Kappa Group and WestRock Company occupy positions within the integrated paper-based holder segment, with the former representing European corrugated expertise and the latter anchoring North American pulp-to-converting supply security.
| Leading Market Players |
|---|
| Adflair India |
| Plastic Design & Manufacturing |
| Packzen |
| G.D. Enterprises |
| Smurfit Kappa Group |
| WestRock Company |
| Graphic Packaging International |
| Fishbone Packaging |
| Grip-Pak |
| Others |
Supply & Pricing Matrix
Recycled-content polypropylene compounding for office-grade holders simultaneously compresses sustainable price premiums and concentrates supply among converters with validated recycling partnerships. ECHA's REACH substance restrictions and India's PLI scheme for technical textiles are bifurcating cost structures between European premium positioning and Indian volume production.
Pricing Analysis
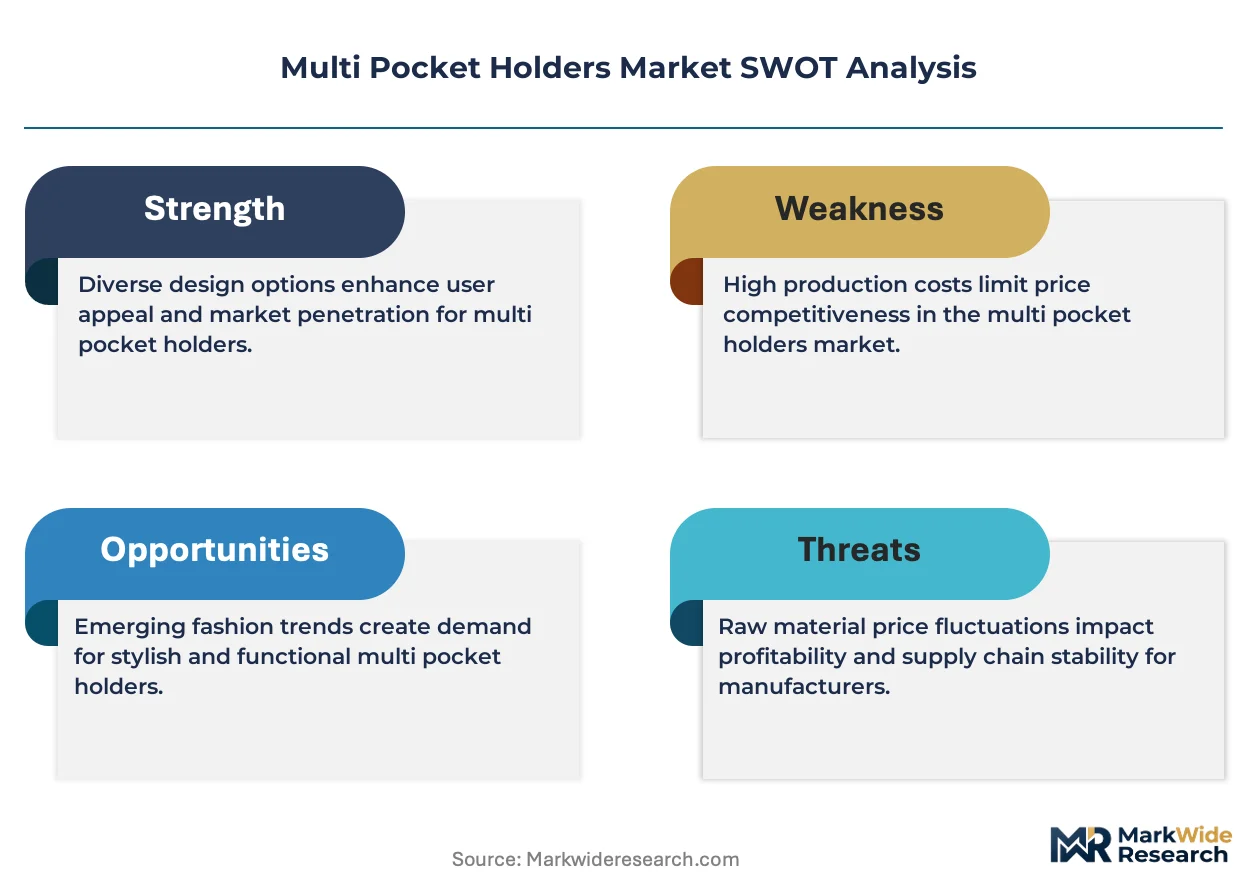
The bundled-vs-unbundled service split separates contract-based procurement with traceability documentation from spot-market commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-tier plastic variants is intensifying because petrochemical volatility compresses margin predictability. Students in India exhibit highest price sensitivity, while Swiss healthcare procurement teams demonstrate lowest sensitivity due to sterilization compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements from German corporate procurement teams and French retail chains mandate multi-supplier qualification across substrate categories. Manufacturing concentrates in India for fabric variants, China for thermoformed plastic components, and Germany for precision metal fabrication. Raw material inputs draw from polypropylene resin markets, technical textile spunbond capacity, and corrugated board pulp supply. Single-source vulnerability persists in custom aluminum thermoforming dies with 12-16 week procurement cycles. Distribution runs through direct sales for institutional healthcare contracts and online retail for student and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal implementation through CSRD and packaging waste directives continuously escalates compliance thresholds that reshape procurement specifications.
For Market Incumbents: Hedge against resin price volatility through backward integration into recycled-content polypropylene compounding or long-term offtake agreements with validated recycling partners. Smurfit Kappa's corrugated board expertise demonstrates how sustainable forestry integration defends margin position against commodity board price spikes. ECHA's tightening phthalate limits threaten incumbents without batch-level traceability documentation.
For New Entrants and Emerging Players: Specialized workplace supply platforms offer the most penetrable channel entry point for bypassing traditional distributor relationships consolidating in Nordic municipal procurement cooperatives. Target fabric holder segments in Indian student markets where PLI scheme incentives lower synthetic fiber input costs. Food-contact retail display applications in French supermarket produce departments present adjacent white-space with barrier-coated board technology requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among technical textile converters with industrial laundry certification partnerships serving healthcare sterilization workflows. Long-term viability across the projection horizon rests on extended producer responsibility framework compliance capabilities. Watch France's AGEC law implementation trajectory as the signal indicating which substrate categories retain structural cost advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification Investment | Post-consumer polypropylene compounds with near-virgin properties unlock German and Dutch corporate procurement contracts. |
| Technical Textile Capacity Expansion | PLI scheme incentives in India lower spunbond input costs for fabric holder exports to European residential segments. |
| Food-Contact Barrier Coating Development | EFSA-validated layers extend holder utility into French supermarket chilled ready-meal merchandising applications. |
| Direct-to-Facility Platform Partnership | UK university facilities managers consolidate holder purchases with ergonomic furniture contracts through specialized supply platforms. |
| Mono-Material Construction Redesign | QR-coded disassembly instructions meet France's AGEC law mandates for extended producer responsibility compliance. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with injection molding plant managers, technical textile procurement leads, retail category buyers, and healthcare supply chain directors combined with secondary validation from customs records, BIS certification databases, and ECHA substance restriction filings. Triangulation across stakeholder inputs and regulatory documentation ensures segment-level accuracy.
Historical trendline analysis of replacement cycle patterns across substrate categories informed projection framework construction. Segmentation dimensions span material type, end-user archetype, dimensional class, and distribution channel throughout the forecast period. CAGRs derive from elasticity-adjusted demand curves incorporating hybrid work normalization trajectories and regulatory compliance cost pass-through assumptions. Forecast inputs include petrochemical price volatility indices and technical textile capacity utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction amendments and extended producer responsibility framework expansions. Deviation in EU packaging waste directive implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Bath Heater Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
South Korea Cookware Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
UK Digital Showers Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Powered Lawn Mowers Market
Household Items
Air Humidifier Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Canada Digital Showers Market
Household Items
Japan Faucets Market
Household Items
Middle East and Africa Air Purifier Market
Household Items
Fan Market
Household Items
Manual Bottle Opener Market
Household Items
Electric Hedge Trimmer Market
Household Items
Brush Cover Market