
 Saudi Arabia Cookware Market | 2026-2036
Saudi Arabia Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Cookware Market Insights
Commercial kitchen operators are bifurcating from traditional household buyers as the dominant growth archetype in Saudi Arabia's cookware channel. TTK Prestige Ltd. leverages its induction-compatible portfolio to capture contract catering demand in Riyadh's expanding hotel sector. GROUPE SEB anchors its position through multi-brand distribution across hypermarket and specialty retail channels. Alama Enterprises competes with localized supply chain arrangements that reduce lead times for institutional buyers in the Central Region.
Cookware encompasses metal vessels engineered for thermal conductivity, food safety compliance, and repeated thermal cycling across stovetop and oven environments. Stainless steel variants with aluminum-core construction achieve heat distribution thresholds required for commercial kitchen throughput, while non-stick ceramic coatings address consumer preference for reduced-oil preparation. Stainless steel commands the largest material share due to durability demands from Saudi foodservice operators, though non-stick fry pans represent the fastest-expanding product type among urban households. International brands dominate margin pools in premium mall-based specialty stores, while local brands occupy price-sensitive segments through hypermarket distribution.
SFDA governs food-contact material safety standards for all imported cookware, requiring migration testing for heavy metals and coating stability. SASO mandates energy-efficiency labeling and product conformity assessments under its Saudi Quality Mark scheme, directly affecting market access timelines for foreign manufacturers. The Vollrath Company, LLC navigates these requirements through certified Gulf-region distribution partnerships. Stakeholders must monitor evolving SASO technical regulations for induction compatibility standards as Saudi Arabia electrifies commercial kitchen infrastructure.
Market Dynamics
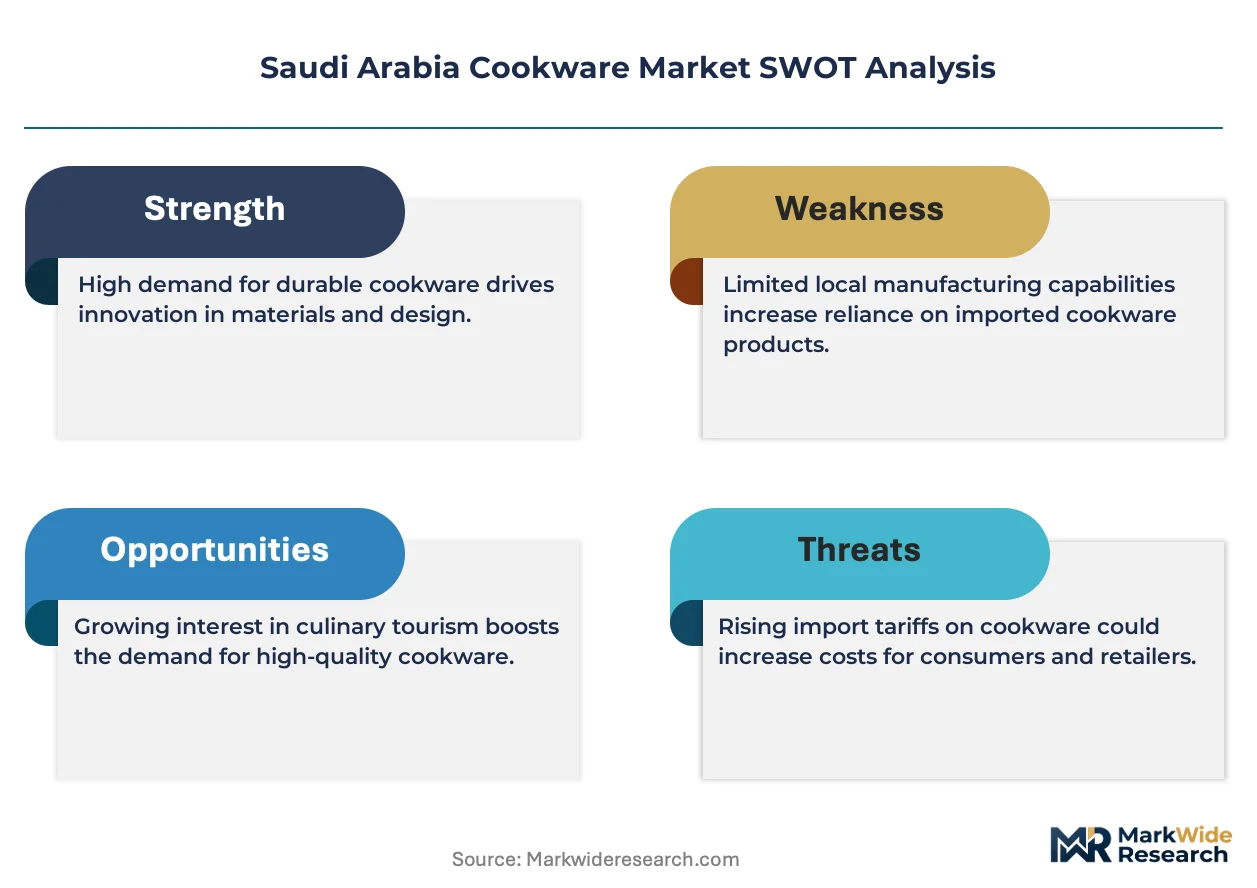
Saudi Arabia's commercial kitchen electrification is compressing replacement cycles for legacy gas-compatible cookware, while SFDA and SASO compliance timelines extend procurement lead times for imported collections.
Growth Catalysts
- Induction infrastructure rollout:Riyadh and Jeddah hotel operators are specifying induction-compatible stainless steel collections as kitchen electrification accelerates under Saudi Vision 2030 targets.
- SFDA food-contact compliance:Migration testing mandates for heavy metals and coating stability are filtering out low-grade imports, creating premium positioning for certified manufacturers.
- Central Region foodservice density:Riyadh's concentration of contract catering, hotel chains, and cloud kitchen facilities generates concentrated demand for commercial-grade thermal cycling performance.
Market Restraints
- Aluminum price volatility:Core-clad construction relies on aluminum thermal layers, exposing margin structures to London Metal Exchange price swings and freight cost pass-through.
- Import concentration risk:European and East Asian manufacturing clusters dominate certified supply, leaving Saudi distributors vulnerable to shipping lane disruptions through the Red Sea corridor.
- SFDA testing bottlenecks:Laboratory capacity constraints for food-contact material certification extend product registration timelines, delaying market entry for new collections.
Strategic Opportunities
- Eastern Province hospitality pipeline:Khobar and Dammam hotel developments along the Gulf coast represent underpenetrated procurement zones with less saturated distributor networks than Riyadh.
- SASO energy-efficiency labeling:Early certification under evolving induction compatibility standards creates first-mover positioning as commercial kitchen electrification mandates tighten.
- Direct-to-institutional channels:Cloud kitchen operators and ghost kitchen infrastructure projects are bypassing traditional retail distribution, enabling volume contracts with shorter sales cycles.
Industry Challenges
- Technical salesforce scarcity:Commercial kitchen specification requires staff fluent in thermal conductivity metrics, induction frequency compatibility, and SFDA documentation protocols.
- Legacy gas-equipment integration:Hybrid kitchen environments demand cookware compatible with both induction and conventional flame, complicating product line architecture and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Cookware Market |
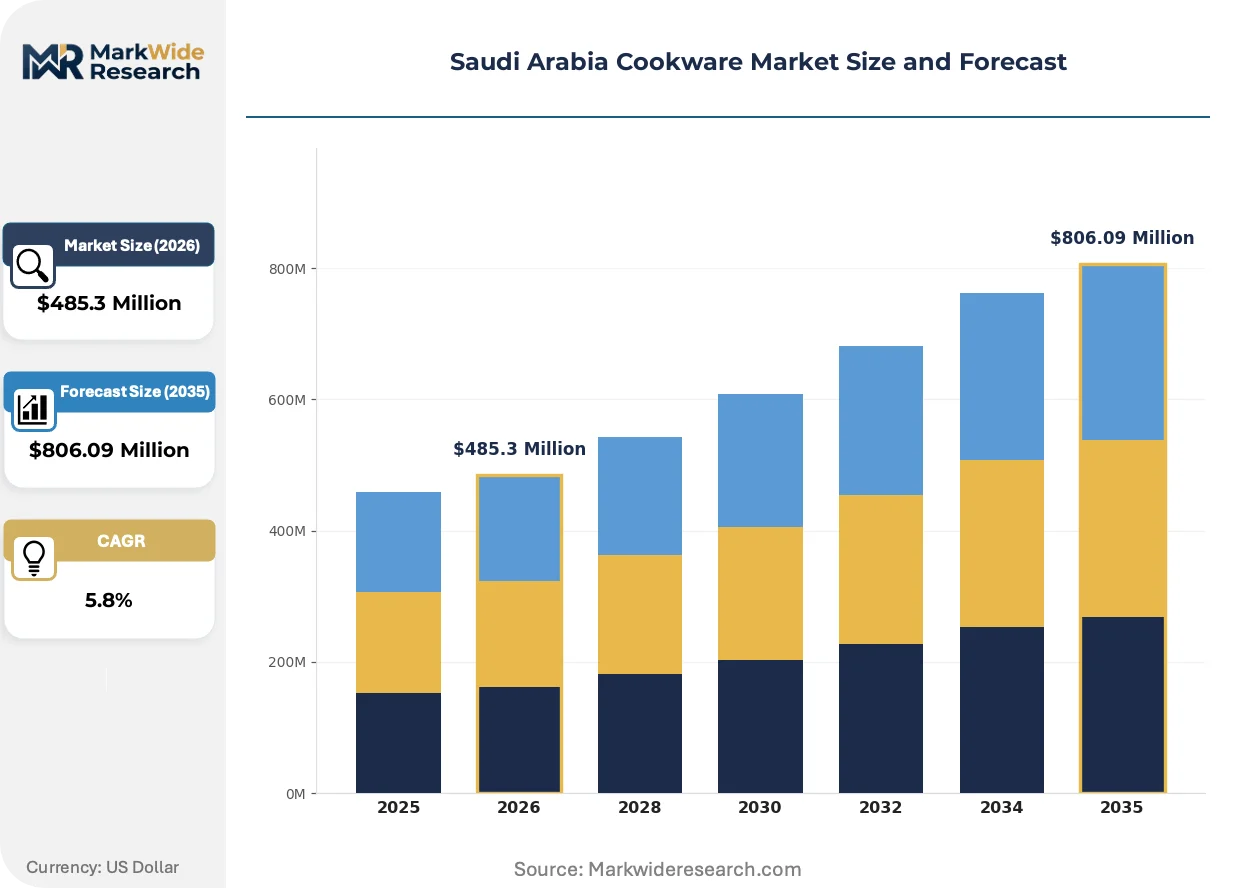
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware Sets, Fry Pans, Saucepans, Stock Pots Material: Stainless Steel, Cast Iron, Non-stick, Copper Brand: Local Brands, International Brands, Premium Brands, Budget Brands Sales Channel: Online Retail, Specialty Stores, Department Stores, Hypermarkets |
| Companies Covered | TTK Prestige Ltd., Newell Brands, Alama Enterprises, Tramontina, Fissler, Oasis International, The Vollrath Company, LLC, Zinox El Zenouki, GROUPE SEB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Cookware Market Trends and Innovations
Material science advances and regulatory precision are compressing the gap between consumer-grade aesthetics and commercial-grade durability, reshaping how Saudi buyers evaluate cookware procurement.
Multi-layer stainless steel construction with embedded aluminum or copper cores is fragmenting the traditional divide between restaurant-grade and household cookware. Jeddah's premium residential developments now specify thermal performance thresholds previously reserved for hotel procurement. This convergence is compressing price premiums for professional collections while elevating baseline consumer expectations.
SASO's expanding technical regulations for induction compatibility are forcing recertification of existing product lines. Manufacturers must resubmit collections for electromagnetic efficiency testing under updated Saudi Quality Mark protocols. Commercial kitchen operators in Riyadh are prioritizing pre-certified collections to avoid procurement delays during renovation cycles.
Foodservice procurement teams are consolidating vendor relationships around full-service kitchen outfitters rather than discrete cookware suppliers. Hotel operators in the Central Region now expect bundled specification support, staff training, and maintenance scheduling alongside product delivery. This unbundling of procurement risk is favoring distributors with in-house culinary technical support over pure retail channels.
Saudi Arabia Cookware Market Segmentation
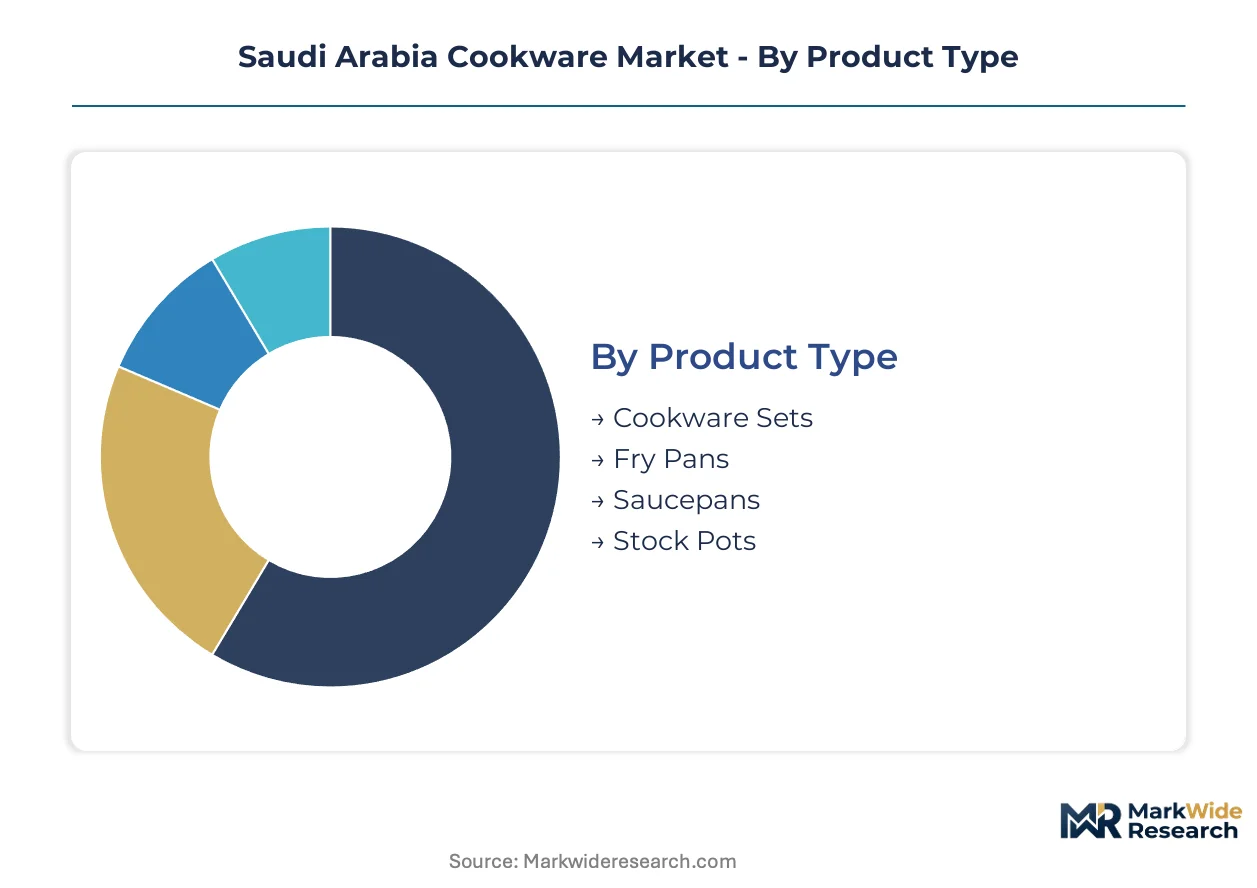
Cookware procurement patterns in Saudi Arabia diverge sharply between institutional buyers prioritizing thermal cycling durability and households balancing aesthetic preference with price sensitivity. Material specifications and certification compliance create non-substitutable requirements that lock segments into distinct supply channels.
Product Type:
Substitution pressure concentrates in single-vessel categories where cloud kitchen operators and ghost kitchen facilities prioritize unit economics over set completeness.
- Cookware Sets:Bundled configurations of five to twelve pieces with coordinated thermal performance ratings. Hotel procurement teams in Riyadh's Central Region specify these for uniform kitchen outfitting, though SASO recertification costs for entire collections extend replacement cycles.
- Fry Pans:Shallow vessels with optimized surface-area-to-depth ratios for high-heat searing and reduced-oil preparation. Non-stick ceramic coatings dominate urban household demand in Jeddah's premium residential developments, displacing traditional carbon steel in consumer channels.
- Saucepans:Medium-capacity vessels with pour spouts and lid compatibility for reduction cooking and sauce preparation. Contract catering operators favor stainless steel variants with aluminum-core construction for consistent heat distribution across batch operations.
- Stock Pots:Large-capacity vessels engineered for broth extraction and volume cooking. Commercial kitchen electrification in Riyadh hotel renovations is filtering demand toward induction-compatible base constructions with magnetic grade verification.
Cookware Sets retain volume leadership; Fry Pans hold the steepest expansion curve.
Material:
Cost tier stratification separates foodservice procurement from retail channels, with thermal conductivity specifications determining acceptable price bands.
- Stainless Steel:Austenitic grades with embedded aluminum or copper cores achieving heat distribution thresholds required for commercial throughput. SFDA migration testing for nickel and chromium leaching creates compliance barriers that favor established Gulf-region distributors with certified laboratory relationships.
- Non-stick:Ceramic and reinforced fluoropolymer coatings applied to aluminum or stainless steel substrates. Saudi households in urban centers are expanding purchases as reduced-oil cooking aligns with health positioning, though coating durability concerns limit commercial adoption.
- Cast Iron:Ferrous vessels with seasoning-dependent non-stick properties and extreme thermal retention. Niche demand concentrates among traditional cooking enthusiasts and specialty restaurant concepts emphasizing heritage preparation methods.
- Copper:High-conductivity vessels with tin or stainless steel lining for reactive food contact. Premium positioning in Jeddah specialty retail channels targets culinary professionals and affluent households seeking thermal responsiveness for precision cooking.
Stainless Steel commands institutional procurement volume; Non-stick is climbing the fastest in household replacement cycles.
Brand:
Customer type segmentation separates specification-driven institutional buyers from price-elastic retail consumers, with certification history serving as the primary trust signal.
- International Brands:Manufacturers with established SFDA compliance histories and Gulf-region distribution infrastructure. These collections occupy premium mall-based specialty stores and hotel procurement channels where documentation transparency reduces vendor risk.
- Local Brands:Domestic or regional manufacturers with localized supply chains reducing lead times for institutional buyers. Hypermarket distribution dominates, with price positioning targeting budget-conscious households in the Central Region.
- Premium Brands:Collections emphasizing design differentiation, limited production runs, and chef endorsement partnerships. Concentrated in Riyadh's luxury retail clusters and hospitality gift channels.
- Budget Brands:Basic functionality offerings with minimal coating complexity and simplified base construction. Volume sales through hypermarket promotional cycles serve price-sensitive segments and temporary foodservice installations.
International Brands retain procurement preference among certified buyers; Local Brands are gaining share fastest through hypermarket expansion.
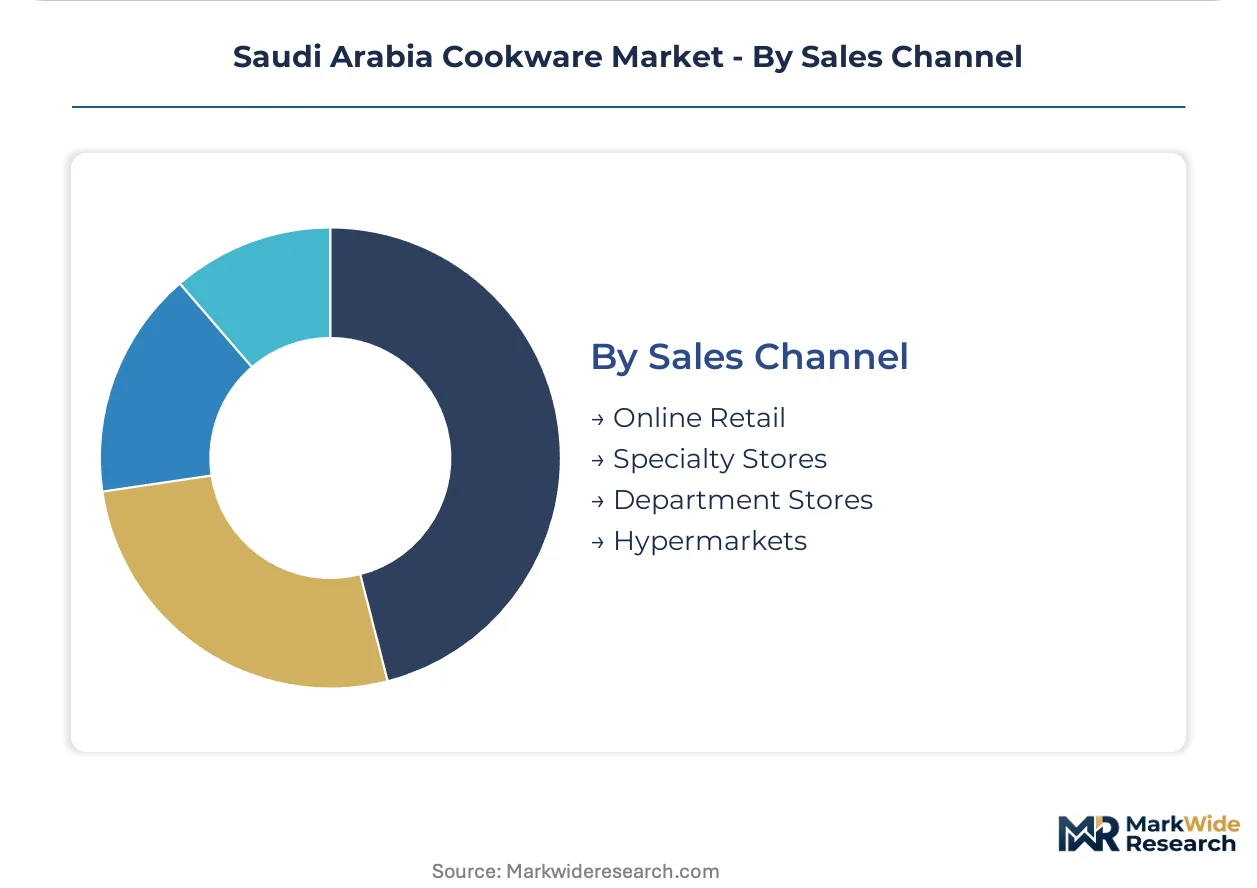
Sales Channel:
Supply concentration in import-dependent distribution creates vulnerability to Red Sea shipping disruptions, favoring channels with inventory depth and alternative sourcing relationships.
- Hypermarkets:Large-format retail with dedicated housewares sections and promotional pricing cycles. Central Region concentration aligns with Riyadh's population density and foodservice procurement consolidation.
- Specialty Stores:Curated collections with in-house culinary demonstration and specification support. Jeddah's premium retail clusters host these outlets, serving hotel outfitters and affluent households with technical sales assistance.
- Online Retail:E-commerce platforms with expanded delivery coverage and comparison shopping infrastructure. Cloud kitchen operators and ghost kitchen projects increasingly specify through these channels for direct-to-facility delivery.
- Department Stores:Mid-tier retail with mixed housewares inventory and seasonal promotional calendars. Declining relative share as hypermarket scale and online convenience fragment traditional department store traffic.
Hypermarkets retain volume leadership; Online Retail holds the steepest expansion curve among procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import-dependent distribution clusters around Red Sea shipping corridors, concentrating certified supply in the Central Region while Eastern Province hospitality projects open alternative procurement zones. SFDA laboratory capacity and SASO certification timelines create geographic friction that favors distributors with established Gulf-region infrastructure.
Riyadh
Hotel renovation cycles and cloud kitchen proliferation are compressing replacement timelines for induction-compatible collections. SFDA migration testing requirements filter import flows through certified distributors with laboratory relationships. The King Abdullah Financial District and Diriyah hospitality corridor concentrate contract catering procurement for stainless steel thermal cycling performance.
Jeddah
Premium residential developments are elevating consumer-grade thermal performance expectations previously reserved for commercial buyers. SASO energy-efficiency labeling mandates reshape retail inventory planning for specialty stores in the Tahlia Street retail cluster. Red Sea port proximity reduces freight lead times for European and East Asian manufacturing clusters.
Eastern Province
Khobar and Dammam hotel developments along the Gulf coast represent underpenetrated procurement zones with less saturated distributor networks. SFDA food-contact compliance timelines extend product registration for new market entrants lacking established Gulf-region partnerships. Aramco-related hospitality infrastructure generates institutional demand for commercial-grade durability specifications.
Western Region
Makkah and Madinah hospitality operators serving religious tourism flows prioritize rapid replacement cycles for high-throughput kitchen environments. Localized supply chain arrangements from regional distributors reduce lead times compared to Central Region import concentration. SASO technical regulations for induction compatibility are forcing recertification of existing product lines ahead of kitchen electrification mandates.
NEOM Northwest
Sustainable city construction is specifying commercial kitchen infrastructure with electrification targets that filter cookware procurement toward pre-certified induction-compatible collections. SFDA and SASO compliance documentation serves as primary vendor selection criteria for project procurement teams. Giga-project scale enables direct-to-institutional volume contracts bypassing traditional retail distribution channels.
Saudi Arabia Cookware Market Competitive Landscape
Concentration sits with international manufacturers possessing established SFDA compliance histories and Gulf-region distribution infrastructure. The market structures around three tiers: premium collections occupying mall-based specialty retail, institutional-grade suppliers serving hotel procurement channels, and localized distributors competing on hypermarket price positioning. Strategic moves center on certification pre-positioning ahead of evolving SASO induction standards and direct-to-institutional channel development bypassing traditional retail.
Within the international manufacturer tier, TTK Prestige Ltd. and GROUPE SEB exemplify archetypes leveraging multi-brand distribution across hypermarket and specialty retail channels. Alama Enterprises occupies a position representing localized supply chain arrangements that reduce lead times for institutional buyers. The Vollrath Company, LLC sits within the certified Gulf-region distributor archetype navigating SFDA and SASO requirements through established partnerships.
| Leading Market Players |
|---|
| TTK Prestige Ltd. |
| Newell Brands |
| Alama Enterprises |
| Tramontina |
| Fissler |
| Oasis International |
| The Vollrath Company, LLC |
| Zinox El Zenouki |
| GROUPE SEB |
| Others |
Pricing and Supply Chain Analysis
Project-based procurement contracts for hotel renovation cycles lock in both aluminum-core stainless steel supply access and price visibility against London Metal Exchange volatility. SFDA certification timelines and SASO energy-efficiency labeling requirements compress negotiation windows, forcing buyers to accept fixed-price terms for certified collections.
Pricing Analysis
SASO energy-efficiency labeling dictates the pricing tier structure across Saudi Arabia's cookware channel. Three-tier pricing structure across premium, standard, and economy levels separates induction-certified hotel collections from basic household fry pans and budget hypermarket offerings. Price differentiation rests on SFDA compliance history and thermal conductivity certification grade. Cost compression in standard-tier aluminum-core construction is intensifying because freight pass-through from Red Sea disruptions squeezes distributor margins. Cloud kitchen operators exhibit highest price sensitivity; Riyadh hotel procurement teams show least sensitivity due to bundled specification support requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites the bulk of European and East Asian cookware shipments into Jeddah's Red Sea ports. Manufacturing concentrates in China, South Korea, and Germany for stainless steel forming and ceramic coating application. Raw material dependencies include aluminum thermal bonding layers, nickel-chromium austenitic steel grades, and fluoropolymer coating precursors. Single-source vulnerability concentrates in certified Gulf-region distributors with established SFDA laboratory relationships. Distribution runs through hypermarket central buying offices and specialty store direct import arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's cookware market fragments around electrification timelines, creating niches for certified induction-compatible specialists alongside legacy gas-compatible suppliers. Cloud kitchen proliferation and hotel renovation cycles generate divergent procurement rhythms that reward flexible supply chain architectures.
For Market Incumbents: Compound certification advantages by pre-positioning collections under evolving SASO induction standards before mandatory recertification deadlines. Deepen backward integration into aluminum-core bonding capacity to offset London Metal Exchange price volatility threatening margin structures. Defensive priority sits with locking long-term offtake agreements with Riyadh hotel operators ahead of Eastern Province hospitality pipeline competition. For New Entrants and Emerging Players: Differentiate on rapid SFDA compliance turnaround for cloud kitchen operators bypassing traditional retail distribution. Target Khobar and Dammam hotel developments with localized inventory positioning that reduces lead times versus Central Region import concentration. Go-to-market angle should emphasize direct-to-institutional volume contracts with embedded staff training and maintenance scheduling. For Investors and Strategic Acquirers: Capital is best deployed toward certified Gulf-region distributors with established SFDA laboratory relationships and multi-brand portfolio breadth. Long-term viability over the next decade hinges on electrification mandate timing and commercial kitchen infrastructure buildout pacing. Watch for SASO technical regulation publication schedules as inflection signal for induction compatibility standard enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pre-Certification Investment | Early compliance positioning captures hotel procurement ahead of mandatory recertification cycles. |
| Direct-to-Institutional Channel Development | Cloud kitchen operators bypass hypermarkup through volume contracts with shorter sales cycles. |
| Aluminum-Core Backward Integration | In-house thermal bonding capacity insulates margin structures from London Metal Exchange volatility. |
| Eastern Province Distribution Expansion | Khobar and Dammam hotel pipelines offer less saturated procurement zones than Riyadh concentration. |
| Technical Salesforce Development | Staff fluent in induction frequency compatibility and SFDA documentation protocols secure commercial specifications. |
Research Methodology
A spread of perspectives from hotel procurement directors, contract catering operators, hypermarket category buyers, specialty store owners, and SFDA regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SASO technical regulation filings, customs import records, Red Sea shipping manifests, and hospitality sector capex disclosures. Bottom-up demand modeling from institutional buyer specifications triangulated against top-down market sizing from distributor shipment data.
Segmentation dimensions modeled include product type, material construction, brand tier, and sales channel across the analysis window. CAGRs were derived from weighted average growth trajectories incorporating electrification mandate pacing, hotel renovation cycle timing, and cloud kitchen facility buildout rates. Industry-specific forecast inputs include SFDA laboratory capacity constraints and SASO recertification cost pass-through assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained commercial kitchen electrification and stable Red Sea shipping corridors; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as SFDA testing bottleneck severity and aluminum price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Steamers Market
Household Items
Drinkware Market
Household Items
Tiki Torch Market
Household Items
United Kingdom Air Purifier Market
Household Items
Leaf Blower Market
Household Items
Plastic Bathtub Market
Household Items
Porcelain Tableware Market
Household Items
Can Opener Market
Household Items
Range Hood Cleaning Service Market
Household Items
South Korea Cookware Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
South Africa Cookware Market
Household Items
Toilet Cistern Blocks Market
Household Items
Global Buddhist Supplies Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Silicone Soap Mold Market