
 Smart Drying Racks Market | 2026-2036
Smart Drying Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Drying Racks Market Analytics
Residential buyer concentration is pivoting toward urban apartment complexes and property developers specifying smart home infrastructure in new builds. Xiaomi leverages its IoT ecosystem to bundle drying racks with broader smart home platforms, while HOTATA anchors its position through specialized manufacturing scale in motorized lifting systems. Panasonic competes on climate-control integration, extending its HVAC expertise into humidity-managed drying solutions.
Smart drying racks are electromechanical laundry fixtures incorporating sensors, motorized deployment, and connectivity modules to optimize air circulation and drying cycles based on ambient humidity and load weight. Wall-mounted electric variants with integrated heating elements currently occupy the largest share of installed value, though IoT-enabled units with app-based scheduling represent the fastest-growing technology segment. Climate control features command premium positioning, while portable racks serve price-sensitive entry segments with thinner margins.
China's MIIT enforces GB standards for wireless connectivity and energy consumption in smart home devices, while the EU's Ecodesign Directive and CE marking requirements shape product architecture for European-bound exports. India's BIS certification mandates electrical safety testing for imported motorized appliances, creating compliance barriers for unaccredited manufacturers. Stakeholders must monitor evolving interoperability standards as smart home platforms consolidate around dominant protocols.
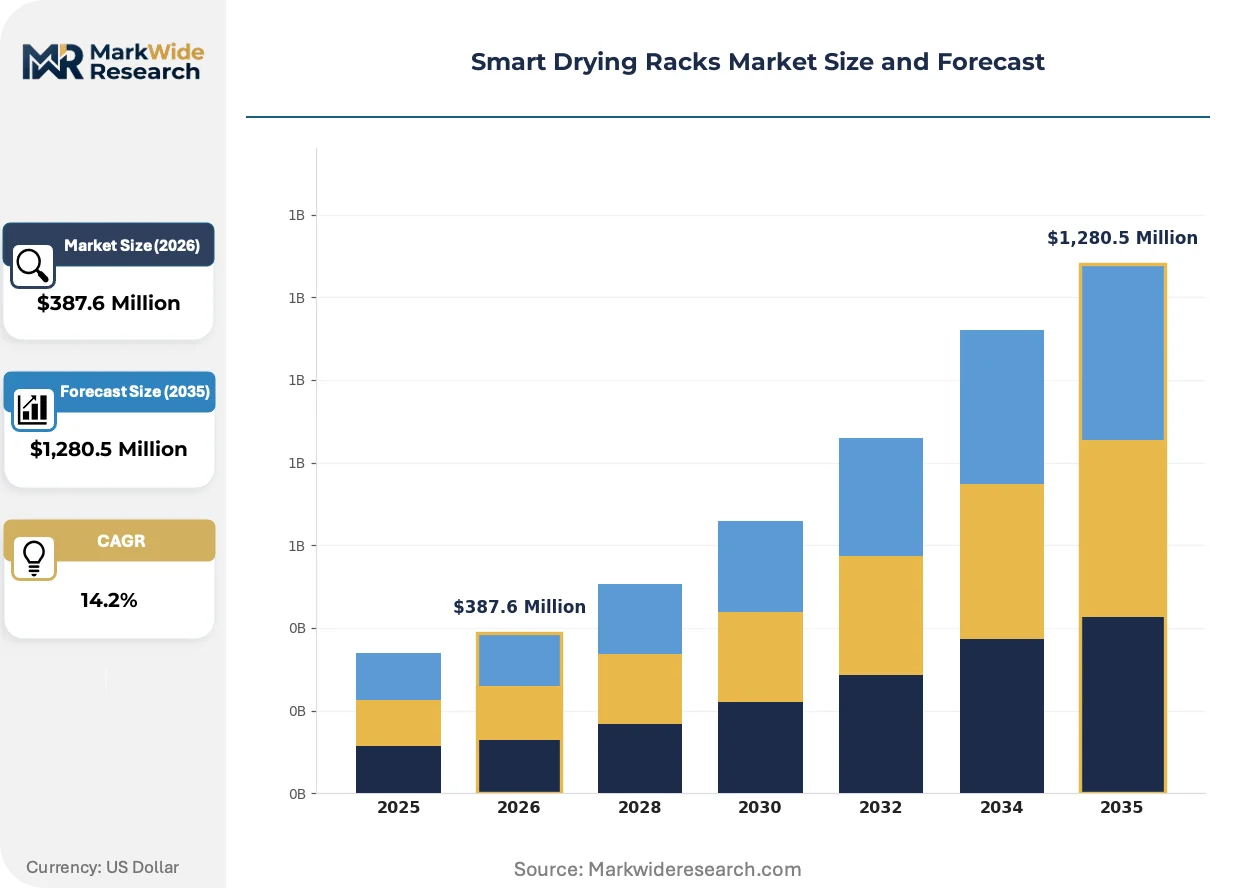
Market Dynamics
Urbanization density and smart home platform consolidation are compressing distribution channels and forcing electromechanical component suppliers to integrate humidity sensors and motor controls into unified subsystems for space-constrained residential installations.
Growth Catalysts
- China's GB Standards for Energy Efficiency:MIIT mandates for wireless-connected appliances are accelerating certified product rollouts in tier-one cities where compliance unlocks developer procurement contracts.
- Motorized Lifting Systems:Advancements in compact DC motor design are reducing unit depth requirements, enabling wall-mounted installation in apartments under 50 square meters.
- Property Developer Specifications:Pre-installation in new residential builds across Shenzhen and Shanghai is creating captive demand channels before individual consumer purchase decisions occur.
Market Restraints
- Aluminum and Copper Input Volatility:Heating element and frame material costs fluctuate with commodity markets, compressing margins for mid-tier manufacturers without long-term supplier contracts.
- Regional Supply Concentration:Motorized component production clusters in Guangdong province, creating vulnerability to localized logistics disruptions or energy rationing events.
- Technical Limitation in Humidity Sensing:Consumer-grade moisture detection accuracy degrades in high-ambient-humidity environments, limiting automated cycle optimization reliability.
Strategic Opportunities
- India's BIS Certification Gap:Unaccredited import barriers create first-mover advantage for manufacturers establishing local testing partnerships before enforcement tightens.
- Climate-Control Convergence:Integration of HVAC-linked humidity management with existing residential cooling systems opens premium positioning in Southeast Asian markets.
- Property Management Channel:Direct bulk procurement by rental housing operators bypasses retail markup structures and secures multi-year replacement revenue.
Industry Challenges
- Embedded Systems Engineering Talent:Firmware development for IoT connectivity stacks competes with broader consumer electronics hiring pools, elongating product development timelines.
- Interoperability Certification Delays:Protocol fragmentation across Xiaomi, Huawei, and independent smart home ecosystems requires redundant testing expenditures for multi-platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Drying Racks Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Racks, Adjustable Racks, Wall-Mounted Racks, Portable Racks Technology: Smart Sensors, IoT Integration, Climate Control, Automated Drying End User: Residential Users, Commercial Users, Laundry Services, Hospitality Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Xiaomi, Panasonic, Philips, JOMOO, HOTATA, L Best, Varlux, Orlant, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Drying Racks Market Evolving Landscape
Edge computing architectures and sensor fusion are displacing cloud-dependent drying optimization, enabling real-time humidity response without latency-dependent connectivity. This shift is compressing the value capture of platform-dependent hardware vendors.
Sensor fusion technology combining load-weight detection with ambient humidity measurement is decentralizing drying cycle control from centralized cloud platforms to on-device processing. Residential buyers in bandwidth-constrained buildings are prioritizing units with local decision-making capability. This architecture is reducing subscription dependency and enabling offline functionality during network outages.
China's MIIT is tightening GB standard enforcement for wireless transmission power and standby energy consumption in connected appliances. Manufacturers are redesigning RF modules and sleep-state circuitry to maintain market access. Export-oriented suppliers are dual-certifying products to satisfy both domestic compliance and EU Ecodesign Directive requirements for European-bound shipments.
Developer-direct procurement is displacing retail channel dominance for initial equipment installation in new residential construction. Property technology integrators in Shanghai and Shenzhen are specifying smart drying racks as standard infrastructure in premium apartment offerings. This channel compression is reducing brand visibility requirements while intensifying price negotiation leverage among volume buyers.
Smart Drying Racks Market Segmentation
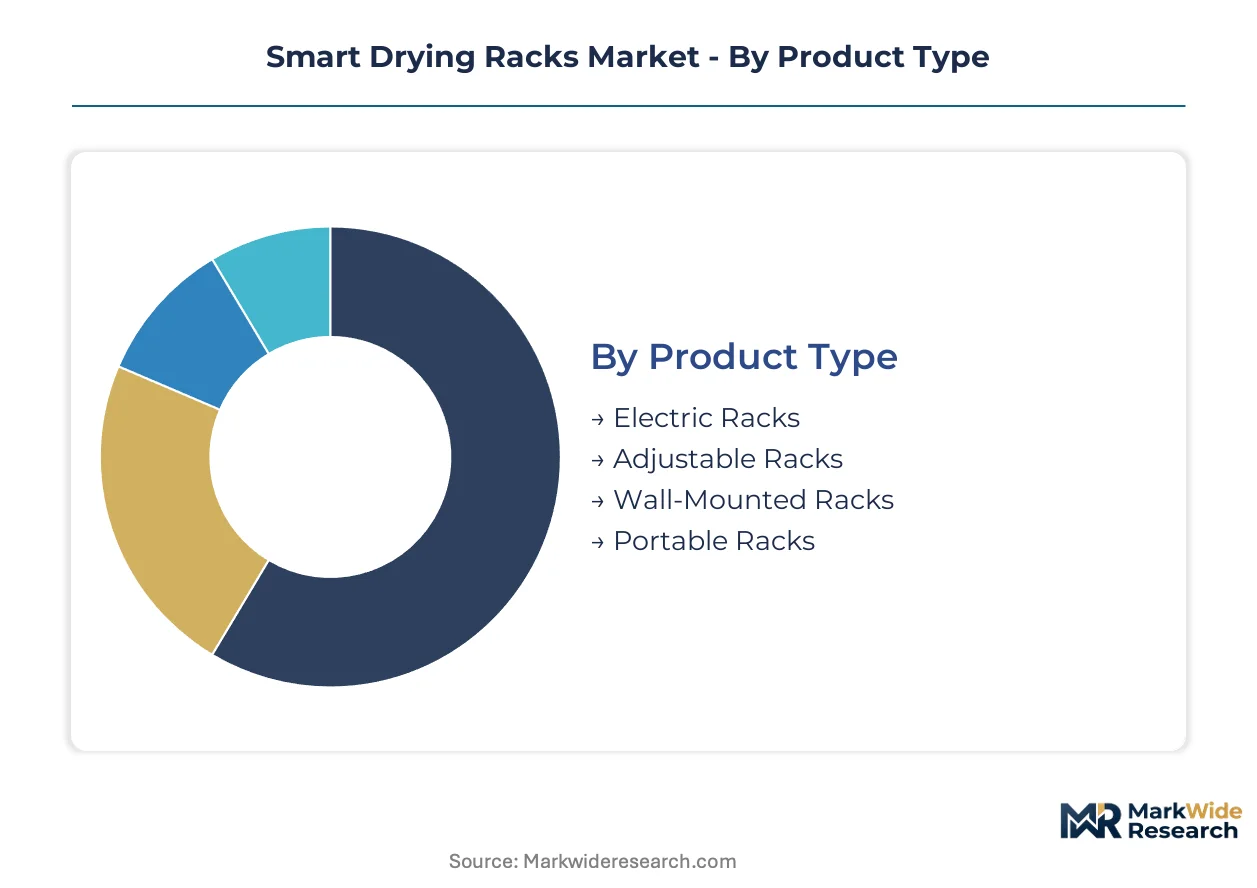
Smart drying rack segmentation reflects divergent compliance burdens across electromechanical complexity tiers. GB standards from MIIT apply selectively to connected variants, while simpler mechanical units face lighter certification loads.
Product Type:
MIIT's GB standards for wireless connectivity and energy efficiency apply most stringently to electric and wall-mounted variants with embedded heating elements, while portable mechanical racks bypass RF transmission certification entirely.
- Electric Racks:Integrated heating elements with thermostatic control and motorized deployment mechanisms. Demand concentrates in Shanghai and Shenzhen apartment complexes where property developers specify pre-installed infrastructure to meet smart building certification requirements.
- Wall-Mounted Racks:Permanent installation with load-bearing aluminum frames and compact DC motor systems. Shenzhen residential towers under 50 square meters drive specification volume, as space constraints eliminate freestanding alternatives.
- Adjustable Racks:Manual height and width modification without motorized components.
- Portable Racks:Collapsible lightweight frames for temporary deployment.
Leading the category by volume: Wall-Mounted Racks. Expanding most quickly: Electric Racks with integrated climate control modules.
Technology:
Technology tiers stratify sharply by firmware development cost and interoperability testing burden, with IoT-enabled units requiring redundant certification across Xiaomi, Huawei, and independent smart home ecosystems.
- Climate Control:HVAC-linked humidity management with real-time ambient moisture sensing and automated airflow modulation. Southeast Asian residential cooling system integration drives premium positioning in bandwidth-constrained buildings where local edge processing eliminates cloud dependency.
- IoT Integration:App-based scheduling with multi-platform smart home protocol compatibility. India's BIS certification requirements for imported connected appliances create compliance barriers that favor manufacturers with established local testing partnerships.
- Smart Sensors:Load-weight detection combined with ambient humidity measurement for cycle optimization.
- Automated Drying:Timer-based motor control with basic moisture detection.
Dominating current installed value: Climate Control. Steepest expansion trajectory: IoT Integration as property developer specifications mandate connected infrastructure.
End User:
End user segments diverge by procurement channel structure, with residential buyers reached through retail and developer-direct paths while commercial accounts demand bulk pricing and multi-year service agreements.
- Residential Users:Individual apartment dwellers and homeowners purchasing through retail channels or receiving pre-installed units in new construction. Tier-one Chinese cities concentrate demand where space constraints and smart home penetration are most acute.
- Commercial Users:Multi-unit housing operators and corporate facilities managers procuring through direct bulk contracts. Rental housing operators in Shenzhen bypass retail markup structures to secure captive replacement revenue streams.
- Laundry Services:Professional wash-and-fold operations with high-throughput drying requirements.
- Hospitality:Hotels and serviced apartments with guest-facing amenity specifications.
Highest volume segment: Residential Users. Fastest channel shift: Commercial Users adopting property management procurement models.
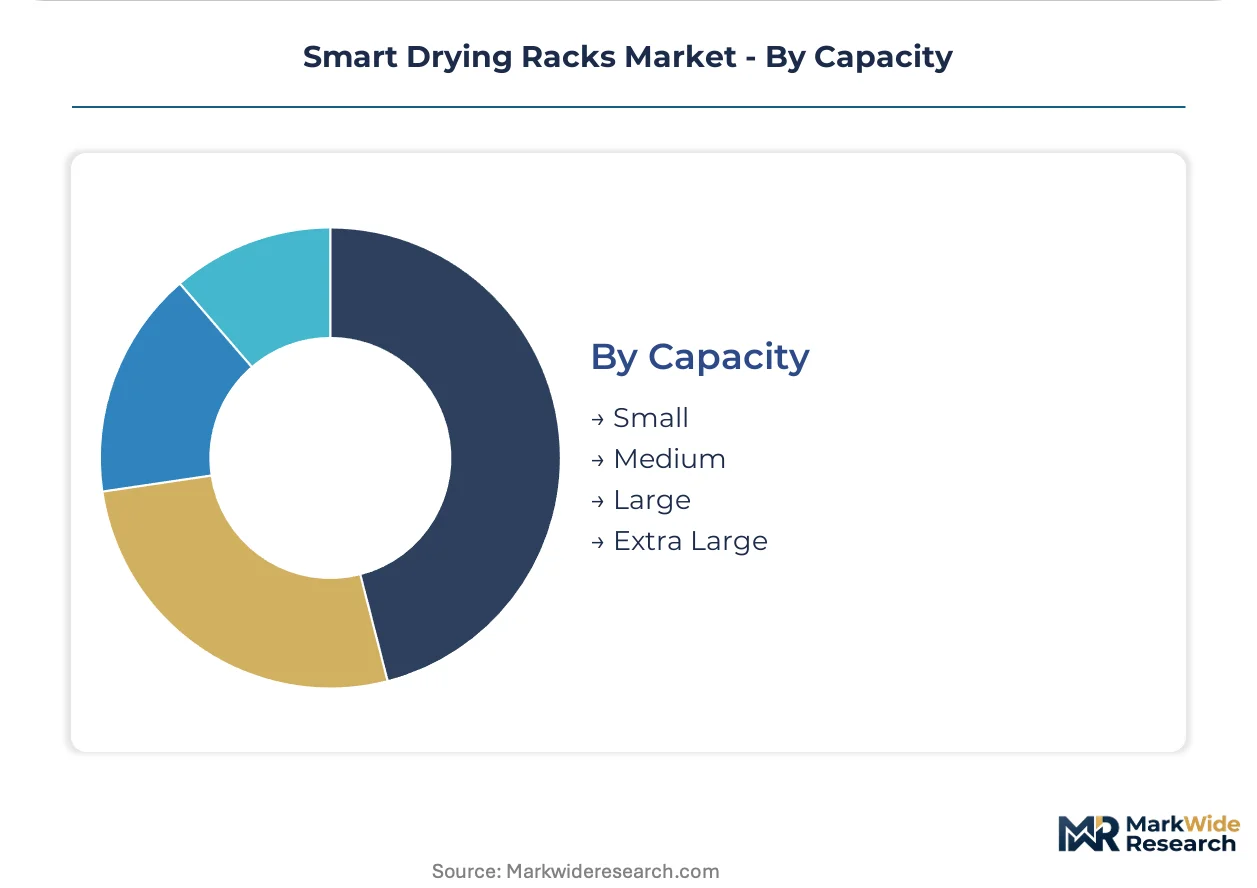
Capacity:
Capacity tiers map directly to installation feasibility in constrained floor plans, with smaller units commanding disproportionate development attention for urban infill applications.
- Small:Under 8 kilogram load capacity with sub-60-centimeter width for studio apartments.
- Medium:8-12 kilogram capacity serving standard two-bedroom apartments.
- Large:12-16 kilogram capacity for family units with bulk laundry requirements.
- Extra Large:Over 16 kilogram capacity for commercial throughput or extended-family households.
Volume leader: Medium capacity. Gaining share fastest: Small capacity as micro-apartment construction accelerates in Guangdong province.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the dominant share of smart drying rack demand, with tier-one cities driving specification volume through property developer mandates and space-constrained residential construction.
China
Shanghai and Shenzhen apartment complexes account for the steepest demand concentration as developers pre-install motorized wall-mounted units in micro-apartments under 50 square meters. MIIT's GB standards for wireless transmission power and standby energy consumption force RF module redesigns for market access. Guangdong province hosts the densest cluster of motorized component suppliers, where DC motor production serves both domestic installation and export assembly.
India
Mumbai and Bangalore residential towers are adopting smart home infrastructure at accelerating rates, creating pull-through for connected drying solutions in premium developments. BIS certification mandates for imported motorized appliances erect compliance barriers that favor manufacturers with established local testing partnerships. Tamil Nadu's electronics manufacturing corridor is attracting assembly investment from suppliers seeking to bypass import duty structures.
Japan
Tokyo's compact urban dwellings sustain demand for space-optimized wall-mounted systems with integrated humidity management. METI energy efficiency guidelines for home appliances shape product architecture, particularly for standby power consumption limits. Osaka-Kansai manufacturing clusters specialize in precision motor controls and sensor modules for domestic brands.
Germany
Berlin and Munich rental housing operators are specifying climate-integrated drying systems as standard amenities in new-build efficiency apartments. The EU Ecodesign Directive and CE marking requirements govern product architecture for connected variants entering the single market. Bavaria's industrial automation sector supplies motor control subsystems to appliance manufacturers serving Central European distribution.
South Korea
Seoul Capital Area apartment reconstruction projects are embedding smart home infrastructure at scale, including networked drying fixtures in premium units. MFDS electrical safety standards and KC certification for wireless devices regulate import compliance. Busan-Ulsan manufacturing bases produce compact heating elements and aluminum extrusion frames for regional supply.
Smart Drying Racks Market Competitive Landscape
Chinese producers anchor the volume tier through integrated manufacturing scale and domestic platform ecosystem access; Japanese and Korean specialists hold premium positioning through climate-control engineering heritage. The vendor base stratifies across three tiers: platform-integrated ecosystem players, specialized electromechanical fabricators, and HVAC-extended appliance manufacturers. Dominant competitive moves include developer-direct procurement contracting and multi-protocol interoperability certification to capture smart home platform consolidation.
Within the platform-integrated tier, Xiaomi exemplifies ecosystem bundling strategy, leveraging IoT infrastructure to capture residential specification channels. HOTATA occupies a position among specialized electromechanical fabricators, representing manufacturing-scale concentration in motorized lifting systems. Panasonic anchors the HVAC-extension archetype, extending climate-control expertise into humidity-managed drying solutions for premium residential segments.
| Leading Market Players |
|---|
| Xiaomi |
| Panasonic |
| Philips |
| JOMOO |
| HOTATA |
| L Best |
| Varlux |
| Orlant |
| LG Electronics |
| Others |
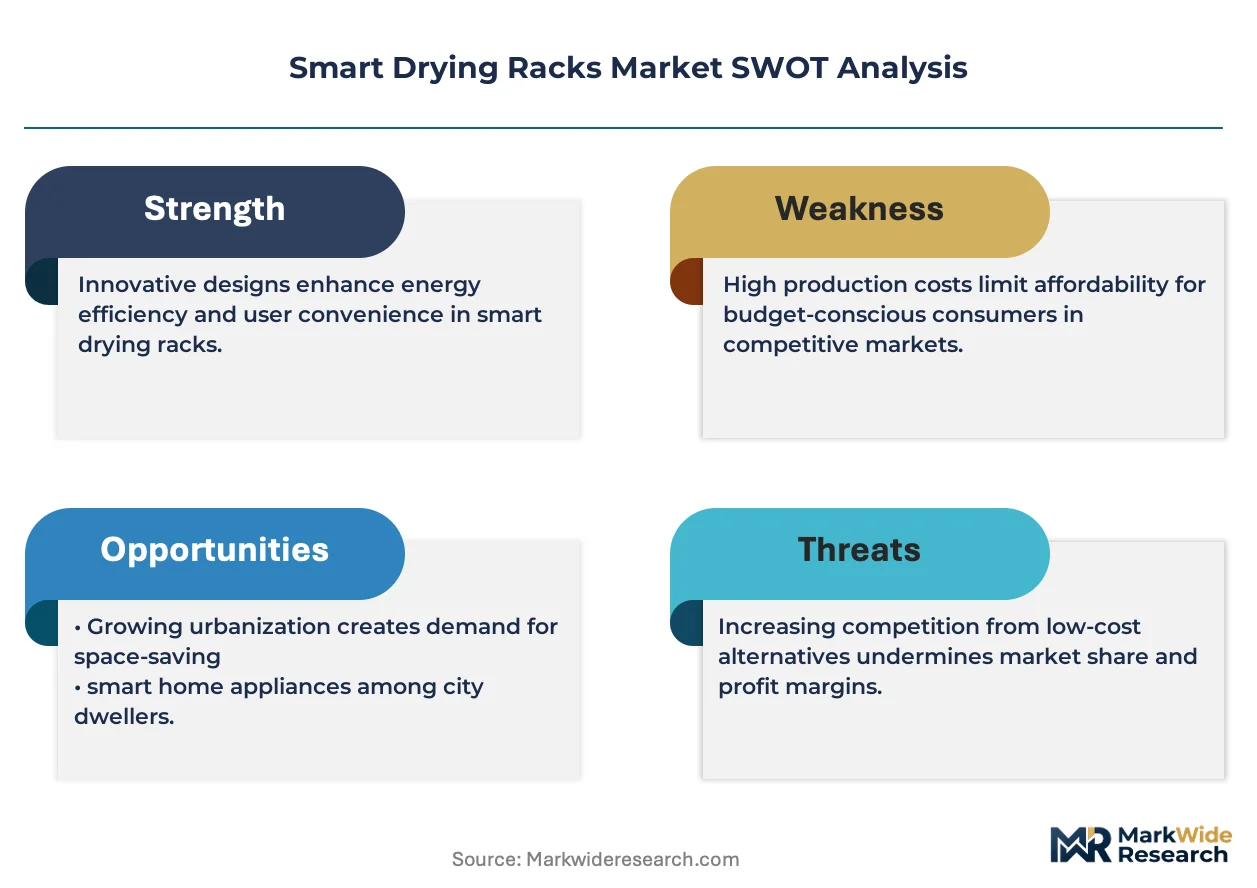
Value Network & Pricing Analysis
Aluminum extrusion and copper heating element costs cascade through three distinct pricing tiers as Guangdong-based component suppliers negotiate annual contracts with Shenzhen and Shanghai property developers. DC motor assemblies and RF connectivity modules concentrate margin capture at the subsystem level, forcing finished goods manufacturers to absorb commodity volatility or surrender share to integrated platform vendors.
Pricing Analysis
Volume leaders in wall-mounted electric racks sacrifice margin for developer-direct procurement scale, while climate-control-enabled units with HVAC integration command premium positioning through differentiated humidity management. Price differentiation hinges on MIIT GB certification tier and multi-protocol smart home interoperability, with uncertified portable mechanical racks facing acute price erosion as commodity aluminum costs fluctuate. Property management buyers exhibit lowest price sensitivity due to multi-year replacement revenue bundling, whereas individual retail purchasers in tier-two cities drive aggressive tier-down trading.
Supply Chain Analysis
Regional distribution centers in Guangdong province anchor hub-and-spoke patterns serving domestic installation crews and export assembly lines across Southeast Asia. DC motor production draws from precision manufacturing clusters in Japan and South Korea, while aluminum frame extrusion rests on captive smelter relationships in China's southwestern provinces. Single-source vulnerability concentrates in Guangdong's motorized component ecosystem, where energy rationing events disrupt just-in-time delivery to Shenzhen residential tower projects. Distribution runs through property technology integrators and developer procurement offices, compressing traditional retail channel participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as subsystem suppliers capture margin through unified humidity sensor and motor control modules, compelling finished goods manufacturers to secure captive component supply or surrender pricing power to platform-integrated competitors.
For Market Incumbents: Acquire sensor fusion engineering teams to internalize edge-computing firmware development and reduce dependency on fragmented IoT connectivity stacks. Consolidate position through backward integration into DC motor manufacturing in Guangdong, countering the threat of commodity aluminum cost spikes and single-source component vulnerability. Secure multi-protocol certification across Xiaomi, Huawei, and independent smart home ecosystems before interoperability testing expenditures escalate. For New Entrants and Emerging Players: Edge-computing architectures with local humidity processing offer a technology-first wedge into bandwidth-constrained residential buildings where cloud-dependent units fail. Target India's BIS certification gap by establishing Tamil Nadu testing partnerships before enforcement tightens, leveraging white-space availability in Mumbai and Bangalore premium developments. Pursue property management channel entry with direct bulk procurement pitches to rental housing operators seeking captive replacement revenue. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized electromechanical fabricators with Guangdong manufacturing scale and established MIIT compliance records. Long-term viability centers on climate-control convergence with HVAC systems, positioning humidity-management engineering heritage as durable competitive moat. Watch for inflection signals in developer-direct procurement volume across Shenzhen and Shanghai new-build permits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captures margin from DC motor suppliers in Guangdong while reducing single-source disruption exposure. |
| Multi-Protocol Smart Home Certification | Unlocks developer procurement contracts requiring Xiaomi, Huawei, and ecosystem interoperability. |
| Climate-Control HVAC Convergence | Extends premium positioning into Southeast Asian markets with integrated humidity management. |
| India BIS Testing Partnership | Establishes compliance infrastructure before import barriers tighten for motorized connected appliances. |
| Property Management Channel Direct Sales | Bypasses retail markup compression while securing multi-year replacement revenue streams. |
Research Methodology
Document review covered MIIT GB standard filings, EU Ecodesign Directive compliance databases, and BIS certification registries, complemented by interviews with property technology integrators, smart home platform engineers, and electromechanical component procurement managers. Secondary validation drew from customs trade data, SEC filings of listed appliance manufacturers, and regional construction permit databases. Bottom-up demand modeling across tier-one Chinese cities was triangulated against top-down smart home penetration forecasts.
Installed value projections and segment-level CAGRs were derived through econometric modeling of property developer specification rates, motorized component cost curves, and certification burden trajectories across the analysis window. Segmentation dimensions included product type electromechanical complexity, technology firmware development tier, end-user procurement channel structure, and capacity installation feasibility. Climate-control integration adoption and edge-computing architecture displacement were incorporated as technology transition inputs.
Several conditions sit outside the modeled scope, including abrupt MIIT regulatory revisions, sustained aluminum commodity price spikes exceeding historical volatility bands, and smart home platform protocol consolidation to single dominant standards. Forecasts reflect assumptions regarding continued urbanization density in tier-one Chinese cities and property developer smart infrastructure mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Toilet Paper Market
Household Items
Global Electric Scissors Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Global Humidifier Market
Household Items
Tablet Tissue Paper Market
Household Items
Smart Pool Skimmer Market
Household Items
Trash Can Market
Household Items
Europe Handheld Fans Market
Household Items
Electric Air Freshener Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market
Household Items
Knife Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Leaf Blower Market
Household Items
US Digital Showers Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Stainless Steel Thermos Cup Market