
 Gel Warmers Market | 2026-2036
Gel Warmers Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Warmers Market Foresight
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape into qualified suppliers and marginal participants. Parker Laboratories leverages its vertically integrated manufacturing to sustain consistent output for hospital networks. CIVCO Medical Solutions anchors its position through specialized thermal regulation technology for imaging suites. AliMed competes on channel density, with broad distribution through medical supply catalogs and direct sales infrastructure.
Gel warmers are temperature-controlled devices designed to heat conductive ultrasound gel to approximately body temperature, typically employing thermostatic electric heating elements or microwaveable thermal mass materials to prevent patient discomfort and acoustic impedance mismatch during diagnostic imaging. The primary commercial purpose centers on eliminating cold-shock response during ultrasound procedures while maintaining gel viscosity for optimal sound wave transmission. Stationary units dominate hospital procurement budgets due to higher throughput requirements, while portable warmers represent the fastest-expanding category as point-of-care ultrasound migrates beyond radiology departments into emergency medicine and sports facilities. Electric gel warmers command premium positioning through precise digital temperature control, whereas microwaveable alternatives occupy cost-sensitive segments in home care and smaller clinics.
FDA 510(k) clearance requirements for thermal medical devices shape product development timelines and capital allocation for US market entrants, while ISO 10993 biocompatibility standards govern material selection for gel-contact surfaces. The EU Medical Device Regulation imposes additional clinical evaluation obligations on manufacturers seeking CE marking for European distribution. Stakeholders must monitor evolving state-level energy efficiency mandates that could restrict electric warmer specifications in California and New York, and assess whether backward integration into heating element production offers sustainable margin protection against component cost volatility.
Market Dynamics
ISO 13485 certification requirements are concentrating procurement authority among qualified suppliers while marginalizing uncertified manufacturers, reshaping competitive access to hospital networks and imaging center contracts.
Growth Catalysts
- Point-of-care ultrasound expansion:Emergency medicine departments and sports medicine facilities are adopting portable gel warmers to support bedside imaging protocols outside traditional radiology suites.
- FDA 510(k) pathway maturation:Clearance frameworks for thermal medical devices have stabilized, reducing regulatory uncertainty for electric warmer innovations targeting hospital procurement cycles.
- Germany outpatient imaging investment:Thermal management infrastructure upgrades across ambulatory diagnostic centers are driving replacement demand for precision-controlled warming systems.
Market Restraints
- Heating element cost volatility:Ceramic resistor and PTC thermistor supply chains face price pressure from rare earth mineral concentration in Chinese processing facilities.
- EU MDR clinical evaluation burdens:European Medical Device Regulation requirements for CE marking have extended product launch timelines and inflated compliance expenditures for thermal device categories.
- Microwaveable gel warmer substitution:Low-cost thermal mass alternatives compete on upfront capital avoidance, particularly in home care and small clinic segments with limited procedure volumes.
Strategic Opportunities
- India diagnostic infrastructure buildout:Government health scheme expansion into tier-2 and tier-3 cities creates first-mover positioning for affordable electric warmer distribution through medical device importers.
- Battery-powered portable convergence:Lithium-ion cell density improvements combined with low-power heating element design enable cordless operation for field ultrasound applications.
- California energy efficiency mandates:Title 20 appliance standards for medical equipment create regulatory tailwind for smart thermostat integration and standby power reduction technologies.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing protocols for gel-contact surface materials extend product development cycles by 8-14 months for new polymer formulations.
- Legacy system integration friction:Digital temperature logging capabilities in new electric warmers require API compatibility with hospital information systems and radiology workflow software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Warmers Market |
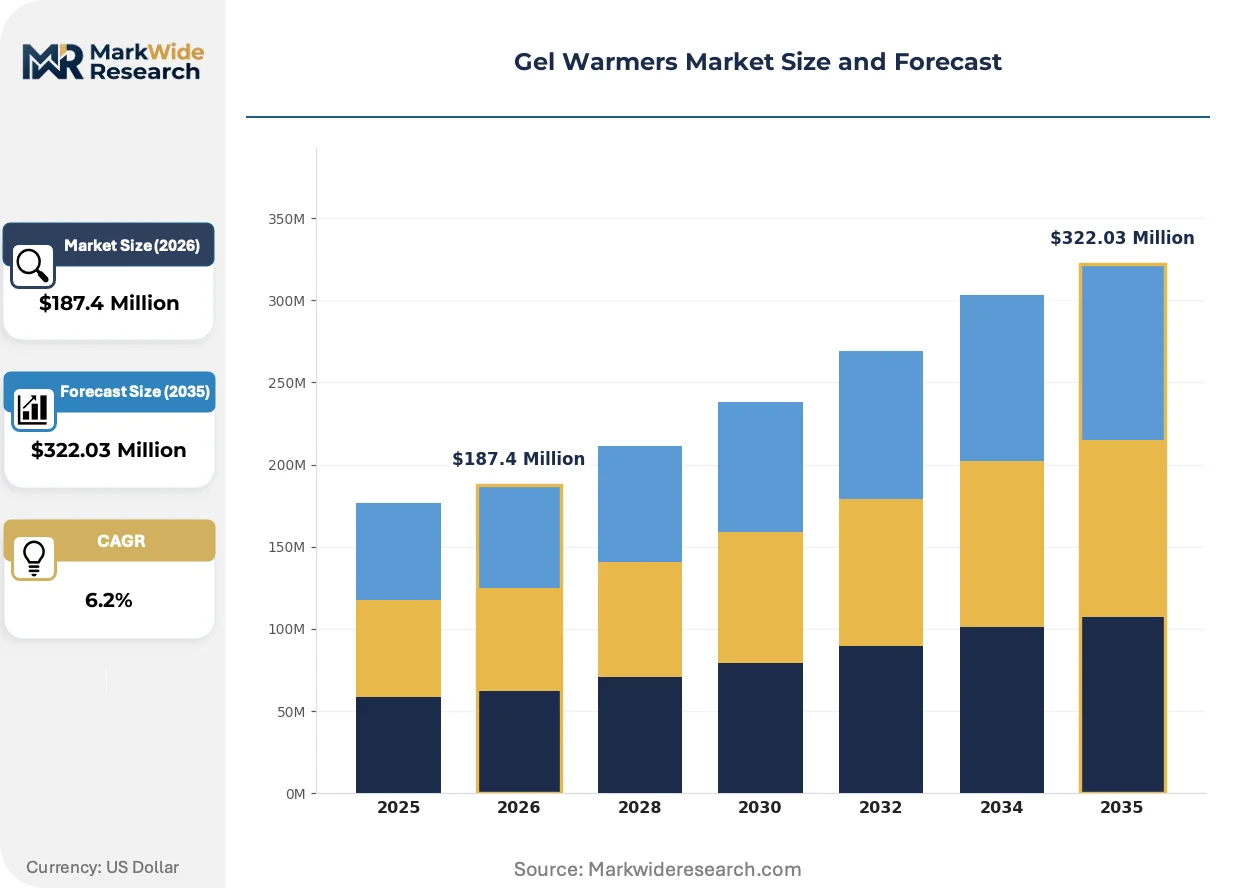
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $322.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Warmers, Stationary Units, Electric Gel Warmers, Microwaveable Warmers End User: Hospitals, Clinics, Home Care, Sports Facilities Distribution Channel: Online Retailers, Medical Supply Stores, Direct Sales, Distributors Application: Physical Therapy, Sports Medicine, Aesthetic Treatments, Pain Relief |
| Companies Covered | Parker Laboratories, Softgel International, CIVCO Medical Solutions, AliMed, Imotek, Medline, Cadmet, Vermed, Ideal Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Warmers Market Shifts & Advancements
Silicon-controlled rectifier and solid-state relay technologies are replacing electromechanical thermostats, enabling precise temperature modulation that reduces thermal overshoot and improves patient safety profiles.
Silicone-based heating membranes with embedded thermistor arrays are displacing traditional aluminum-block heating elements in premium electric warmer segments. Outpatient imaging centers and hospital ultrasound departments are adopting these flexible substrates for faster thermal response and uniform gel temperature distribution. This displacement is compressing service intervals and reducing warranty claim rates for manufacturers investing in membrane production capability.
EU Medical Device Regulation biocompatibility requirements for patient-contacting surfaces have tightened material selection protocols across European supply chains. Manufacturers must now document clinical evaluation data for gel-contact polymers under MDR Annex XIV, elevating documentation costs for CE-marked products. German and French notified bodies are enforcing these provisions most stringently, driving consolidation toward larger manufacturers with dedicated regulatory affairs functions.
Hospital procurement departments are consolidating supplier relationships through group purchasing organization frameworks that bundle gel warmers with broader ultrasound accessory contracts. Independent distributors and catalog-based medical supply channels face margin compression as IDN-level contracting centralizes purchasing authority. This concentration is most visible in United States health system networks exceeding 50 hospital facilities, where standardization incentives override brand preference at individual department levels.
Gel Warmers Market Segmentation
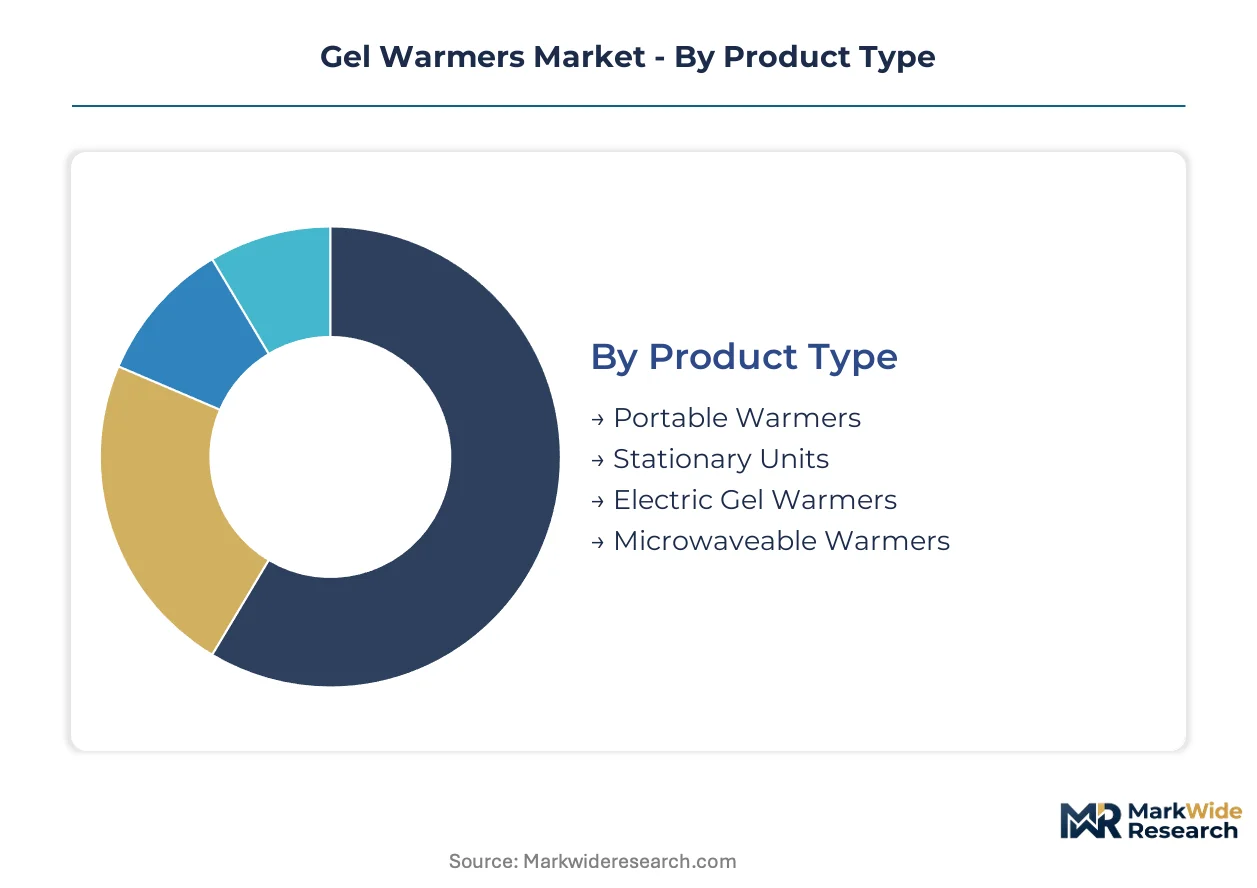
Gel warmer procurement flows through distinct channel pathways shaped by volume scale, regulatory requirements, and end-user technical sophistication. Segment boundaries are hardening as ISO 13485 certification requirements filter supplier access to institutional buyers.
Product Type:
Channel concentration varies sharply across product formats, with hospital procurement favoring certified stationary units while portable formats migrate through distributor and direct-sales channels toward point-of-care settings.
- Stationary Units:These thermostatically controlled cabinet systems employ aluminum-block or silicone-membrane heating elements with digital temperature displays. Hospital ultrasound departments and outpatient imaging centers in Germany and the United States concentrate replacement demand here, driven by throughput requirements and FDA 510(k) compliance mandates for thermal medical devices.
- Portable Warmers:Battery-compatible and AC-powered mobile units serve emergency medicine departments and sports facilities. Demand is climbing fastest in United States health systems expanding bedside ultrasound protocols beyond radiology suites, though heating element cost volatility constrains margin expansion.
- Electric Gel Warmers:Precision-controlled units with solid-state relay technology dominate premium positioning through medical supply catalogs and GPO frameworks.
- Microwaveable Warmers:Thermal mass alternatives bypass electrical infrastructure requirements, flowing primarily through online retailers toward home care segments and small clinics with limited procedure volumes.
Stationary units dominate installed base. Portable warmers are where expansion concentrates most steeply.
End User:
Customer type determines specification requirements, with institutional buyers demanding digital logging capabilities and home care segments prioritizing capital avoidance.
- Hospitals:IDN-level contracting centralizes procurement for ultrasound departments, emergency medicine, and operating suites. United States health networks exceeding 50 facilities drive standardization incentives, with FDA device classification requirements and HIPAA-aligned data logging specifications shaping vendor selection.
- Clinics:Ambulatory diagnostic centers, particularly Germany's outpatient imaging infrastructure, prioritize CE-marked systems with MDR-compliant biocompatibility documentation for gel-contact surfaces.
- Sports Facilities:Athletic training departments and field medicine operations favor cordless portable units, with lithium-ion battery density improvements enabling diagnostic imaging outside fixed clinical infrastructure.
- Home Care:Cost-sensitive demand concentrates in microwaveable formats through online retail channels, with limited procedure volumes suppressing electric warmer adoption.
Hospitals anchor revenue concentration. Sports facilities represent the steepest expansion trajectory among customer types.
Distribution Channel:
Channel power is consolidating as group purchasing organizations bundle gel warmers with broader ultrasound accessory contracts, compressing independent distributor margins.
- Direct Sales:Manufacturer field organizations serve hospital networks and IDNs requiring API integration with radiology workflow software and hospital information systems. This channel captures premium pricing for systems with digital temperature logging capabilities.
- Distributors:Regional medical device distributors retain relevance in tier-2 and tier-3 city penetration, particularly for India's diagnostic infrastructure buildout under government health scheme expansion.
- Medical Supply Stores:Catalog-based channels including AliMed's broad distribution infrastructure serve smaller clinics and outpatient facilities with standardized product configurations.
- Online Retailers:E-commerce platforms concentrate microwaveable warmer volume toward home care segments, with price transparency intensifying competition in unsophisticated buyer segments.
Direct sales commands margin leadership. Online retailers are gaining share fastest in absolute volume terms.
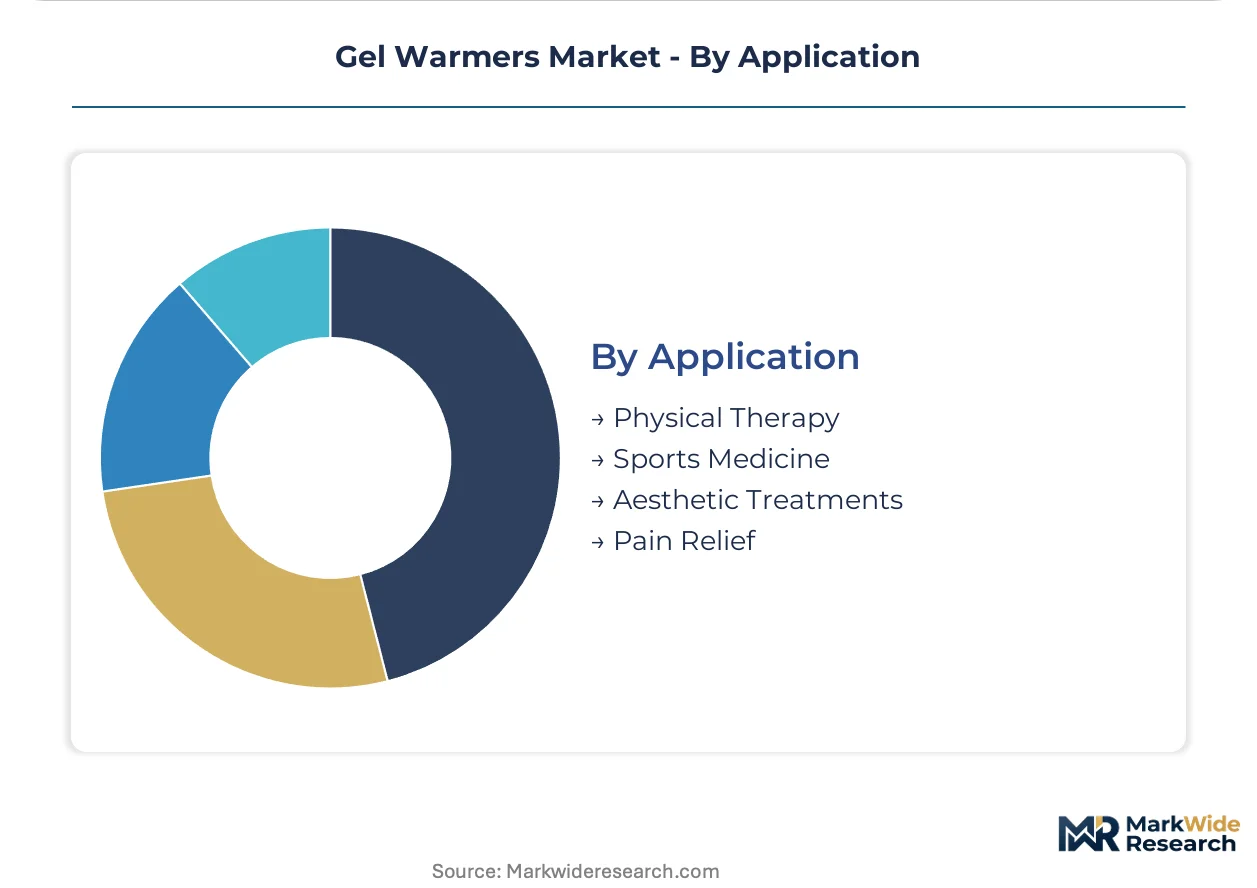
Application:
Use-case specificity determines thermal performance requirements and regulatory exposure, with diagnostic imaging applications facing stricter device classification than therapeutic warming.
- Sports Medicine:Sideline and training room applications demand rapid thermal response and portability. United States collegiate and professional athletic programs are expanding portable warmer procurement as point-of-care ultrasound protocols migrate beyond traditional clinical settings.
- Physical Therapy:Rehabilitation clinics utilize gel warmers for therapeutic ultrasound applications, with ISO 10993 biocompatibility standards governing gel-contact surface materials extending product development timelines for new polymer formulations.
- Pain Relief:Chronic pain management applications in outpatient settings favor cost-optimized electric units with basic thermostatic control, with procurement flowing through medical supply distributors.
- Aesthetic Treatments:Medical spa and cosmetic clinic demand concentrates in compact countertop units with aesthetic housing designs, typically sourced through specialized aesthetic equipment distributors rather than mainstream medical supply channels.
Physical therapy anchors historical installed base. Sports medicine applications are expanding most quickly as portable technology enables field deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance frameworks and EU MDR compliance mandates are redirecting procurement flows toward certified suppliers in established medical device manufacturing clusters. Hospital network consolidation and outpatient imaging expansion are reshaping demand geography across North America, Europe, and Asia-Pacific.
United States
Hospital networks exceeding 50 facilities are centralizing gel warmer procurement through IDN-level contracts that bundle ultrasound accessories. FDA device classification requirements for thermal medical equipment are tightening compliance burdens for manufacturers seeking 510(k) clearance. The Greater Boston and Pacific Northwest clusters concentrate imaging technology R&D, with Massachusetts General Brigham and Providence St. Joseph Health driving standardization protocols.
Germany
Outpatient imaging centers across Bavaria and North Rhine-Westphalia are upgrading thermal management infrastructure under ambulatory diagnostic investment programs. EU Medical Device Regulation biocompatibility requirements for patient-contacting surfaces have extended CE marking timelines for gel-contact polymer documentation. The Munich-Stuttgart medical technology corridor hosts concentrated notified body activity, with TÜV SÜD enforcing MDR Annex XIV provisions stringently.
India
Government health scheme expansion into tier-2 and tier-3 cities is creating first-mover positioning for affordable electric warmer distribution. CDSCO medical device registration requirements are formalizing quality standards for thermal equipment imports. The Maharashtra-Gujarat pharmaceutical and medical device manufacturing belt, anchored by Mumbai and Ahmedabad, is absorbing diagnostic infrastructure buildout under Ayushman Bharat.
China
NMPA Class II medical device registration is standardizing thermal equipment safety protocols for domestic and imported gel warmers. Dual carbon goals are pressuring electric warmer manufacturers toward energy-efficient heating element designs. The Yangtze River Delta medical device cluster, centered on Shanghai and Suzhou, is consolidating contract manufacturing for export-oriented thermal equipment.
Japan
PMDA quality management system requirements are filtering market access to ISO 13485-certified suppliers for hospital procurement. METI energy efficiency standards are accelerating standby power reduction technologies in electric warmer specifications. The Kanto region, with Tokyo and Saitama prefectures, concentrates diagnostic imaging equipment demand from university hospitals and municipal medical centers.
Gel Warmers Market Competitive Landscape
Player mix skews toward vertically integrated medical device specialists and catalog-based distribution platforms. The vendor base separates into three tiers: ISO 13485-certified manufacturers with direct hospital relationships, regional distributors serving clinic networks, and cost-optimized suppliers penetrating home care through online channels. Dominant competitive moves include backward integration into heating element production and strategic partnerships with ultrasound equipment OEMs for bundled accessory contracts.
Among US-based medical device fabricators, Parker Laboratories and CIVCO Medical Solutions exemplify the certified-manufacturer archetype with concentrated hospital network penetration. AliMed occupies a position within the catalog-distribution tier, leveraging broad medical supply channel density to serve smaller clinics and outpatient facilities. These three anchors illustrate how regulatory certification and channel configuration determine competitive access to institutional procurement budgets.
| Leading Market Players |
|---|
| Parker Laboratories |
| Softgel International |
| CIVCO Medical Solutions |
| AliMed |
| Imotek |
| Medline |
| Cadmet |
| Vermed |
| Ideal Products |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with ceramic resistor and PTC thermistor suppliers lock in heating element access for ISO 13485-certified manufacturers while anchoring unit cost visibility across volatile rare earth mineral markets. These arrangements concentrate procurement power among vertically integrated players in the United States and Germany, marginalizing smaller fabricators exposed to spot-market component pricing.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared electric units and uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility documentation depth and digital logging capability integration. Cost compression in the portable segment is intensifying because lithium-ion battery density improvements attract new entrants with aggressive hardware pricing. Home care buyers exhibit highest price sensitivity, while hospital IDNs prioritize total cost of ownership over upfront capital avoidance.
Supply Chain Analysis
Strategic stockpiling of heating elements dominates procurement strategy among certified manufacturers facing rare earth mineral concentration in Chinese processing facilities. Component sourcing draws from China for ceramic resistors, Japan for precision thermistors, and Germany for silicone-membrane substrates. Single-source vulnerability in PTC thermistor supply chains creates exposure to export restriction shocks. Distribution runs through group purchasing organization frameworks that bundle gel warmers with ultrasound accessory contracts, compressing independent distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from preventive maintenance contracts and calibration services is expanding faster than hardware sales as hospital procurement committees prioritize uptime guarantees over capital expenditure minimization.
For Market Incumbents: Shield installed base relationships through backward integration into silicone-membrane heating element production, reducing exposure to rare earth mineral price volatility. Deepen API compatibility investments with radiology workflow software vendors to raise switching costs for hospital IDNs. The microwaveable warmer substitution threat in home care segments demands selective price repositioning rather than full portfolio engagement. For New Entrants and Emerging Players: Differentiate on battery-powered cordless architecture targeting United States sports medicine and field ultrasound applications where incumbent coverage remains thin. India's tier-2 and tier-3 diagnostic infrastructure buildout offers the most penetrable geography for affordable electric warmer distribution through CDSCO-registered importer partnerships. Direct sales to athletic training departments bypasses GPO consolidation that blocks hospital channel access. For Investors and Strategic Acquirers: The market sits at a certification-concentration phase that favors ISO 13485-qualified manufacturers with dedicated regulatory affairs functions over catalog distributors facing margin compression. Acquisition targets should demonstrate CE marking completion for EU MDR Annex XIV compliance and established notified body relationships. Watch CDSCO registration acceleration in India as the signal indicating when geographic expansion premiums compress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Element Production | Captive supply of silicone-membrane substrates insulates margins from rare earth mineral volatility concentrated in Chinese processing. |
| FDA 510(k) Clearance Pathway Investment | Device classification compliance unlocks IDN-level contracting with hospital networks exceeding fifty facilities. |
| CE Marking under EU MDR Annex XIV | Notified body relationships with TÜV SÜD enable ambulatory diagnostic center access across Bavaria and North Rhine-Westphalia. |
| API Integration with Radiology Workflow Software | Digital temperature logging compatibility raises switching costs for hospital information system procurement committees. |
| Battery-Powered Portable Development | Lithium-ion cell density improvements enable cordless operation for emergency medicine departments expanding bedside ultrasound protocols. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors at thermal device manufacturers; and secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement contract disclosures, and trade flow records for heating element components. Bottom-up triangulation across product type, end user, and distribution channel segments was cross-checked against top-down market sizing from institutional healthcare expenditure patterns.
Across the analysis window, forecasts incorporate segmentation by product format, customer type, and application use case, with particular weighting for point-of-care ultrasound expansion rates and outpatient imaging infrastructure investment cycles. CAGRs were derived from installed base replacement demand modeling and procedure volume elasticity assumptions. Energy efficiency mandate trajectories in California and New York, plus CDSCO registration formalization in India, served as scenario inputs.
The analysis sits within stated boundaries; outcomes outside sustained hospital network consolidation and stable FDA device classification frameworks would require recalibration. Forecasts reflect assumptions about rare earth mineral supply continuity and MDR enforcement consistency. Revision becomes warranted when heating element cost volatility crosses thresholds that trigger procurement committee preference shifts toward microwaveable alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Vacuum Cleaner Market
Household Items
Bagless Vacuum Cleaner Market
Household Items
Mosquito Repellent Candles Market
Household Items
Smart Faucets Market
Household Items
Replacement Sheets Market
Household Items
Soap Dispenser Market
Household Items
Ceramic Travel Mug Market
Household Items
Deodorizer Bag Market
Household Items
Sanitary Metal Ware Market
Household Items
Mexico Cookware Market
Household Items
Candle Jar Market
Household Items
Non-Stick Cookware Market
Household Items
Range Hood Cleaning Service Market
Household Items
Drinkware Accessories Market
Household Items
Sorting Hampers Market
Household Items
Shower Heads and Systems Market