
 Global Organic Baby Bathing Products Market | 2026-2036
Global Organic Baby Bathing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Baby Bathing Products Market Foresight
Ingredient certification and clean-label verification is reshaping margin pools across the Global Organic Baby Bathing Products Market, pulling value from basic formulation toward third-party validated supply chains. The Honest Company leverages its vertical control over sourcing to sustain premium positioning in North American retail. Burt's Bees Baby anchors its competitive stance through heritage brand equity and pharmacy-channel density. Earth Mama differentiates via herbal-specialist credibility and midwife-endorsed distribution networks.
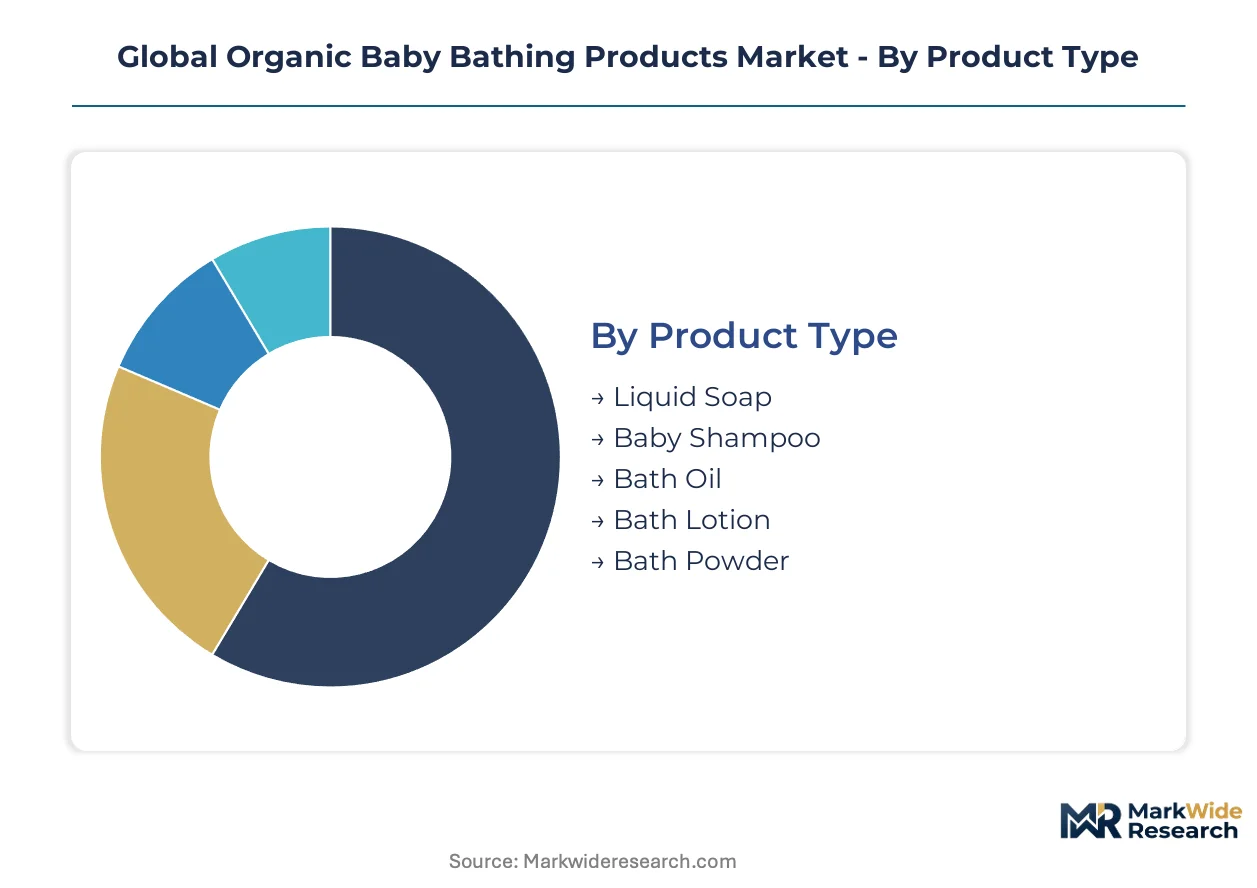
Organic baby bathing products comprise rinse-off and leave-on formulations manufactured without synthetic fragrances, parabens, sulfates, or petrochemical derivatives, typically achieving 95%+ plant-derived content under USDA Organic or COSMOS standards, designed to cleanse and protect infant epidermal barriers with pH-balanced, tear-free chemistry. Liquid soap and baby shampoo command the largest revenue share due to daily-use frequency and caregiver familiarity, while bath oil and bath lotion segments attract the fastest expansion as parents prioritize post-bath moisture retention for eczema-prone infants. Formulations based on herbal extracts and plant-based surfactants capture disproportionate margin pools because certification complexity limits competitor entry.
USDA Organic certification, EU REACH chemical registration requirements, and FDA cosmetic labeling rules collectively elevate compliance costs while filtering out uncredentialed entrants. These frameworks shape demand by converting ingredient transparency from a marketing claim into a mandatory disclosure threshold. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances as the next regulatory frontier that could force additional reformulation cycles.
Market Dynamics
Ingredient certification mandates from FDA, ECHA, and MFDS are compressing formulation cycles and forcing supply chain requalification across the organic baby bathing products sector. This regulatory convergence is redistributing margin pools toward vertically integrated producers with captive organic sourcing.
Growth Catalysts
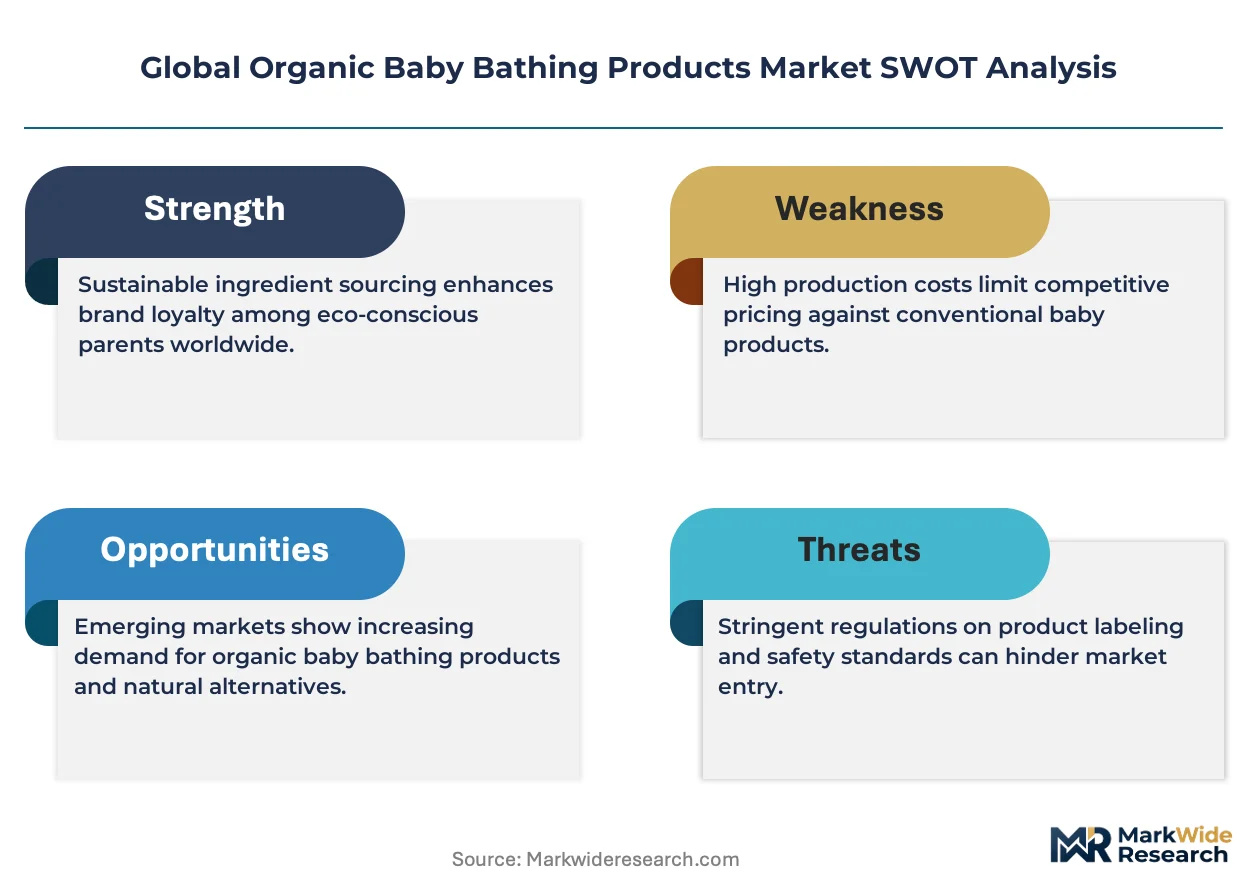
- EU REACH chemical registration:Mandatory disclosure thresholds for cosmetic ingredients accelerate reformulation investments, filtering out uncredentialed entrants and concentrating demand among certified suppliers.
- Gen Z parent cohorts:First-time buyers in the United States and South Korea prioritize USDA Organic and COSMOS-verified products, sustaining premium price acceptance for tear-free, pH-balanced formulations.
- Herbal extract formulations:Plant-derived surfactants with 95%+ organic content capture disproportionate margins because certification complexity limits competitor replication.
Market Restraints
- Organic raw material concentration:Certified plant oil and surfactant supply concentrates in limited geographies, exposing formulators to harvest volatility and input cost spikes.
- USDA Organic compliance timelines:Multi-year certification cycles for new suppliers delay product launches and lock working capital in qualification pipelines.
- Synthetic preservative substitution limits:Technical constraints on natural preservation chemistry shorten shelf life and complicate distribution logistics for mass retail channels.
Strategic Opportunities
- Post-bath moisture retention segment:Bath oils and lotions for eczema-prone infants represent underdeveloped white space with faster expansion potential than saturated shampoo categories.
- German pharmacy channel density:Midwife-endorsed distribution networks offer premium positioning leverage absent from conventional mass retail.
- State-level PFAS restrictions:Emerging prohibitions on per- and polyfluoroalkyl substances create first-mover advantage for brands with pre-qualified fluorine-free supply chains.
Industry Challenges
- Cosmetic chemist specialization gap:Formulation expertise bridging natural ingredient stability and infant epidermal safety remains scarce, inflating R&D payroll costs.
- Multi-jurisdiction label harmonization:Divergent FDA cosmetic rules, EU REACH annex requirements, and MFDS notification procedures force redundant compliance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Baby Bathing Products Market |
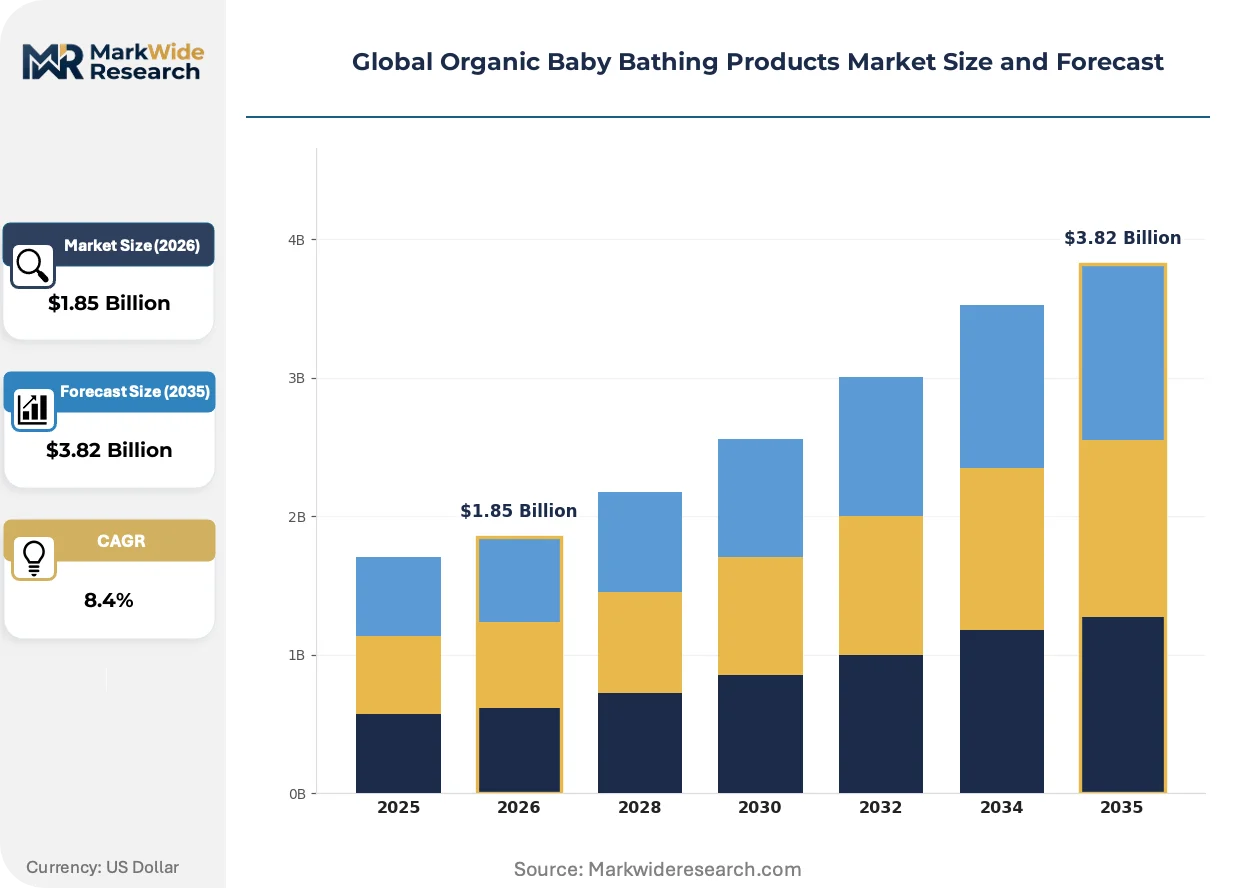
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Baby Shampoo, Bath Oil, Bath Lotion, Bath Powder Formulation: Herbal Extracts, Essential Oils, Plant-Based Surfactants, Natural Emollients, Mineral Enriched Application: Newborn Care, Sensitive Skin Care, Moisturizing Bath, Soothing Bath, Cleansing Bath End User: Newborns, Infants, Toddlers, Caregivers, Pediatricians |
| Companies Covered | The Honest Company, Burt's Bees Baby, Earth Mama, Weleda, Babyganics, California Baby, Green People, Erbaviva, Nature’s Baby Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Baby Bathing Products Market Shifts & Advancements
Blockchain-enabled supply chain verification is digitizing organic baby bathing products, converting certification from static documentation into dynamic, queryable records. This shift is compressing audit cycles and redistributing trust mechanisms from third-party laboratories to distributed ledger architectures.
Near-infrared spectroscopy paired with machine learning is digitizing raw material authentication at receiving docks. Large contract manufacturers in Germany and the United States deploy these systems to verify organic content claims without destructive sampling. The technology is digitizing quality assurance workflows and compressing batch release timelines from days to hours.
REACH annex revisions under ECHA oversight are tightening restrictions on fragrance allergens and endocrine-disrupting compounds in rinse-off cosmetics. Formulators face forced reformulation of legacy surfactant systems and accelerated substitution timelines for preservative packages. Infant-specific product lines bear disproportionate compliance burden due to heightened sensitivity thresholds and pediatric dermatology scrutiny.
Subscription-based replenishment models are displacing conventional retail stocking patterns among millennial parent cohorts. Direct-to-consumer channels in the United States capture recurring revenue streams through auto-ship configurations, while pharmacy networks in South Korea resist this shift. The behavior concentrates demand forecasting risk with brand operators and compresses working capital cycles for inventory-light digital natives.
Global Organic Baby Bathing Products Market Segmentation
Segmentation in organic baby bathing products reveals how formulation chemistry, age-specific skin biology, and certification standards fragment purchasing decisions. Parents navigate distinct product architectures for daily cleansing versus therapeutic skin conditions, with regulatory thresholds varying sharply across infant life stages.
Product Type:
Daily-use frequency and caregiver familiarity span from rinse-off cleansers to leave-on moisture barriers, with eczema management driving premium positioning in specialized formats.
- Liquid Soap:pH-balanced, tear-free surfactant systems with 95%+ plant-derived content under USDA Organic standards. Demand concentrates in United States mass retail for daily bathing routines, constrained by synthetic preservative substitution limits that shorten shelf life.
- Baby Shampoo:Mild cleansing bases excluding sulfates and synthetic fragrances, achieving COSMOS certification for European pharmacy channels. German and South Korean parents prioritize these for scalp-specific infant care, with midwife endorsement sustaining premium price acceptance.
- Bath Oil:Post-bath moisture retention formulations for eczema-prone infants, capturing disproportionate margins through certification complexity barriers.
- Bath Lotion:Leave-on emollient systems designed for sensitive epidermal barriers, expanding through direct-to-consumer subscription models in North America.
- Bath Powder:Talc-free absorbent formulations with herbal astringent properties, concentrated in traditional Asian markets with heritage usage patterns.
The dominant share belongs to Liquid Soap, while Bath Oil is closing the gap fastest.
Formulation:
Ingredient sourcing costs and certification timelines stratify margin pools across natural chemistry architectures.
- Herbal Extracts:Midwife-endorsed botanical systems with documented epidermal safety profiles, concentrated in German pharmacy distribution networks.
- Essential Oils:Fragrance-functional plant distillates subject to EU REACH allergen restrictions, forcing reformulation of legacy preservative packages.
- Plant-Based Surfactants:Decyl glucoside and coco-glucoside cleansing bases with 95%+ organic content, capturing premium positioning through limited qualified supplier pools.
- Natural Emollients:Shea butter and jojoba oil moisture barriers for eczema-prone infants, with South Korean MFDS notification procedures adding compliance overhead.
- Mineral Enriched:Thermal spring water and trace element formulations, anchored in French dermocosmetic heritage with ANSM pediatric scrutiny thresholds.
Plant-Based Surfactants command the largest formulation share, though Herbal Extracts are gaining share fastest through pharmacy channel density.
Application:
Clinical need severity and bathing ritual purpose determine price elasticity and channel selection across infant care scenarios.
- Newborn Care:Ultra-mild, tear-free chemistry for umbilical cord healing stages, with FDA cosmetic labeling rules mandating ingredient transparency disclosures.
- Sensitive Skin Care:Dermatologist-tested formulations for atopic dermatitis-prone infants, concentrated in United States pediatrician recommendation networks.
- Moisturizing Bath:Hydration-focused leave-on systems for dry climate conditions, expanding through South Korean beauty retail ecosystems.
- Soothing Bath:Colloidal oatmeal and calendula-based therapeutic bathing for irritated skin, with ECHA REACH annex revisions tightening fragrance allergen restrictions.
- Cleansing Bath:Daily hygiene surfactant systems with pH-balanced chemistry, saturating mass retail channels with private-label competition pressure.
Newborn Care holds the dominant application position, while Sensitive Skin Care is climbing the fastest on eczema prevalence trends.
End User:
Purchasing authority and skin biology maturity create distinct demand profiles across infant development stages and professional intermediaries.
- Newborns:Zero-to-three-month cohort with immature epidermal barriers, driving USDA Organic certification requirements and premium price tiers.
- Infants:Three-to-twelve-month daily bathing frequency, concentrated in millennial parent subscription-based replenishment models.
- Toddlers:Active bathing with play-focused product formats, constrained by multi-year organic supplier qualification timelines.
- Caregivers:Grandparent and childcare facility procurement with cost sensitivity distinct from parent purchasers, favoring economy-tier positioning.
- Pediatricians:Professional recommendation influence on sensitive skin and eczema segments, with clinical validation requirements adding R&D overhead.
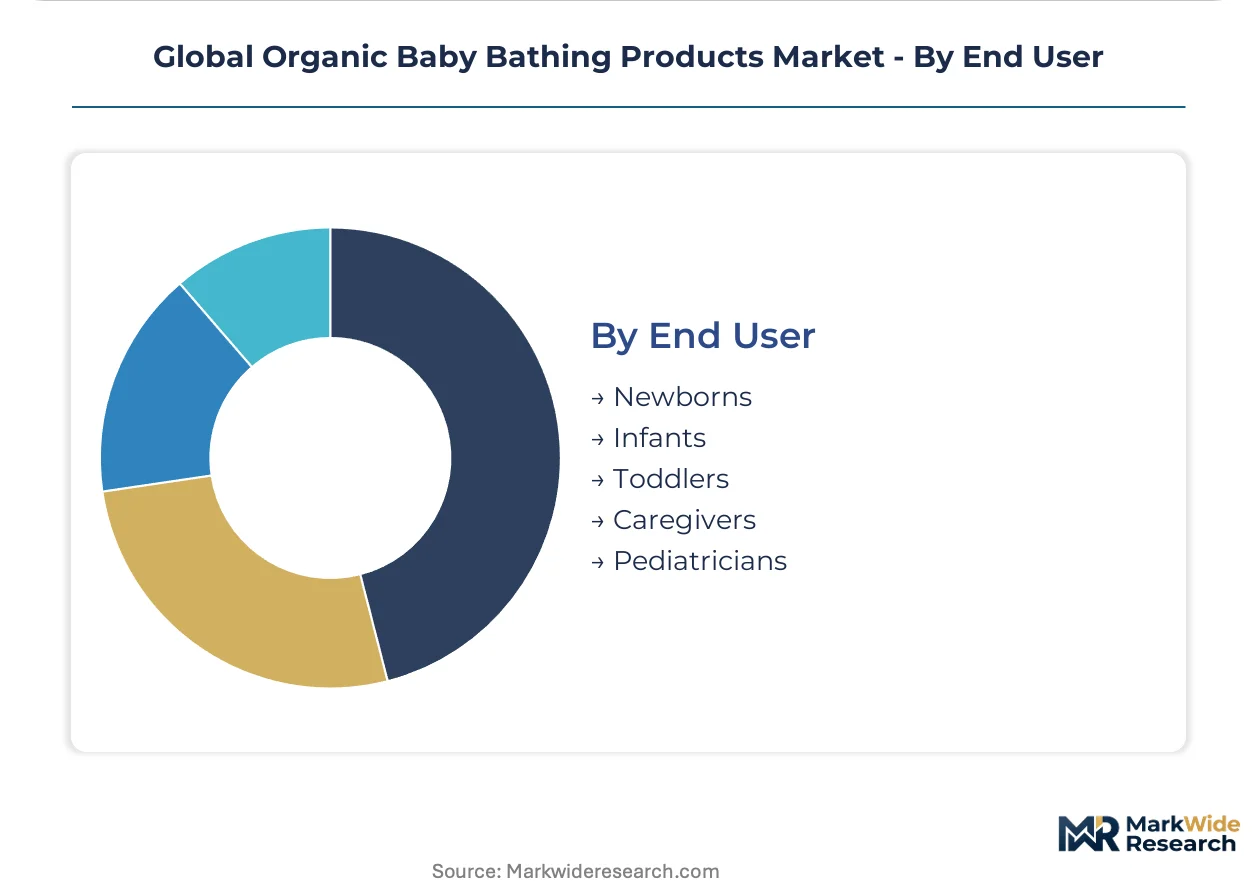
Newborns represent the largest end-user segment, though Pediatricians are expanding their influence fastest through clinical endorsement pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parents in South Korea treat organic baby bathing products as skincare rituals with multi-step routines, while German consumers prioritize pharmacy-channel verification and midwife endorsement over mass retail convenience. This consumption-mix differential fragments pricing power and channel strategy across national boundaries.
United States
Millennial subscription-based replenishment models concentrate demand forecasting risk with direct-to-consumer operators. FDA cosmetic labeling rules mandate ingredient transparency disclosures that convert clean-label claims into mandatory compliance thresholds. Los Angeles and New York anchor premium brand headquarters clusters where vertical sourcing control sustains margin retention against private-label pressure.
Germany
Pharmacy-channel density and midwife endorsement networks sustain premium positioning unavailable through conventional retail. ECHA REACH annex revisions tighten fragrance allergen restrictions that force reformulation of legacy surfactant systems. Bavaria and Baden-Württemberg concentrate contract manufacturing capabilities where near-infrared spectroscopy deployment compresses batch release timelines.
South Korea
Beauty retail ecosystems integrate organic baby bathing into multi-step skincare rituals with higher per-capita consumption frequency than Western markets. MFDS notification procedures add compliance overhead that filters out uncredentialed entrants. Seoul Capital Area dominates brand headquarters concentration where subscription resistance preserves traditional retail stocking patterns.
France
Thermal spring water heritage anchors dermocosmetic credibility for mineral-enriched infant formulations. ANSM pediatric scrutiny thresholds impose heightened sensitivity requirements that inflate R&D overhead for newborn-specific lines. Île-de-France maintains formulation chemistry clusters serving both domestic pharmacy networks and export markets.
United Kingdom
Clean-label verification demand from Gen Z parent cohorts accelerates COSMOS certification adoption ahead of regulatory mandates. Divergent post-Brexit cosmetic rules force redundant label harmonization expenditure against EU REACH requirements. Southeast England concentrates digital-native brand operations where blockchain-enabled supply chain verification trials digitize audit cycles.
Global Organic Baby Bathing Products Market Competitive Landscape
Capability concentration sits with heritage specialists possessing herbal-formulation expertise and pharmacy-channel relationships; scale advantage sits with mass-market operators with retail distribution density. The market structures around three archetypes: vertically integrated organic sourcing specialists, heritage dermocosmetic brands with thermal or botanical credibility, and digital-native direct-to-consumer operators with subscription infrastructure. Competitive moves concentrate on supply chain requalification for REACH compliance and pharmacy-channel partnership expansion for premium positioning leverage.
Within the heritage specialist tier, Weleda and Earth Mama exemplify midwife-endorsed distribution models that sustain price premiums through clinical credibility rather than advertising expenditure. California Baby occupies a position bridging natural-formulation heritage with United States mass retail scale. The Honest Company anchors the digital-native vector where vertical control over sourcing supports subscription-based replenishment economics.
| Leading Market Players |
|---|
| The Honest Company |
| Burt's Bees Baby |
| Earth Mama |
| Weleda |
| Babyganics |
| California Baby |
| Green People |
| Erbaviva |
| Nature's Baby Organics |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors linking certified organic plantations in Indonesia and Sri Lanka to contract manufacturers in Germany and the United States impose cost volatility that stratifies price tiers across the Global Organic Baby Bathing Products Market. Shippers absorbing bunker fuel surcharges and port congestion premiums pass these costs downstream, compressing margins for mass-market operators while reinforcing premium positioning for vertically integrated specialists with captive sourcing.
Pricing Analysis
Long-term offtake agreements between certified organic suppliers and heritage brands anchor pricing stability for plant-derived surfactants and herbal extracts, while spot-market procurement exposes digital-native entrants to harvest-season volatility. Price differentiation separates USDA Organic-certified formulations from COSMOS-verified equivalents through third-party audit costs and supply chain traceability investments. Cost compression in the economy tier intensifies as private-label competitors source lower-certification grades from concentrated supplier pools. Subscription-based direct-to-consumer buyers demonstrate lowest price sensitivity, while grandparent and childcare facility procurement segments favor economy positioning.
Supply Chain Analysis
Certified organic coconut oil and shea butter feedstock production concentrates in Indonesia, Sri Lanka, and Ghana, with decyl glucoside surfactant manufacturing anchored in Germany and the United States. Formulation chemistry draws from plant-derived inputs including calendula extract, colloidal oatmeal, and jojoba oil, each subject to multi-year organic qualification timelines. Single-source vulnerability in Indonesian coconut derivatives exposes formulators to El Niño-driven harvest shortfalls. Distribution runs through pharmacy networks in Germany, mass retail in the United States, and beauty retail ecosystems in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise bridging natural ingredient stability and infant epidermal safety remains scarce across the Global Organic Baby Bathing Products Market, constraining R&D throughput and inflating payroll costs for qualified cosmetic chemists. This capability gap rewards incumbents with established laboratory infrastructure while erecting barriers for uncredentialed entrants.
For Market Incumbents: Entrench pharmacy-channel relationships in Germany and midwife endorsement networks through exclusive distribution partnerships that resist mass retail commoditization. Deepen backward integration into certified organic plantations in Indonesia and Sri Lanka to secure surfactant supply against harvest volatility and input cost spikes. Prioritize ECHA REACH annex compliance investments ahead of fragrance allergen restriction tightening to force competitor reformulation cycles. For New Entrants and Emerging Players: Pursue post-bath moisture retention segments including bath oils and lotions for eczema-prone infants, where certification complexity limits incumbent replication speed and premium positioning remains underdeveloped. Target South Korean beauty retail ecosystems with multi-step skincare ritual positioning absent from Western market saturation. Deploy direct-to-consumer subscription infrastructure with auto-ship configurations to capture recurring revenue streams from millennial parent cohorts. For Investors and Strategic Acquirers: Heritage dermocosmetic specialists with thermal spring water or botanical formulation credibility and established pharmacy-channel density represent priority acquisition archetypes for portfolio exposure to premium-margin segments. Long-term viability across the analysis window hinges on pre-qualified fluorine-free supply chains ahead of state-level PFAS restriction waves. Watch ECHA REACH annex revision timing as inflection indicator for forced reformulation investment cycles and supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Expansion | Midwife endorsement networks in Germany sustain premium positioning unavailable through mass retail. |
| Backward Integration into Plantations | Captive organic coconut oil sourcing in Indonesia insulates against harvest volatility and cost spikes. |
| Blockchain Supply Chain Verification | Distributed ledger architectures compress audit cycles and redistribute trust from third-party laboratories. |
| PFAS-Free Formulation Pre-Qualification | Fluorine-free supply chains create first-mover advantage ahead of state-level restriction enforcement. |
| Direct-to-Consumer Subscription Launch | Auto-ship configurations concentrate demand forecasting risk while capturing recurring revenue from millennial parents. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at pharmacy and mass retail chains, cosmetic chemists, and organic certification auditors anchored the qualitative base for this study. Primary interviews with supply chain planners and procurement leads at contract manufacturers in Germany and the United States combined with secondary validation from USDA Organic certification databases, ECHA REACH annex filings, MFDS notification records, and customs trade data. Bottom-up volume modeling across product type, formulation chemistry, and end-user segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing around regulatory acceleration and supply disruption cases structured the analytical framework across the projection horizon. Segmentation dimensions modeled include rinse-off versus leave-on product architectures, herbal extract versus plant-based surfactant formulations, newborn versus toddler age cohorts, and pharmacy versus mass retail versus direct-to-consumer channel patterns. CAGRs derived from historical certification adoption curves and parent cohort purchasing behavior shifts, with infant eczema prevalence trends and organic retail ecosystem maturity serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices, container freight rates, and organic commodity harvest yields would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timing and certification pipeline throughput. Cross-checking against Nielsen retail audit data and pharmacy channel sell-through reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Makeup Brushes Market
Consumer Goods
Tobacco Products Market
Consumer Goods
Electronics Retailing Market
Consumer Goods
Europe Aromatherapy Diffuser Market
Consumer Goods
Built-In Hobs Market
Consumer Goods
Portable Iron Market
Consumer Goods
Emea Beauty Devices Market
Consumer Goods
Fitness Apparel Market
Consumer Goods
China Pet Clothing Market
Consumer Goods
Command Hooks Market
Consumer Goods
India Pant Type Adult Diaper Market
Consumer Goods
Global Cigarette Vending Machine Market
Consumer Goods
Global Organic Hair Color Market
Consumer Goods
Cutlery Market
Consumer Goods
Art Supplies Market
Consumer Goods
Breathable Mesh Running Shoes Market