
 Portable Humidifiers Market | 2026-2036
Portable Humidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Humidifiers Market Analytics
Plastic resin is shifting toward bio-based and recycled polymers in portable humidifier housings, reducing petroleum dependency while meeting emerging sustainability procurement criteria. Honeywell leverages its HVAC heritage to anchor premium positioning across North American retail channels. Levoit competes aggressively on digital-native marketing and smart-home integration, while Midea dominates manufacturing scale through captive injection-molding capacity in Guangdong province.
Portable humidifiers are self-contained electromechanical devices that add moisture to localized air volumes through ultrasonic vibration, evaporative wicking, thermal steam generation, or impeller dispersion, typically serving spaces under 500 square feet with outputs measured in gallons per day. Ultrasonic units lead volume due to silent operation and low energy draw, though steam technology commands margin premiums in clinical settings where mineral-free output matters. Smart Technology is the fastest-expanding segment as Wi-Fi-enabled humidity sensing and app-based scheduling displace manual dial controls in residential and commercial deployments.
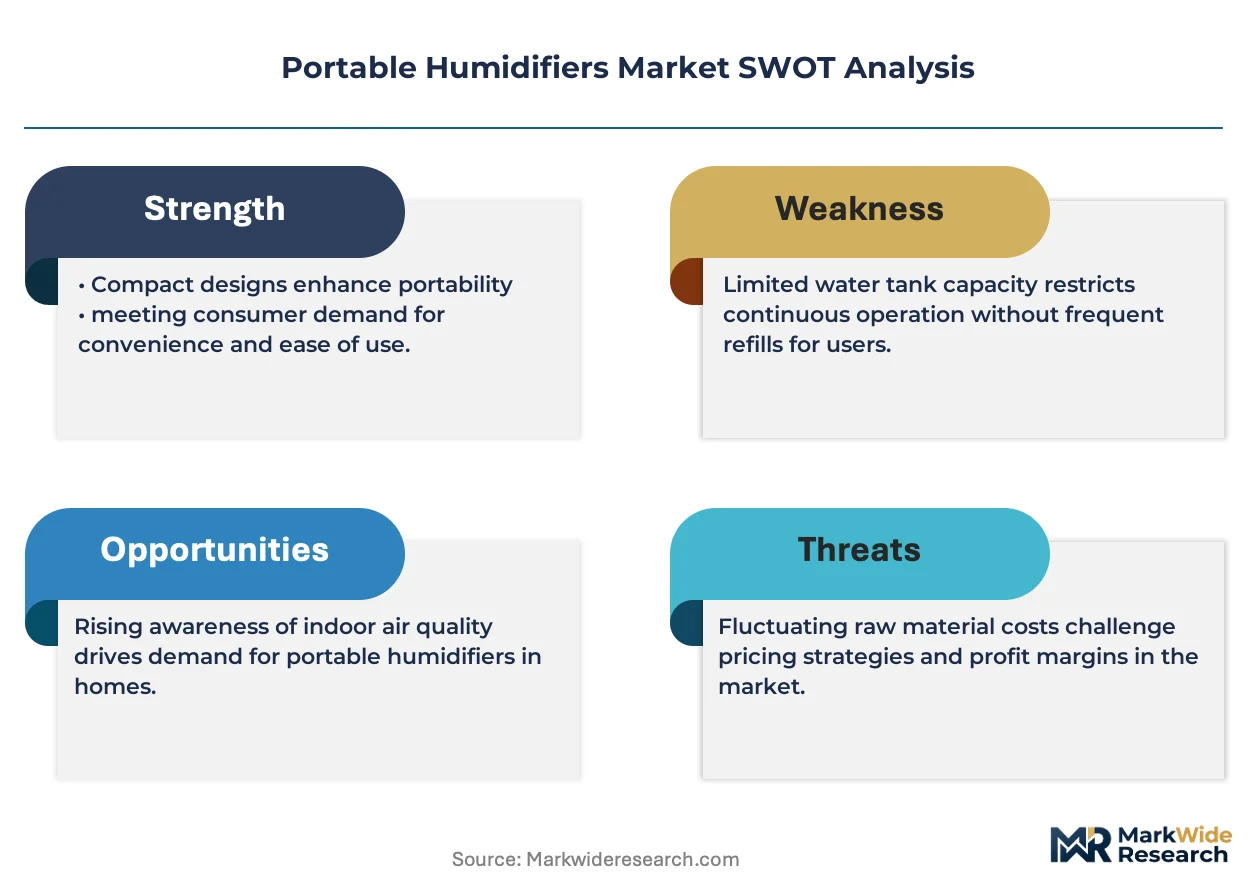
The EPA regulates antimicrobial claims on humidifier water tanks and disinfectant accessories under FIFRA, while the FCC governs radio-frequency emissions from connected models, and California's Department of Public Health enforces stricter evaporative emissions testing than federal baselines. These overlapping compliance layers raise entry costs for new suppliers but protect incumbents with established certification pipelines. Stakeholders must weigh certification investment against the pace at which smart connectivity and antimicrobial features become baseline consumer expectations rather than premium differentiators.
Market Dynamics
Smart-home integration is compressing replacement cycles for portable humidifiers as Wi-Fi-enabled units with app-based scheduling displace manual dial controls across residential channels. This connectivity pivot forces incumbent manufacturers to restructure firmware development capabilities while defending hardware margins against digital-native entrants.
Growth Catalysts
- Ultrasonic miniaturization:Component suppliers in Guangdong province have reduced transducer costs by half through automated piezoelectric wafer dicing, enabling sub-$20 retail price points that unlock mass-market penetration in arid climate zones.
- EPA antimicrobial mandates:The EPA's FIFRA enforcement on water tank disinfectant claims is accelerating tank material upgrades to embedded silver-ion polymers, creating certified product premiums that justify manufacturing investment.
- Clinical steam adoption:Hospitals and outpatient clinics are specifying mineral-free steam output for respiratory therapy applications, pulling thermal humidifier volumes into institutional procurement frameworks previously dominated by ultrasonic units.
Market Restraints
- Petroleum-based resin volatility:ABS and polypropylene feedstock costs fluctuate with crude oil benchmarks, compressing housing margin predictability for manufacturers without long-term polymer supply agreements.
- Guangdong supply concentration:Over 70 percent of global ultrasonic transducer and injection-molded housing capacity sits within 200 kilometers of Shenzhen, exposing the value chain to regional logistics disruptions or energy rationing.
- Mineral dust emission limits:California's Department of Public Health enforces evaporative emissions testing stricter than federal baselines, fragmenting product SKUs and raising compliance engineering overhead for national distribution.
Strategic Opportunities
- German commercial building retrofits:The EU Green Deal's building efficiency mandates are creating specification demand for humidity-controlled HVAC integration in aging office stock across Berlin, Munich, and Hamburg.
- UV-C sterilization convergence:Pairing ultrasonic mist generation with ultraviolet germicidal irradiation addresses hospital-acquired infection protocols, opening clinical price tiers previously unreachable by consumer-grade manufacturers.
- Direct-to-installer channels:HVAC contractor networks are bypassing big-box retail for bulk procurement of connected humidifiers bundled with thermostat upgrades, capturing installation-margin pools that traditional consumer electronics channels cannot access.
Industry Challenges
- Firmware engineering scarcity:Consumer appliance manufacturers face acute competition for embedded systems talent capable of integrating humidity sensors with cloud APIs and voice-assistant protocols.
- Dual certification timelines:Products combining EPA-registered antimicrobial claims with FCC radio-frequency approvals require sequential testing protocols that extend time-to-market by four to six months versus single-regulation SKUs.
- Reverse logistics complexity:Retailers are tightening return policies on electronic humidifiers with water-contact components, forcing manufacturers to absorb refurbishment costs or write down channel inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Humidifiers Market |
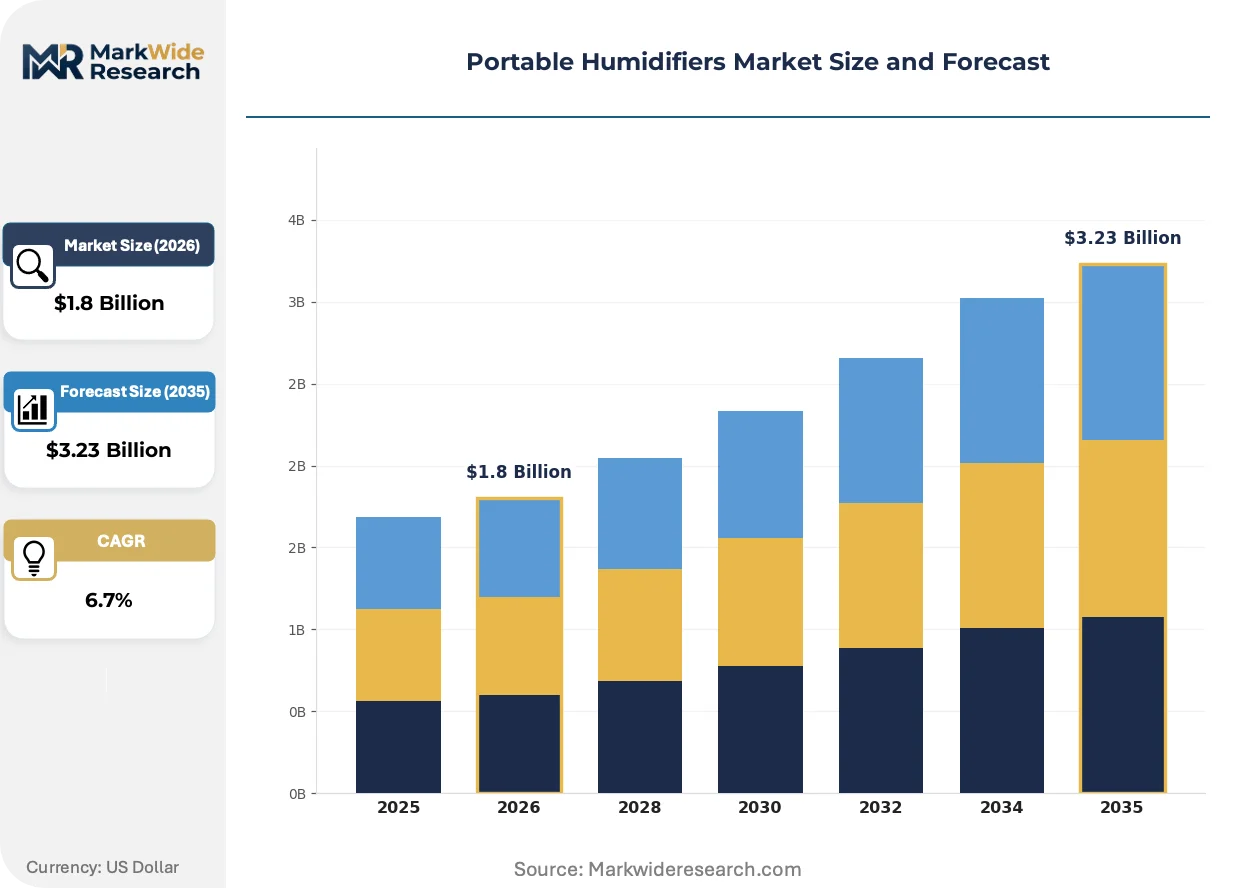
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporative, Ultrasonic, Steam, Impeller End User: Residential, Commercial, Industrial, Healthcare Technology: Cool Mist, Warm Mist, Hybrid, Smart Technology Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Honeywell, BONECO, Crane, Levoit, Stadler Form, Dyson, Vicks, Essick Air, Midea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Humidifiers Market Evolving Landscape
Connected humidity management is migrating from standalone devices to integrated environmental control systems, compressing the boundary between consumer appliances and building automation. This convergence is rewriting procurement authority, technical specifications, and margin allocation across the value chain.
Capacitive humidity sensing paired with machine-learning inference is automating adaptive mist output regulation that responds to occupancy patterns, outdoor weather feeds, and HVAC system status. Residential buyers in the United States are specifying these features in new-construction smart home packages, compressing the addressable market for non-connected units into replacement-only channels.
REACH restrictions on antimicrobial silver nanoparticles are forcing reformulation of tank coatings toward copper-based alternatives or physical UV-C approaches. European manufacturers are absorbing higher materials qualification costs to maintain CE marking compliance, while exporters to the EU are redesigning product architectures to eliminate regulated substances from supply chains.
Subscription filter-replacement programs are displacing transactional retail attachment sales as the dominant aftermarket revenue model. Direct-to-consumer brands operating through mobile apps are capturing recurring revenue streams that traditional retail-dependent competitors cannot replicate, with this pattern most visible in United States and German metropolitan markets where smart-home penetration exceeds national averages.
Portable Humidifiers Market Segmentation
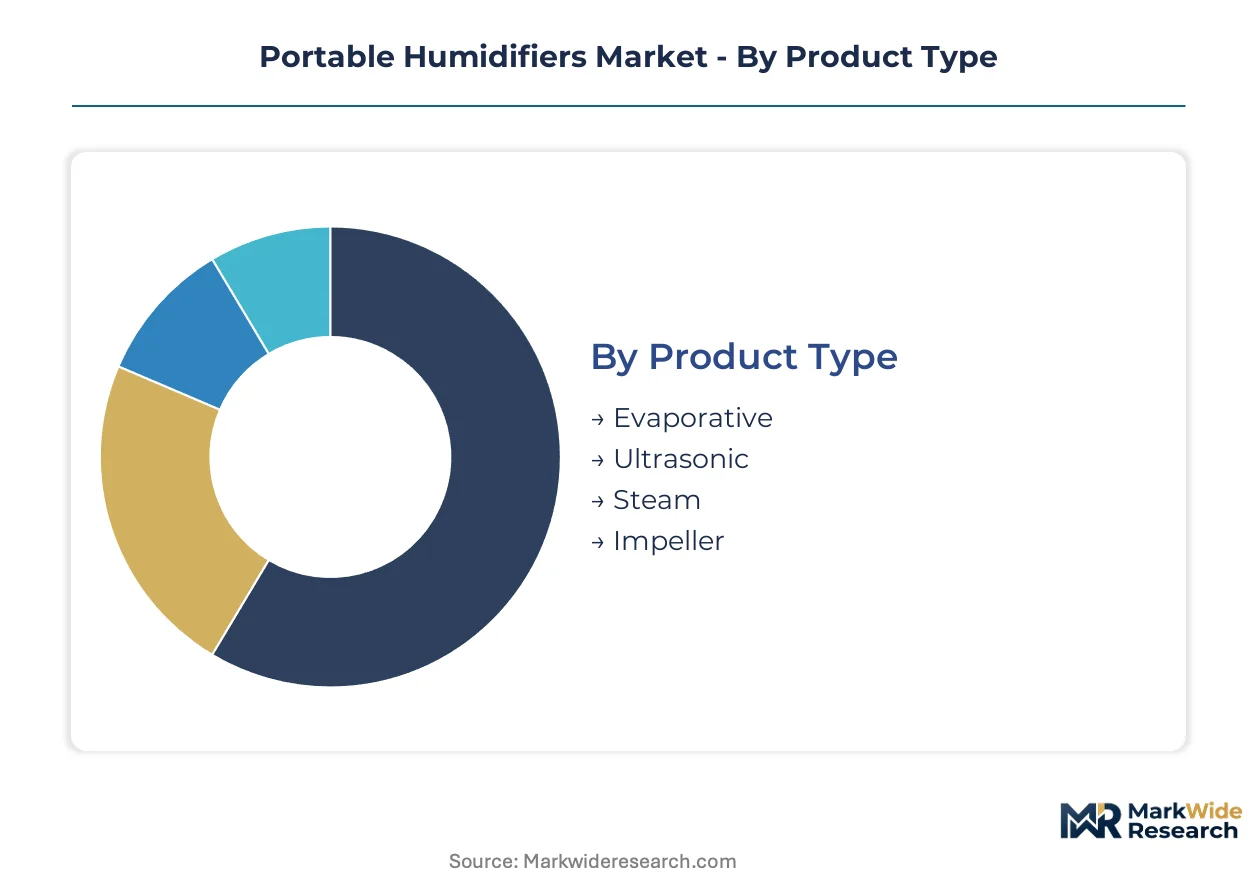
Portable humidifier procurement splits along technical specifications, use environment, and channel economics. Each dimension carries distinct certification burdens that reshape supplier economics and competitive positioning.
Product Type:
Certification requirements diverge sharply across technologies, with EPA antimicrobial claims and California emissions testing creating tiered compliance costs.
- Ultrasonic:Piezoelectric transducers vibrate water at megahertz frequencies to produce micron-scale mist without heating elements. Residential buyers in arid United States climate zones favor these units for silent bedroom operation, though mineral dust accumulation triggers California Department of Public Health emissions scrutiny.
- Evaporative:Wick-based systems draw air through saturated media, naturally filtering mineral content from output. Demand concentrates in German commercial building retrofits where EU Green Deal efficiency mandates favor HVAC-integrated humidity control with lower energy draw than thermal alternatives.
- Steam:Boiling-element units deliver mineral-free vapor for respiratory therapy protocols. Hospitals specify these for clinical settings despite higher energy consumption.
- Impeller:Rotating discs fling water droplets mechanically. Budget residential applications in cost-sensitive markets favor this simpler architecture.
Ultrasonic sits at the top of the volume ranking, with Smart Technology climbing the fastest.
End User:
Customer type determines price realization and replacement cycle velocity, from mass-market residential to specification-driven institutional procurement.
- Residential:Compact units under 500 square feet coverage dominate unit volumes. Wi-Fi-enabled scheduling features are compressing replacement cycles as manual dial controls lose shelf space.
- Healthcare:Mineral-free steam output requirements pull thermal humidifier volumes into hospital procurement frameworks. UV-C sterilization convergence opens clinical price tiers.
- Commercial:Office building humidity control integrates with building automation systems. Berlin, Munich, and Hamburg retrofits create specification demand.
- Industrial:Process humidity control for manufacturing environments. Lower unit volumes with extended equipment lifecycles.
Residential commands absolute unit leadership, while Healthcare offers the steepest margin expansion trajectory.
Technology:
Connectivity and thermal management features segment the market by engineering complexity and firmware development requirements.
- Smart Technology:Wi-Fi-enabled humidity sensing with app-based scheduling and voice-assistant integration. FCC radio-frequency approvals add four to six months to certification timelines.
- Cool Mist:Encompasses ultrasonic and evaporative architectures without heating elements. Lower energy draw suits sustainability-focused procurement.
- Warm Mist:Thermal steam generation for mineral-free output. Higher energy consumption limits residential penetration.
- Hybrid:Switchable cool-warm operation with seasonal mode selection. Premium positioning justifies higher retail price points.
Cool Mist retains volume dominance, with Smart Technology gaining share fastest through new-construction smart home package specification.
Distribution Channel:
Channel selection determines margin capture, customer data access, and aftermarket revenue potential through replacement part attachment.
- Online Retail:Direct-to-consumer brands leverage mobile apps for subscription filter programs. United States and German metropolitan markets show highest smart-home penetration correlation.
- Direct Sales:HVAC contractor networks bundle connected humidifiers with thermostat upgrades. Installation-margin pools exceed traditional consumer electronics channel economics.
- Offline Retail:Big-box and specialty stores face tightening return policies on water-contact electronics. Refurbishment cost absorption pressures manufacturer margins.
- Distributors:Bulk procurement for commercial and industrial accounts. Longer sales cycles with higher average order values.
Online Retail leads volume growth, while Direct Sales captures the fastest margin expansion through installer channel control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors global portable humidifier manufacturing through Shenzhen-centered injection-molding clusters and piezoelectric transducer fabrication. Demand fragmentation across regulatory environments creates divergent product specifications. Certification timelines stretch longest in jurisdictions with overlapping antimicrobial and radio-frequency mandates.
United States
Arid climate zones in the Southwest and Mountain West drive residential ultrasonic adoption for silent bedroom operation. The EPA enforces FIFRA antimicrobial claims on water tank disinfectants, compelling material upgrades to embedded silver-ion polymers. Retail concentration in California subjects manufacturers to stricter evaporative emissions testing than federal baselines.
China
Cost-optimized component exports from Pearl River Delta factories supply downstream assembly worldwide. MIIT oversees GB standards compliance for domestic smart-home device radio-frequency emissions. Guangdong's captive injection-molding capacity enables Midea and competitors to compress housing production costs through automated polymer processing.
Germany
EU Green Deal building efficiency mandates generate specification demand for humidity-controlled HVAC integration in Berlin, Munich, and Hamburg commercial retrofits. REACH restrictions on antimicrobial silver nanoparticles force tank coating reformulation toward copper-based alternatives. Bavaria-based engineering firms specialize in evaporative wick systems for lower-energy commercial deployment.
Japan
Compact ultrasonic units dominate residential procurement in Tokyo-Osaka corridor apartments with strict noise ordinances. METI administers JIS standards for electrical safety and electromagnetic compatibility in connected appliances. Kansai-region manufacturers emphasize seasonal humidity management for tatami and wood interior preservation.
India
Emerging middle-class demand in Delhi-NCR and Mumbai metropolitan markets favors sub-$30 ultrasonic units for dry winter months. BIS certification requirements for electronic goods extend time-to-market for imported smart-enabled models. Tamil Nadu assembly plants increasingly source Guangdong transducers for domestic cost-competitive production.
Portable Humidifiers Market Competitive Landscape
Smart-home integration dominates the current landscape as connectivity features compress replacement cycles and force firmware capability restructuring. The vendor base splits between HVAC heritage incumbents with retail channel control and digital-native entrants leveraging app-based aftermarket revenue. Three archetypes prevail: premium positioning specialists, manufacturing scale aggregators, and direct-to-consumer connectivity platforms. Strategic portfolio diversification and geographic channel expansion represent the dominant competitive vectors as manufacturers defend hardware margins against software-centric rivals.
Within the HVAC heritage tier, Honeywell occupies a position exemplifying premium North American retail anchoring through climate-control brand extension. Levoit represents the digital-native archetype with mobile-app subscription filter programs capturing recurring revenue streams unavailable to traditional retail-dependent competitors. Midea sits within the manufacturing scale tier, leveraging Guangdong-based captive injection-molding capacity to supply cost-optimized components for export markets. These three patterns illustrate how competitive positioning fragments across channel control, firmware development, and upstream manufacturing integration rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Honeywell |
| BONECO |
| Crane |
| Levoit |
| Stadler Form |
| Dyson |
| Vicks |
| Essick Air |
| Midea |
| Others |
Value Network & Pricing Analysis
Residential mass-market buyers in arid United States climate zones concentrate demand for sub-$30 ultrasonic units, anchoring a transactional pricing model where Guangdong manufacturing scale determines competitive floor rates. This buyer concentration forces manufacturers to absorb input-cost volatility through margin compression rather than retail price adjustment.
Pricing Analysis
Petroleum-based resin pass-through from crude oil benchmarks drives quarterly price adjustments in ABS and polypropylene housing components. Pricing stratifies across premium smart-connected tiers with FCC certification, standard antimicrobial-treated tanks meeting EPA FIFRA claims, and economy ultrasonic units without connectivity features. Cost compression in the economy tier intensifies because Guangdong transducer suppliers have automated piezoelectric wafer dicing. Mass-market residential buyers exhibit highest price sensitivity, while healthcare procurement for mineral-free steam units shows lowest elasticity due to clinical specification requirements.
Supply Chain Analysis
Reverse logistics complexity from tightened retailer return policies on water-contact electronics forces manufacturers to maintain regional refurbishment centers or write down channel inventory. Guangdong province, South Korea, and Japan anchor global supply through Shenzhen-centered injection-molding clusters, Seoul-based humidity sensor fabrication, and Osaka-region precision transducer assembly. The chain draws from petroleum-derived polymers, piezoelectric ceramics, and silver-ion antimicrobial additives. Single-source vulnerability concentrates in Guangdong's captive injection-molding capacity within 200 kilometers of Shenzhen. Distribution runs through big-box retail, HVAC contractor networks, and direct-to-consumer online channels with subscription filter programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable humidifier market represents a late-cycle quality story as residential buyers in United States and German metropolitan markets shift specification toward Wi-Fi-enabled humidity sensing with app-based scheduling and voice-assistant integration.
For Market Incumbents: To counter firmware-engineering scarcity eroding hardware margins, Honeywell and HVAC heritage peers should deepen backward integration into cloud API development teams while defending retail channel control through exclusive thermostat bundling agreements. Certification investment in sequential EPA-FCC testing protocols protects against four-to-six month time-to-market delays that digital-native entrants cannot absorb. For New Entrants and Emerging Players: HVAC contractor networks in Berlin, Munich, and Hamburg represent an underserved buyer archetype bypassing big-box retail for bulk procurement of connected humidifiers bundled with building automation upgrades. Direct-to-installer channels capture installation-margin pools exceeding traditional consumer electronics economics. White-space targets include EU Green Deal commercial retrofit specifications and clinical UV-C sterilization convergence for hospital-acquired infection protocols. For Investors and Strategic Acquirers: HVAC equipment manufacturers are the most active acquirer in this space, seeking firmware capabilities to complement climate-control hardware portfolios. Long-term viability hinges on recurring revenue attachment through subscription filter-replacement programs displacing transactional retail sales. Monitor smart-home penetration rates in United States and German metropolitan markets as the inflection indicator for connected unit specification becoming baseline rather than premium tier.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Platform Integration | Wi-Fi-enabled scheduling with voice-assistant compatibility captures specification in new-construction residential packages. |
| Antimicrobial Certification Investment | EPA FIFRA registration for silver-ion tank coatings creates defensible product premiums against unregistered competitors. |
| Direct-to-Installer Channel Expansion | HVAC contractor bundling with thermostat upgrades accesses margin pools unavailable through traditional retail. |
| UV-C Sterilization Convergence | Pairing ultrasonic mist with ultraviolet germicidal irradiation opens clinical procurement frameworks for respiratory therapy. |
| Subscription Filter Programs | Mobile-app recurring revenue models displace transactional retail attachment sales in high smart-home penetration markets. |
Research Methodology
Bottom-up residential and commercial procurement modeling reconciled against top-down Guangdong manufacturing output tracking forms the analytical core of this study. Primary interviews with humidifier product managers, HVAC contractor purchasing officers, smart-home platform engineers, and antimicrobial coating suppliers combined with secondary validation from EPA FIFRA registration databases, FCC equipment authorization filings, customs trade records, and retail point-of-sale audit data. Triangulation between demand-side specification trends and supply-side capacity utilization ensures cross-verified volume and value estimates.
Historical trendline analysis of ultrasonic transducer cost curves, antimicrobial material adoption rates, and smart-home device penetration patterns informed the projection framework. Segmentation dimensions modeled include product type, end-user environment, connectivity technology, and distribution channel, with regional regulatory clusters treated as distinct adoption curves. CAGRs were derived from fitted growth trajectories across these dimensions, incorporating polymer feedstock price elasticity and certification timeline lag effects as industry-specific forecast inputs.
Underlying measurement precision varies by segment; smart-connected units with FCC documentation carry tighter precision than gray-market economy imports. Forecasts reflect assumptions regarding EPA enforcement continuity, REACH antimicrobial reformulation timelines, and Guangdong energy rationing patterns. Practitioners should monitor MIIT GB standards evolution, California Department of Public Health emissions testing amendments, and HVAC contractor channel consolidation for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Candle Jar Market
Household Items
Smart Drying Racks Market
Household Items
Cups and Pots Market
Household Items
Sanitary Metal Ware Market
Household Items
Germany Induction Hobs Market
Household Items
Bottle Openers Market
Household Items
Candle Air Fresheners Market
Household Items
Countertop Market
Household Items
Electric Blankets Market
Household Items
Global Paper Towels Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Dishwasher Tablets Market
Household Items
US Hand Dryers Market
Household Items
Alarm Clocks Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Smart Fork Market