
 Middle East and Africa Air Purifier Market | 2026-2036
Middle East and Africa Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Air Purifier Market Insights
Qualified HVAC technician availability is collapsing across the Middle East and Africa, constraining installation capacity and pushing buyers toward plug-and-play portable units. Panasonic Marketing Middle East & Africa FZE leverages its regional service network to sustain aftermarket attachment rates. Daikin Industries Ltd anchors premium centralized system sales through direct contractor training programs in the UAE and Saudi Arabia.
An air purifier is an electromechanical device that forces ambient air through fibrous, adsorptive, or photocatalytic media to remove particulate matter, volatile organic compounds, and biological contaminants, with HEPA filtration requiring a minimum 99.97% capture efficiency at 0.3 microns. Portable units dominate residential uptake across the region due to minimal installation dependency and lower capital outlay. Photocatalytic technology segments are gaining fastest in healthcare end-use settings where pathogen neutralization requirements exceed standard filtration capability.
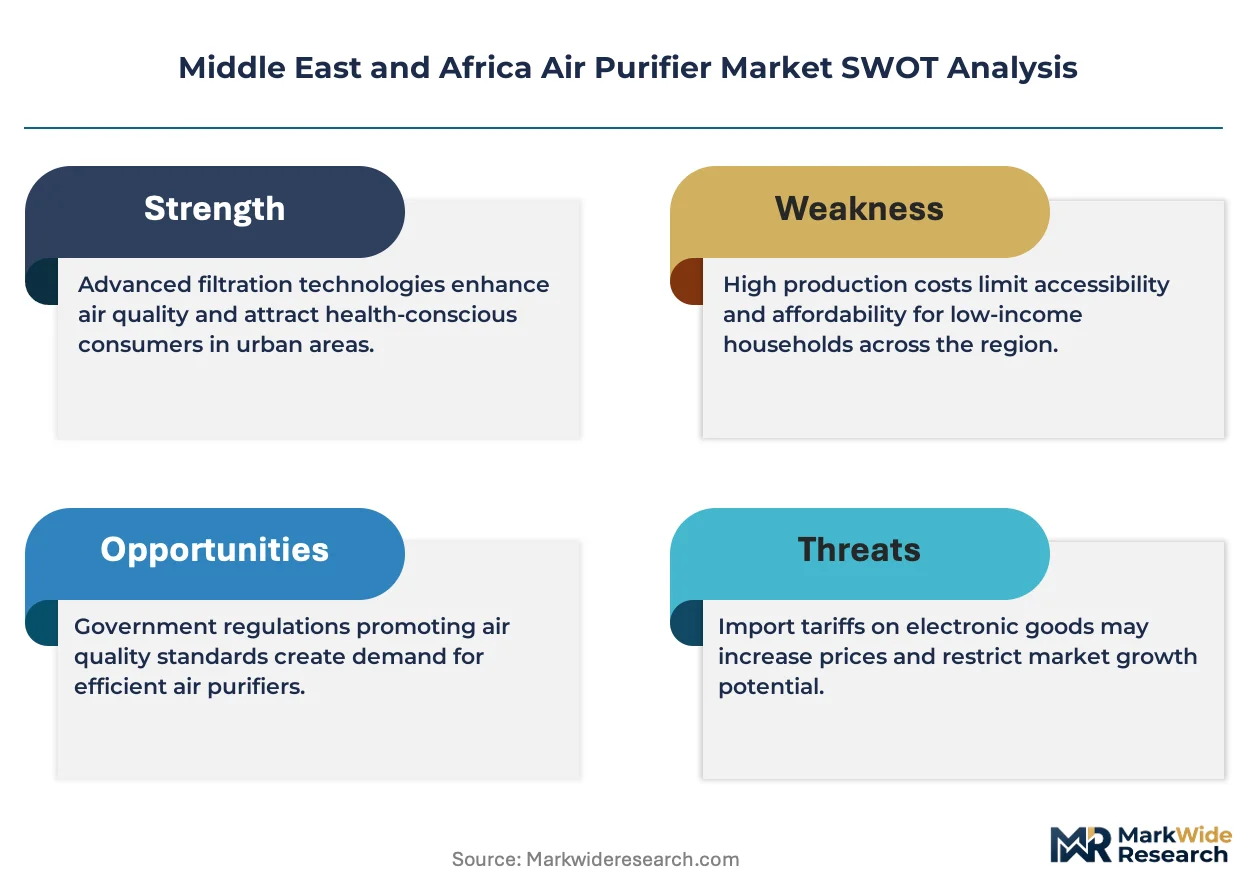
Saudi Arabia's SFDA and the UAE's MOHAP enforce divergent medical-grade air quality standards, fragmenting product certification requirements for hospital procurement. South Africa's environmental quality regulator mandates workplace particulate thresholds that extend demand into industrial retrofit applications. Stakeholders must monitor harmonization efforts between Gulf standardization bodies and sub-Saharan national regulators to anticipate cross-border product registration efficiencies.
Market Dynamics
The Middle East and Africa air purifier market is being fundamentally restructured by a severe contraction in qualified HVAC technician availability, which is compressing installation capacity and redirecting procurement toward portable, plug-and-play units across Gulf Cooperation Council urban centers.
Growth Catalysts
- Healthcare facility expansion:Hospitals across Saudi Arabia and the UAE are scaling HEPA-grade procurement to meet medical-grade air quality mandates from the SFDA and MOHAP.
- MOHAP enforcement tightening:The UAE's health authority is accelerating compliance timelines for surgical suite ventilation, forcing equipment refresh cycles in Dubai and Abu Dhabi medical centers.
- Photocatalytic pathogen neutralization:Healthcare end-users are prioritizing photocatalytic oxidation systems where standard filtration cannot satisfy infection control protocols.
Market Restraints
- Filter media import dependency:HEPA and activated carbon substrates concentrate in East Asian supply bases, exposing regional assemblers to freight cost volatility and extended lead times.
- South Africa's fragmented enforcement:The national environmental regulator's workplace particulate thresholds vary by provincial interpretation, creating compliance uncertainty for industrial retrofit buyers.
- Portable unit substitution pressure:Low-cost unbranded imports from unregulated channels undercut certified equipment in residential segments across Nigeria and Kenya.
Strategic Opportunities
- Kenya's underpenetrated commercial sector:Nairobi's office construction pipeline lacks centralized air handling specifications, creating first-mover advantage for modular filtration system suppliers.
- SFDA-MOHAP harmonization momentum:Convergence discussions between Saudi and UAE standardization bodies promise streamlined cross-border product registration for hospital-grade equipment.
- Photocatalytic-UV convergence:Integration of titanium dioxide catalysts with UV-C irradiation is opening specification wins in isolation ward and laboratory applications where single-technology systems fail.
Industry Challenges
- Technician certification bottlenecks:Daikin Industries Ltd and Panasonic Marketing Middle East & Africa FZE are absorbing training costs for contractor networks in the UAE and Saudi Arabia, but graduation rates lag installation demand.
- Divergent medical-grade standards:Saudi Arabia's SFDA and the UAE's MOHAP maintain non-interchangeable testing protocols, forcing manufacturers to duplicate certification expenditures for Gulf market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Air Purifier Market |
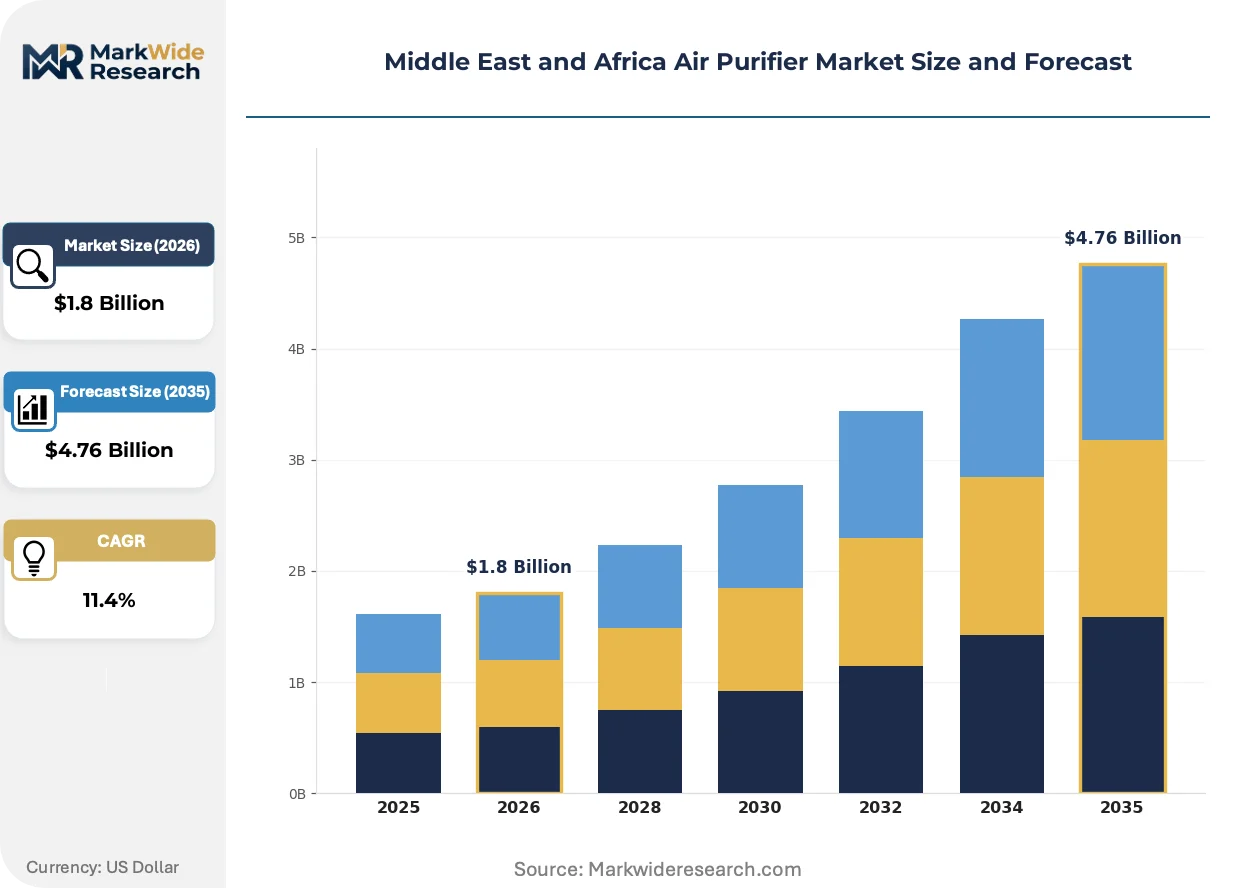
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-Mounted, Centralized, HEPA Filter Technology: Activated Carbon, UV Light, Ionizer, Photocatalytic End User: Residential, Commercial, Industrial, Healthcare Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Panasonic Marketing Middle East & Africa FZE, Camfil AB, Daikin Industries Ltd, LG Electronics Inc, Aerofil Filters Manufacturing LLC, Carrier Global Corp, Royal Philips Group, Honeywell International Inc, Samsung Electronics Co Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Air Purifier Market Trends and Innovations
Photocatalytic and smart sensor architectures are compressing the performance gap between centralized and portable systems, while regulatory divergence between Gulf standardization bodies is forcing adaptive product strategies.
Photocatalytic oxidation modules are miniaturizing into portable form factors previously restricted to fixed installations. Hospital procurement committees in Riyadh and Dubai are specifying these units for emergency department triage areas and temporary isolation facilities. The technology is miniaturizing filtration-equivalent performance into battery-operated deployments, collapsing the traditional centralized-versus-portable capability gap in healthcare settings.
SFDA and MOHAP are enforcing divergent medical-grade air quality standards that fragment product certification requirements for hospital procurement across the Gulf. Manufacturers must maintain parallel testing regimens to satisfy both regulators, elevating compliance overhead for multinational suppliers. Saudi Arabia's surgical suite specifications and the UAE's intensive care ventilation mandates are responding with country-specific product line extensions rather than unified Gulf certification.
Facility managers are unbundling after-sales service contracts from equipment procurement, treating filter replacement and sensor calibration as separate spend categories. This disintermediation is compressing OEM service attachment rates and elevating third-party maintenance providers in UAE commercial real estate. Dubai's property management sector is most visible in this shift, with landlords negotiating service-level agreements independent of capital equipment purchases.
Middle East and Africa Air Purifier Market Segmentation
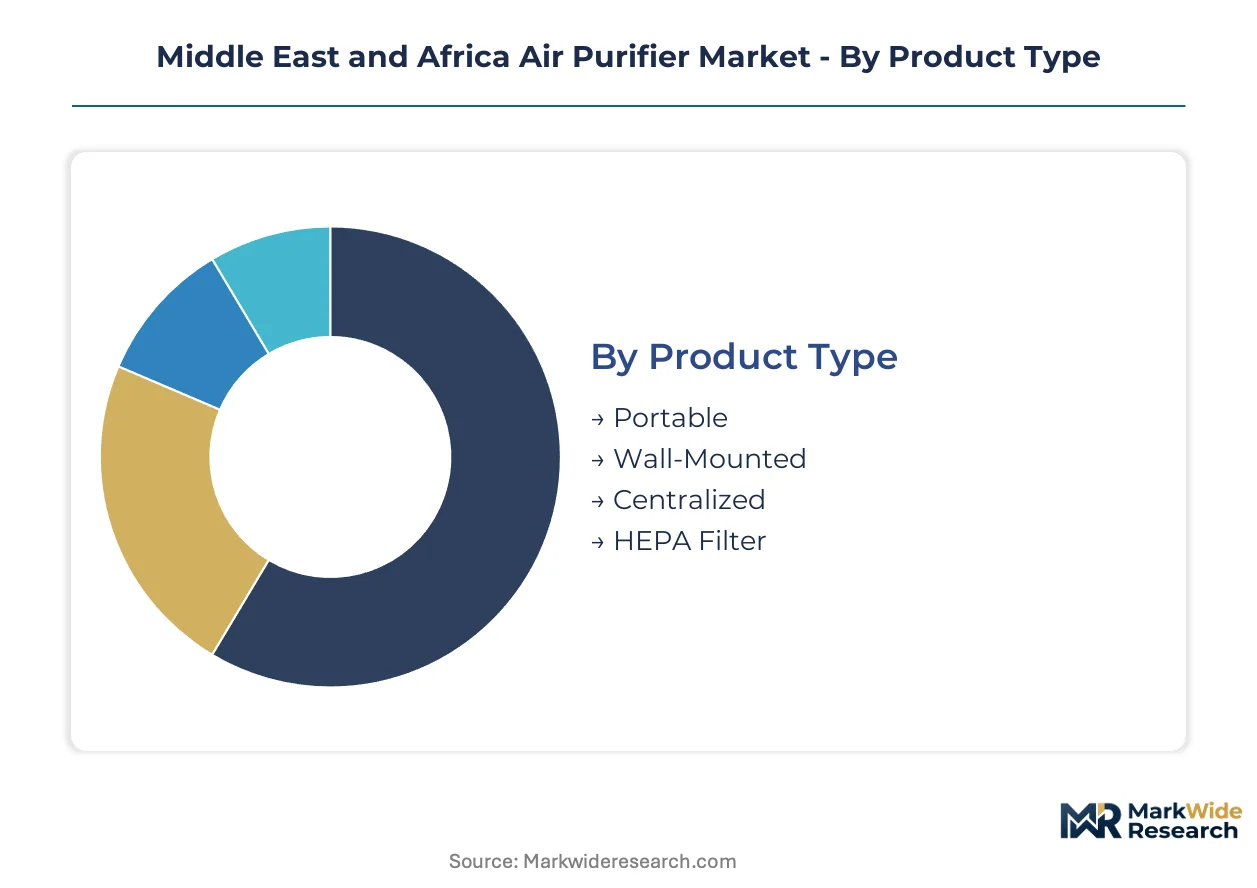
Product architecture and procurement pathways fragment the Middle East and Africa air purifier market into distinct competitive arenas. Each dimension carries divergent margin profiles, certification burdens, and service attachment rates that shape supplier positioning across Gulf Cooperation Council urban centers and sub-Saharan growth corridors.
Product Type:
Margin pools concentrate in centralized systems where contractor relationships and maintenance contracts extend revenue capture over multi-year horizons, while portable units compete on volume throughput and channel efficiency.
- Portable:Self-contained electromechanical units requiring no permanent installation dominate residential procurement across Nigeria and Kenya due to minimal capital outlay and immediate deployment capability. Dust-storm frequency in Dubai and Riyadh drives repeat purchase cycles as filter saturation accelerates in high-particulate environments.
- Centralized:Building-integrated air handling systems with dedicated filtration banks command premium specification in Saudi Arabian healthcare construction where SFDA mandates surgical-suite air exchange protocols. Daikin Industries Ltd and Panasonic Marketing Middle East & Africa FZE anchor market presence through contractor certification programs that lock out unqualified competitors.
- Wall-Mounted:Fixed-installation units targeting commercial retrofit applications where floor space constraints eliminate portable alternatives. Nairobi office construction pipelines specify these for open-plan environments lacking raised-floor infrastructure.
- HEPA Filter:Standalone filtration media and cartridge systems sold as replacement components or upgrade modules. MOHAP enforcement tightening in Abu Dhabi medical centers accelerates compliance-driven refresh cycles for existing installed bases.
The dominant share belongs to Portable, while Centralized is closing the gap fastest through healthcare facility expansion mandates.
Technology:
Technology selection tracks end-use severity, with pathogen-neutralization capabilities commanding price premiums in regulated medical environments versus odor-adsorption solutions in commercial and residential settings.
- Photocatalytic:Titanium dioxide catalyst systems activated by UV irradiation achieve complete oxidation of biological contaminants rather than mere capture. Hospital procurement committees in Riyadh and Dubai specify these for isolation wards and emergency triage areas where standard HEPA filtration cannot satisfy infection control protocols.
- Activated Carbon:Porous adsorptive media targeting volatile organic compounds and gaseous pollutants from construction materials and industrial processes. UAE commercial real estate developers embed these in fit-out specifications for new office towers addressing tenant air quality concerns.
- UV Light:Germicidal irradiation systems disrupting pathogen DNA/RNA without filtration media replacement. South African workplace particulate threshold enforcement extends demand into industrial retrofit applications where biological contamination risks accompany manufacturing processes.
- Ionizer:Electrostatic precipitation generating charged particles for collection on oppositely charged plates. Residential segments across unregulated channels in Nigeria and Kenya absorb low-cost imports despite ozone emission concerns absent local enforcement.
Photocatalytic systems capture the steepest expansion trajectory as healthcare end-users prioritize pathogen neutralization, though Activated Carbon retains volume leadership in commercial construction.
End User:
Customer-type segmentation reveals divergent procurement sophistication, with healthcare and industrial buyers demanding certified performance documentation while residential purchasers prioritize immediate availability and price accessibility.
- Healthcare:Hospitals, clinics, and laboratory environments subject to SFDA and MOHAP air quality mandates. Saudi Arabian surgical suite specifications and UAE intensive care ventilation requirements force country-specific product line extensions rather than unified Gulf certification.
- Commercial:Office buildings, retail environments, and hospitality properties where tenant expectations and lease competitiveness drive filtration investment. Dubai property managers unbundle service contracts from equipment procurement, compressing OEM attachment rates.
- Residential:Individual household purchases dominated by plug-and-play portable units across Gulf Cooperation Council urban centers and sub-Saharan markets. Low-cost unbranded imports from unregulated channels undercut certified equipment in Nigeria and Kenya.
- Industrial:Manufacturing facilities, warehouses, and processing plants where process emissions and occupational exposure limits create retrofit demand. South Africa's national environmental regulator mandates workplace particulate thresholds that vary by provincial interpretation.
Healthcare commands the highest revenue per unit, with Commercial expanding most quickly as construction booms elevate filtration specifications in new office stock.
Distribution Channel:
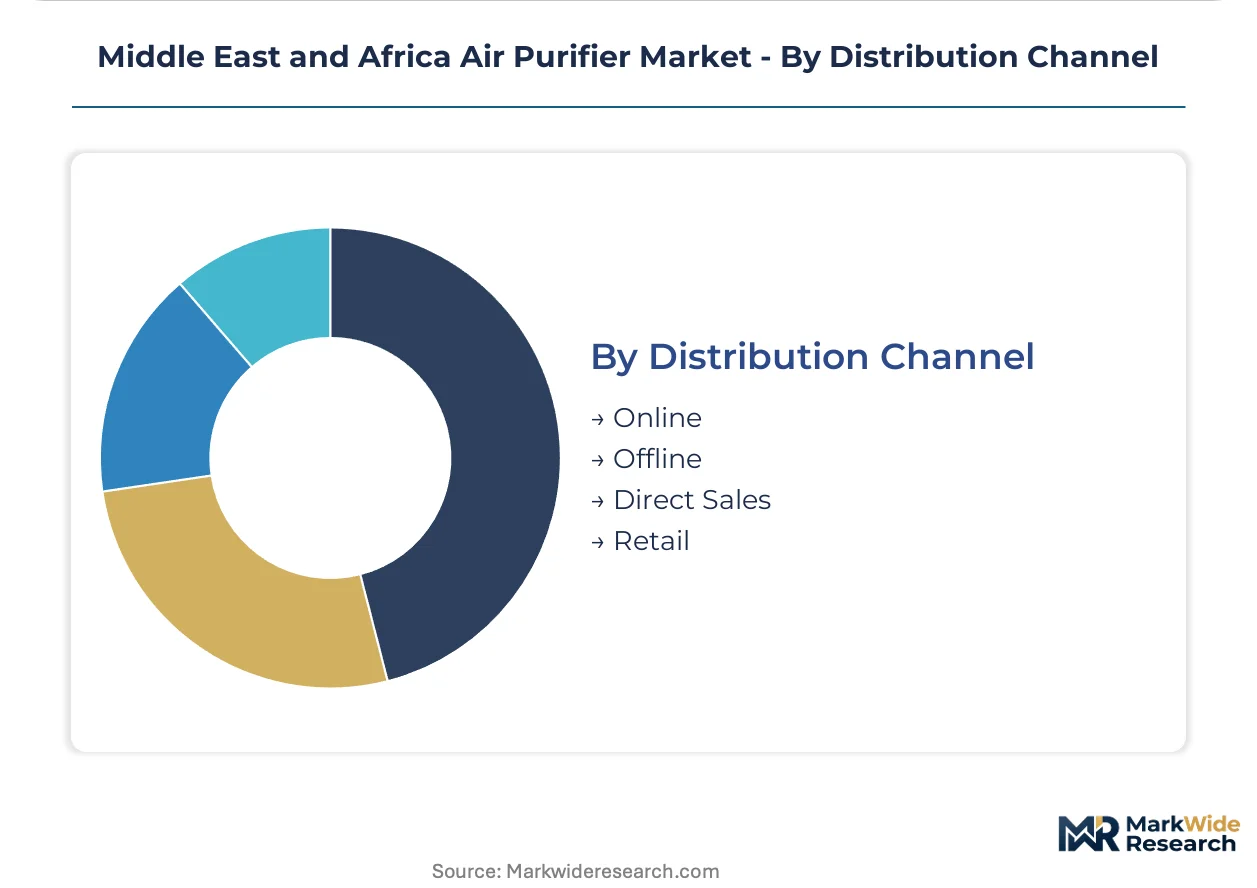
Channel economics reflect buyer sophistication gradients, with direct sales capturing complex healthcare specifications while online and retail channels serve price-sensitive residential segments.
- Direct Sales:Manufacturer-to-institution relationships for large-scale healthcare and commercial projects requiring customized engineering and installation coordination. Panasonic Marketing Middle East & Africa FZE leverages its regional service network to sustain aftermarket attachment rates through direct hospital contracts.
- Retail:Big-box electronics and home improvement stores stocking portable units for immediate consumer purchase. Dust-storm seasonality in Gulf Cooperation Council markets creates predictable demand spikes that retail inventory planning must anticipate.
- Online:E-commerce platforms aggregating unbranded imports and certified equipment across price tiers. Kenya's underpenetrated commercial sector sees emerging specification activity through online channels as facility managers research modular filtration alternatives.
- Offline:Traditional dealer networks and HVAC contractor channels for centralized system specification. Technician certification bottlenecks constrain installation capacity, redirecting some procurement toward simpler portable alternatives.
Direct Sales retains margin leadership in project-based healthcare procurement, while Online is gaining share fastest as digital penetration deepens across residential buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf Cooperation Council healthcare procurement, where SFDA and MOHAP mandates sustain premium equipment margins, while sub-Saharan markets absorb cost-optimized portable units through unregulated import channels.
United Arab Emirates
MOHAP enforcement tightening accelerates surgical suite ventilation upgrades across Dubai and Abu Dhabi medical centers. The health authority's intensive care air exchange mandates force equipment refresh cycles every 36-48 months. Dubai's commercial real estate boom embeds filtration specifications in new office tower fit-outs, with property managers unbundling service contracts from capital purchases.
Saudi Arabia
SFDA surgical-suite air quality protocols drive HEPA-grade procurement in Riyadh and Jeddah hospital construction. The regulator's testing requirements diverge from UAE standards, forcing country-specific product line extensions. Riyadh's healthcare infrastructure expansion absorbs centralized systems through contractor certification programs that limit supplier pools to qualified installers.
South Africa
The national environmental regulator's workplace particulate thresholds extend demand into industrial retrofit applications across Gauteng and Western Cape manufacturing belts. Provincial interpretation variance creates compliance uncertainty for buyers. Johannesburg's warehousing sector faces occupational exposure limit enforcement that elevates filtration investment in logistics facilities.
Nigeria
Lagos and Abuja residential segments absorb low-cost unbranded portable imports through unregulated distribution channels. Absent local enforcement of ozone emission standards, electrostatic precipitators compete on price against certified HEPA units. The underdeveloped HVAC contractor base redirects procurement toward plug-and-play alternatives requiring minimal technical installation.
Kenya
Nairobi's office construction pipeline lacks centralized air handling specifications, creating specification gaps for modular filtration suppliers. Emerging commercial buyer research activity flows through online channels as facility managers evaluate alternatives to permanent infrastructure. The absence of national indoor air quality mandates leaves procurement decisions to individual developer discretion.
Middle East and Africa Air Purifier Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium centralized system suppliers absorbing training costs for contractor certification while volume-oriented portable manufacturers optimize channel efficiency. Market structure tilts toward consolidation in healthcare procurement, where regulatory compliance elevates barriers, and fragmentation in residential segments where import arbitrage sustains price competition. Three archetypes dominate: multinational HVAC integrators with regional service networks, East Asian electronics conglomerates leveraging consumer brand equity, and regional filter media specialists capturing replacement cycles. Competitive moves concentrate on geographic licensing partnerships and portfolio diversification into photocatalytic-UV convergence systems.
Within the multinational HVAC integrator tier, Daikin Industries Ltd and Panasonic Marketing Middle East & Africa FZE occupy positions anchored by contractor training investments in the UAE and Saudi Arabia. These Japan-based entities exemplify the premium-system archetype where direct hospital relationships sustain aftermarket attachment. LG Electronics Inc represents the consumer-electronics conglomerate vector, sitting within a positioning that trades installation dependency for brand recognition in portable segments.
| Leading Market Players |
|---|
| Panasonic Marketing Middle East & Africa FZE |
| Camfil AB |
| Daikin Industries Ltd |
| LG Electronics Inc |
| Aerofil Filters Manufacturing LLC |
| Carrier Global Corp |
| Royal Philips Group |
| Honeywell International Inc |
| Samsung Electronics Co Ltd |
| Others |
Pricing and Supply Chain Analysis
SFDA and MOHAP certification regimes gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to maintain parallel testing regimens that elevate compliance overhead while compressing margins on non-certified equipment. This regulatory fragmentation concentrates pricing power among incumbents with established hospital relationships, while channel arbitrage sustains low-cost alternatives in residential segments.
Pricing Analysis
Dubai commands 40-60% premiums over Lagos for equivalent HEPA-grade units, with certification tier and after-sales service bundling as the primary price differentiation drivers. Cost compression in the portable segment is intensifying because unbranded imports from unregulated channels undercut certified equipment. Residential buyers in Nigeria and Kenya exhibit highest price sensitivity, while Saudi Arabian hospital procurement committees prioritize compliance documentation over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites freight cost volatility for HEPA and activated carbon substrates drawn from East Asian manufacturing clusters in China, South Korea, and Japan. Filter media production rests on glass microfiber, activated carbon granule, and titanium dioxide catalyst supply. Single-source vulnerability concentrates in photocatalytic oxidation module fabrication. Distribution runs through HVAC contractor networks for centralized systems and retail e-commerce platforms for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation capacity constraints and divergent Gulf certification standards define this market's capability-scarcity architecture, rewarding players who can bridge technician training gaps or accelerate regulatory harmonization.
For Market Incumbents: Compound contractor certification investments in Riyadh and Dubai to lock out unqualified competitors facing technician graduation bottlenecks. Absorb training costs for Panasonic and Daikin-affiliated installer networks while accelerating photocatalytic-UV convergence R&D to defend premium positioning against modular filtration entrants. For New Entrants and Emerging Players: MOHAP fast-track certification for hospital-grade equipment opens procurement access in Abu Dhabi and Dubai medical centers before SFDA convergence completes. Target Kenya's underpenetrated commercial sector where Nairobi office construction lacks centralized air handling specifications. Lead with online channel education campaigns positioning modular filtration against permanent infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable photocatalytic segments as miniaturization collapses centralized-portable capability gaps. Five-to-ten year viability favors acquisition of regional filter media specialists with replacement cycle capture and existing Gulf distributor relationships. Watch SFDA-MOHAP harmonization momentum as inflection indicator for cross-border product registration efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Contractor Certification Program Expansion | Daikin and Panasonic training investments lock hospital procurement to qualified installer networks in Saudi Arabia and UAE. |
| Photocatalytic-UV Convergence Development | Titanium dioxide catalyst integration with UV-C irradiation captures specification wins in Riyadh isolation ward deployments. |
| Cross-Border Harmonization Advocacy | SFDA-MOHAP convergence lobbying streamlines dual certification burdens for multinational suppliers. |
| Online Channel Infrastructure Buildout | Kenya facility manager research activity flows through digital platforms ahead of permanent infrastructure decisions. |
| Filter Media Backward Integration | East Asian supply base exposure motivates captive production of HEPA substrates and activated carbon. |
Research Methodology
The analysis maps portable, centralized, wall-mounted, and HEPA replacement product architectures, each validated through HVAC contractor interviews, hospital procurement committee discussions, facility manager surveys, and regulatory affairs consultations. Primary fieldwork combined with secondary validation from SFDA filings, MOHAP technical circulars, customs trade data, and hospital construction pipeline databases. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and distribution channel dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product architecture, pathogen neutralization technology, procurement sophistication tier, and channel efficiency. CAGRs derived from installed base turnover rates, construction pipeline absorption, and compliance-driven replacement cycle analysis. Forecast inputs included dust-storm frequency indices, healthcare infrastructure budget allocations, and technician certification graduation rates.
Decision-makers should treat outputs as directional under stable regulatory divergence and construction pipeline continuity assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as SFDA-MOHAP harmonization negotiations and East Asian supply chain resilience evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Cookware Market
Household Items
Europe Cookware Market
Household Items
Dishwasher Tablets Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Hydralight Lanterns Market
Household Items
Home Use Air Purifiers Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Kick Bucket Market
Household Items
Cutlery Market
Household Items
Desktop Air Purifier Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Chest Freezers Market
Household Items
Electric Hedge Trimmer Market